
 Europe Low-Calorie Sweeteners Market | 2026-2036
Europe Low-Calorie Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Low-Calorie Sweeteners Market Foresight
Premium-grade sweetener certification is bifurcating the competitive landscape as EU buyers enforce stricter purity thresholds for stevia and enzymatically modified variants. Cargill Incorporated leverages its European extraction infrastructure to supply high-Reb-A stevia concentrates to major beverage clients. Kerry Group plc sustains formulation partnerships across dairy and confectionery segments, while Tate & Lyle PLC anchors its position through specialty fiber-sweetener blends that reduce net carbohydrates in baked applications.
Europe low-calorie sweeteners comprise high-intensity sugar substitutes—stevia glycosides, aspartame, sucralose, and acesulfame-K—typically delivering 200-600 times the sweetness of sucrose at negligible caloric contribution, manufactured through extraction, fermentation, or chemical synthesis for mass-market food and beverage reformulation. Stevia dominates volume flows as beverage sector procurement prioritizes plant-derived, non-synthetic labels across carbonated soft drinks and flavored waters. Sucralose maintains structural importance in heat-stable baking and confectionery applications where thermal degradation resistance determines functional performance, while aspartame competes in cost-sensitive dairy and tabletop segments despite ongoing EFSA re-evaluation pressures.
EFSA purity standards, EU Food Information to Consumers Regulation labeling mandates, and F-Gas Regulation constraints on extraction solvents collectively elevate compliance costs and favor suppliers with integrated quality-assurance laboratories. ECHA REACH registration requirements for novel enzymatically modified stevia variants create extended market-access timelines that incumbent producers exploit to defend shelf positions. Stakeholders must monitor EFSA's scheduled aspartame safety reassessment and emerging novel-food approvals for fermented sweetener platforms to anticipate portfolio rebalancing requirements.
Market Dynamics
EFSA's scheduled aspartame safety reassessment is compressing formulation timelines as beverage manufacturers accelerate stevia and enzymatically modified sweetener trials to preempt portfolio disruption. This regulatory overhang concentrates procurement power among suppliers with established novel-food dossiers and integrated extraction infrastructure.
Growth Catalysts
- EU Sugar-Reduction Targets:Member-state beverage taxes and reformulation mandates are forcing carbonated soft drink producers to replace sucrose with high-intensity alternatives at scale.
- Enzymatic Bioconversion:Fermentation-derived steviol glycosides achieve higher Reb-A purity than leaf extraction, satisfying EFSA clean-label thresholds for premium positioning.
- German Retail Channel:Discounters Aldi and Lidl are expanding private-label reduced-sugar product lines, creating volume pull for certified sweetener concentrates.
Market Restraints
- Input Cost Volatility:Stevia leaf supply from China faces climate-driven harvest variability, compressing margins for European extraction facilities dependent on imported raw material.
- Regulatory Friction:ECHA REACH registration timelines for novel enzymatically modified variants extend 18-24 months, delaying market entry for innovative suppliers.
- Technical Limitation:Stevia glycosides exhibit bitter aftertaste in high-concentration dairy applications, restricting penetration in yogurt and flavored milk segments.
Strategic Opportunities
- Poland and Romania:Underpenetrated confectionery markets present first-mover potential for fiber-sweetener blends reducing net carbohydrates in baked goods.
- Fermented Sweetener Platforms:Precision fermentation using modified yeast strains enables rare glycoside production without agricultural cultivation.
- Direct-to-Manufacturer Distribution:Bypassing traditional ingredient distributors allows sweetener suppliers to capture formulation service revenue and lock in multi-year supply contracts.
Industry Challenges
- Specialized Formulation Talent:Scarcity of food technologists skilled in stevia-sucralose synergy optimization slows product development cycles for mid-tier manufacturers.
- Capex Intensity:In-house enzymatic bioconversion requires fermentation capacity investments exceeding EUR 50 million, favoring incumbents with existing biotechnology infrastructure.
- Certification Timeline Compression:Accelerated EFSA novel-food approvals demand simultaneous toxicology and stability studies, straining quality-assurance laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Low-Calorie Sweeteners Market |
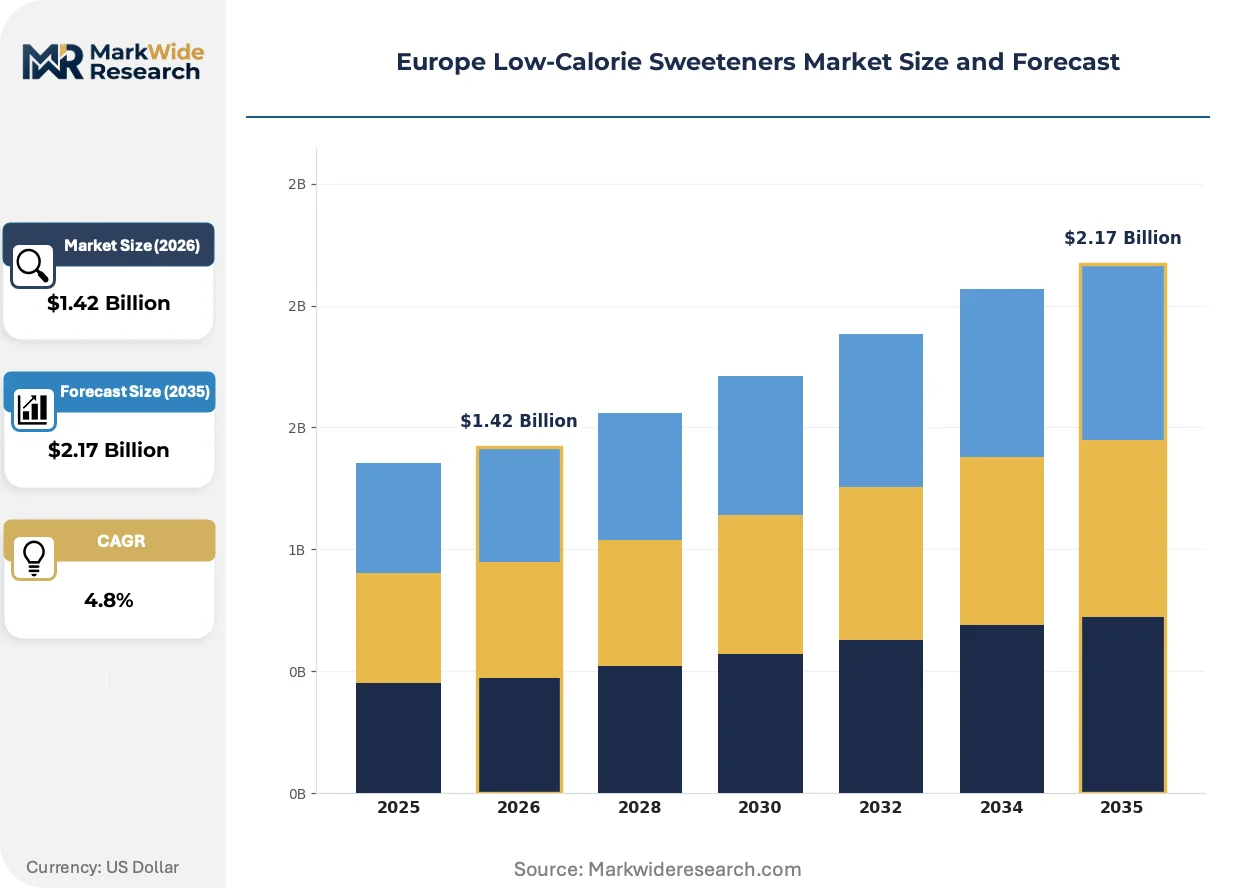
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Aspartame, Sucralose, Acesulfame-K End User: Food Industry, Beverage Sector, Pharmaceutical Companies, Personal Care Products Form: Liquid, Powder, Granular, Tablet Application: Baking, Confectionery, Dairy Products, Beverages |
| Companies Covered | Roquette Freres, Kerry Group plc, Cargill Incorporated, NutraSweet Co, Ajinomoto Foods Europe SAS, Tate & Lyle PLC, Ingredion Incorporated, Koninklijke DSM N.V., Archer Daniels Midland Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Low-Calorie Sweeteners Market Shifts & Advancements
Biotechnology convergence with precision fermentation is displacing agricultural extraction as the dominant production paradigm, while regulatory pressure on synthetic sweeteners accelerates plant-derived alternative development. These forces are compressing traditional supply chain configurations.
Enzymatically modified stevia variants are miniaturizing the functional gap between natural and synthetic high-intensity sweeteners by delivering clean taste profiles previously achievable only with sucralose. Beverage formulators in France and the Netherlands are adopting these variants at triple-digit annual rates for carbonated and still water applications. This technology is miniaturizing the market presence of aspartame in premium positioning tiers where label transparency commands price premiums.
F-Gas Regulation constraints on extraction solvents are elevating capital requirements for stevia processing facilities across EU member states. Industrial consequence includes accelerated adoption of supercritical CO2 and aqueous ethanol alternatives with higher equipment costs but regulatory compliance certainty. Heat pump and mechanical vapor recompression installations are concentrating in Spanish and Italian extraction plants where energy costs dominate operational economics.
Clean-label certification is displacing cost-per-serving as the primary procurement criterion among branded beverage manufacturers reformulating for EU Food Information to Consumers Regulation compliance. Direct supplier relationships are replacing distributor intermediation as technical formulation support becomes a bundled service requirement. This behavioral shift is most visible in German and British dairy alternative segments where organic and non-GMO certifications command shelf placement priority.
Europe Low-Calorie Sweeteners Market Segmentation
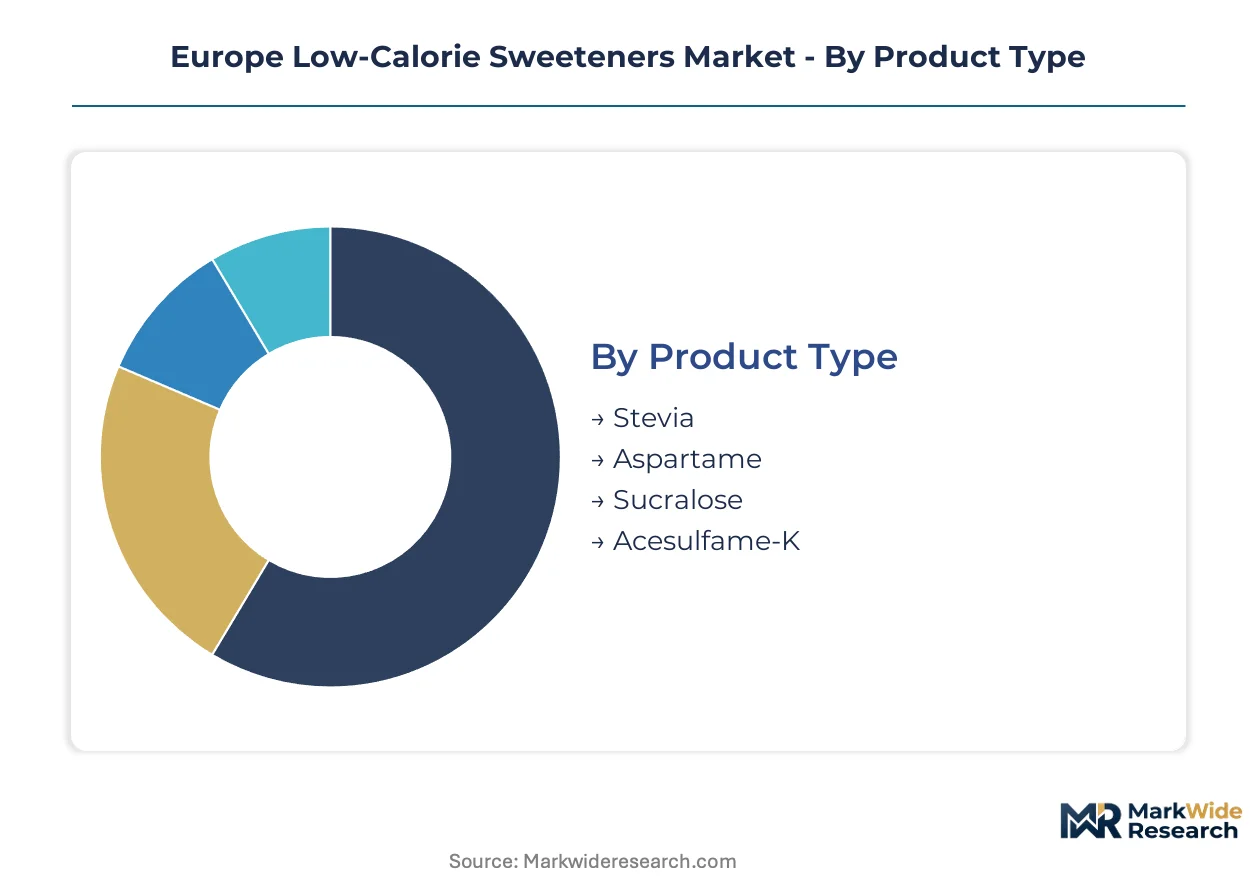
Sweetener procurement patterns diverge sharply across end-use categories, with beverage manufacturers prioritizing label-friendly plant extracts while pharmaceutical buyers enforce pharmacopeial-grade purity standards. Formulation requirements for thermal stability, solubility profiles, and regulatory compliance create distinct segment economics that suppliers must navigate through specialized product portfolios.
Product Type:
Stevia extraction concentrates in Spain and Italy where supercritical CO2 processing infrastructure clusters near Mediterranean agricultural inputs, while synthetic variants ship from centralized chemical manufacturing hubs serving pan-European distribution networks.
- Stevia:Glycoside concentrates extracted from Stevia rebaudiana leaves deliver 200-350x sucrose sweetness with zero caloric contribution. German and French beverage manufacturers dominate procurement for carbonated soft drinks and flavored waters, driven by EFSA clean-label thresholds and EU sugar-reduction mandates. Reb-A purity grades above 97% command premium positioning in organic-certified product lines.
- Sucralose:Chemically modified sugar derivative maintains thermal stability above 200°C without degradation, enabling high-temperature baking applications. UK and Polish confectionery producers anchor demand for heat-stable sweetening in hard candies and baked goods, constrained by F-Gas Regulation compliance costs for chlorinated intermediate processing.
- Aspartame:Dipeptide methyl ester synthesized through L-phenylalanine and L-aspartic acid condensation serves cost-sensitive dairy and tabletop segments. EFSA's scheduled safety reassessment compresses formulation timelines across Italian and Spanish yogurt manufacturers.
- Acesulfame-K:Potassium salt of 6-methyl-1,2,3-oxathiazine-4(3H)-one 2,2-dioxide provides synergistic sweetness enhancement when blended with aspartame or sucralose. Heat stability and pH tolerance sustain penetration in processed food applications across Central European manufacturing clusters.
Stevia holds the largest share; momentum sits with enzymatically modified variants climbing the fastest as beverage formulators preempt aspartame regulatory uncertainty.
End User:
Procurement scale and technical sophistication create three distinct customer tiers: multinational beverage conglomerates with integrated formulation laboratories, mid-tier food manufacturers outsourcing technical development, and pharmaceutical buyers enforcing pharmacopeial-grade documentation.
- Food Industry:Baked goods, sauces, and processed food manufacturers blend high-intensity sweeteners with bulking agents to maintain texture and mouthfeel. German and British industrial bakeries drive volume for sucralose-acesulfame-K combinations in reduced-sugar bread and pastry applications, constrained by Maillard reaction interference from non-reducing sweeteners.
- Beverage Sector:Carbonated soft drink, flavored water, and dairy alternative producers constitute the dominant demand center for stevia glycosides. French and Dutch formulators are adopting enzymatically modified variants at accelerated rates for clean-label positioning, while EFSA novel-food approvals compress supplier qualification timelines.
- Pharmaceutical Companies:Excipient-grade sweeteners for chewable tablets, syrups, and pediatric formulations require USP/EP pharmacopeial certification. Swiss and German contract manufacturers enforce batch-level traceability and residual solvent testing exceeding food-grade standards.
- Personal Care Products:Toothpaste, mouthwash, and cosmetic applications utilize sweeteners for taste masking without cariogenic risk. Niche volume concentrates in Italian and French oral care manufacturing where triclosan-free formulations demand alternative taste-modification strategies.
The beverage sector commands the dominant revenue share; pharmaceutical applications are expanding most quickly as pediatric formulation pipelines diversify excipient sourcing.
Form:
Processing economics and end-use handling requirements segment manufacturing investment: liquid concentrates demand aseptic filling infrastructure, powder production requires spray-drying capacity, and tablet compression serves tabletop retail channels.
- Liquid:Aqueous concentrates and alcohol-based extracts enable precise dosing in continuous beverage manufacturing lines. High-concentration stevia liquids dominate German and Austrian dairy alternative production where automated batching systems require pumpable inputs.
- Powder:Spray-dried or crystallized products provide extended shelf stability and simplified logistics for industrial food manufacturing. Sucralose and acesulfame-K powders serve Polish and Romanian confectionery producers with limited liquid handling infrastructure.
- Granular:Agglomerated particles with controlled dissolution rates mimic sucrose texture in tabletop and baking applications. UK retail channels favor granular stevia-sugar blends for consumer substitution in home baking.
- Tablet:Compressed single-serve units target foodservice and institutional catering where portion control and hygiene priorities dominate. Limited penetration outside German and Scandinavian contract catering channels.
Powder forms retain the largest installed base; liquid concentrates are gaining share fastest as beverage sector automation investments accelerate.
Application:
Thermal processing requirements and finished-product pH environments dictate sweetener selection: high-temperature baking demands heat-stable molecules, while acidic beverages tolerate broader molecular ranges.
- Baking:Maillard browning and yeast fermentation compatibility constrain sweetener selection in bread and pastry applications. Sucralose-acesulfame-K combinations serve German and Austrian industrial bakeries where sugar reduction must preserve crust color and crumb structure.
- Confectionery:Hard candy, chocolate, and chewing gum manufacturing requires thermal stability across cooking and cooling phases. Polish and Turkish confectionery exporters in the European supply chain favor sucralose for high-boiled sweets where caramelization control is critical.
- Dairy Products:Yogurt, flavored milk, and ice cream applications face bitter aftertaste challenges with high-concentration stevia. French and Italian formulators are investing in glycoside blending and bitter-masking technologies to expand plant-derived penetration in fermented dairy.
- Beverages:Carbonated soft drinks, still waters, and dairy alternatives constitute the most technically advanced application segment. Dutch and Belgian beverage innovators lead adoption of enzymatically modified stevia variants with improved temporal sweetness profiles.
Beverages represent the largest application segment; dairy products are climbing the fastest as enzymatic bioconversion resolves taste-profile limitations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction infrastructure clusters along Mediterranean coastlines where stevia leaf processing facilities leverage established supercritical CO2 capacity. EFSA regulatory harmonization creates divergent national compliance burdens that reshape procurement patterns across member states.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive sucralose-acesulfame-K procurement for reduced-sugar bread applications. The Federal Ministry of Food and Agriculture enforces strict sugar-reduction benchmarks through its National Reduction and Innovation Strategy. Frankfurt and Hamburg host formulation laboratories serving pan-European beverage clients seeking enzymatically modified stevia certification.
France
Carbonated soft drink manufacturers in Île-de-France accelerate trials of fermented steviol glycosides to preempt aspartame regulatory uncertainty. ANSM monitors novel-food dossiers alongside EFSA timelines, compressing approval windows for innovative suppliers. Lyon and Marseille extraction facilities specialize in high-Reb-A concentrates for organic-certified dairy alternatives.
United Kingdom
Retail channel consolidation through Aldi and Lidl private-label expansion creates volume pull for certified sweetener concentrates in Greater London and the Midlands. The Food Standards Agency maintains post-Brexit alignment with EFSA purity thresholds while streamlining domestic approval pathways. Manchester and Birmingham host tabletop sweetener packaging operations serving foodservice distribution.
Italy
Yogurt manufacturers in Emilia-Romagna and Lombardy face bitter aftertaste constraints limiting high-concentration stevia penetration in fermented dairy. The Ministry of Health coordinates with EFSA on aspartame safety reassessment impacts for domestic formulation pipelines. Parma and Milan concentrate pharmaceutical-grade excipient production for chewable tablet applications.
Netherlands
Beverage innovators in Rotterdam and Amsterdam lead adoption of enzymatically modified variants with improved temporal sweetness profiles for still water applications. The Netherlands Food and Consumer Product Safety Authority enforces EU Food Information to Consumers Regulation labeling mandates with accelerated inspection protocols. Wageningen University partnerships drive precision fermentation research for rare glycoside production.
Europe Low-Calorie Sweeteners Market Competitive Landscape
Concentration sits with integrated agribusiness conglomerates possessing captive extraction infrastructure and biotechnology fermentation capacity. Mid-tier specialists occupy formulation service niches, while regional distributors face margin compression from direct-to-manufacturer procurement shifts. Three archetypes dominate: vertically integrated agricultural processors, enzymatic bioconversion technology licensors, and specialty fiber-sweetener blend innovators. Competitive dynamics center on M&A activity targeting novel-food dossier portfolios and capacity expansion into precision fermentation platforms.
Within the integrated processor tier, Cargill Incorporated and Tate & Lyle PLC exemplify scale-driven positioning through European extraction infrastructure and specialty blend portfolios. Kerry Group plc occupies the formulation partnership archetype, anchoring service relationships across dairy and confectionery segments. These three companies represent distinct strategic vectors—agricultural supply security, hybrid fiber-sweetener innovation, and technical formulation support—that define competitive differentiation in EFSA-compliant procurement.
| Leading Market Players |
|---|
| Roquette Freres |
| Kerry Group plc |
| Cargill Incorporated |
| NutraSweet Co |
| Ajinomoto Foods Europe SAS |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Koninklijke DSM N.V. |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Supercritical CO2 extraction capacity utilization above 85% in Spanish and Italian processing clusters compresses marginal cost curves for high-Reb-A stevia concentrates, concentrating pricing power among integrated agribusinesses while elevating price floors for mid-tier buyers lacking captive supply. EFSA purity thresholds and F-Gas Regulation compliance costs create dual barriers that scale-advantaged incumbents exploit to defend margin positions against enzymatic bioconversion entrants.
Pricing Analysis
EFSA's novel-food certification tiers dictate the pricing structure across the Europe low-calorie sweeteners landscape. Three-tier pricing separates pharmacopeial-grade excipients from food-grade concentrates and commodity tabletop blends, with Reb-A purity above 97% commanding substantial premia in organic-certified beverage applications. Cost compression in standard-grade stevia leaf extracts is intensifying because Chinese harvest variability forces European processors to absorb input volatility or sacrifice volume commitments. Mid-tier dairy manufacturers exhibit the highest price sensitivity, while multinational beverage conglomerates prioritize label-friendly certification over per-kilogram cost.
Supply Chain Analysis
China anchors raw stevia leaf supply for European extraction facilities, while Spain and Italy concentrate supercritical CO2 processing infrastructure near Mediterranean logistics hubs. Steviol glycoside production draws from imported agricultural biomass, specialized extraction solvents, and enzymatic bioconversion catalysts. Single-source vulnerability in Chinese leaf supply chains exposes processors to climate-driven harvest disruptions and phytosanitary export restrictions. Distribution runs through direct-to-manufacturer channels for multinational beverage clients, with traditional ingredient distributors serving fragmented mid-tier food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement power is concentrating among German and French beverage conglomerates consolidating reformulation pipelines, squeezing margin capture for suppliers lacking integrated certification laboratories or captive extraction assets.
For Market Incumbents: Shield margin positions by deepening backward integration into precision fermentation capacity and locking multi-year supply contracts with Aldi and Lidl private-label divisions before enzymatic bioconversion entrants achieve EFSA novel-food approvals. Accelerate toxicology dossier submissions for rare glycoside variants to exploit 18-24 month REACH registration timelines that delay competitive market access. For New Entrants and Emerging Players: Anchor in Polish and Romanian confectionery markets where fiber-sweetener blend penetration remains underdeveloped and incumbent formulation partnerships are sparse. Target bakery applications requiring sucralose-acesulfame-K combinations with technical service bundling that mid-tier industrial bakeries cannot source from established distributors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic bioconversion technology licensors with validated novel-food dossiers and pilot-scale fermentation capacity. Long-term viability over the next decade hinges on rare glycoside production economics achieving parity with agricultural extraction. Monitor EFSA's aspartame safety reassessment timeline as the critical signal for portfolio rebalancing toward plant-derived alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables rare glycoside production without Chinese leaf supply dependence. |
| EFSA Novel-Food Dossier Acquisition | Accelerates market access timelines that REACH registration compresses. |
| Direct-to-Manufacturer Distribution | Captures formulation service revenue from bypassing traditional distributors. |
| Supercritical CO2 Capacity Expansion | Secures F-Gas Regulation compliance for Mediterranean extraction clusters. |
| Fiber-Sweetener Blend Development | Addresses net carbohydrate reduction demand in Polish and Romanian bakeries. |
Research Methodology
Cross-validation between formulation laboratory directors at German and Dutch beverage manufacturers and EFSA novel-food submission databases anchors the qualitative findings in documented regulatory pathways. Primary interviews with stevia extraction plant managers, procurement leads at French dairy conglomerates, supercritical CO2 equipment suppliers, and enzymatic bioconversion R&D directors combined with secondary validation from REACH registration filings, EU Food Information to Consumers Regulation implementation reports, and trade customs data for stevia leaf imports. Bottom-up capacity assessments at Spanish and Italian processing facilities triangulate against top-down demand estimates from beverage sector reformulation pipelines.
Sensitivity analysis around EFSA approval timelines, Chinese leaf harvest yields, and enzymatic conversion cost curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include sweetener type, end-use industry, form factor, and application heat-stability requirements, with regional regulatory clusters capturing EFSA-ANSM coordination effects. CAGRs derive from installed capacity utilization trajectories and substitution elasticity estimates for aspartame-to-stevia transitions, incorporating beverage tax pass-through rates and private-label expansion velocity at German discounters.
Decision-makers should treat outputs as directional under sustained EFSA clean-label enforcement and EU sugar-reduction mandate continuity; material deviation in aspartame safety reassessment outcomes or Chinese export restriction severity would warrant model refresh. Recalibration cycles align with material shifts in novel-food approval velocities and precision fermentation yield improvements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Japan Food Sweetener Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Xylitol Injection Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
United States Xylitol Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Rice Syrup Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
D-Mannose Market