
 Europe Food Sweetener Market | 2026-2036
Europe Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Sweetener Market Foresight
Software-defined formulation services is decoupling ingredient procurement from finished-product development across European sweetener supply chains. Cargill Incorporated leverages its integrated stevia extraction and formulation capabilities to anchor premium positioning in beverage reformulation programs. Tate & Lyle PLC sustains competitive differentiation through specialized fiber-based sweetening systems targeting dairy and bakery applications. Südzucker AG dominates conventional sucrose supply while navigating gradual portfolio migration toward specialty sweetener blends.
Food sweeteners encompass caloric and non-caloric substances that impart sweetness to consumable products, with functional parameters measured by relative sweetness intensity, thermal stability, and glycemic response index. Sucrose remains the baseline reference standard at 1.0 sweetness intensity, while high-potency alternatives such as stevia glycosides achieve 200-400 times equivalent sweetness at negligible caloric contribution. The product type dimension shows stevia recording the fastest volume expansion as beverage manufacturers pursue clean-label positioning, while sucrose retains margin concentration through bulk industrial contracts. Within end users, the beverage industry leads absolute consumption volume, though the confectionery sector generates superior per-unit value through precision blending requirements.
EFSA sweetness additive evaluations and the EU Farm to Fork Strategy establish the regulatory perimeter governing novel sweetener approvals and sugar reduction mandates across member states. REACH compliance requirements for imported stevia extracts and aspartame precursors shape supply chain configuration and sourcing geography for compounders operating within the European Economic Area. Stakeholders must monitor pending EFSA re-evaluations of existing additive authorizations and anticipate how evolving Nutri-Score thresholds will redirect procurement priorities across food manufacturing categories.
Market Dynamics
Reformulation mandates from the EU Farm to Fork Strategy are compressing procurement timelines across European beverage and bakery supply chains, forcing compounders to pre-validate sweetener blends before Nutri-Score thresholds tighten.
Growth Catalysts
- EU Sugar Reduction Targets:Mandatory reduction benchmarks for processed foods are accelerating substitution contracts in Germany and France, pulling high-potency alternatives into carbonated beverage lines ahead of enforcement deadlines.
- Stevia glycoside extraction advances:Enzymatic bioconversion methods are lowering production costs for Reb M and Reb D variants, expanding accessible supply for clean-label confectionery applications.
- Bakery sector concentration:Industrial bakeries in Northern Europe are consolidating procurement around pre-mixed sweetener-fiber systems to simplify recipe reformulation at scale.
Market Restraints
- Input cost volatility:Stevia leaf supply from China faces weather-driven harvest variability, compressing margin stability for European extractors dependent on imported raw material.
- Technical limitation:Aspartame thermal degradation above 150°C restricts deployment in baked goods, forcing reliance on more expensive heat-stable alternatives for high-temperature processing.
- Regulatory friction:Pending EFSA re-evaluations of existing additive authorizations are freezing new product launches as manufacturers await clarity on acceptable daily intake adjustments.
Strategic Opportunities
- Eastern Europe penetration gap:Poland and Romania retain higher per-capita sugar consumption than Western peers, creating runway for low-calorie alternatives as retail chains expand Nutri-Score labeling.
- Fermentation-derived sweeteners:Precision fermentation platforms producing rare steviol glycosides are opening supply of molecules previously limited to scarce leaf extraction.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are incentivizing food manufacturers to source sweeteners with verified carbon footprints, favoring regional European suppliers.
Industry Challenges
- Formulation talent scarcity:Food technologists skilled in multi-sweetener synergy optimization are concentrated at legacy sucrose houses, constraining recruitment for specialty blenders.
- Dual certification timelines:Simultaneous organic and non-GMO verification for stevia supply chains extends qualification periods by 8-14 months, delaying customer conversions.
- Legacy equipment retrofit costs:Powder handling systems designed for crystalline sucrose require modification to manage hygroscopic high-potency alternatives without segregation or flow issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Sweetener Market |
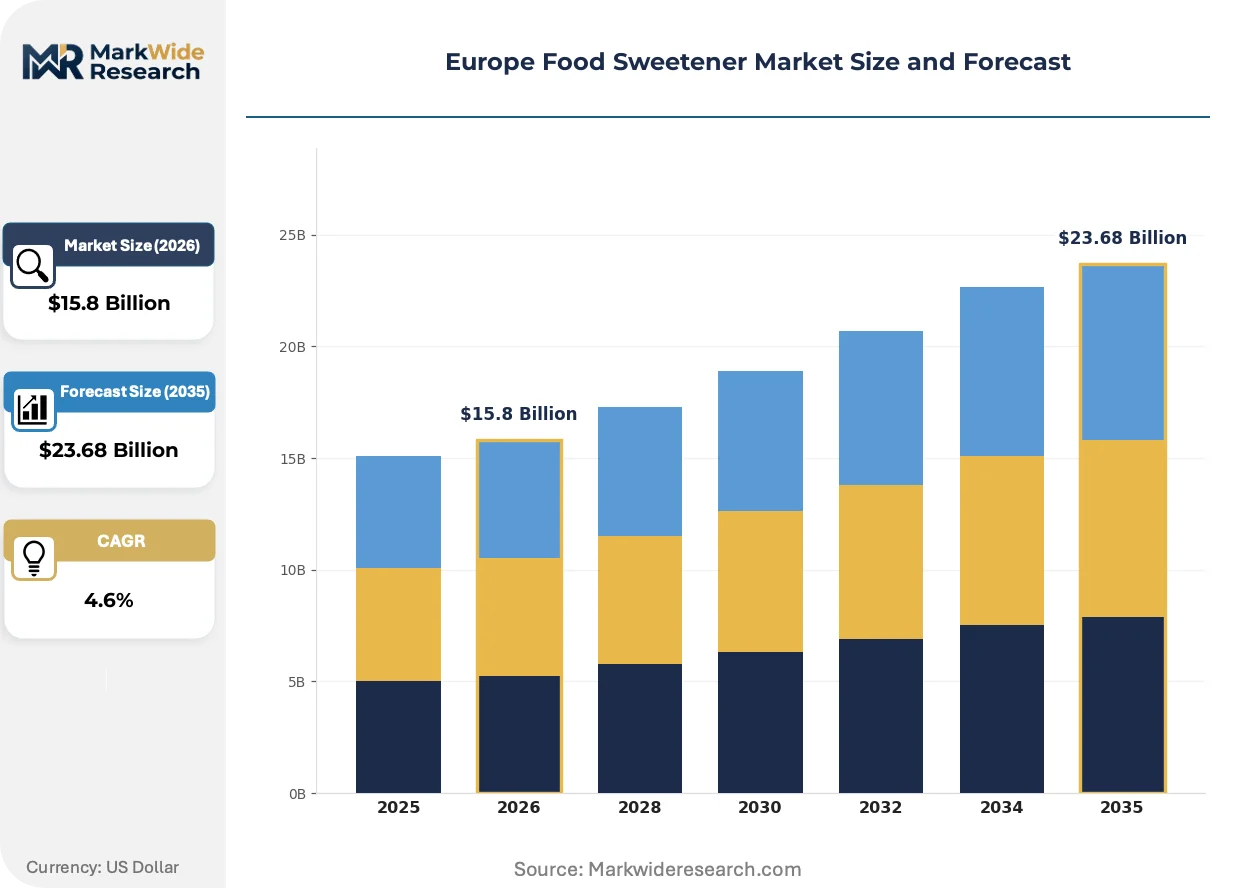
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $23.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Fructose, Aspartame, Stevia End User: Food Manufacturers, Beverage Industry, Confectionery Sector, Bakeries Form: Liquid, Granular, Powder, Syrup Application: Beverages, Bakery Products, Dairy, Sauces |
| Companies Covered | Cargill Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Ingredion Incorporated, Roquette Frères, Südzucker AG, DuPont de Nemours Inc., PureCircle Ltd, Ajinomoto Co. Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Sweetener Market Shifts & Advancements
Digital formulation platforms are collapsing the traditional sequence between ingredient testing and production scaling, enabling real-time optimization of sweetness profiles against nutritional targets.
Enzymatic glycosylation technology is modularizing stevia production by enabling conversion of standard Reb A into higher-value Reb M and Reb D variants at contract manufacturing sites rather than captive extraction facilities. Mid-sized beverage compounders in the Netherlands and Belgium are adopting this capability to bypass volume minimums from integrated suppliers. The shift is compressing minimum efficient scale for premium clean-label positioning.
REACH compliance requirements for imported stevia extracts are tightening documentation burdens on non-European suppliers, redirecting sourcing geography toward EEA-based extraction facilities. ECHA substance evaluation workflows are extending lead times for novel glycoside registrations. Dairy processors in Denmark and Sweden are responding by locking multi-year supply agreements with REACH-registered compounders to secure continuity.
Retail buyer consolidation across German and French supermarket chains is concentrating procurement authority in fewer technical sourcing teams, compressing supplier negotiation cycles and favoring full-service formulation partners over commodity ingredient vendors. Discounters Aldi and Lidl are expanding private-label clean-label ranges, pulling reformulation demand through their supplier qualification programs. This concentration is most visible in the ready-to-drink beverage category, where listing decisions now hinge on integrated sweetness-nutrition proposals rather than ingredient specifications alone.
Europe Food Sweetener Market Segmentation
Sweetener procurement in Europe diverges sharply between commodity bulk buyers and precision formulators seeking functional synergies. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Standardization dominates sucrose and fructose procurement through established purity grades, while stevia and aspartame demand intensive customization around glycoside profiles and blend ratios.
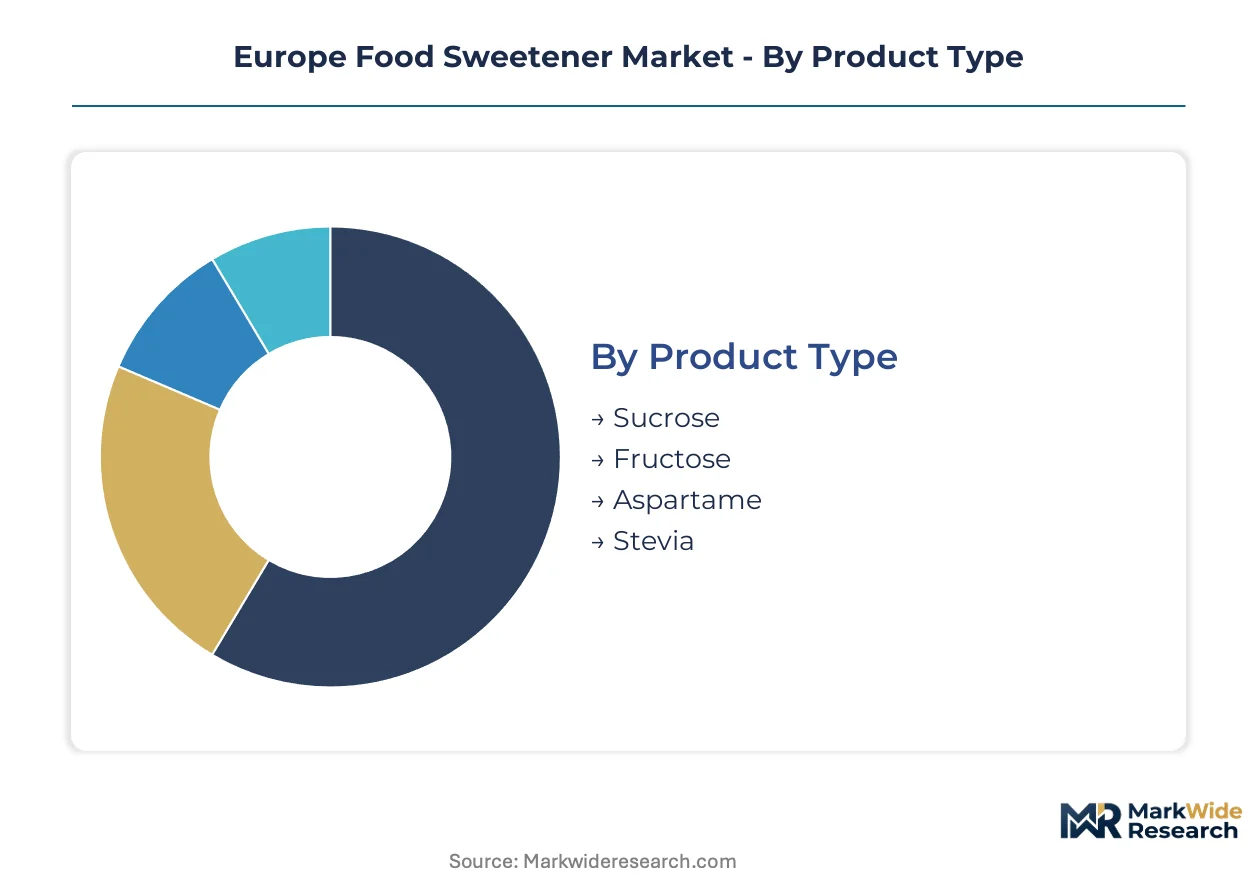
- Sucrose:Crystalline disaccharide extracted from sugar beet across Northern European cultivation zones serves as the baseline sweetness reference. German and French industrial bakeries anchor volume demand through annual procurement contracts, though EU Sugar Reduction Targets are compressing contract renewal rates.
- Stevia:Steviol glycosides extracted primarily from imported leaf material deliver 200-400 times sucrose-equivalent sweetness at negligible caloric load. Beverage manufacturers in the Netherlands and Belgium are driving fastest adoption as enzymatic bioconversion methods expand supply of Reb M and Reb D variants for clean-label positioning.
- Fructose:Monosaccharide sweetness from fruit and honey sources finds niche application in premium confectionery where crystallization control matters.
- Aspartame:Dipeptide methyl ester delivers intense sweetness with thermal instability above 150°C restricting bakery deployment to ambient applications.
Leading the category by volume: sucrose through legacy industrial contracts. Growing fastest: stevia as reformulation mandates accelerate.
End User:
Procurement sophistication varies from commodity spot purchasing at small bakeries to integrated formulation partnerships at multinational beverage compounders.
- Beverage Industry:Carbonated and flavored water manufacturers across Germany, France, and the United Kingdom command the largest absolute tonnage. These buyers are consolidating supply relationships around full-service formulation partners capable of delivering pre-validated sweetness-nutrition proposals aligned with tightening Nutri-Score thresholds.
- Food Manufacturers:Processed food compounders spanning ready meals and shelf-stable products require heat-stable sweetener systems. EFSA additive re-evaluations are freezing new product launches as technical teams await clarity on acceptable daily intake adjustments for existing formulations.
- Confectionery Sector:Precision blending requirements around texture and mouthfeel generate superior per-unit value despite smaller absolute volumes.
- Bakeries:Industrial operations in Northern Europe are consolidating procurement around pre-mixed sweetener-fiber systems to simplify recipe reformulation at manufacturing scale.
Volume concentrates with beverage compounders. Value per kilogram peaks in confectionery applications demanding precision synergy optimization.
Form:
Physical state selection directly determines handling infrastructure requirements and hygroscopicity management protocols across manufacturing facilities.
- Powder:Fine particulate grades dominate high-potency sweetener deployment where micro-dosing accuracy proves critical. Legacy powder handling systems designed for crystalline sucrose require modification to manage hygroscopic stevia extracts without flow interruption or segregation.
- Liquid:Aqueous solutions and suspensions simplify incorporation into continuous beverage processing lines. Dutch and Belgian mid-sized compounders are adopting liquid enzymatic glycosylation capabilities to bypass volume minimums from integrated suppliers.
- Granular:Free-flowing crystalline formats maintain preference among traditional bakeries with established bulk handling infrastructure.
- Syrup:Viscous preparations serve specialized applications requiring controlled moisture contribution alongside sweetness delivery.
Powder formats retain installed base dominance. Liquid formats are climbing fastest as enzymatic processing platforms proliferate.
Application:
Technical requirements diverge sharply between thermal processing environments and ambient formulation conditions.
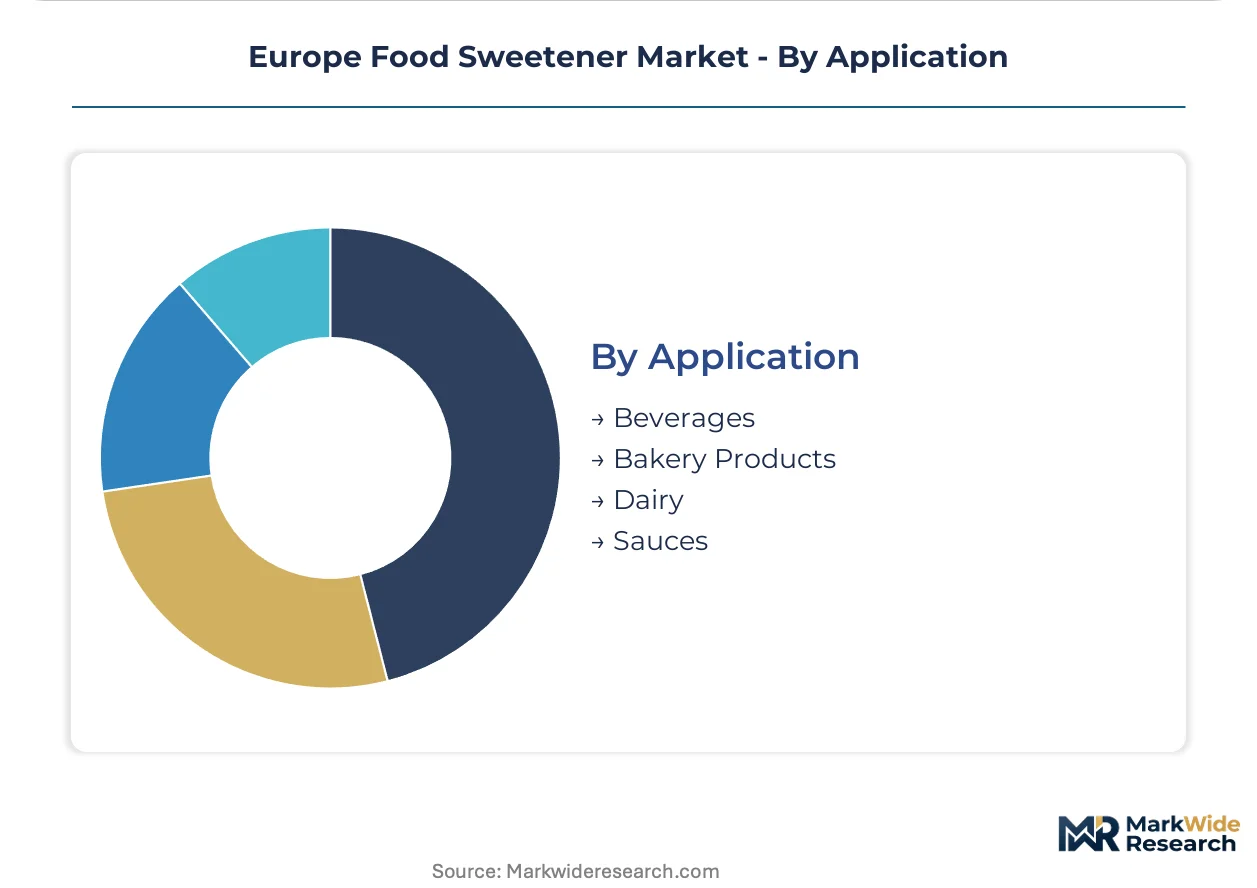
- Beverages:Ready-to-drink and concentrate formulations represent the primary volume sink. Retail buyer consolidation across German and French supermarket chains is concentrating procurement authority, with Aldi and Lidl expanding private-label clean-label ranges that pull reformulation demand through supplier qualification programs.
- Bakery Products:High-temperature processing above 150°C excludes aspartame from most applications, forcing reliance on heat-stable alternatives. Danish and Swedish dairy processors are responding to REACH compliance tightening by locking multi-year supply agreements with EEA-registered compounders.
- Dairy:Fermented and fresh dairy applications require sweetness systems compatible with live culture viability.
- Sauces:Shelf-stable condiment formulations demand sweetness stability across extended ambient storage durations.
Beverage applications anchor absolute consumption. Bakery applications face the steepest technical substitution challenges as thermal constraints limit alternative deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beet cultivation in Northern France and Germany supplies raw sucrose to compounders, yet reformulation demand concentrates in beverage clusters across the Netherlands and Belgium where enzymatic processing platforms proliferate.
Germany
Industrial bakeries in Lower Saxony and North Rhine-Westphalia are consolidating procurement around pre-mixed sweetener-fiber systems. EFSA additive re-evaluations are freezing new product launches as technical teams await acceptable daily intake adjustments. Berlin-Brandenburg hosts formulation service providers specializing in Nutri-Score optimization for private-label ranges.
France
Beet processing facilities in Hauts-de-France anchor sucrose supply while Paris-based beverage compounders accelerate stevia adoption. ANSM consultations on novel food approvals are compressing launch timelines for fermentation-derived glycosides. The Grand Est region concentrates dairy processors locking multi-year supply agreements with REACH-registered compounders.
United Kingdom
Carbonated drink manufacturers in the Midlands are expanding reformulation programs to meet retailer sugar reduction mandates. FSA guidance on clean-label claims is redirecting procurement toward enzymatically converted Reb M variants. Greater Manchester hosts mid-sized compounders adopting liquid glycosylation capabilities to bypass integrated supplier minimums.
Netherlands
Port infrastructure in Rotterdam facilitates stevia leaf importation for EEA-based extraction facilities. REACH compliance documentation requirements are extending lead times for novel glycoside registrations. Eindhoven Region concentrates enzymatic bioconversion specialists serving Belgian and German beverage clients.
Belgium
Flavor houses in Flanders are integrating sweetness modulation with bitter-masking technologies for zero-sugar beverage lines. CSRD disclosure requirements are incentivizing verified carbon footprint sourcing from regional suppliers. Brussels hosts technical teams pre-validating sweetener blends ahead of Nutri-Score threshold tightening.
Europe Food Sweetener Market Competitive Landscape
Top-tier vendors anchor integrated extraction-to-formulation capabilities, while mid-tier specialists occupy enzymatic conversion niches and regional compounders compete on REACH-registered supply security. The structure concentrates around three strategic archetypes: agricultural processors with captive beet supply, biotechnology platforms leveraging precision fermentation, and formulation service providers bundling sweetness with fiber systems. Competitive moves center on backward integration into leaf supply and technology licensing partnerships for rare glycoside production.
Among North American agricultural processors, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven supply security archetypes. European specialists Tate & Lyle PLC and Südzucker AG occupy positions bridging conventional sucrose dominance with gradual specialty migration. Japanese fermentation technology providers including Ajinomoto Co. Inc. represent the biotechnology platform tier. These named entities anchor archetype descriptions rather than serving as subjects of specific strategic claims.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Roquette Frères |
| Südzucker AG |
| DuPont de Nemours Inc. |
| PureCircle Ltd |
| Ajinomoto Co. Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between REACH-registered stevia extracts and conventional sucrose creates parallel procurement channels with distinct margin structures and supplier qualification timelines. Beverage compounders in Germany and the Netherlands pay premiums for EEA-based extraction facilities with verified carbon footprints, while industrial bakeries in Northern France anchor volume contracts around beet-derived sucrose from captive agricultural processors.
Pricing Analysis
Margin tightening in high-potency sweetener tiers reflects enzymatic bioconversion cost curves and leaf supply volatility from Chinese harvests. Three-tier pricing structure across premium Reb M/D variants, standard Reb A grades, and commodity sucrose tracks certification level and thermal stability performance. Cost-down pressure on stevia glycosides accelerates as mid-sized Dutch compounders adopt liquid enzymatic processing to bypass integrated supplier minimums. Industrial bakeries show highest price sensitivity due to thin reformulation budgets, while beverage manufacturers absorb premiums for clean-label positioning.
Supply Chain Analysis
Freight cost escalation on stevia leaf shipments from China to Rotterdam is redirecting sourcing geography toward EEA-based extraction facilities with REACH-registered status. Supply concentrates in China for leaf raw material, Germany and France for beet sucrose processing, and Belgium-Netherlands clusters for enzymatic glycosylation. Raw material dependencies include Chinese stevia leaf, Northern European sugar beet, and fermentation feedstocks for precision-derived glycosides. Single-source vulnerability on Chinese leaf supply creates structural risk during weather-driven harvest shortfalls. Distribution runs through full-service formulation partners rather than commodity ingredient traders as retail buyer consolidation intensifies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated extraction-to-formulation capabilities as EFSA re-evaluations and REACH compliance costs force sub-scale compounders toward acquisition or exit.
For Market Incumbents: Extend backward integration into stevia leaf supply through long-term offtake agreements with Chinese cultivation cooperatives to secure margin stability against harvest volatility. Lock multi-year formulation partnerships with German and French retail chains ahead of Nutri-Score threshold tightening, anchoring customer relationships that emerging entrants cannot replicate within qualification timelines. For New Entrants and Emerging Players: Begin with enzymatic bioconversion service provision to mid-sized Dutch and Belgian beverage compounders seeking to bypass volume minimums from integrated suppliers. Eastern European markets in Poland and Romania offer white-space penetration as retail chains expand Nutri-Score labeling into higher per-capita sugar consumption regions. Position around fermentation-derived rare glycosides with shorter regulatory pathways than leaf-extraction alternatives. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation platforms producing Reb M and Reb D variants given EFSA novel food approval momentum and clean-label demand acceleration. Long-term viability favors biotechnology archetypes with intellectual property on enzymatic glycosylation rather than commodity extraction dependent on Chinese agricultural cycles. Watch EFSA acceptable daily intake adjustments on existing additives as inflection signal for substitution contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaf Supply | Long-term offtake agreements with Chinese cooperatives secure raw material continuity against weather volatility. |
| Enzymatic Bioconversion Capacity Addition | Modular processing platforms in Netherlands-Belgium cluster bypass integrated supplier volume minimums for mid-tier compounders. |
| REACH Registration Investment | EEA-based extraction facilities capture procurement redirection as documentation burdens tighten on non-European suppliers. |
| Full-Service Formulation Partnership | Pre-validated sweetness-nutrition proposals align with Aldi and Lidl supplier qualification programs for private-label ranges. |
| Precision Fermentation Platform Development | Biotechnology routes to rare steviol glycosides open supply previously constrained by scarce leaf extraction yields. |
Research Methodology
Independent corroboration across formulation technologists at beverage compounders, procurement directors at industrial bakeries, regulatory affairs specialists navigating EFSA processes, and stevia extraction facility operators underwrites the qualitative findings. Primary interviews with Dutch enzymatic bioconversion specialists and German retail chain technical sourcing teams combined with secondary validation from EFSA additive evaluation databases, REACH registration filings, and EU Farm to Fork Strategy implementation documents. Bottom-up volume modeling across product type and end-use segments triangulates against top-down market sizing from agricultural processor disclosures and trade flow analysis.
Comparable-period anchoring to historical procurement contract renewal rates and reformulation program adoption curves established the forecast baseline across the projection horizon. Segmentation dimensions modeled include sweetener product type, end-use industry, physical form, and application thermal processing requirements. CAGRs derived from elasticity-adjusted substitution curves tracking EU Sugar Reduction Target compliance deadlines. Industry-specific inputs incorporated enzymatic conversion cost trajectories and Nutri-Score threshold implementation schedules.
Underlying measurement precision varies by segment; fermentation-derived sweetener forecasts carry tighter precision than conventional sucrose projections given earlier-stage commercialization. Forecasts reflect assumptions on EFSA re-evaluation timelines and retail chain labeling expansion that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Compressible Sugar Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Sorbitol Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Sweet Modulator Market
Sweeteners
Corn Sweeteners Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
China Saccharin Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Sugar Syrups Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Cassava Syrup Market
Sweeteners
Sweeteners Market