
 Second Stage Organic Infant Formula Market | 2026-2036
Second Stage Organic Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Second Stage Organic Infant Formula Market Insights
EU Organic Regulation 2018/848 is redrawing competitive boundaries by mandating stricter farm-to-formula traceability and prohibiting certain processing aids. HiPP leverages its vertically integrated German dairy network to control raw milk quality from biodynamic farms. Abbott anchors its position through extensive pediatric clinical research infrastructure that supports health claims in regulated markets. Nestlé competes via broad distribution reach across European pharmacy and supermarket channels.
Second stage organic infant formula denotes powdered or liquid nutrition products designed for infants aged six to twelve months, typically containing adjusted protein ratios, added iron, and docosahexaenoic acid to support neurodevelopment during the weaning transition. Powder formulations dominate volume due to longer shelf stability and lower per-feed cost, while ready-to-use liquid formats command premium positioning in convenience-oriented channels. Goat's milk ingredient sourcing is gaining structural traction among parents seeking alternatives to bovine protein, though organic cow's milk still occupies the largest margin pool across ingredient categories.
EMA guidelines on infant nutrition health claims, USDA National Organic Program standards, and China's SAMR registration requirements collectively shape formulation rules, labeling protocols, and import eligibility across major markets. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established regulatory dossiers and local laboratory testing partnerships. Stakeholders must monitor evolving pesticide residue thresholds and emerging microbiome-related claim restrictions that could force formula reformulation or delisting in key jurisdictions.
Market Dynamics
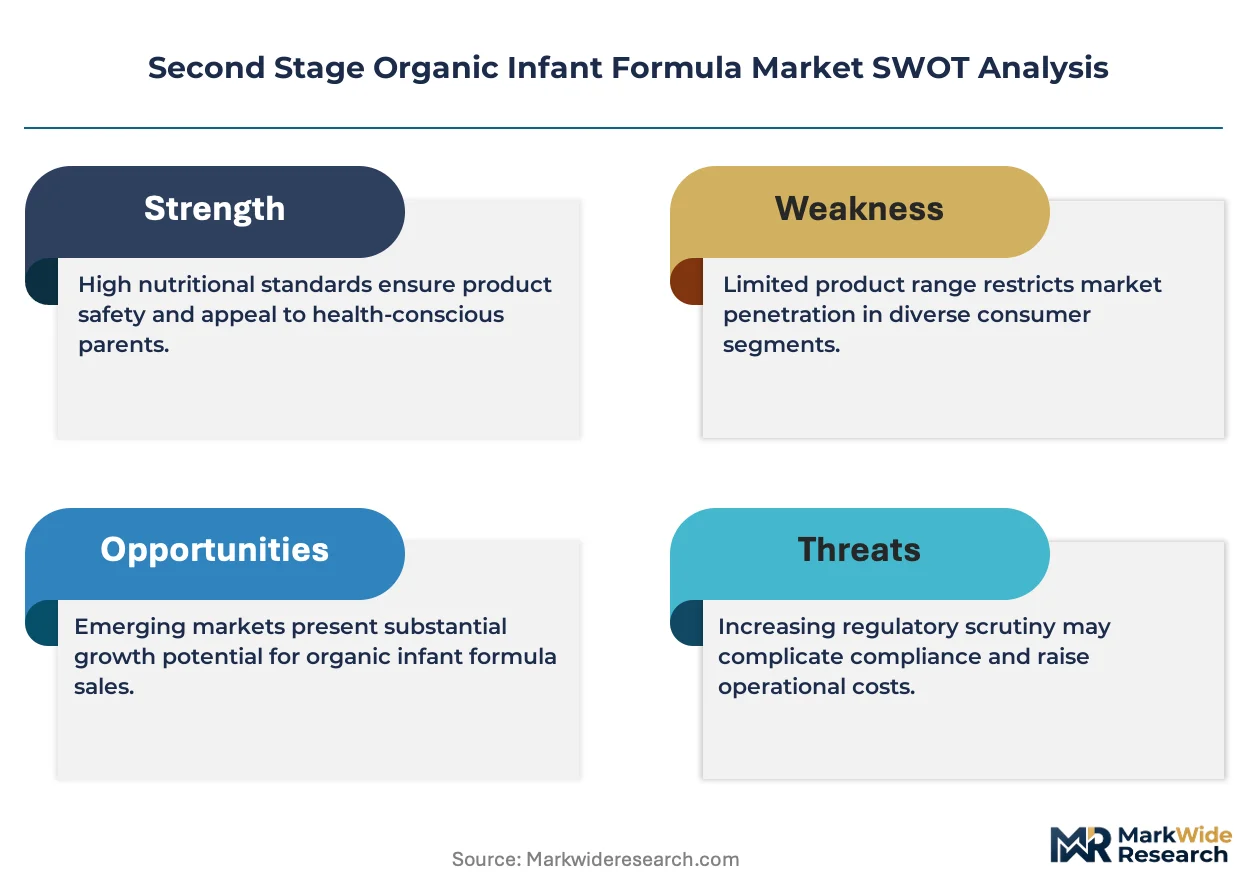
EU Organic Regulation 2018/848 is compressing supplier margins by mandating farm-to-formula traceability systems that smaller blenders cannot afford. This regulatory pivot favors dairy networks with captive organic milk supply and in-house testing laboratories.
Growth Catalysts
- Dual-income household expansion:Working parents in China and South Korea prioritize certified organic nutrition for infants aged six to twelve months, creating sustained volume pull through pharmacy and e-commerce channels.
- GB 10765-2021 tightening:China's updated national food safety standards for infant formula are disqualifying non-compliant imports, redirecting demand toward EU-certified organic brands with complete dossier documentation.
- Goat's milk protein traction:Parents seeking alternatives to bovine protein are driving formulation R&D toward organic caprine sourcing, opening margin pools beyond conventional cow's milk derivatives.
Market Restraints
- Organic dairy input volatility:Biodynamic farm output fluctuates with seasonal pasture conditions, constraining raw milk availability for second-stage formula production during peak demand windows.
- EMA health claim restrictions:The European Medicines Agency's stringent guidelines on infant nutrition claims limit marketing differentiation, compressing brand premium realization in regulated European markets.
- SAMR registration timelines:China's State Administration for Market Regulation requires 18-24 month approval cycles for new organic formula entrants, freezing competitive repositioning for latecomers.
Strategic Opportunities
- Ready-to-use liquid penetration:Convenience-oriented urban parents in Shanghai and Seoul are shifting toward premium liquid formats for travel and nighttime feeding, creating channel-specific margin expansion.
- Microbiome claim development:Emerging research on HMO fortification and gut flora modulation offers pathways to differentiated positioning ahead of anticipated EFSA claim restrictions.
- Subscription direct-to-home models:Pharmacy chains in Germany and the Netherlands are piloting auto-replenishment services for second-stage organic formula, locking in recurring revenue and reducing price transparency.
Industry Challenges
- Analytical chemistry talent scarcity:ISO 17025-accredited pesticide residue testing requires specialized laboratory personnel that organic dairy networks struggle to recruit at scale.
- Legacy ERP integration friction:Farm-to-formula traceability mandates are forcing mid-sized blenders to replace batch tracking systems, disrupting production scheduling during 12-18 month implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second Stage Organic Infant Formula Market |
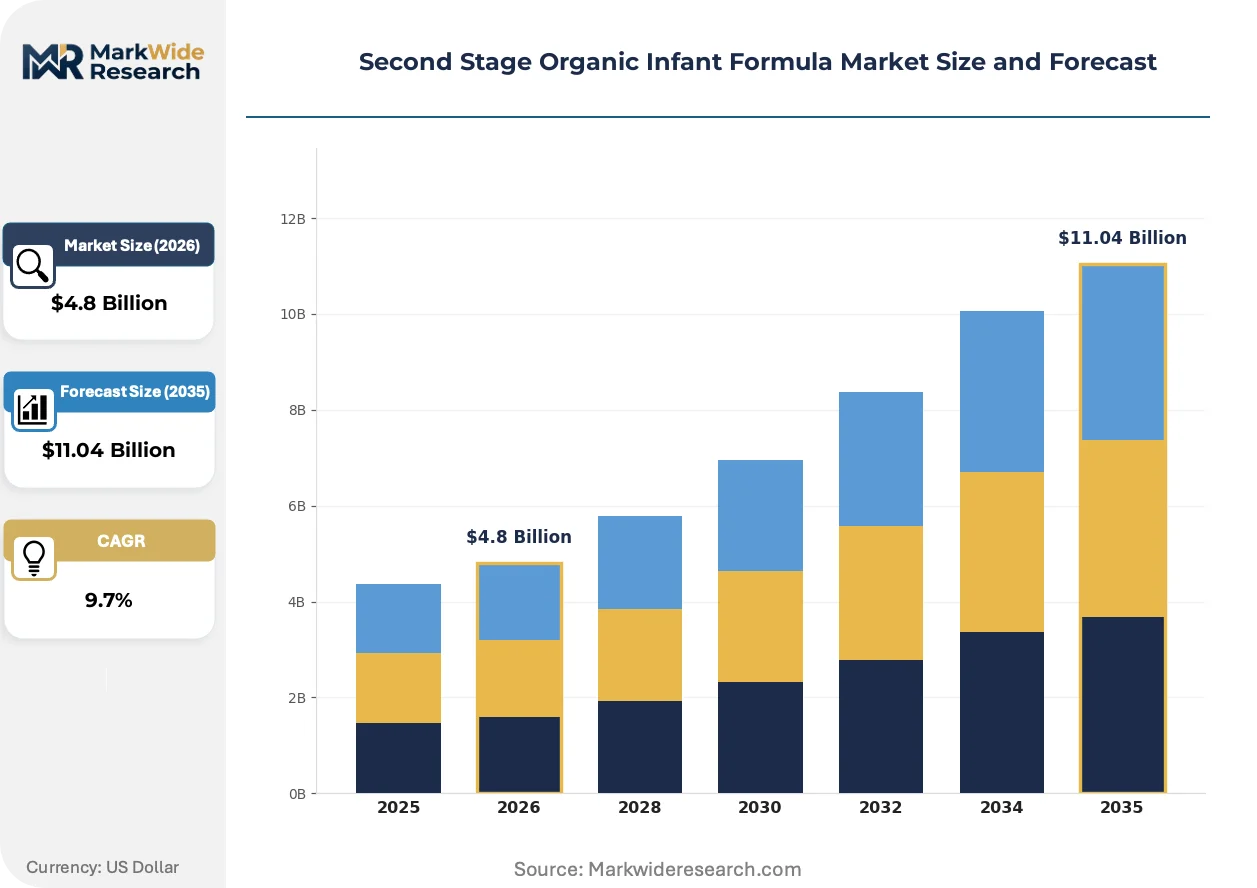
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Ready-to-Use, Nutrient-Enriched Ingredient Source: Organic Milk, Soy-Based, Lactose-Free, Goat's Milk Package Type: Metal Can, Tetra Pak, Plastic Container, Pouch Distribution Channel: Supermarkets, Online Retail, Pharmacies, Health Food Stores |
| Companies Covered | HiPP, Holle, Bellamy's Organic, Nestlé, Abbott, Topfer, The Hain Celestial Group, Ausnutria, Kendamil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second Stage Organic Infant Formula Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how organic infant nutrition reaches parents. Three distinct vectors are compressing development cycles and rewiring competitive advantage.
Precision fermentation for dairy protein is miniaturizing. Startups in California and the Netherlands are deploying microbial platforms to produce lactoferrin and casein without bovine agriculture, attracting venture funding from consumer health investors. This technology is miniaturizing the upstream supply chain, enabling brands to decouple from seasonal organic milk volatility and compress ingredient lead times from months to weeks.
REACH chemical safety protocols are extending into food-contact materials. ECHA's expanding substance restrictions now cover processing aids and packaging migrants used in infant formula manufacturing, forcing reformulation of emulsifiers and antioxidant stabilizers. European contract manufacturers are responding by qualifying alternative lipid encapsulation technologies that satisfy both organic certification and migration limits.
Parents are consolidating purchase decisions around third-party certification marks. The USDA National Organic Program seal and EU organic leaf logo now dominate shelf selection criteria in U.S. specialty retailers, displacing brand loyalty as the primary filter. This behavioral pivot is most pronounced among first-time mothers in coastal metropolitan markets, where subscription box curation amplifies certification visibility over traditional advertising.
Second Stage Organic Infant Formula Market Segmentation
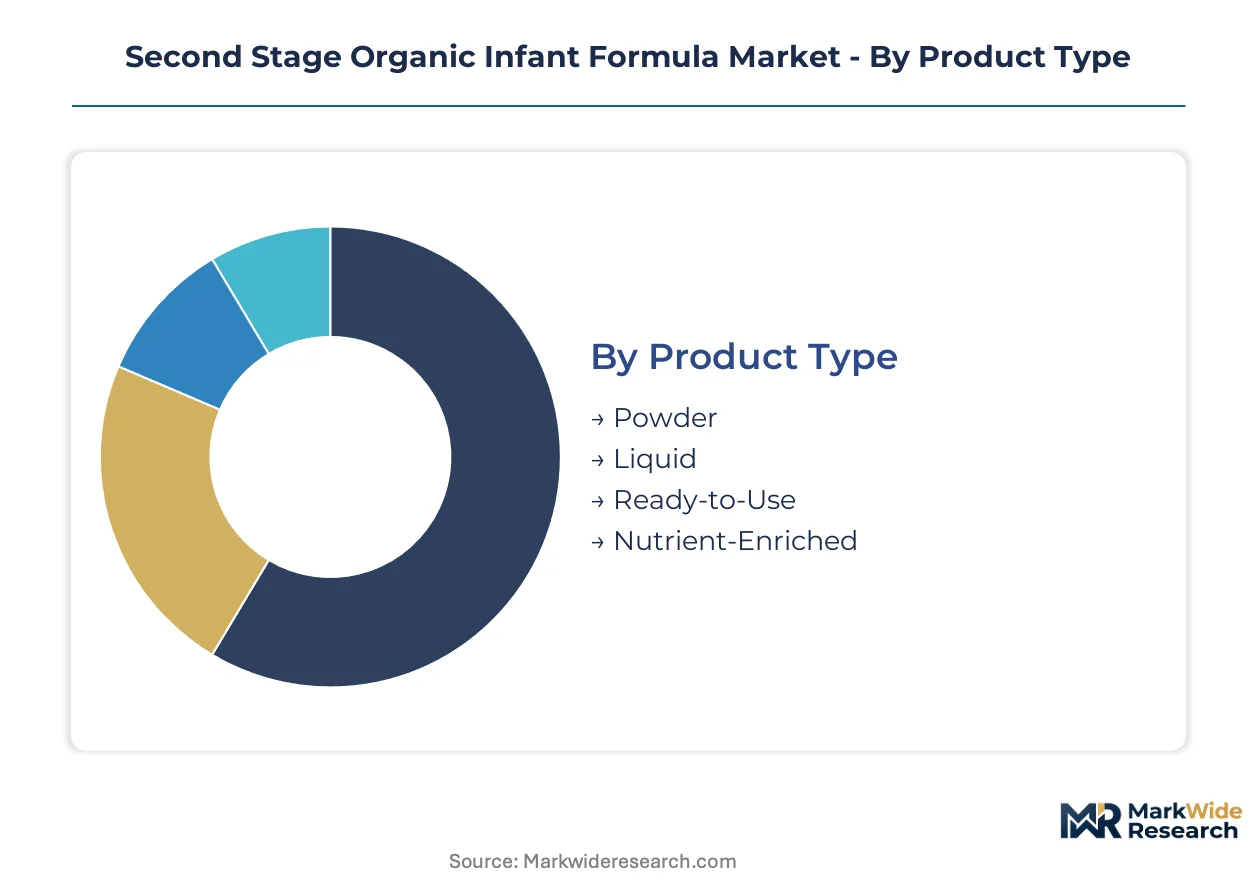
Second stage organic infant formula segmentation reveals how formulation choices, packaging formats, and channel access fragment purchasing behavior across working parents with divergent convenience needs and ingredient preferences. Understanding these divides exposes where margin pools concentrate and which technical specifications drive premium realization.
Product Type:
Powder formats dominate domestic consumption in Germany and the Netherlands, while liquid variants concentrate in export channels serving convenience-oriented urban parents in Shanghai and Seoul.
- Powder:Dried formulation with extended shelf stability and lower per-feed cost structure. Demand concentrates in German pharmacy chains and Dutch supermarket bulk purchasing, where price-sensitive dual-income households optimize for volume economics during the six-to-twelve month feeding window.
- Liquid:Reconstituted concentrate requiring dilution before serving. Export-led traction in South Korean e-commerce channels accelerates as working parents prioritize preparation speed over unit cost, particularly for nighttime feeding scenarios.
- Ready-to-Use:Pre-diluted single-serve format eliminating mixing steps. Travel-focused demand in China's first-tier cities supports premium positioning.
- Nutrient-Enriched:Fortified variants with added iron, DHA, or HMO compounds. Specialized positioning for neurodevelopment-focused parents in EU markets.
Powder commands the established base. The steepest expansion runs through Ready-to-Use.
Ingredient Source:
Cost tiers stratify sharply here, with commodity organic cow's milk anchoring volume and goat's milk protein extracting structural premiums from allergy-concerned parents.
- Organic Milk:Bovine-derived base meeting EU Organic Regulation 2018/848 and USDA National Organic Program standards. German biodynamic farm networks supply captive raw material to vertically integrated blenders, constraining availability during seasonal pasture fluctuations.
- Goat's Milk:Caprine protein alternative with smaller fat globule structure. Chinese SAMR-registered imports from EU-certified facilities climb fastest as domestic consumers abandon non-compliant local brands under GB 10765-2021 enforcement.
- Soy-Based:Plant-derived protein isolate for dairy-intolerant infants. Niche positioning in North American specialty retailers.
- Lactose-Free:Hydrolyzed carbohydrate formulation addressing digestive sensitivity. Pharmacy-channel concentration in France and Italy.
Organic Milk retains the volume anchor. Goat's Milk gains share fastest.
Package Type:
Supply concentration in European metal can manufacturing contrasts with Asia-Pacific adoption of Tetra Pak aseptic systems for liquid format export.
- Metal Can:Tinplate or aluminum cylindrical container with nitrogen flushing. German and Swiss canneries dominate production for powder formulations, with REACH-compliant internal coatings now mandatory under ECHA substance restrictions.
- Tetra Pak:Aseptic carton with aluminum barrier layer. Swedish packaging technology enables ambient-stable liquid distribution to China's inland cities without cold chain infrastructure.
- Plastic Container:Polypropylene wide-mouth jars for scoop access. US specialty retail concentration with FDA food-contact material compliance.
- Pouch:Flexible film single-serve sachets. Travel and sampling applications in South Korean convenience channels.
Metal Can holds the incumbent position. Tetra Pak climbs the fastest.
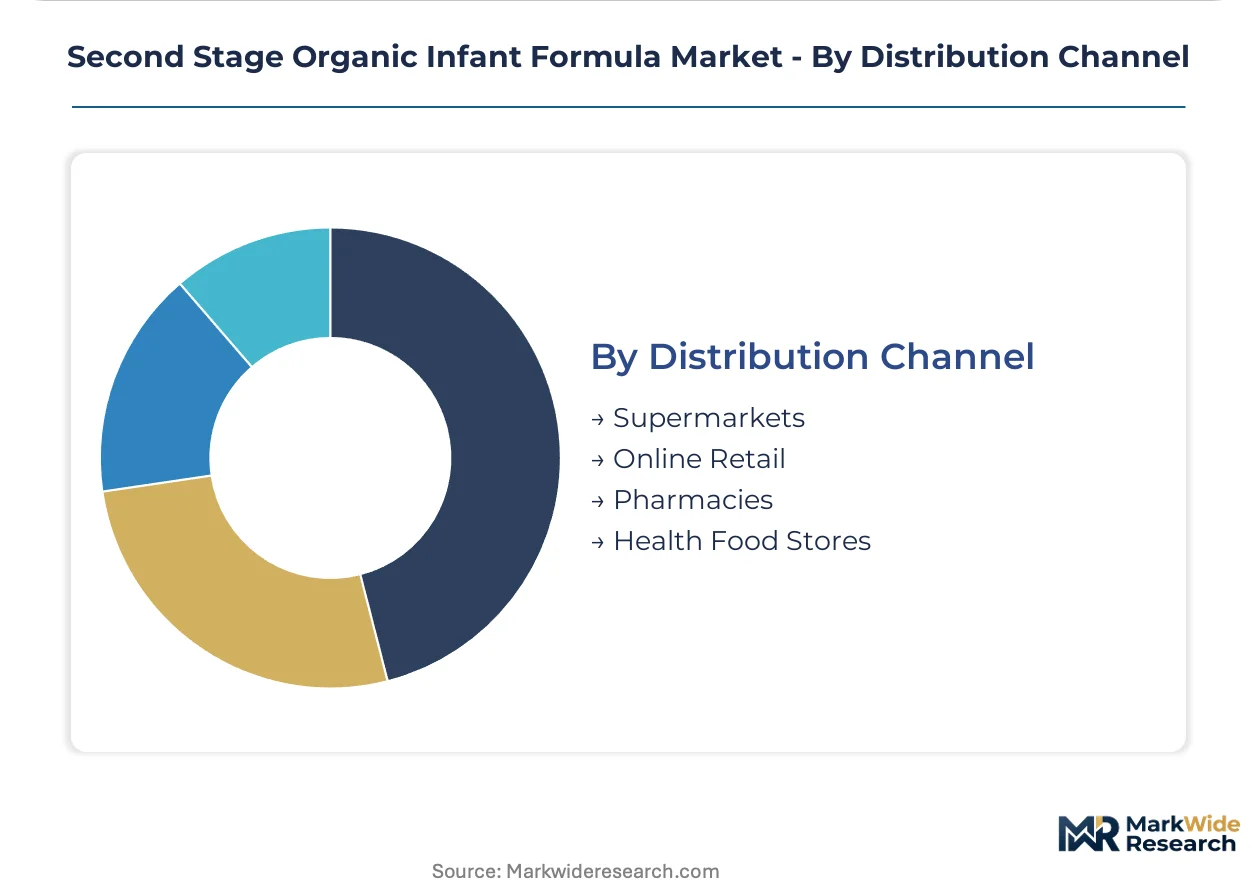
Distribution Channel:
Customer type fragmentation separates subscription-loyal pharmacy patrons from price-comparing online shoppers and impulse-driven supermarket buyers.
- Supermarkets:Mass-market retail with shelf-space competition. German DM-drogerie and Dutch Albert Heijn anchor volume for standard powder SKUs.
- Online Retail:E-commerce platforms with cross-border import functionality. Tmall Global and Coupang dominate China and South Korea respectively, enabling direct EU brand access without SAMR registration delays for gray-market purchases.
- Pharmacies:Professional recommendation channel with consultation services. German Apotheken and French officines drive premium positioning through pharmacist endorsement.
- Health Food Stores:Specialty retail with certification-focused curation. US coastal metropolitan markets concentrate USDA Organic seal visibility.
Supermarkets maintain the broadest reach. Online Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income working parents in metropolitan China and South Korea anchor demand concentration, with regulatory divergence between EU organic certification and China's SAMR registration requirements reshaping import flows and local production strategies.
China
First-tier city parents in Shanghai and Beijing drive premium organic formula adoption through cross-border e-commerce channels. SAMR's GB 10765-2021 standards disqualify non-compliant imports, redirecting demand toward EU-certified brands with complete registration dossiers. Yangtze River Delta distribution hubs concentrate gray-market import processing before formal channel clearance.
Germany
Biodynamic farm networks in Bavaria and Lower Saxony supply captive organic milk to vertically integrated blenders. EU Organic Regulation 2018/848 mandates farm-to-formula traceability systems that favor established dairy cooperatives with in-house testing laboratories. Pharmacy chains in Munich and Hamburg pilot subscription auto-replenishment services.
South Korea
Seoul Capital Area working parents prioritize convenience-oriented ready-to-use liquid formats for nighttime feeding scenarios. MFDS alignment with international Codex standards enables faster EU import approval than China's SAMR timeline. Coupang's logistics infrastructure enables direct-to-home delivery within 24 hours.
United States
Coastal metropolitan first-time mothers in California and New York consolidate purchases around USDA National Organic Program certification marks. FDA food-contact material compliance requirements intersect with state-level Proposition 65 chemical disclosure rules. Health food store curation in Los Angeles and San Francisco amplifies certification visibility over traditional brand advertising.
Netherlands
Randstad region supermarkets anchor volume for standard powder SKUs among price-sensitive dual-income households. ECHA REACH protocols extend into food-contact materials, forcing reformulation of emulsifiers and antioxidant stabilizers. Dutch contract manufacturers qualify alternative lipid encapsulation technologies for export-compliant production.
Second Stage Organic Infant Formula Market Competitive Landscape
Player mix skews toward European heritage brands with captive dairy supply and multinational nutrition conglomerates with clinical research infrastructure. Market structure concentrates around vertically integrated organic specialists and broad-reach pharmaceutical-channel operators. Two strategic archetypes dominate: biodynamic farm-network owners controlling raw material quality, and pediatric clinical trial sponsors supporting regulated health claims. Competitive moves center on SAMR registration dossier completion and precision fermentation technology licensing for dairy protein alternatives.
Within the European heritage tier, HiPP and Holle occupy positions exemplifying biodynamic supply chain control, while Nestlé represents broad distribution reach across pharmacy and supermarket channels. Abbott anchors the clinical research vector through extensive pediatric infrastructure. These players illustrate how regulatory compliance capabilities and captive raw material access separate viable competitors from marginal entrants facing 18-24 month approval timelines.
| Leading Market Players |
|---|
| HiPP |
| Holle |
| Bellamy's Organic |
| Nestlé |
| Abbott |
| Topfer |
| The Hain Celestial Group |
| Ausnutria |
| Kendamil |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation for dairy protein is displacing traditional biodynamic farm sourcing, compressing ingredient lead times from seasonal months to weeks while eroding the geographic premium commanded by German and Austrian alpine dairy networks. This substitution dynamic simultaneously shifts supply gravity toward California and Netherlands microbial platforms and forces price recalibration across organic certification tiers as synthetic biology inputs bypass pasture-dependent cost structures.
Pricing Analysis
Cost-plus contracts indexed to EU organic milk powder futures dominate procurement between German blenders and Bavarian dairy cooperatives, creating transparency that limits margin extraction during seasonal pasture shortfalls. Price differentiation rests on certification grade—EU Organic leaf logo commands pharmacy-channel premiums over USDA National Organic Program equivalents in cross-border Chinese e-commerce—and volume scale, with bulk powder SKUs in Dutch supermarkets running at per-gram economics that undercut single-serve ready-to-use formats by substantial multiples. Cost compression in standard powder tiers is intensifying as precision fermentation startups attract venture funding and threaten to flood the protein isolate market. Price-sensitive buyers concentrate in German DM-drogerie and Dutch Albert Heijn bulk purchasing, while least-sensitive parents in Shanghai's Yangtze River Delta prioritize SAMR-registered convenience formats regardless of unit cost.
Supply Chain Analysis
Baltic Sea port congestion at Rotterdam and Hamburg underwrites distribution delays for EU-certified organic formula destined for Chinese cross-border e-commerce channels, forcing inventory pre-positioning in Yangtze River Delta bonded warehouses. Supply concentrates in Germany, the Netherlands, and Austria, where biodynamic farm networks feed captive processing facilities with ISO 17025-accredited testing laboratories. Raw material dependencies center on organic skim milk powder, lactoferrin isolates, and DHA algal oil sourced from controlled-environment fermentation. Single-source vulnerability runs through German metal can manufacturing for nitrogen-flushed powder packaging, where REACH-compliant internal coating suppliers number fewer than four qualified vendors. Distribution runs through pharmacy chains in Munich and Hamburg for subscription auto-replenishment, Tmall Global for Chinese gray-market import, and Coupang's Seoul logistics infrastructure for South Korean direct-to-home delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025-accredited analytical chemistry talent scarcity constrains organic dairy network expansion, with specialized pesticide residue testers commanding compensation premiums that smaller blenders cannot absorb. This capability gap separates viable competitors from marginal entrants facing production halts during peak seasonal demand windows.
For Market Incumbents: Fortify upstream control over biodynamic farm networks through exclusive milk supply agreements with Bavarian and Lower Saxony cooperatives, locking out precision fermentation entrants from premium certification tiers. Invest in captive SAMR registration dossier completion to exploit China's GB 10765-2021 enforcement that disqualifies non-compliant imports. Channel control through German Apotheken subscription pilots reduces price transparency and builds switching costs against liquid-format convenience competitors. For New Entrants and Emerging Players: Lead with precision fermentation-derived lactoferrin and casein platforms targeting the goat's milk protein alternative segment, where parental concern over bovine allergy creates willingness to pay for novel sourcing stories. The most penetrable white-space sits in South Korean ready-to-use liquid formats, where MFDS alignment with Codex standards enables faster import approval than China's SAMR timeline. A direct-to-home subscription go-to-market through Coupang bypasses incumbent pharmacy channel gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated organic specialists with captive dairy supply and completed SAMR registration dossiers, as these assets compound in value under tightening Chinese import standards. Long-term viability over the analysis window hinges on regulatory compliance infrastructure rather than brand equity alone. The signal to watch is EFSA preliminary opinions on microbiome-related health claims, which could force formula reformulation and delisting for players without R&D flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Registration Dossier Completion | GB 10765-2021 enforcement disqualifies non-compliant EU imports, redirecting demand toward registered brands. |
| Precision Fermentation Licensing | Microbial platforms for lactoferrin production decouple supply from seasonal biodynamic farm output volatility. |
| Pharmacy Subscription Pilot Expansion | German Apotheken auto-replenishment services lock in recurring revenue and reduce cross-channel price transparency. |
| Goat's Milk Protein R&D Investment | Caprine sourcing alternatives extract structural premiums from allergy-concerned parents abandoning bovine formulas. |
| REACH-Compliant Packaging Qualification | ECHA substance restrictions on food-contact materials force reformulation of emulsifiers and antioxidant stabilizers. |
Research Methodology
A standing panel of organic dairy cooperative managers, infant formula regulatory affairs leads at EU-certified blenders, Chinese cross-border e-commerce platform category buyers, and South Korean pharmacy chain procurement directors provided ongoing calibration against secondary validation from EFSA scientific opinions, SAMR registration databases, EU Organic Regulation 2018/848 implementation guidance, and MFDS import approval records. Bottom-up volume estimates from segment-level demand modeling triangulated against top-down market sizing from trade flow analysis and channel audit data.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with modeled segmentation spanning product format, ingredient source, certification tier, and distribution channel. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory inflection points. Industry-specific forecast inputs included biodynamic farm output seasonality, SAMR approval timeline distributions, and precision fermentation technology readiness assessments.
The analysis sits within stated boundaries; outcomes outside sustained dual-income household expansion in China and South Korea, continued EU organic certification integrity, and stable Baltic Sea logistics corridors would require recalibration. Practitioners should keep alternative scenarios live as EFSA microbiome claim restrictions and precision fermentation cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Pet Milk Replacers Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
North America Baby Food Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Europe Organic Baby Food Market