
 Sugar-Free Syrups Market | 2026-2036
Sugar-Free Syrups Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Syrups Market Analytics
E-commerce distribution for beverage ingredients is rewriting procurement patterns across the sugar-free syrups category. Monin leverages its European production footprint to sustain bulk supply contracts with café chains across France and Germany. Torani anchors North American demand through direct-to-restaurant distribution and private-label partnerships. Cargill competes on ingredient-scale economics, supplying erythritol and stevia blends to downstream syrup formulators.
Sugar-free syrups are aqueous flavoring systems containing non-nutritive sweeteners, typically 0-5 calories per serving, manufactured through controlled thermal blending of water, acidulants, preservatives, and high-intensity sweeteners such as sucralose, acesulfame potassium, or monk fruit extract; they function primarily as tabletop or back-bar flavor modifiers in beverages and desserts. Fruit-flavored variants occupy the largest volume share due to their versatility across coffee, tea, and mocktail applications. Online retail channels represent the fastest-growing distribution pathway, driven by subscription models and bulk purchasing from health-conscious households and small foodservice operators.
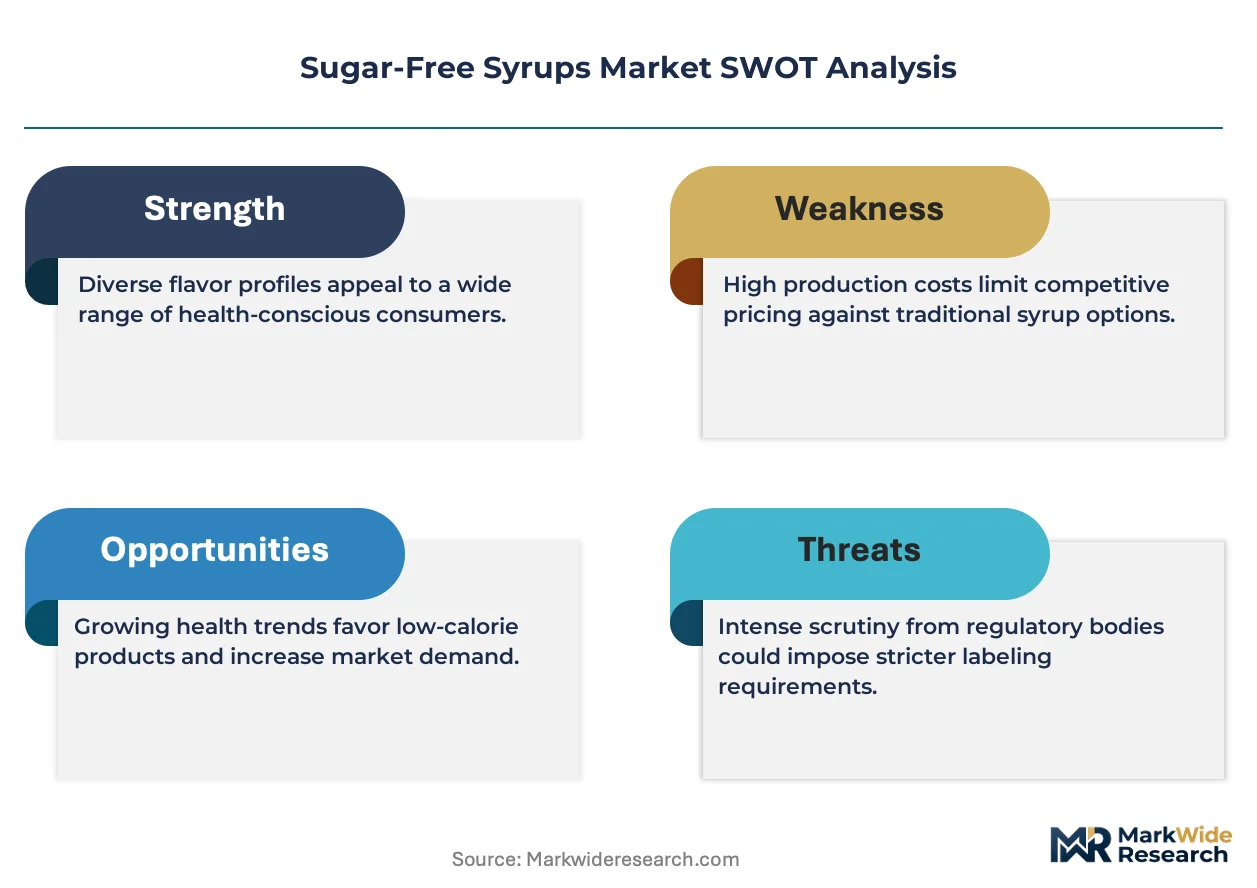
The FDA governs sweetener safety and labeling claims under 21 CFR 172, while the EMA and EFSA coordinate novel food assessments and additive approvals across EU member states; these frameworks determine which sweetener systems gain market access and how products communicate reduced-sugar benefits. The FSSAI in India and China's SAMR are tightening scrutiny of imported sugar-free formulations, creating compliance barriers for brands without localized regulatory expertise. Stakeholders must monitor evolving sweetener approval pipelines and front-of-pack labeling mandates to anticipate which formulations will retain shelf space across major markets.
Market Dynamics
FDA nutrition labeling updates and WHO sugar reduction guidelines are compressing reformulation timelines across beverage and confectionery supply chains, forcing manufacturers to source non-nutritive flavoring systems at scale.
Growth Catalysts
- Specialty café proliferation:Third-wave coffee chains in the United States and Germany are standardizing sugar-free flavor menus, creating pull-through demand for back-bar syrup systems.
- 21 CFR 172 sweetener approvals:The FDA's expanded clearance of monk fruit and allulose formulations is unlocking new clean-label positioning for beverage brands.
- Home barista equipment sales:Consumer-grade espresso machine penetration in urban China is driving direct-to-consumer syrup purchases through e-commerce platforms.
Market Restraints
- Stevia supply concentration:Raw stevia leaf processing clusters in Guangdong and Shandong provinces, exposing formulators to Chinese export duty volatility.
- Aftertaste masking costs:Erythritol-stevia blends require 15-20% higher flavor load to achieve parity with sucrose mouthfeel, compressing gross margins.
- SAMR import scrutiny:China's State Administration for Market Regulation is extending novel food assessment timelines for imported monk fruit concentrates.
Strategic Opportunities
- Indian foodservice whitespace:FSSAI enforcement of front-of-pack sugar warnings in Maharashtra and Karnataka is creating first-mover advantage for reformulated syrup suppliers.
- Functional beverage convergence:Collagen-infused and adaptogenic coffee applications in South Korea are pulling sugar-free syrups into nutraceutical positioning.
- Subscription replenishment models:Direct-to-consumer auto-ship programs in the United Kingdom are reducing customer acquisition costs for premium flavor brands.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise bridging high-intensity sweetener stability with thermal processing requirements commands 40% salary premiums in competitive labor markets.
- Clean-label certification lag:Non-GMO Project and organic syrup certifications require 18-24 month validation cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Syrups Market |
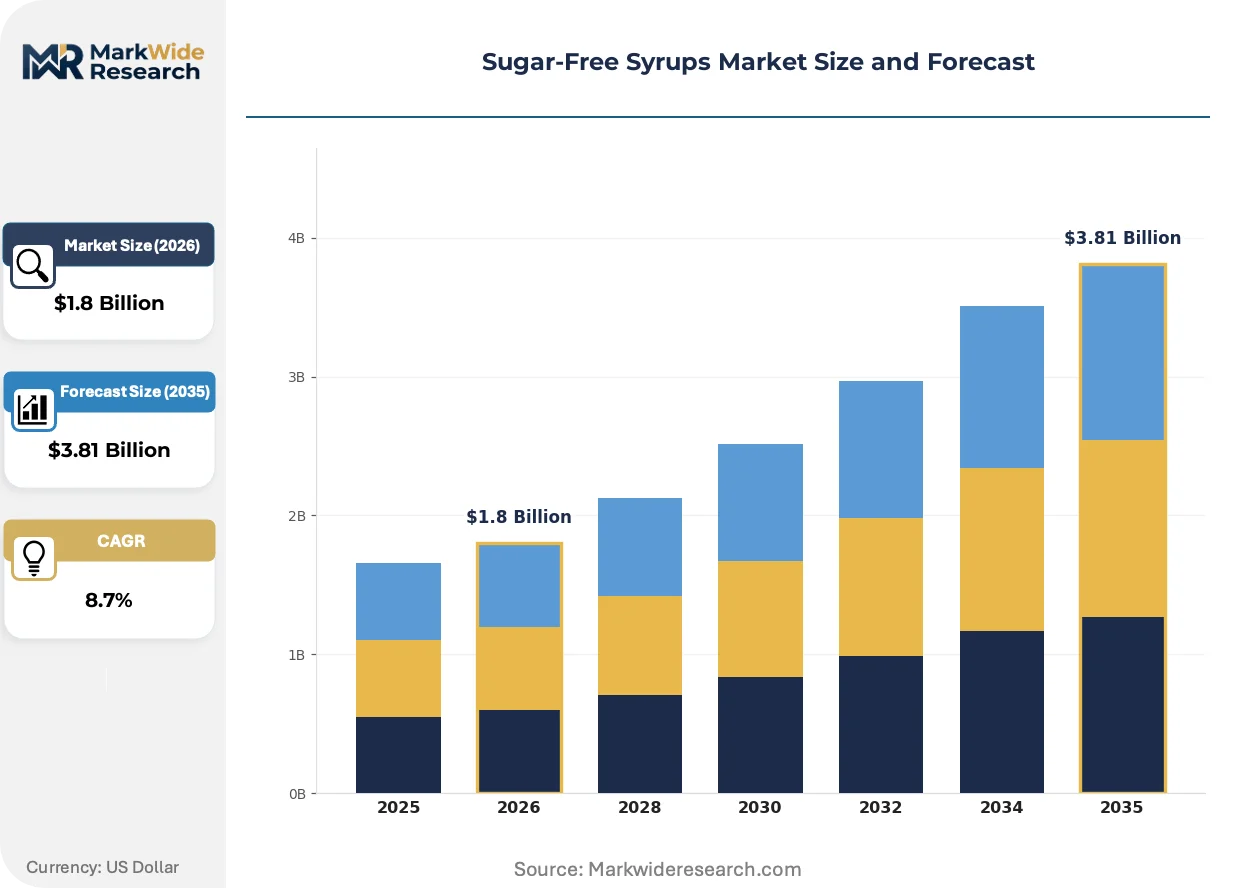
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
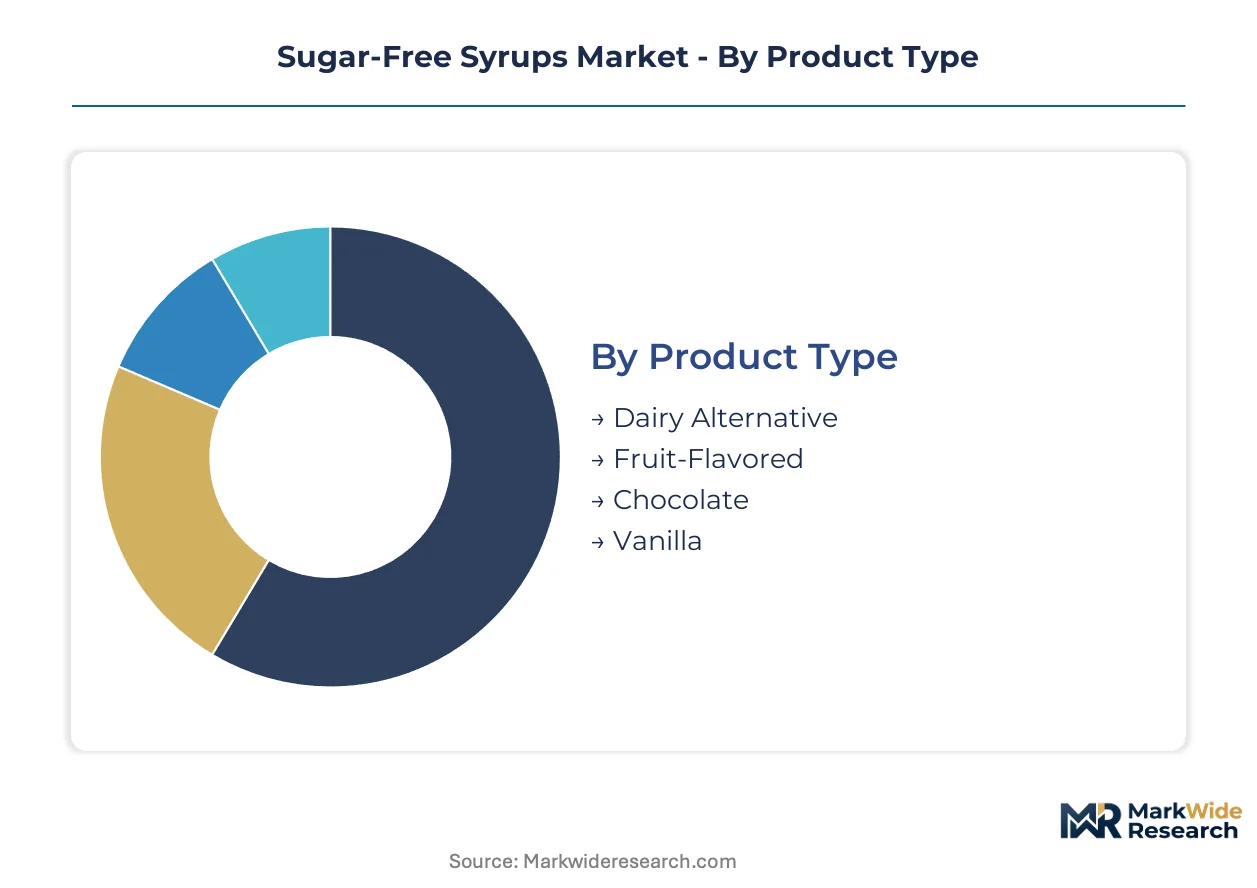
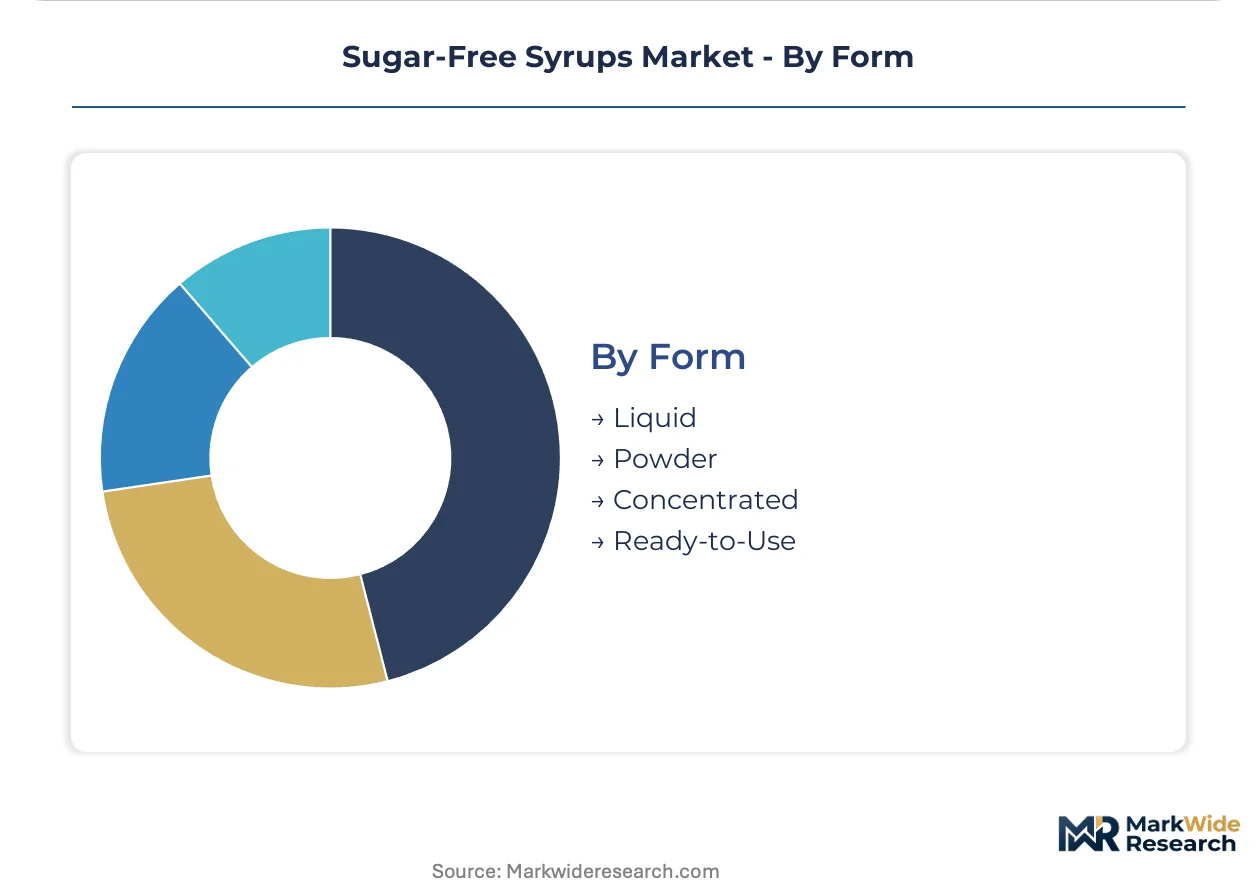
| Segmentation | Product Type: Dairy Alternative, Fruit-Flavored, Chocolate, Vanilla End User: Households, Restaurants, Cafes, Food Manufacturers Distribution Channel: Online Retail, Grocery Stores, Specialty Shops, Health Food Stores Form: Liquid, Powder, Concentrated, Ready-to-Use |
| Companies Covered | DaVinci Gourmet, Fabbri, Monin, Tastecraft, Bogari, Torani, Routin, Seasun, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Syrups Market Evolving Landscape
Digital flavor formulation platforms and precision fermentation-derived sweeteners are compressing R&D cycles while expanding the organoleptic palette available to sugar-free syrup developers.
Enzymatic bioconversion of allulose from corn starch is virtualizing traditional sucrose-replacement economics. Large beverage manufacturers in the United States are adopting this pathway for zero-calorie cola reformulations. The technology is virtualizing cost structures that previously favored artificial sweeteners, enabling broader natural-positioning adoption.
REACH authorization requirements for novel food contact substances are tightening migration testing protocols for syrup packaging films. European co-packers are accelerating compliance investments to maintain shelf access. German and French retail chains are now requiring full sweetener supply chain disclosure as a listing condition.
Direct sourcing through B2B ingredient marketplaces is fragmenting traditional distributor relationships. Small roasteries and regional bakery chains in Australia and Canada are purchasing monk fruit and erythritol blends directly from Chinese manufacturers. This channel shift is most visible in urban markets where procurement teams possess in-house regulatory documentation capabilities.
Sugar-Free Syrups Market Segmentation
Sugar-free syrup purchasing patterns diverge sharply between back-bar foodservice operations and household replenishment cycles. Understanding these behavioral splits enables suppliers to calibrate packaging formats, sweetness intensity, and distribution investments to specific channel economics.
Product Type:
After-sales intensity varies dramatically across flavor categories, with fruit-based variants requiring more frequent technical support for beverage formulation consistency than single-note profiles like vanilla or chocolate.
- Fruit-Flavored:Aqueous systems combining citric acid, potassium sorbate, and high-intensity sweeteners with natural or synthetic fruit essences; versatility across coffee, tea, and mocktail applications drives concentrated demand from United States café chains and German specialty beverage operators.
- Vanilla:Creamy, lactone-rich flavor profiles achieved through vanillin or natural vanilla extract combined with erythritol-stevia bases; premium positioning in French patisserie supply chains and Japanese home barista markets supports sustained margin capture.
- Chocolate:Cocoa alkaloid suspensions stabilized with xanthan gum for uniform dispersion in hot beverages; concentrated demand from Italian gelato manufacturers and Brazilian confectionery formulators.
- Dairy Alternative:Plant-based creamer-compatible formulations using oat or coconut milk emulsion systems; emerging traction in Nordic specialty coffee roasting operations and Australian plant-based café menus.
Fruit-flavored holds the largest share; momentum sits with vanilla as clean-label positioning intensifies.
End User:
Volume concentration follows commercial kitchen throughput, with institutional buyers commanding formulation customization and extended payment terms unavailable to household purchasers.
- Cafes:High-velocity back-bar operations requiring pump-dispensed, shelf-stable concentrates in 750ml to 1-liter formats; third-wave coffee chains in Seattle and Melbourne standardizing sugar-free flavor menus drives bulk procurement contracts.
- Restaurants:Full-service dining operations integrating syrups into dessert plating and craft cocktail programs; dessert-forward concepts in Lyon and Chicago expanding zero-sugar beverage pairings.
- Households:Direct-to-consumer purchasers through subscription models and e-commerce bulk buys; health-conscious urban demographics in London and Toronto driving auto-replenishment adoption.
- Food Manufacturers:Industrial-scale buyers requiring tanker-load deliveries of standardized sweetness bases; yogurt and ice cream processors in the Netherlands and California reformulating product lines under FDA and EFSA sugar reduction guidance.
Cafes hold the largest share; households are expanding most quickly as home espresso equipment penetration accelerates.
Distribution Channel:
Channel selection determines margin structure, with direct digital relationships capturing 15-20 point premiums over wholesale grocery placements.
- Online Retail:Direct-to-consumer and B2B marketplace platforms enabling subscription replenishment and bulk purchasing; Amazon and specialized beverage ingredient portals in the United Kingdom and Australia fragmenting traditional distributor control.
- Grocery Stores:Mass-market retail placements in conventional supermarket chains; shelf space competition in United States Kroger and Safeway banners favoring established brands with slotting fee capacity.
- Specialty Shops:Curated independent retailers serving enthusiast demographics; Italian espresso equipment dealers and Japanese kitchenware boutiques bundling syrups with machine sales.
- Health Food Stores:Natural-channel retailers emphasizing organic and non-GMO certifications; Whole Foods and regional cooperatives in California and Pacific Northwest prioritizing monk fruit and allulose-based formulations.
Grocery stores hold the largest share; online retail is gaining share fastest as procurement digitization extends to small foodservice operators.
Form:
Physical state dictates logistics economics, with concentrated and powder formats offering freight cost advantages for long-distance supply chains.
- Liquid:Ready-to-pump aqueous solutions in PET or glass packaging; dominant format for United States café back-bar operations requiring immediate dispensing without reconstitution.
- Concentrated:High-brix formulations requiring dilution prior to use; favored by German and Brazilian industrial food manufacturers for tank-farm storage efficiency.
- Powder:Spray-dried or agglomerated sweetener-flavor matrices; shelf stability advantages drive adoption in Australian remote mining camp catering and military field ration programs.
- Ready-to-Use:Single-serve portion packets and pre-mixed beverage bases; convenience positioning in Japanese vending machine channels and airline catering operations.
Liquid holds the largest share; concentrated forms show the steepest expansion trajectory as industrial reformulation scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for bulk sweetener imports, while the Los Angeles-Long Beach complex handles Pacific-rim syrup concentrate arrivals for North American formulation plants.
United States
Third-wave coffee chains in Seattle and Portland standardize sugar-free flavor menus, creating concentrated demand for back-bar syrup systems. The FDA governs sweetener safety under 21 CFR 172, with recent expanded clearances for monk fruit and allulose formulations. Industrial formulation clusters in California and Illinois are scaling enzymatic allulose production for zero-calorie beverage reformulations.
Germany
Specialty beverage operators in Berlin and Munich drive premium syrup adoption through curated café experiences. REACH authorization requirements tighten migration testing protocols for syrup packaging films, forcing co-packer compliance investments. The Rhine-Ruhr industrial corridor hosts concentrated flavor formulation capacity serving pan-European food manufacturers.
China
Urban home barista culture in Shanghai and Beijing accelerates direct-to-consumer syrup purchases through e-commerce platforms. SAMR extends novel food assessment timelines for imported monk fruit concentrates, creating regulatory friction. Guangdong and Shandong provinces cluster raw stevia leaf processing, exposing formulators to export duty volatility.
United Kingdom
Health-conscious households in London and Manchester adopt subscription auto-ship programs for premium flavor brands. EFSA coordinates additive approvals across EU member states, determining which sweetener systems retain market access. Specialty coffee roasting operations in Manchester and Bristol integrate sugar-free syrups into plant-based menu expansions.
India
FSSAI enforcement of front-of-pack sugar warnings in Maharashtra and Karnataka creates first-mover advantage for reformulated syrup suppliers. The regulator's tightening scrutiny of imported formulations demands localized compliance expertise. Mumbai and Bangalore foodservice markets show emerging whitespace as health-conscious urban demographics expand.
Sugar-Free Syrups Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sweetener bases and flavor compounds. The vendor base organizes around three strategic archetypes: European flavor houses with café chain relationships, North American direct-distribution specialists, and agricultural conglomerates with ingredient-scale economics. Dominant competitive moves include geographic expansion through bulk supply contracts and portfolio diversification into functional beverage applications.
Among European flavor houses, Monin and Routin occupy positions emphasizing back-bar penetration and bulk supply relationships with café chains. Torani anchors the North American direct-distribution tier, exemplifying the restaurant-focused archetype through private-label partnerships. Cargill sits within the agricultural conglomerate tier, representing ingredient-scale supply of erythritol and stevia blends to downstream formulators.
| Leading Market Players |
|---|
| DaVinci Gourmet |
| Fabbri |
| Monin |
| Tastecraft |
| Bogari |
| Torani |
| Routin |
| Seasun |
| Cargill |
| Others |
Value Network & Pricing Analysis
Guangdong and Shandong provinces cluster raw stevia leaf processing, concentrating upstream sweetener supply in Chinese manufacturing zones and positioning downstream formulators to capture margin through long-term offtake contracts with café chains and industrial food manufacturers.
Pricing Analysis
Volume-discount tiering structures separate premium clean-label formulations from standard artificial-sweetener blends and economy private-label supply. Price differentiation rests on organic certification status and monk fruit concentration levels. Cost compression in the standard tier is intensifying because erythritol-stevia blends require elevated flavor loads to mask aftertaste. Household purchasers through subscription channels show lowest price sensitivity; small foodservice operators purchasing through B2B marketplaces are most price-sensitive.
Supply Chain Analysis
Export-control regimes limiting flows of novel food contact substances under REACH authorization requirements constrain European co-packer flexibility. Supply concentrates in China for stevia and monk fruit raw material, the United States for enzymatic allulose production, and Germany for flavor formulation capacity. Formulators draw from erythritol, stevia extracts, and allulose as core inputs. Single-source vulnerability in Chinese stevia leaf processing exposes margin to export duty volatility. Distribution runs through direct-to-restaurant networks for bulk foodservice supply and e-commerce platforms for household replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation expertise bridging high-intensity sweetener stability with thermal processing requirements commands substantial salary premiums, creating a persistent capability gap that rewards firms investing in captive technical talent and R&D infrastructure.
For Market Incumbents: Build formulation-IP moats through patent protection of enzymatic allulose conversion processes and proprietary flavor masking systems. Defensive moves should include backward integration into stevia cultivation partnerships in Guangdong to reduce tariff exposure, and certification investment in Non-GMO Project validation cycles to delay competitive launches. The threat of direct B2B marketplace procurement by small roasteries erodes traditional distributor control. For New Entrants and Emerging Players: Indian foodservice whitespace in Maharashtra and Karnataka offers the most penetrable entry point, with FSSAI sugar warning enforcement creating first-mover advantage for reformulated syrup suppliers. Target the café segment through localized compliance expertise and direct relationships with Mumbai and Bangalore third-wave coffee operators. The optimal go-to-market angle is regulatory-navigation services bundled with product supply. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier flavor houses with established café chain relationships and scalable clean-label certification pipelines. Long-term viability across the analysis window favors firms with demonstrated monk fruit and allulose formulation capabilities aligned with FDA 21 CFR 172 expansion trends. The signal to watch is SAMR approval velocity for imported novel sweeteners as an inflection indicator for Chinese market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Cultivation | Captive supply from Guangdong plantations reduces exposure to Chinese export duty volatility. |
| Clean-Label Certification Investment | Non-GMO Project and organic validation cycles create 18-24 month competitive barriers for rivals. |
| Direct-to-Consumer Subscription Launch | Auto-ship programs in London and Manchester reduce customer acquisition costs for premium brands. |
| Functional Beverage Convergence | Collagen-infused and adaptogenic applications in South Korea pull syrups into nutraceutical positioning. |
| Regulatory Navigation Services | Localized FSSAI and SAMR expertise creates first-mover advantage in tightening compliance environments. |
Research Methodology
The analysis maps fruit-flavored, vanilla, chocolate, and dairy-alternative syrup sub-sectors, each validated through flavor chemists, café procurement managers, food manufacturer R&D directors, and e-commerce platform category leads. Primary interviews with these stakeholders combined with secondary validation from FDA 21 CFR 172 filings, EFSA novel food assessments, FSSAI enforcement notices, and customs trade data. Bottom-up volume estimates from individual product categories triangulated against top-down market sizing from sweetener consumption patterns.
Assumptions held constant include prevailing FDA and EFSA regulatory frameworks, existing stevia supply concentration in Chinese provinces, and continuation of WHO sugar reduction guidance adoption rates. Segmentation dimensions modeled encompass product type, end-user channel, distribution pathway, and physical form across the projection horizon. CAGRs derived from historical volume trajectories adjusted for channel-shift acceleration and reformulation mandate timelines. Industry-specific inputs include home espresso equipment penetration rates and enzymatic allulose production scaling curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by agricultural conglomerates with ingredient-scale economics would shift outcomes through vertical integration into downstream formulation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Muscovado Sugar Market
Sweeteners
South Korea Allulose Market
Sweeteners
Allulose Powder Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
India Food Sweetener Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Sweeteners Market
Sweeteners
Mannitol Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Stevia Mints Market
Sweeteners
Steviol Glycoside Market