
 Vintage Bulb Market | 2026-2036
Vintage Bulb Market Size, Share, and Industry Trends Forecast 2026-2036
Vintage Bulb Market Analytics
The capital-intensity gap between artisan glassworks and mass producers is collapsing as automated filament-winding equipment reaches smaller factories. Westinghouse Lighting leverages its century-old brand recognition to sustain premium positioning in North American retail channels. Philips competes through backward integration into LED chip fabrication, controlling cost structures that artisan rivals cannot match. Aladdin Industries anchors its niche in oil-lamp heritage aesthetics, occupying a defensible position among restoration specialists and museum gift stores.
Vintage bulbs encompass electrically powered light sources engineered to replicate the warm amber glow, visible filament architecture, and spherical or elongated glass envelopes characteristic of early twentieth-century illumination technology, typically operating at color temperatures between 2200K and 2700K with dimmable drivers. These products serve primarily decorative and ambient lighting functions in hospitality, residential, and retail environments where atmospheric quality supersedes raw lumen output. LED filament variants now lead value generation across the product type dimension, capturing margin pools from incandescent alternatives facing regulatory phase-out. Decorative lighting applications represent the fastest-growing segment as restaurant and hotel designers specify vintage aesthetics for brand differentiation. Globe shapes dominate residential channels while Edison profiles concentrate in commercial installations seeking industrial heritage cues.
The EU Ecodesign Directive and REACH frameworks constrain mercury content and minimum efficacy thresholds, forcing incandescent and halogen variants toward specialty exemption pathways or outright displacement. The US Department of Energy's appliance standards program and California Title 20 regulations impose comparable efficiency floors that reshape import eligibility and domestic manufacturing requirements. China's GB standards for lighting products add compliance layers for export-oriented producers serving multiple jurisdictions. Stakeholders must monitor regulatory harmonization gaps between efficiency mandates and aesthetic preservation exemptions that determine viable product architectures.
Market Dynamics
The EU Ecodesign Directive's progressive wattage restrictions are compressing incandescent bulb availability while redirecting specification flows toward compliant LED filament architectures that preserve heritage aesthetics.
Growth Catalysts
- EU Ecodesign Directive:The regulatory framework's phase-out schedule for inefficient lighting creates mandatory replacement cycles in Germany's contract interiors sector, where heritage aesthetics command specification premiums.
- Boutique hospitality chains:Paris and Brooklyn property developers now specify filament-style Edison bulbs for lobby and restaurant fit-outs, embedding vintage lighting into brand identity standards.
- Automated filament-winding:This manufacturing process is collapsing the capital-intensity gap between artisan glassworks and mass producers, enabling smaller factories to enter premium segments.
Market Restraints
- Mercury content thresholds:REACH frameworks constrain certain specialty bulb chemistries, forcing incandescent and halogen variants toward narrow exemption pathways or displacement.
- Input cost volatility:Rare earth elements in LED chip substrates face price instability from concentrated upstream supply in China.
- Substitution threat:Smart ambient lighting systems with programmable color temperatures threaten vintage bulb positioning in residential renovation projects.
Strategic Opportunities
- Underpenetrated museum sector:Restoration specialists and museum gift stores represent untapped distribution channels for heritage-authentic lighting products.
- Regulatory tailwind:California Title 20 regulations and US Department of Energy appliance standards create compliance-driven demand for LED filament alternatives.
- Technology convergence:Dimmable LED drivers combined with visible filament architecture bridge efficiency mandates and aesthetic preservation requirements.
Industry Challenges
- Glassblowing skill scarcity:Artisan envelope production requires specialized craft capabilities that aging workforce demographics threaten.
- Multi-jurisdiction certification:China's GB standards, EU CE marking, and US compliance layers impose fragmented testing timelines for export-oriented producers.
- Legacy electrical infrastructure:Historic building rewiring constraints limit LED driver compatibility in certain restoration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vintage Bulb Market |
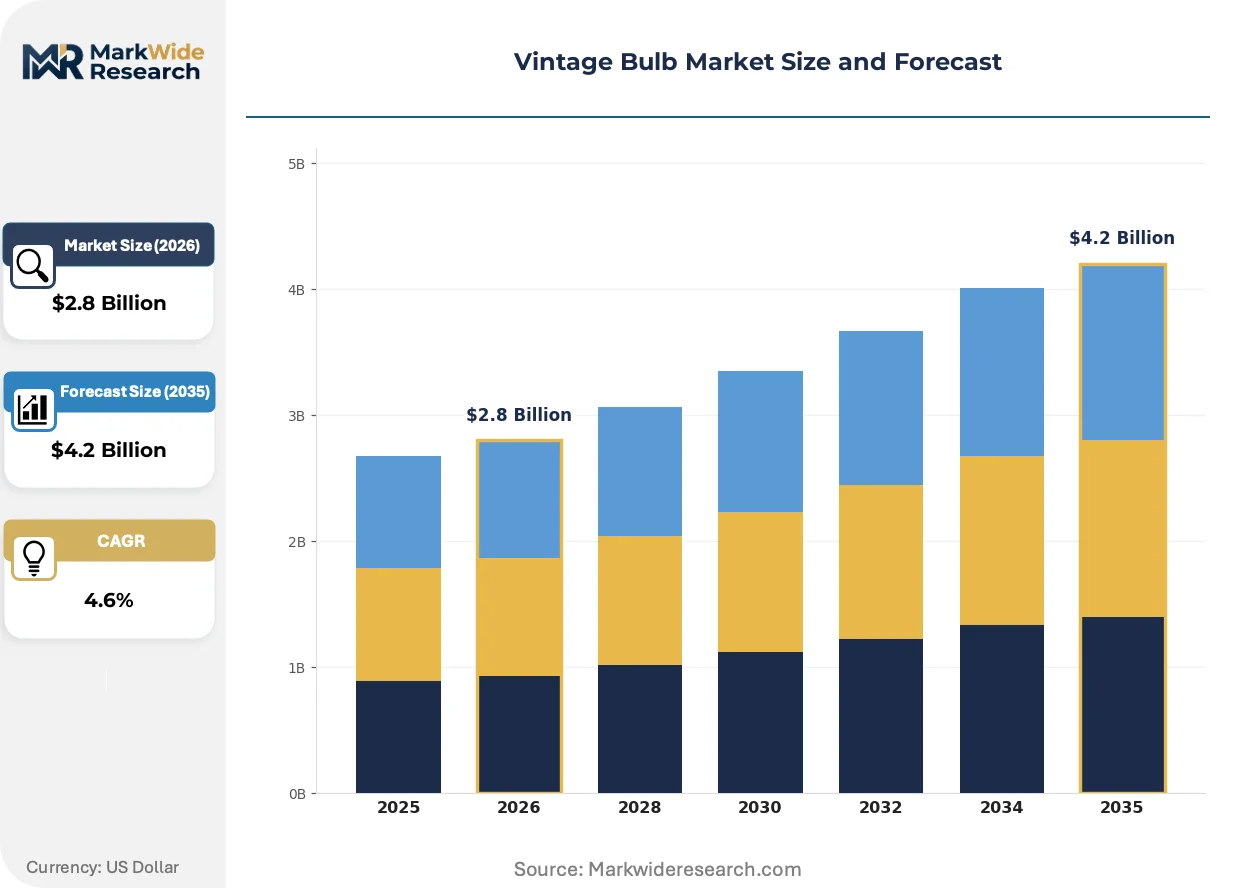
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Incandescent, Halogen, Fluorescent Application: Residential Lighting, Commercial Lighting, Decorative Lighting, Outdoor Lighting Shape: Filament, Globe, Edison, Candle Wattage: Low Wattage, Medium Wattage, High Wattage, Ultra High Wattage |
| Companies Covered | Artemide, Nessen Lighting, O-luce, Pairpoint Corporation, Phoenix Glass Company, Westinghouse Lighting, Philips, Lightolier, Aladdin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vintage Bulb Market Evolving Landscape
Specification behavior in hospitality and residential channels is fragmenting as buyers prioritize atmospheric quality metrics over raw lumen output, compressing traditional performance-based procurement criteria.
LED filament technology is decomposing the historical trade-off between energy efficiency and visible filament aesthetics. Hospitality designers in Germany and France specify these hybrids for dimmable ambient installations. The technology is decomposing price premiums previously captured by artisan incandescent producers.
REACH and the EU Ecodesign Directive are tightening mercury content and minimum efficacy thresholds simultaneously. Incandescent variants face specialty exemption narrowing or outright displacement. Germany's design-conscious contract interiors sector responds by accelerating LED filament specification rates.
Buyer concentration among boutique hotel chains and restaurant groups is consolidating procurement authority at the brand-design level. Traditional electrical distributors lose specification influence to hospitality design firms. Brooklyn and Paris property developments exhibit this pattern most visibly.
Vintage Bulb Market Segmentation
Vintage bulb procurement channels diverge sharply by segment—contract interior designers source architectural shapes directly from manufacturers, while retail distributors handle residential replacements. Channel fragmentation forces suppliers to maintain parallel go-to-market structures with incompatible margin profiles.
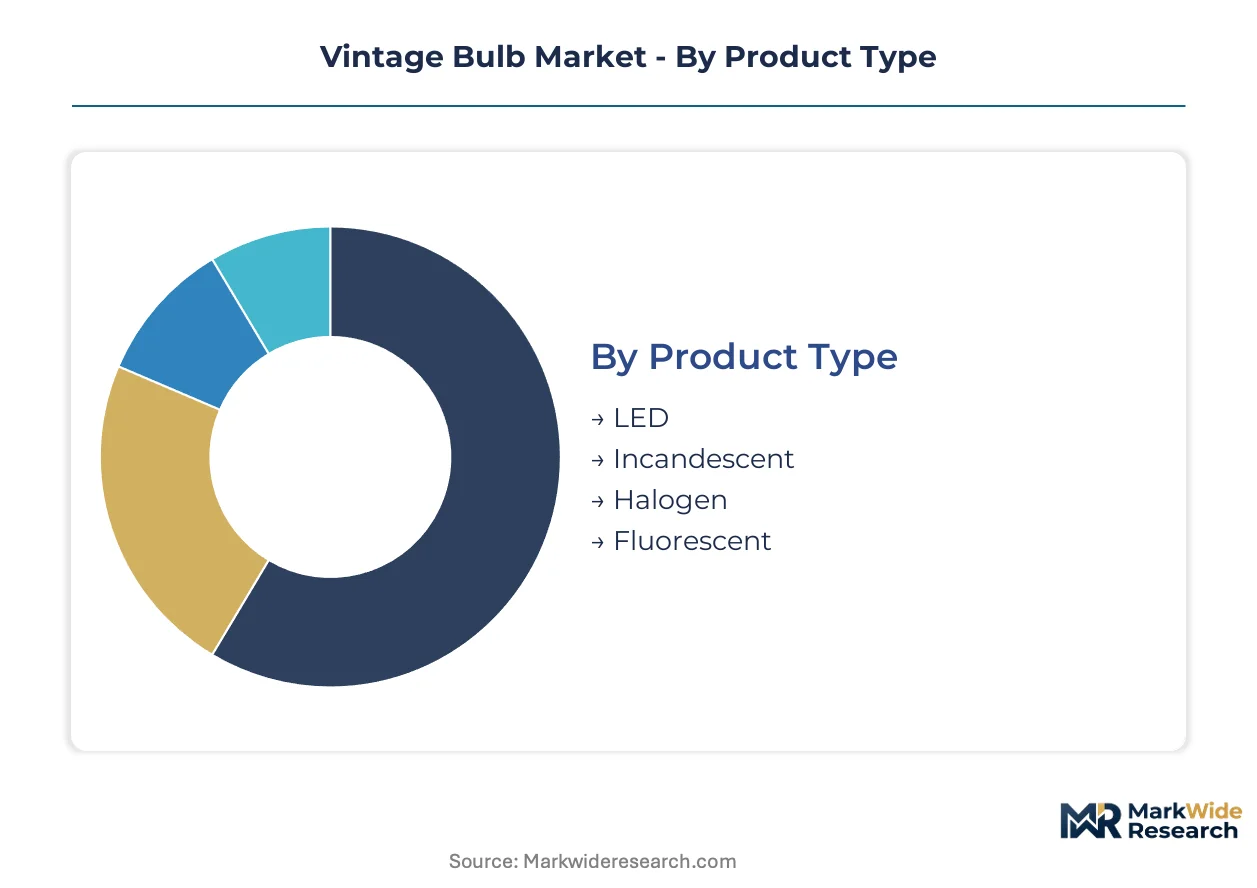
Product Type:
LED filament architectures flow through specification-grade channels to hospitality designers, while incandescent remnants persist in restoration-specialty retail. Channel conflict intensifies as mass-market distributors attempt to stock both tiers.
- LED:Visible filament construction replicates incandescent amber glow at 2200K-2700K color temperatures with dimmable drivers. Germany's contract interiors sector specifies these for Ecodesign compliance without sacrificing heritage aesthetics.
- Incandescent:Tungsten filament technology delivers authentic thermal radiation and continuous spectrum rendering. REACH mercury thresholds and EU wattage phase-outs compress availability toward narrow specialty exemptions in museum restoration channels.
- Halogen:Compact filament envelopes with halogen regenerative cycle extend service life in enclosed fixtures.
- Fluorescent:Mercury vapor excitation produces vintage-styled envelopes with phosphor-converted output, constrained by disposal regulations.
LED dominates installed base in commercial specification. Incandescent is where expansion concentrates in heritage-authentic restoration niches.
Application:
Margin structures invert across applications—decorative projects command 3-4x material premiums over functional residential replacements, while outdoor installations face harsh-environment warranty costs that compress profitability.
- Residential Lighting:Globe shapes prevail in living room and bedroom ambient installations where homeowners prioritize atmospheric warmth over task illumination. Brooklyn brownstone renovations specify dimmable Edison profiles for exposed fixture aesthetics.
- Commercial Lighting:Boutique hospitality chains in Paris embed filament-style specifications into brand identity standards for lobby and restaurant fit-outs, consolidating procurement authority at the design-firm level.
- Decorative Lighting:Purely aesthetic function supersedes lumen output metrics in specification criteria. This segment climbs fastest as atmospheric quality metrics displace traditional performance-based procurement.
- Outdoor Lighting:Weather-resistant envelope sealing and thermal management requirements constrain vintage aesthetic replication.
Commercial Lighting dominates installed base. Decorative Lighting is where expansion concentrates.
Shape:
Manufacturing tooling costs fragment competitive dynamics—Edison profiles require specialized filament-winding equipment that favors automated factories, while artisan glassworks retain advantage in irregular hand-blown Candle variants.
- Filament:Linear LED arrays arranged in visible helical or looped patterns replicate early electrical illumination architecture. Automated winding equipment collapses capital barriers between mass producers and smaller factories.
- Globe:Spherical glass envelopes distribute light uniformly for pendant and chandelier installations. Residential channels concentrate demand here for vanity and dining room fixtures.
- Edison:Elongated pear-shaped envelopes with exposed squirrel-cage or spiral filaments anchor industrial heritage aesthetics. Commercial installations in Germany and France specify these for brand differentiation.
- Candle:Tapered flame-shaped envelopes replicate gaslight and candle antecedents for wall sconce and candelabra applications.
Filament dominates installed base. Edison is where expansion concentrates.
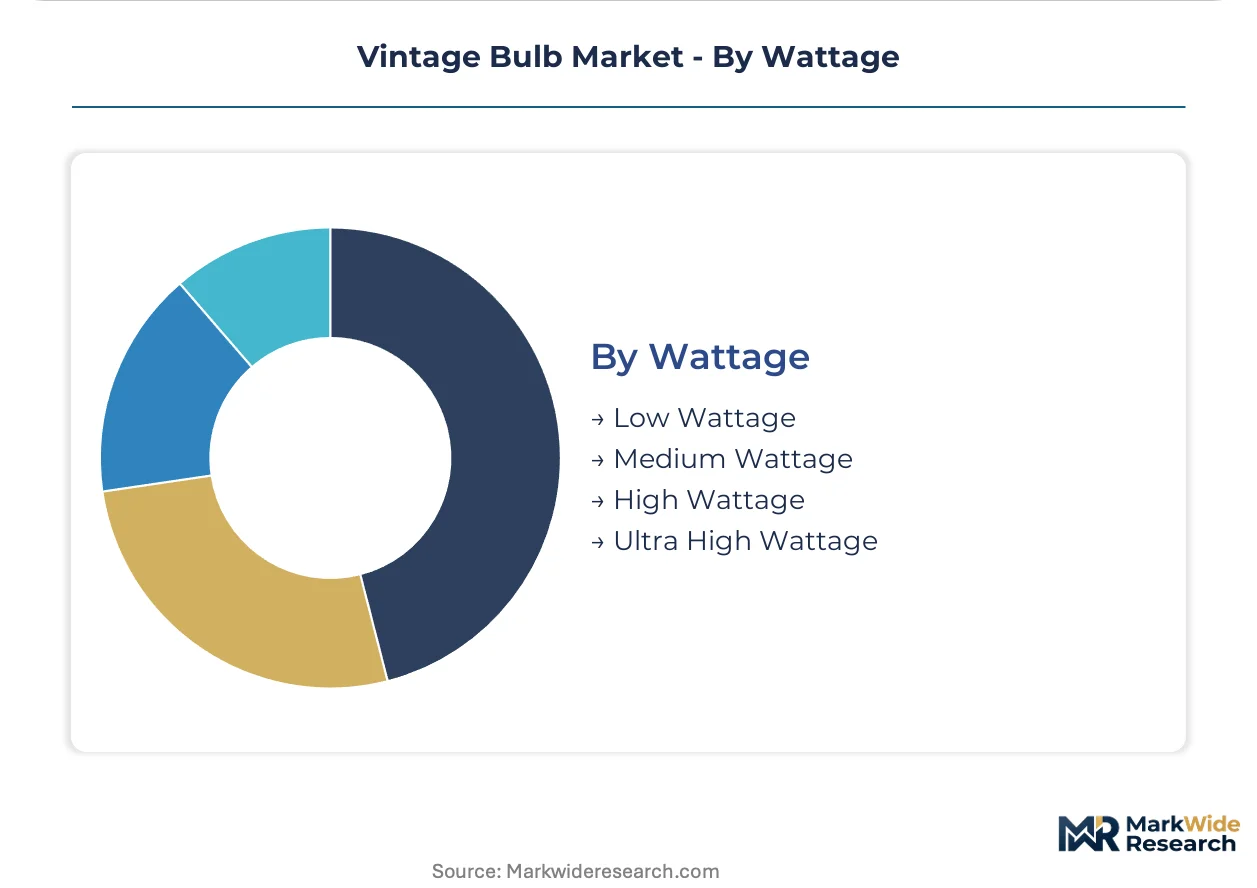
Wattage:
Regulatory thresholds slice the wattage spectrum into incompatible compliance zones—low and medium tiers face mandatory LED displacement, while high-wattage specialty exemptions preserve incandescent architectures for authentic restoration.
- Low Wattage:Sub-25W equivalents for accent and indicator lighting in hospitality wayfinding. EU Ecodesign Directive efficacy floors eliminate incandescent options here entirely.
- Medium Wattage:25-60W range for general ambient illumination in residential and commercial settings. LED filament technology captures specification share as compliance mandates tighten.
- High Wattage:60-100W equivalents for primary illumination in larger volume spaces. Historic building electrical infrastructure constraints limit LED driver compatibility in certain restoration projects.
- Ultra High Wattage:Above-100W specialty applications for industrial heritage replication and theatrical lighting. Narrow exemption pathways preserve incandescent availability for museum and film production procurement.
Medium Wattage dominates installed base. Low Wattage is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes vintage bulbs primarily through specification-grade contract interiors, while the United States channels demand through retail home renovation and boutique hospitality fit-outs. France concentrates procurement authority within Paris-based design firms. China's production clusters supply LED filament architectures globally.
Germany
Contract interior designers in Berlin and Munich specify LED filament bulbs for Ecodesign Directive compliance without sacrificing heritage aesthetics. REACH mercury thresholds constrain specialty incandescent chemistries, narrowing exemption pathways. The Baden-Württemberg manufacturing corridor hosts automated filament-winding equipment suppliers serving smaller factories entering premium segments.
United States
Brooklyn brownstone renovations and boutique hotel chains drive Edison-profile demand for exposed fixture aesthetics. California Title 20 regulations and Department of Energy appliance standards reshape import eligibility and domestic manufacturing requirements. The Pacific Northwest restoration specialist network preserves incandescent procurement for heritage-authentic museum projects.
France
Paris property developers embed filament-style specifications into brand identity standards for lobby and restaurant fit-outs. EU Ecodesign Directive phase-out schedules create mandatory replacement cycles in hospitality design. The Île-de-France design firm cluster consolidates procurement authority away from traditional electrical distributors.
China
Export-oriented producers serve multiple jurisdictions with GB standards-compliant LED filament architectures. Rare earth element price instability in LED chip substrates originates from concentrated upstream supply. The Yangtze River Delta manufacturing base supplies automated winding equipment collapsing capital barriers for smaller factories.
United Kingdom
London hospitality designers specify vintage bulbs for atmospheric quality metrics displacing traditional performance-based procurement. CE marking requirements align with EU regulatory frameworks post-transition. The Midlands industrial heritage restoration sector maintains narrow incandescent exemption pathways for museum-authentic lighting.
Vintage Bulb Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with brand-heritage incumbents and automated manufacturers occupying distinct competitive spaces. The structure fragments across specification-grade and retail channels with incompatible margin profiles. Three archetypes dominate: century-old lighting brands leveraging recognition for premium positioning, LED chip fabricators controlling cost structures through backward integration, and artisan glassworks defending niche restoration markets. Competitive moves concentrate on automated manufacturing adoption and regulatory compliance certification across multi-jurisdiction frameworks.
Among heritage-brand incumbents, Westinghouse Lighting and Aladdin Industries exemplify distinct positioning vectors. Westinghouse occupies a position anchored in North American retail channel recognition, while Aladdin Industries represents the restoration-specialist archetype serving museum gift stores and heritage-authentic procurement. Philips sits within the integrated-technology tier, with LED chip fabrication capabilities distinguishing its cost structure from artisan rivals. These three players illustrate how brand age, manufacturing integration depth, and channel specialization segment competitive territory.
| Leading Market Players |
|---|
| Artemide |
| Nessen Lighting |
| O-luce |
| Pairpoint Corporation |
| Phoenix Glass Company |
| Westinghouse Lighting |
| Philips |
| Lightolier |
| Aladdin Industries |
| Others |
Value Network & Pricing Analysis
EU CE marking requirements gate both supply qualification and price differentiation simultaneously, forcing export-oriented producers to absorb multi-jurisdiction testing costs that stratify competitive tiers. Compliance layering creates natural segmentation between specification-grade channels serving hospitality designers and mass-market retail distributors, with certification investment acting as a pricing floor that artisan glassworks struggle to clear.
Pricing Analysis
Long-term offtake contracts dominate specification-grade channels serving Paris and Berlin hospitality designers, while spot-market transactions prevail in residential replacement segments. Three-tier pricing structure across heritage-authentic, LED filament, and mass-market economy levels tracks certification grade and visible filament craftsmanship. Cost compression in the economy tier intensifies as automated winding equipment collapses capital barriers for smaller factories. Boutique hospitality chains exhibit the lowest price sensitivity, prioritizing atmospheric quality metrics over unit economics.
Supply Chain Analysis
China and Germany anchor global LED filament architecture production, with the Yangtze River Delta manufacturing base supplying automated winding equipment and the Baden-Württemberg corridor hosting precision glassworks. Rare earth elements in LED chip substrates and artisan borosilicate glass envelopes constitute critical input dependencies. Single-source vulnerability concentrates in Chinese rare earth processing for phosphor-converted output. Distribution runs through parallel channels: direct manufacturer relationships for contract interior designers, and electrical distributor networks for residential replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in specification-grade channels where procurement authority shifts from traditional distributors to hospitality design firms, creating niche entry points for specialized producers.
For Market Incumbents: Fortify specification-grade channel control by deepening relationships with Paris and Berlin design firms before procurement authority consolidates further. Invest in automated filament-winding capacity to match cost structures of emerging mid-tier competitors. LED chip fabrication capabilities and CE marking certification breadth serve as critical defensive levers against backward-integrated challengers. For New Entrants and Emerging Players: Differentiate on heritage-authentic restoration credentials targeting museum gift stores and Pacific Northwest preservation specialists where incandescent exemptions persist. The underpenetrated museum sector offers the most penetrable white space, with narrow regulatory pathways protecting against mass-market displacement. A direct-to-restoration-specialist go-to-market angle bypasses distributor margin compression entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across LED filament manufacturing as automated equipment reaches smaller factories, compressing returns for late capital deployment. Acquisition target archetypes include artisan glassworks with defensible museum-channel positioning and automated mid-tier producers with CE marking breadth. The signal to watch is REACH exemption pathway narrowing for mercury-containing chemistries, which would accelerate LED filament substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Filament-Winding Adoption | Collapses capital barriers between artisan glassworks and mass producers in Germany and China. |
| Multi-Jurisdiction Certification Investment | CE marking, California Title 20, and GB standards compliance gates specification-grade channel access. |
| Direct Design-Firm Partnership | Bypasses electrical distributor margin compression in Paris and Brooklyn hospitality procurement. |
| Heritage-Authentic Product Line Extension | Captures museum restoration premiums as REACH mercury thresholds narrow incandescent exemptions. |
| Backward Integration into LED Chip Supply | Controls rare earth element cost volatility from concentrated Chinese upstream supply. |
Research Methodology
Desk research of EU regulatory filings, customs trade data, and hospitality design specification databases preceded structured interviews with contract interior designers, lighting procurement managers at boutique hotel chains, glassworks production engineers, and electrical distributor category buyers. Primary fieldwork across Berlin, Paris, Brooklyn, and Shenzhen validated secondary findings on automated manufacturing adoption and channel fragmentation patterns. Bottom-up shipment data triangulated against top-down spending estimates from contract interiors sector reports.
Variance decomposition across product type, application, shape, and wattage dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion constraints. Industry-specific forecast inputs included EU Ecodesign Directive phase-out schedules and REACH mercury threshold enforcement timelines.
Material uncertainties — regulatory harmonization gaps between efficiency mandates and aesthetic preservation exemptions, rare earth element price volatility, and smart ambient lighting substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about LED filament technology cost curves and hospitality sector renovation cycles. Recalibration cycles align with material shifts in EU regulatory enforcement and boutique hospitality chain expansion patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Directional Luminaire Market
Lighting
Smart Lighting Market
Lighting
Xenon Headlights Market
Lighting
UAE Smart Lighting Market
Lighting
Studio Lighting Equipment Market
Lighting
Fluorescent Lighting Market
Lighting
Solid State Lighting System Market
Lighting
Ultraviolet Lamps Market
Lighting
Global Lighting Control System Market
Lighting
Solar Column Headlight Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Intelligent Lighting Controls Market
Lighting
Connected Lighting Platform Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Solar Rope Light Market
Lighting
Photocell Market