
 Industrial OLED Lighting Market | 2026-2036
Industrial OLED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial OLED Lighting Market Insights
Project finance for OLED fabrication lines is tilting competitive advantage toward capital-heavy incumbents with established credit access. LG Display leverages its Gen-8.5 OLED capacity to dominate industrial panel supply. Samsung Display anchors premium rigid panel output through in-house material synthesis. OLEDWorks specializes in small-batch, high-uniformity panels for precision equipment lighting.
Industrial OLED lighting comprises solid-state electroluminescent devices employing organic emissive layers deposited on glass or flexible substrates, typically operating at color temperatures between 3000K and 6500K with CRI values exceeding 90, designed to deliver uniform, glare-free illumination for manufacturing environments where thermal management and spectral precision directly affect output quality. Flexible OLED panels capture expanding share in cold storage retrofit applications where low-profile form factors reduce condensation risk. White OLED technology leads in quality inspection lighting due to its broadband spectral output. Warehouse lighting applications remain the largest application segment by installed base, though precision equipment lighting generates superior margin pools per lumen delivered.
EPA energy efficiency standards and OSHA workplace illumination requirements shape product certification pathways in the United States, while EU REACH restrictions on hazardous substances constrain phosphorescent emitter chemistries imported into Europe. China's GB standards for solid-state lighting, enforced by SAMR, mandate flicker metrics that favor DC-driven OLED architectures over PWM-modulated alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
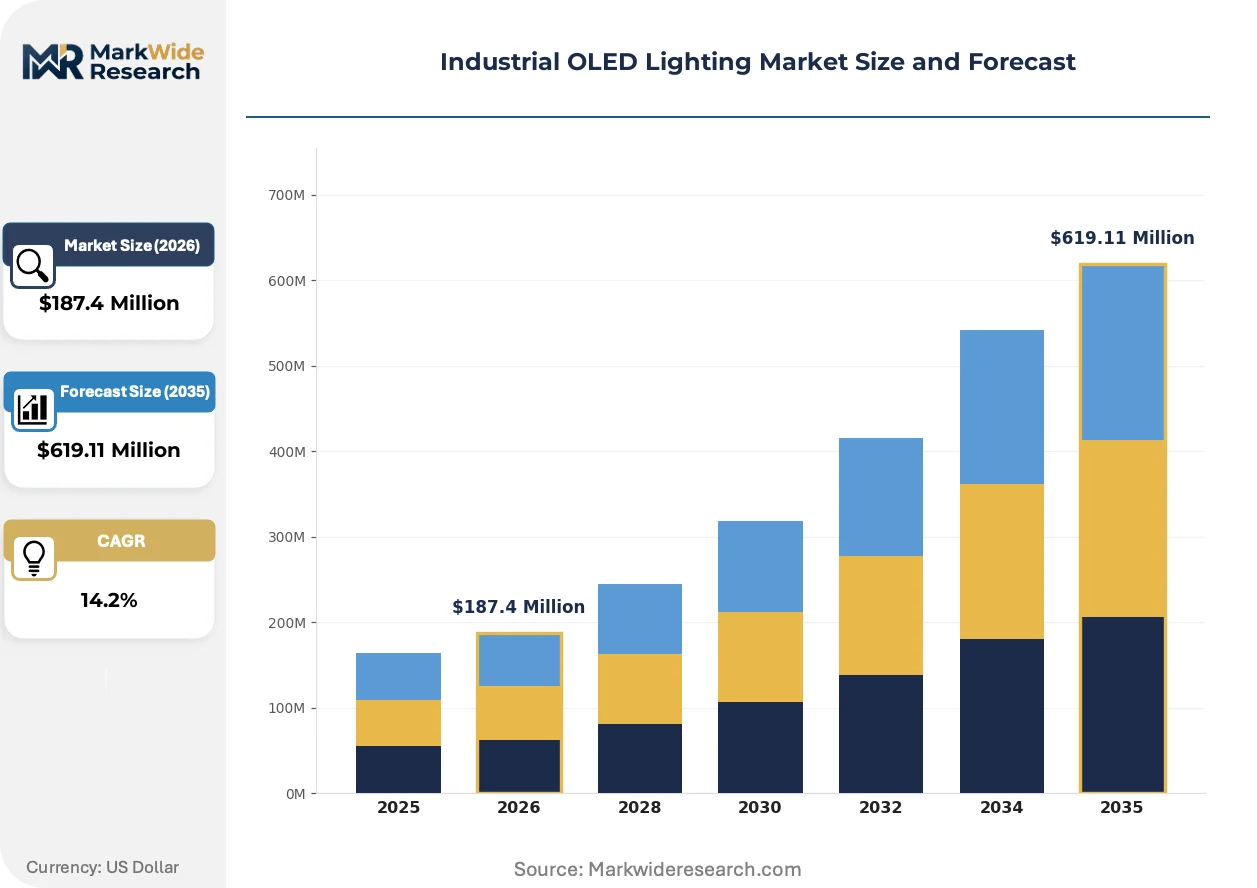
Market Dynamics
Capital concentration in Gen-8.5 OLED fabrication is locking out mid-tier entrants and consolidating supply-side leverage among Korean and Chinese panel makers with state-backed credit facilities.
Growth Catalysts
- EU Green Deal efficiency mandates:Automotive suppliers in Germany are retrofitting factory floors with OLED task lighting to meet 2030 carbon reduction targets, creating anchored demand for high-uniformity panels.
- Flexible substrate advances:Cold storage operators are specifying bendable OLED panels for low-profile ceiling installations where condensation risks exclude conventional luminaires.
- South Korean production clustering:Pangyo and Paju industrial zones concentrate deposition equipment, emitter chemistry, and driver IC fabrication within 50-kilometer radii, compressing lead times for export orders.
Market Restraints
- Iridiun complex cost volatility:Phosphorescent emitter precursors trade on thin spot markets, exposing panel makers to 20-40% quarterly price swings that resist long-term contracting.
- Deposition equipment oligopoly:Canon Tokki and Sunic System control 90% of Gen-8.5 evaporation tool supply, creating single-source vulnerability for capacity expansions.
- LED substitution pressure:Chip-on-board LED arrays with optical diffusers achieve 85+ CRI at one-third the lumen-dollar cost, capturing warehouse retrofit budgets.
Strategic Opportunities
- Precision agriculture lighting:Vertical farming operators in the Netherlands are piloting tunable-spectrum OLED panels for photomorphogenic control, opening a lumen-intensity segment outside industrial manufacturing.
- India PLI scheme extension:Modified incentive structures for display component manufacturing could attract emitter synthesis and driver IC packaging to Noida and Sri City SEZs.
- Digital twin convergence:Integration of OLED lighting controls with Siemens NX and Dassault DELMIA platforms enables real-time spectral adjustment tied to quality inspection algorithms.
Industry Challenges
- Thin-film encapsulation talent scarcity:Fewer than 200 engineers globally possess production-grade expertise in multi-layer barrier deposition, constraining yield ramp rates at new fabs.
- Cross-jurisdictional certification lag:Divergent flicker metrics between China's SAMR GB standards and EPA testing protocols force dual test matrixes that extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial OLED Lighting Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible OLED Panels, Rigid OLED Panels, Transparent OLED Panels, Top-Emission OLED Panels Technology: Small-Molecule OLED, Polymer OLED, Hybrid OLED, White OLED Application: Warehouse Lighting, Factory Floor Illumination, Precision Equipment Lighting, Quality Inspection Lighting, Cold Storage Lighting End User: Manufacturing Plants, Automotive Suppliers, Electronics Assemblers, Aerospace Production, Food Processing Units |
| Companies Covered | LG Display, Samsung Display, BOE Technology, Visionox, Signify, ams OSRAM, Acuity Brands, Konica Minolta, OLEDWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial OLED Lighting Market Trends and Innovations
Spectral tunability and substrate flexibility are collapsing the boundary between functional illumination and process-integrated quality control systems across precision manufacturing environments.
Tandem OLED architectures with charge generation layers are virtualizing the lumen-output-per-watt trajectory that single-stack designs approached asymptotically. Semiconductor fabs in Taiwan are specifying these stacks for cleanroom photolithography bays where spectral stability affects defect detection rates. The technology is virtualizing the competitive gap between OLED and advanced LED systems in color-critical applications.
REACH authorization requirements for iridium-based phosphorescent emitters are forcing European panel importers to maintain dual supply chains with thermally activated delayed fluorescence alternatives. ECHA's 2024 substance evaluation timeline has compressed qualification windows for new emitter chemistries. German automotive lighting divisions are accelerating in-house synthesis partnerships to secure non-iridium feedstock.
Specification authority is migrating from facilities managers to production engineers who prioritize spectral metrics over installed cost. Japanese electronics assemblers now issue purchase orders through MES-integrated procurement portals that auto-populate CRI and CCT requirements from work order data. This shift is most pronounced in South Korea's display panel fabs where lighting specifications tie directly to automated optical inspection calibration protocols.
Industrial OLED Lighting Market Segmentation
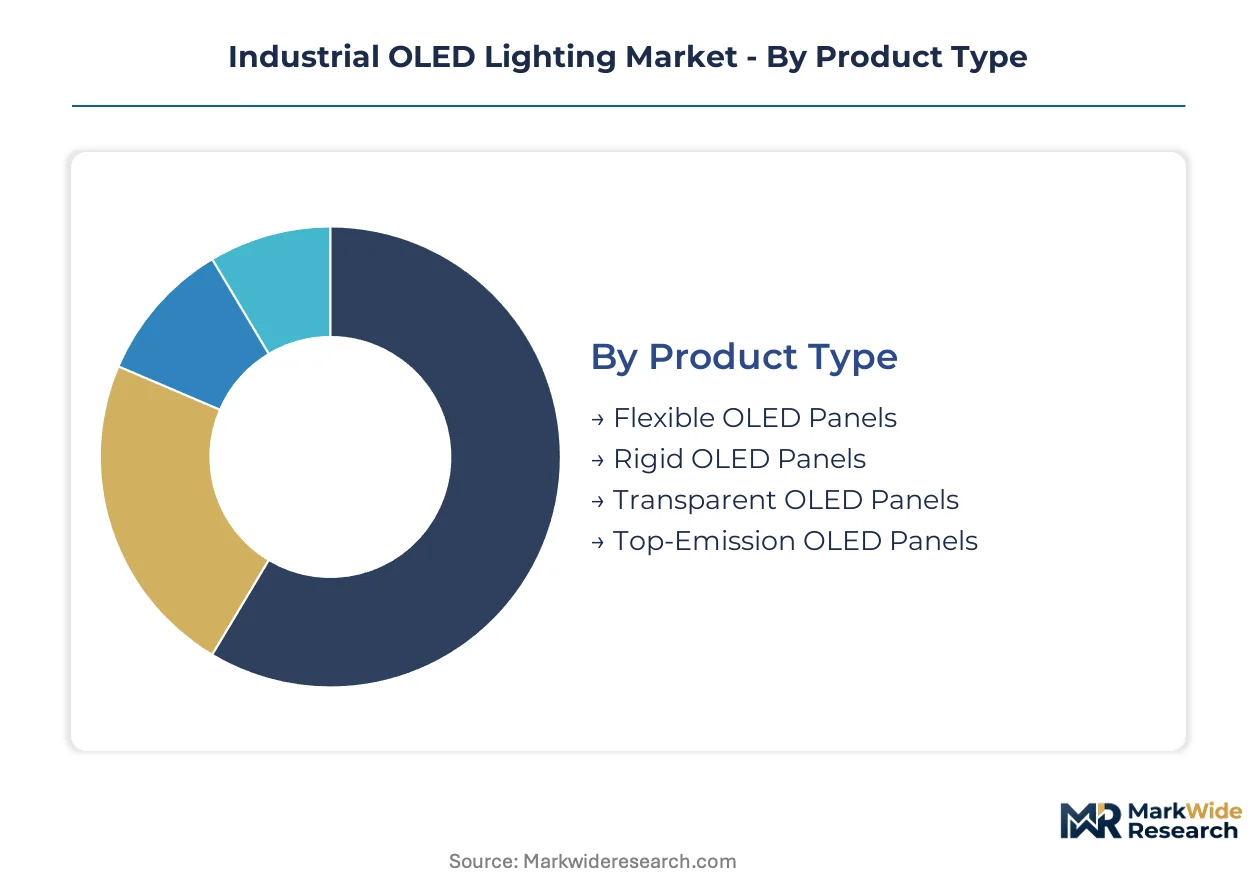
Industrial OLED lighting segments fragment across substrate physics, emitter chemistry, and installation environment. Procurement patterns diverge sharply between facilities managers optimizing lumen-dollar metrics and production engineers prioritizing spectral precision for automated inspection systems.
Product Type:
Mature rigid formats dominate installed base volumes while emerging flexible architectures capture specification authority in retrofit-intensive verticals.
- Rigid OLED Panels:Glass-substrate construction delivers thermal stability and mechanical protection for high-bay warehouse installations. German automotive suppliers specify these for factory floor retrofits under EU Green Deal efficiency mandates, though substrate weight limits suspended mounting options.
- Flexible OLED Panels:Polyimide or thin-glass substrates enable conformal mounting on curved surfaces and low-profile ceiling assemblies. Cold storage operators in South Korea specify bendable panels where condensation risks exclude conventional luminaires, compressing installation depth to under 10 millimeters.
- Transparent OLED Panels:Partial transparency suits display-integrated lighting in electronics assembly cleanrooms where visual access to underlying equipment matters.
- Top-Emission OLED Panels:Light extraction through the top electrode rather than transparent substrate improves efficiency in directional task lighting configurations.
Rigid panels handle the majority of throughput; flexible panels are gaining share fastest in cold chain retrofit specifications.
Technology:
Cost tiers separate vapor-deposited small-molecule systems from solution-processable alternatives, with hybrid architectures emerging at the performance-price intersection.
- Small-Molecule OLED:Vacuum thermal evaporation of organic compounds yields precise layer thickness control and superior efficiency. Taiwan semiconductor fabs specify these for cleanroom photolithography bays where spectral stability affects defect detection rates.
- White OLED:Broadband spectral output without phosphor conversion delivers CRI values exceeding 90 for color-critical quality inspection. Japanese electronics assemblers auto-populate CRI requirements through MES-integrated procurement portals tied to automated optical inspection calibration.
- Polymer OLED:Solution processing enables roll-to-roll manufacturing cost advantages, though efficiency and lifetime metrics trail small-molecule alternatives.
- Hybrid OLED:Combines small-molecule emission layers with polymer charge transport, targeting mid-tier performance at reduced fabrication complexity.
Small-molecule systems command the premium tier; White OLED is climbing fastest on quality inspection specification authority.
Application:
Volume concentration sits with ambient illumination functions, while margin pools concentrate in process-integrated lighting where spectral metrics directly affect output quality.
- Warehouse Lighting:High-bay ambient illumination for storage and retrieval operations, typically specifying 4000K-5000K color temperatures. LED substitution pressure is acute here, with chip-on-board arrays achieving 85+ CRI at lower lumen-dollar cost.
- Precision Equipment Lighting:Task-integrated illumination for CNC machining centers and semiconductor inspection tools. South Korean display panel fabs tie lighting specifications directly to automated optical inspection calibration protocols.
- Factory Floor Illumination:General ambient and task lighting for assembly and material handling zones.
- Quality Inspection Lighting:Spectrally stable panels for visual and automated defect detection systems.
- Cold Storage Lighting:Low-profile installations where thermal management and condensation resistance constrain conventional luminaire options.
Warehouse lighting handles the majority of throughput; precision equipment lighting delivers the steepest margin expansion trajectory.
End User:
Customer type determines whether procurement prioritizes installed cost or process-integrated performance metrics, with specification authority migrating toward production engineering functions.
- Manufacturing Plants:General industrial facilities spanning discrete and process manufacturing, balancing energy efficiency mandates against capital budget constraints.
- Automotive Suppliers:Tier-1 and Tier-2 component manufacturers with stringent quality protocols and EU Green Deal compliance timelines. German suppliers anchor demand for high-uniformity panels in factory floor retrofits targeting 2030 carbon reduction targets.
- Electronics Assemblers:SMT and final assembly operations where ESD-sensitive environments and automated inspection drive spectral precision requirements. Japanese assemblers now issue purchase orders through MES-integrated portals that auto-populate CRI and CCT from work order data.
- Aerospace Production:Cleanroom and precision assembly environments with extreme reliability and traceability requirements.
- Food Processing Units:Hygienic design requirements and cold storage integration create specialized form factor demands.
Manufacturing plants handle the majority of throughput; electronics assemblers are expanding fastest on MES-integrated procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented fabrication clusters in South Korea and China supply the majority of industrial OLED panels, while import-dependent markets in Germany and the United States drive specification standards through regulatory procurement mandates.
South Korea
Pangyo and Paju industrial zones concentrate deposition equipment, emitter chemistry, and driver IC fabrication within 50-kilometer radii. SAMR-equivalent Korean regulators enforce flicker metrics that favor DC-driven OLED architectures for industrial applications. LG Display leverages Gen-8.5 OLED capacity to dominate industrial panel supply from Gumi and Paju facilities.
China
Domestic display fabs in Beijing and Chengdu expand industrial lighting panel output to serve warehouse retrofit demand. GB standards enforced by SAMR mandate flicker metrics that disadvantage PWM-modulated alternatives. BOE Technology anchors production from Hefei and Beijing facilities targeting cold storage and quality inspection segments.
Germany
Automotive suppliers in Stuttgart and Munich retrofit factory floors with OLED task lighting to meet EU Green Deal 2030 carbon reduction targets. REACH restrictions on hazardous substances constrain phosphorescent emitter chemistries imported from Asian suppliers. Bavarian industrial zones concentrate specification authority for high-uniformity panels in precision manufacturing.
United States
Warehouse operators in Illinois and Texas specify OLED ambient illumination for high-bay retrofit projects. EPA energy efficiency standards and OSHA workplace illumination requirements shape product certification pathways for domestic procurement. Midwest manufacturing corridors drive demand for spectral-stable panels in automated inspection environments.
Japan
Electronics assemblers in Osaka and Nagoya issue purchase orders through MES-integrated procurement portals that auto-populate CRI and CCT requirements. METI industrial efficiency programs incentivize solid-state lighting upgrades in precision manufacturing. Kansai region fabs tie lighting specifications directly to automated optical inspection calibration protocols.
Industrial OLED Lighting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in deposition equipment and emitter chemistry. The vendor base concentrates among Korean and Chinese panel makers with state-backed credit access, plus European and Japanese specialists in precision lighting applications. Three archetypes dominate: capital-heavy display incumbents with Gen-8.5 fabrication scale; mid-tier flexible substrate specialists serving retrofit verticals; and precision lighting engineers targeting quality inspection specifications. Capacity expansion and strategic partnerships with automotive suppliers constitute the dominant competitive moves.
Among Korean display fabricators, LG Display and Samsung Display exemplify the capital-concentrated archetype with established Gen-8.5 evaporation capacity. OLEDWorks occupies a position within the precision-tier specialist segment, representing small-batch, high-uniformity panel production for equipment-integrated lighting. These three anchors illustrate the competitive divergence between scale-driven platform supply and specification-driven niche engineering.
| Leading Market Players |
|---|
| LG Display |
| Samsung Display |
| BOE Technology |
| Visionox |
| Signify |
| ams OSRAM |
| Acuity Brands |
| Konica Minolta |
| OLEDWorks |
| Others |
Pricing and Supply Chain Analysis
Canon Tokki and Sunic System's 90% grip on Gen-8.5 evaporation equipment concentrates upstream leverage in Japanese and Korean toolmakers, anchoring margin pools downstream with panel makers who secured long-term tool allocation slots. This equipment oligopoly transmits cost rigidities through emitter chemistry and driver IC tiers, compressing negotiation room for mid-tier assemblers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by CRI certification tiers and volume scale commitments. Price erosion runs through warehouse lighting specifications where chip-on-board LED alternatives achieve comparable color rendering at lower lumen-dollar cost. Automotive suppliers exhibit lowest price sensitivity, prioritizing spectral uniformity for EU Green Deal compliance over installed cost.
Supply Chain Analysis
BOE Technology and LG Display hold captive Gen-8.5 foundry capacity across China and South Korea, with substrate glass and iridium-based phosphorescent emitters drawing from Japanese and German chemical suppliers. Single-source vulnerability concentrates in Canon Tokki's evaporator allocation queue, creating 18-24 month equipment lead time exposure. Distribution runs through direct panel procurement contracts with automotive Tier-1s and electronics assemblers, bypassing traditional lighting distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
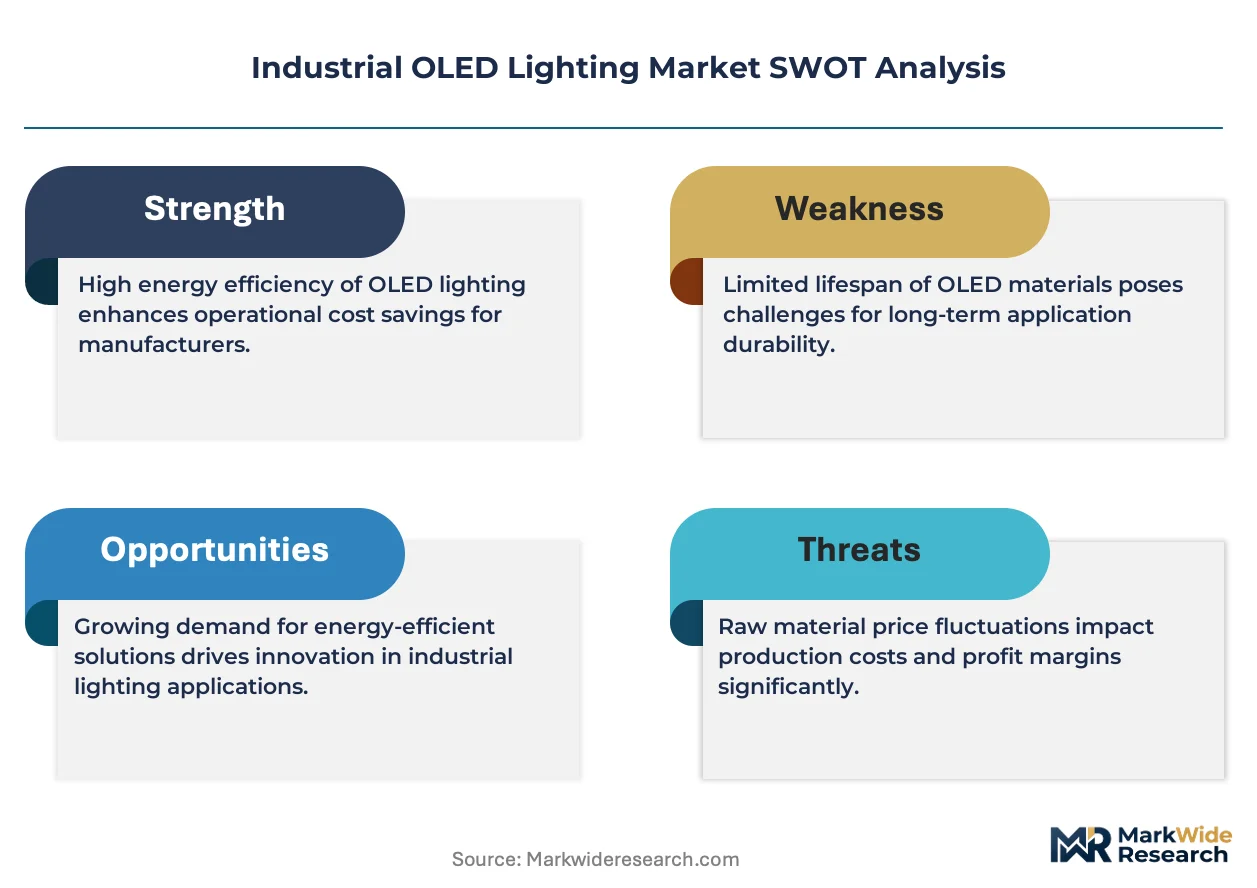
Thin-film encapsulation expertise represents the binding constraint on new fab yield ramps, with fewer than 200 production-grade engineers globally. This capability scarcity privileges incumbents who locked talent through multi-year employment contracts and university pipeline partnerships.
For Market Incumbents: Build captive emitter synthesis capabilities to insulate against REACH authorization volatility for iridium complexes. LG Display and Samsung Display should expand Gen-8.5 capacity in Paju and Tangjeong to preempt Chinese challengers from securing deposition tool slots. Backward integration into phosphorescent precursor chemistry reduces exposure to thin spot market pricing. For New Entrants and Emerging Players: Establish a beachhead in cold storage retrofit specifications where flexible substrate form factors exclude incumbent rigid-panel suppliers. Target South Korean and Netherlands vertical farming operators piloting tunable-spectrum OLED for photomorphogenic control. Partner with Siemens or Dassault on digital twin integration to bypass direct panel manufacturing scale requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across tandem OLED architectures with charge generation layers, favoring specialists over display generalists. Acquisition targets should exhibit in-house thin-film encapsulation expertise and automotive supplier qualification status. Watch for Canon Tokki equipment allocation announcements as inflection signals for Korean versus Chinese capacity expansion trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emitter Synthesis | Secures non-iridium feedstock alternatives ahead of ECHA 2024 substance evaluation timelines. |
| Digital Twin Platform Integration | Links OLED spectral controls to Siemens NX quality inspection algorithms for semiconductor fabs. |
| Flexible Substrate Capacity Expansion | Captures cold storage retrofit demand where condensation risks exclude conventional luminaires. |
| Automotive Supplier Partnership | Locks in factory floor retrofit volumes under EU Green Deal 2030 carbon reduction mandates. |
| Thin-Film Encapsulation Talent Acquisition | Addresses yield ramp constraints with fewer than 200 production-grade engineers globally available. |
Research Methodology
A standing panel of OLED fab operations directors, automotive Tier-1 procurement leads, cold storage facility engineers, and semiconductor cleanroom managers provided ongoing calibration across primary fieldwork. Secondary validation drew from EPA energy efficiency filings, ECHA REACH substance evaluations, SAMR GB standard publications, and SEC 10-K disclosures from display panel manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed volume and value outputs across substrate type, emitter chemistry, installation environment, and end-user procurement authority dimensions. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion patterns. Forecast inputs incorporated EU Green Deal implementation pace, Canon Tokki equipment delivery schedules, and iridium complex spot market volatility indices.
Sensitivities concentrate around ECHA authorization timelines for phosphorescent emitters and Canon Tokki capacity allocation decisions. Forecasts reflect documented assumptions regarding automotive supplier retrofit commitment durability and LED substitution pressure in warehouse segments. Cross-checking against IEA industrial efficiency investment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Digital Light Processing Technology Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Gesture Control Light Market
Lighting
GCC Smart Lighting Market
Lighting
Art and Museum Lighting Market
Lighting
Xenon Lights Market
Lighting
Connected Lighting Platform Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Europe Decorative Lighting Market
Lighting
Ultraviolet Lamps Market
Lighting
Lamps and Lighting Market
Lighting
Battery Operated Lights Market
Lighting
Global Machine Vision Lighting Market
Lighting
Street Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
Specialty Lighting Market