
 Europe Lighting Control Systems Market | 2026-2036
Europe Lighting Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lighting Control Systems Market Foresight
Energy performance certification upgrades are bifurcating the competitive landscape between premium-tier and specification-grade suppliers. Signify Holding B.V. leverages its Philips Hue ecosystem to dominate residential wireless segments across the Netherlands and Belgium. Helvar specializes in DALI-2 wired architectures that anchor its position in Nordic commercial retrofit projects. Legrand controls distribution channels through its Bticino brand, extending its reach into Italian hospitality installations.
Europe lighting control systems encompass networked hardware and software that modulate artificial illumination through protocols such as DALI, KNX, Zigbee, and BACnet, typically operating within 0-10V or digital signal ranges to achieve lumen output adjustment, occupancy responsiveness, and daylight harvesting. These systems serve commercial and industrial facilities seeking to reduce operational expenditure while maintaining compliance with workplace illumination directives. Wireless technology leads volume deployment in residential and small commercial settings where cabling costs prove prohibitive, while wired solutions retain margin concentration in large-scale industrial and integrated building management contracts. Smart technology represents the fastest-expanding category, though analog installations persist in price-sensitive retrofit applications across Southern Europe.
The EU Green Deal and its Energy Performance of Buildings Directive (EPBD) recast mandate systematic lighting upgrades, with ECHA REACH restrictions on hazardous substances further constraining component material selection for manufacturers. CE marking under the Low Voltage Directive and EMC Directive governs product market access, while the F-Gas Regulation indirectly shapes cooling-load calculations that influence lighting heat-output specifications in integrated HVAC-lighting designs. Stakeholders must monitor the EU AI Act's emerging classification framework for autonomous building systems, as algorithmic lighting control may trigger compliance obligations that reshape R&D allocation between European and non-European development centers.
Market Dynamics
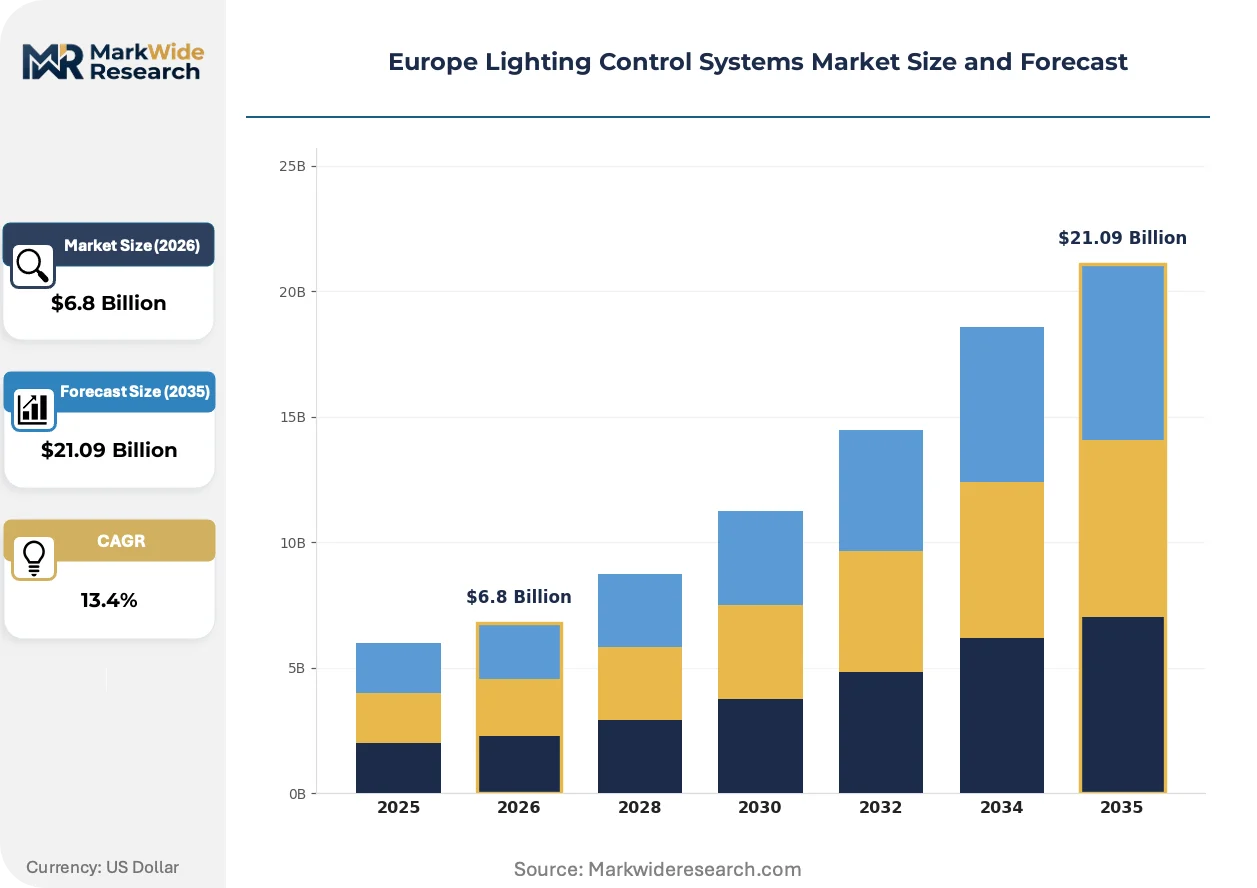
The EU Green Deal's Energy Performance of Buildings Directive is forcing commercial property owners across Germany, France, and Italy into accelerated lighting retrofit cycles, compressing payback-period expectations and fragmenting procurement authority between facility managers and sustainability officers.
Growth Catalysts
- EPBD Recast Mandates:Systematic lighting upgrades in non-residential buildings above threshold sizes create recurring retrofit demand across France and Germany.
- Smart Technology Convergence:DALI-2 and wireless Zigbee protocols enable unified control architectures that reduce commissioning complexity in Nordic commercial projects.
- Hospitality Sector Modernization:Historic hotel properties in Paris and Rome replace analog dimming systems to meet guest experience and energy audit requirements simultaneously.
Market Restraints
- Copper and Semiconductor Input Volatility:Wiring harnesses and microcontrollers face price instability that compresses margin on specification-grade DALI installations.
- REACH Compliance Burden:ECHA restrictions on hazardous substances in electronics extend component qualification timelines and limit supplier pools for PCB assemblies.
- Legacy Analog Persistence:0-10V systems in Southern European price-sensitive retrofits delay full digital adoption and fragment protocol standardization.
Strategic Opportunities
- Polish Industrial Warehouse Expansion:New logistics construction near Warsaw and Krakow presents untapped demand for integrated daylight harvesting and occupancy-responsive systems.
- EU AI Act Classification:Algorithmic lighting control systems may trigger compliance frameworks that reward early algorithm transparency investments by vendors.
- KNX-BACnet Convergence:Building management system integration creates specification advantages for vendors offering unified HVAC-lighting control platforms.
Industry Challenges
- DALI-2 Commissioning Expertise Gap:Certified system integrators remain concentrated in Germany and the Netherlands, constraining deployment velocity in peripheral markets.
- CE Marking Timeline Compression:EMC Directive and Low Voltage Directive testing backlogs delay product launches during peak construction seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lighting Control Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimmers, Sensors, Switches, Controllers Technology: Wireless, Wired, Smart, Analog End User: Residential, Commercial, Industrial, Hospitality Installation Type: New, Retrofit, Integrated, Standalone |
| Companies Covered | Signify Holding B.V., Helvar, Legrand, Honeywell International Inc., Lutron Electronics Co., Inc., Eaton Corporation PLC, ams-OSRAM AG, Schneider Electric SE, Zumtobel Group AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lighting Control Systems Market Shifts & Advancements
Wireless mesh architectures and embedded sensor fusion are collapsing the traditional separation between lighting control and broader building automation, redrawing competitive boundaries around data platform ownership rather than hardware shipment volumes.
DALI-2 is decomposing the monolithic lighting control stack into interoperable sub-components—drivers, sensors, and controllers from different vendors now certify against common device type specifications. Large German commercial contractors are specifying multi-vendor DALI-2 ecosystems to reduce single-source dependency. This modularity is compressing margin capture for integrated system providers while expanding addressable market for specialized sensor and driver manufacturers.
The EU AI Act's risk classification framework for autonomous building systems is forcing vendors to document algorithmic decision logic for lighting control sequences that adjust based on occupancy patterns. Manufacturers serving Dutch and Belgian smart building markets are restructuring R&D teams to maintain technical documentation trails. High-complexity installations in airport and healthcare verticals face the steepest compliance preparation requirements.
Facility managers in France's hospitality sector are unbundling lighting control procurement from electrical contractor relationships, establishing direct vendor contracts for software updates and sensor calibration services. This disintermediation shifts margin from installation toward recurring service revenue. Paris-based hotel chains are piloting subscription-based control platform access that includes predictive maintenance and energy reporting dashboards.
Europe Lighting Control Systems Market Segmentation
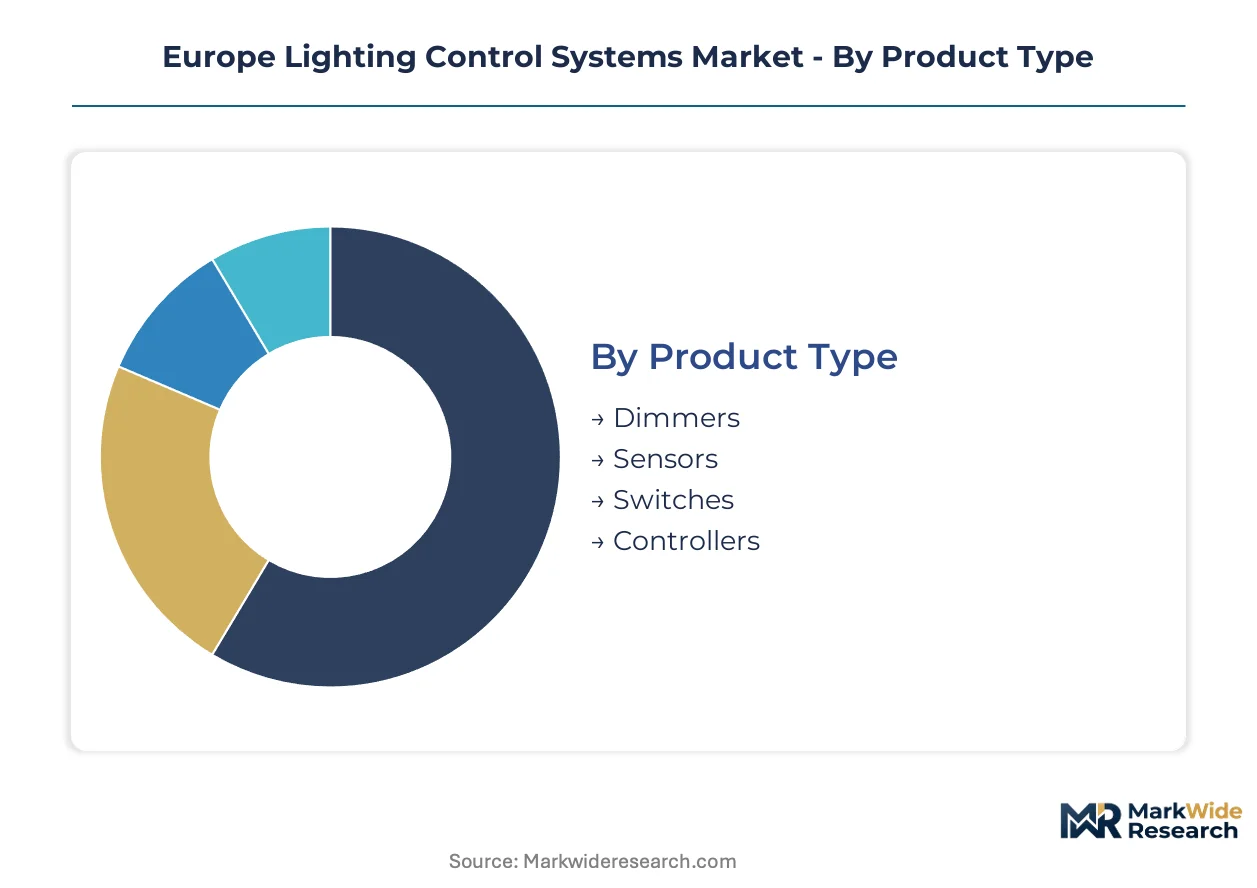
Lighting control procurement patterns diverge sharply across building vintages and regulatory exposure. Segment boundaries determine whether vendors compete on commissioning speed, protocol interoperability, or recurring software revenue.
Product Type:
Dimmers and sensors flow disproportionately into export-led German and Dutch specification channels, while switches and controllers concentrate in domestic French and Italian retrofit markets.
- Dimmers:These units modulate lumen output through phase-cut or 0-10V signal adjustment. Demand clusters in Paris and Milan hospitality retrofits where guest room ambiance controls must integrate with legacy electrical infrastructure.
- Sensors:Occupancy and daylight harvesting devices embed PIR, ultrasonic, or photocell elements with DALI-2 or wireless backends. German commercial contractors specify multi-vendor sensor ecosystems to reduce single-source dependency in large-scale office refurbishments.
- Switches:Wall-mounted control interfaces span mechanical, electronic, and touch-sensitive variants. Italian residential markets favor Bticino-branded designs through established electrical distribution channels.
- Controllers:Centralized processing units aggregate sensor inputs and execute lighting sequences. Nordic industrial facilities deploy these for daylight harvesting coordination across expansive warehouse footprints.
Dimmers command the established base. The steepest expansion runs through sensors.
Technology:
Cost tier stratification separates premium smart architectures from specification-grade wired systems, with wireless and analog occupying mid-market and economy positions respectively.
- Wireless:Zigbee and proprietary mesh protocols eliminate cabling costs in residential and small commercial settings. Netherlands and Belgium residential markets show concentrated uptake through Philips Hue ecosystem dominance.
- Wired:DALI-2 and KNX architectures deliver deterministic control for large-scale commercial and industrial contracts. German facility managers specify these for EPBD compliance in buildings above regulatory threshold sizes.
- Smart:Embedded sensor fusion and cloud-connected analytics platforms collapse boundaries between lighting control and building automation. French hospitality operators pilot subscription-based platform access with predictive maintenance inclusions.
- Analog:0-10V and phase-cut dimming persists in Southern European price-sensitive retrofits where digital upgrade budgets remain constrained.
Wired technology anchors the revenue base. Smart platforms are climbing the fastest.
End User:
Application maturity varies by sector compliance pressure, with commercial and hospitality facing steepest regulatory mandates while residential and industrial follow discretionary upgrade cycles.
- Commercial:Office, retail, and institutional buildings above EPBD threshold sizes drive systematic retrofit demand. German property owners compress payback-period expectations to meet EU Green Deal building performance standards.
- Hospitality:Historic hotel properties in Paris and Rome replace analog dimming systems to satisfy simultaneous guest experience and energy audit requirements.
- Residential:Wireless smart lighting adoption concentrates in Netherlands and Belgium through consumer-facing ecosystem brands.
- Industrial:Warehouse and manufacturing facilities prioritize daylight harvesting and occupancy-responsive controls. Polish logistics construction near Warsaw and Krakow presents untapped integrated system demand.
Commercial installations command the established base. Hospitality verticals show the steepest expansion trajectory.
Installation Type:
Customer type segmentation reveals procurement authority fragmentation, with integrated and standalone decisions increasingly separating from traditional electrical contractor relationships.
- New:Greenfield construction enables native DALI-2 and smart protocol deployment without legacy compatibility constraints. Nordic commercial projects specify multi-vendor ecosystems during initial commissioning.
- Retrofit:Existing building upgrades dominate volume across Germany, France, and Italy as EPBD recast mandates accelerate replacement cycles.
- Integrated:Unified HVAC-lighting control platforms through KNX-BACnet convergence serve large German commercial contractors seeking specification advantages.
- Standalone:Single-function lighting controls without building management system linkage persist in small commercial and residential applications where integration complexity proves prohibitive.
Retrofit installations command the established base. Integrated systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southern Europe prioritize cost containment above protocol sophistication, while Nordic and German facility managers absorb premium pricing for deterministic control architectures that satisfy regulatory audit trails.
Germany
Commercial property owners compress lighting retrofit payback periods to meet EU Green Deal building performance standards. The EPBD recast mandates systematic upgrades in non-residential buildings above threshold sizes. Berlin and Frankfurt facility managers specify DALI-2 wired architectures from certified system integrators concentrated in North Rhine-Westphalia.
France
Historic hotel properties in Paris replace analog dimming systems to satisfy simultaneous guest experience and energy audit requirements. The EU Green Deal's building performance standards accelerate procurement cycles. Île-de-France hospitality operators unbundle lighting control from electrical contractors, establishing direct vendor contracts for software maintenance.
Netherlands
Residential wireless adoption concentrates through consumer-facing ecosystem brands with established retail distribution. CE marking under the Low Voltage Directive governs product market access. Eindhoven-region technology clusters anchor Philips Hue ecosystem development and Zigbee protocol refinement for smart home integration.
Italy
Bticino-branded switches dominate residential retrofit markets through entrenched electrical distribution channels. ECHA REACH restrictions on hazardous substances constrain component material selection for PCB assemblies. Milan hospitality properties balance guest room ambiance controls with legacy electrical infrastructure compatibility.
Poland
New logistics construction near Warsaw and Krakow presents demand for integrated daylight harvesting and occupancy-responsive systems. F-Gas Regulation indirectly shapes cooling-load calculations that influence lighting heat-output specifications. Industrial warehouse developers specify KNX-BACnet converged platforms for unified HVAC-lighting control.
Europe Lighting Control Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium-tier suppliers compete on protocol interoperability while specification-grade vendors compete on commissioning speed. The vendor base fragments across wireless ecosystem providers, DALI-2 wired specialists, and integrated building management platform vendors. Two dominant competitive moves define current positioning: M&A activity consolidating sensor and driver manufacturing capabilities, and strategic partnerships between lighting control vendors and HVAC system integrators pursuing KNX-BACnet convergence.
Among European-headquartered specialists, Signify Holding B.V., Helvar, and Legrand occupy distinct archetype positions. Signify exemplifies the wireless ecosystem model with consumer-facing platform dominance in residential segments. Helvar represents the DALI-2 wired specialist archetype anchoring Nordic commercial retrofit specifications. Legrand sits within the integrated electrical distribution tier, extending control channel reach through established contractor relationships.
| Leading Market Players |
|---|
| Signify Holding B.V. |
| Helvar |
| Legrand |
| Honeywell International Inc. |
| Lutron Electronics Co., Inc. |
| Eaton Corporation PLC |
| ams-OSRAM AG |
| Schneider Electric SE |
| Zumtobel Group AG |
| Others |
Supply & Pricing Matrix
Copper-to-aluminum conductor substitution in DALI-2 wiring harnesses simultaneously redraws supplier geography toward Eastern European cable producers and compresses per-meter material costs for specification-grade installations across German commercial retrofits.
Pricing Analysis
Software maintenance and sensor calibration subscriptions now drive lifetime value capture, displacing upfront hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked DALI-2 ecosystems from uncertified wireless mesh alternatives from specification-grade 0-10V analog bundles. Cost compression in economy tiers is intensifying because REACH compliance extends component qualification timelines. Southern European retrofit contractors exhibit the steepest price sensitivity, while Nordic facility managers absorb premium pricing for deterministic control architectures.
Supply Chain Analysis
Extended lead times for DALI-2 certified microcontrollers and Zigbee radio modules signal inventory strain across tier-one distributors. Manufacturing concentrates in Germany, the Netherlands, and China, with PCB assembly drawing from Taiwanese semiconductor foundries and Belgian sensor fabrication facilities. Copper price volatility and ECHA REACH restrictions on flame-retardant compounds constitute the dominant supply chain risk. Distribution runs through established electrical wholesale channels in Italy and France, alongside direct vendor contracts emerging in hospitality verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock facility managers into DALI-2 ecosystems once commissioning is complete, creating durable revenue streams for incumbent protocol specialists.
For Market Incumbents: Consolidate sensor and driver manufacturing capabilities through targeted acquisition of specialized component vendors, particularly those holding DALI-2 device type certifications. Expand certified system integrator networks into Poland and Southern Europe to preempt emerging competitors. Channel control through direct hospitality contracts in Paris and Milan offsets margin compression from multi-vendor specification trends.
For New Entrants and Emerging Players: Anchor in Polish industrial warehouse construction near Warsaw and Krakow, where integrated daylight harvesting demand outpaces local DALI-2 expertise availability. Target specification-grade wireless mesh architectures for price-sensitive Southern European retrofits where cabling costs prove prohibitive. Pursue partnership routes with HVAC system integrators pursuing KNX-BACnet convergence rather than direct electrical contractor channels.
For Investors and Strategic Acquirers: The EU AI Act's risk classification framework reshapes the acquisition landscape by rewarding vendors with documented algorithmic transparency trails. Five-to-ten-year viability favors platform-integrated specialists over pure hardware manufacturers. Target acquisition archetypes include embedded sensor fusion developers serving Dutch smart building markets. Monitor CE marking testing backlog durations as an inflection indicator for product launch velocity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| DALI-2 Certification Investment | CE marking compliance unlocks German commercial retrofit contracts above EPBD threshold sizes. |
| Wireless Mesh Platform Launch | Zigbee ecosystem expansion captures Netherlands and Belgium residential volume through retail distribution. |
| Sensor-Driver Acquisition | Vertical integration of multi-vendor component capabilities reduces single-source dependency in Nordic specifications. |
| KNX-BACnet Partnership | HVAC-lighting convergence creates specification advantages with large German commercial contractors. |
| Subscription Service Rollout | Predictive maintenance contracts in French hospitality shift margin from installation toward recurring revenue. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lighting control system integrators, facility managers at German commercial properties, French hospitality procurement officers, and Dutch electrical distributors; and secondary validation through EU EPBD regulatory filings, ECHA REACH substance restriction updates, CE marking directive documentation, and customs trade data for copper and semiconductor imports. Bottom-up installation volume estimates triangulated against top-down spending forecasts from building retrofit expenditure surveys.
Across the projection horizon, the analytical framework modeled segmentation across technology type, end-use vertical, installation vintage, and protocol architecture. CAGRs derived from regression analysis of historical retrofit cycle acceleration and regulatory mandate compliance deadlines. Forecast inputs incorporated EU Green Deal building performance standard enforcement timelines and DALI-2 device certification velocity.
Decision-makers should treat outputs as directional under assumptions of sustained EPBD recast enforcement and stable copper pricing; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Smart Lamp Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
Illuminating Signs Market
Lighting
Solar Spotlights Market
Lighting
US Indoor LED Lighting Market
Lighting
Human Centric Lighting Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
Solid State Lighting System Market
Lighting
Display Light Control Film Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
High Bay Lighting Market
Lighting
Smart Street Lighting Systems Market
Lighting
Intelligent Lighting Market
Lighting
Smart Lighting Market
Lighting
Explosion Proof Lighting Market