
 Xenon Flashlamps Market | 2026-2036
Xenon Flashlamps Market Size, Share, and Industry Trends Forecast 2026-2036
Xenon Flashlamps Market Insights
ISO 13485 certification for medical device component suppliers is redrawing competitive access in the xenon flashlamp sector. Excelitas Technologies Corp. leverages its vertically integrated quartz-to-lamp manufacturing to sustain FDA-registered production lines. Hamamatsu Photonics anchors Japanese supply for scientific instrumentation with proprietary electrode designs. Heraeus Noblelight GmbH dominates European medical OEM channels through CE-marked lamp assemblies.
Xenon flashlamps are gas-discharge devices that produce intense broadband optical pulses through electrical excitation of xenon gas contained in fused silica envelopes, with typical pulse durations from microseconds to milliseconds and spectral outputs spanning ultraviolet through near-infrared wavelengths. Medical imaging applications command the largest revenue pool due to stringent replacement cycles in fluoroscopy and endoscopy systems, while phototherapy segments register the fastest expansion as dermatology clinics adopt narrowband UVB protocols. High-power flashlamps capture premium margins from industrial laser pumping and semiconductor inspection equipment where arc stability determines yield.
FDA 510(k) premarket notification requirements and the EU MDR's renewed clinical evidence standards constrain market entry for non-certified lamp architectures. Japan's PMDA enforces parallel quality system inspections that extend approval timelines for imported optical sources. Stakeholders must monitor evolving RoHS exemptions for mercury-free alternatives and position supply chains for dual-certification regimes before regulatory divergence hardens procurement specifications.
Market Dynamics
ISO 13485 certification requirements and FDA 510(k) premarket pathways are restructuring supplier access, forcing lamp manufacturers to absorb compliance costs or exit medical OEM channels entirely.
Growth Catalysts
- EU MDR clinical evidence mandates:Replacement demand accelerates as hospitals refresh fluoroscopy systems to meet renewed CE-marking standards for optical components.
- Dermatology clinic expansion:Narrowband UVB phototherapy protocols drive narrow spectral lamp procurement across outpatient dermatology networks.
- Fused silica envelope advances:Improved thermal shock resistance extends operational lifecycles in high-pulse industrial laser pumping applications.
Market Restraints
- Xenon gas supply concentration:Extraction and refining capacity clusters in Russia and Ukraine, exposing lamp manufacturers to geopolitical input volatility.
- LED substitution in low-power segments:Solid-state alternatives capture cost-sensitive signaling and strobe applications below 50 joules per pulse.
- Japan PMDA inspection timelines:Parallel quality system audits extend approval cycles for imported optical sources by 12-18 months.
Strategic Opportunities
- Semiconductor inspection equipment:EUV lithography precursor systems demand arc-stable flashlamps for wafer defect detection at sub-7nm nodes.
- RoHS mercury exemption positioning:Lamp suppliers can capture mercury-free alternative mandates as RoHS exemptions expire for legacy discharge sources.
- India medical device PLI scheme:Local assembly incentives attract component suppliers to serve domestic imaging OEMs and reduce import dependency.
Industry Challenges
- Electrode fabrication expertise:Precision tungsten doping and emitter coating processes require skilled technicians with decades of gas-discharge lamp experience.
- Dual-certification capex burden:Parallel FDA and EU MDR compliance requires redundant testing facilities and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xenon Flashlamps Market |
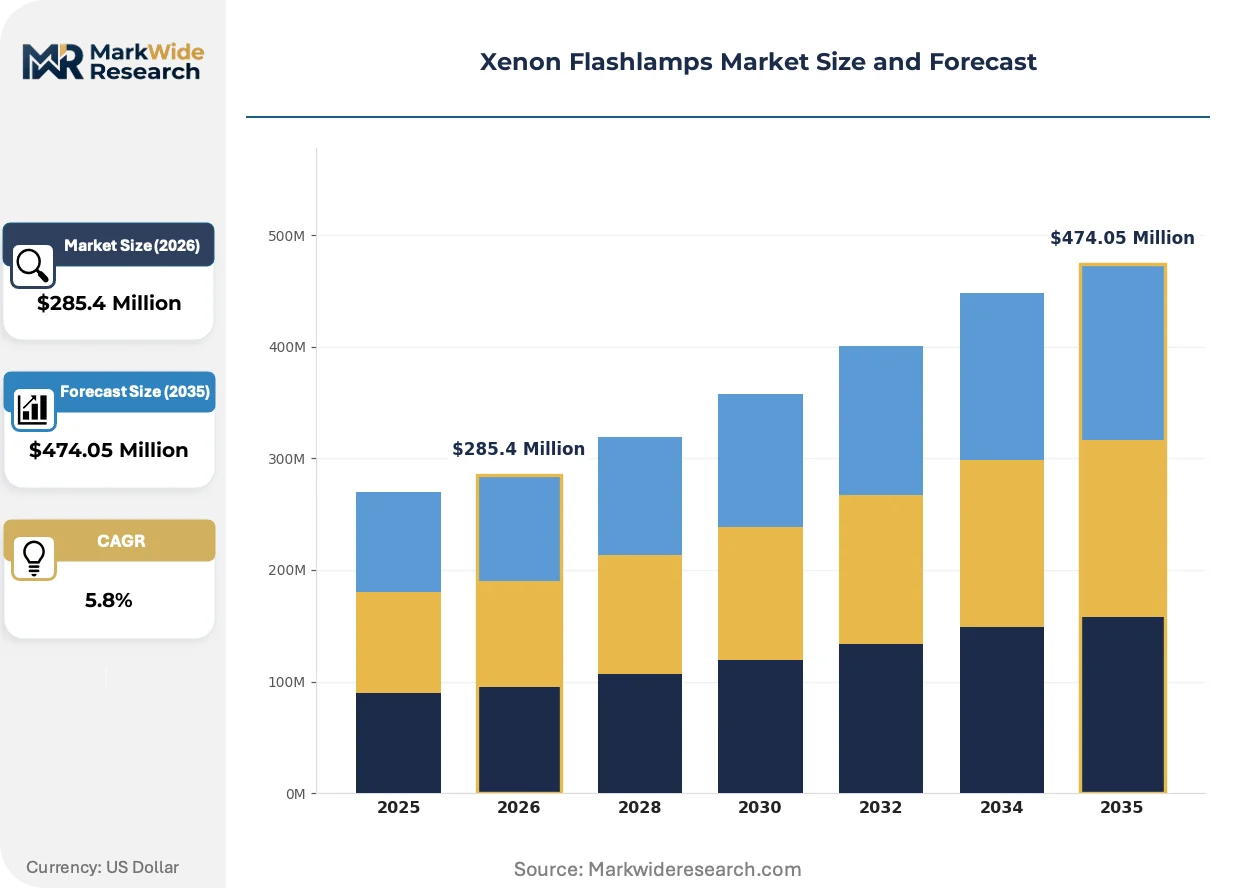
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Flashlamps, High-Power Flashlamps, High-Efficiency Flashlamps, Xenon Short-Arc Lamps Application: Medical Imaging, Phototherapy, Industrial Applications, Scientific Research End User: Hospitals, Research Institutions, Manufacturing Units, Photography Studios Technology: Gas Discharge, Pulsed Laser, Thermal Source, Others |
| Companies Covered | Excelitas Technologies Corp., Hamamatsu Photonics, PerkinElmer Inc., Heraeus Noblelight GmbH, Ushio America Inc., Amglo Kemlite Laboratories Inc., Xenon Corporation, Sarspec LDA, Sugawara Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xenon Flashlamps Market Trends and Innovations
Three forces are compressing product lifecycles and reshaping competitive access: solid-state substitution at the low end, regulatory harmonization failures at the high end, and procurement consolidation among hospital networks.
Ceramic metal halide pre-ionization sources are supplanting traditional trigger transformers in high-repetition-rate flashlamp systems. Semiconductor inspection OEMs in Germany and Japan adopt these compact ignition modules to achieve microsecond jitter stability. The shift is compressing margins for legacy transformer suppliers while enabling lamp architectures with faster warm-up cycles.
REACH substance restrictions on tungsten halide byproducts are forcing electrode chemistry revisions across European manufacturing facilities. Lamp producers must reformulate emitter coatings or relocate final assembly outside EU jurisdiction. Medical device OEMs in Germany face the steepest compliance costs as they cannot easily shift CE-marked supply chains.
Hospital procurement consortia now bundle flashlamp replacement contracts with full imaging system service agreements. Independent lamp distributors lose direct access to radiology departments as OEMs capture aftermarket revenue through captive service subsidiaries. The pattern is most pronounced in United States health networks where vertical integration of maintenance contracts has accelerated since 2022.
Xenon Flashlamps Market Segmentation
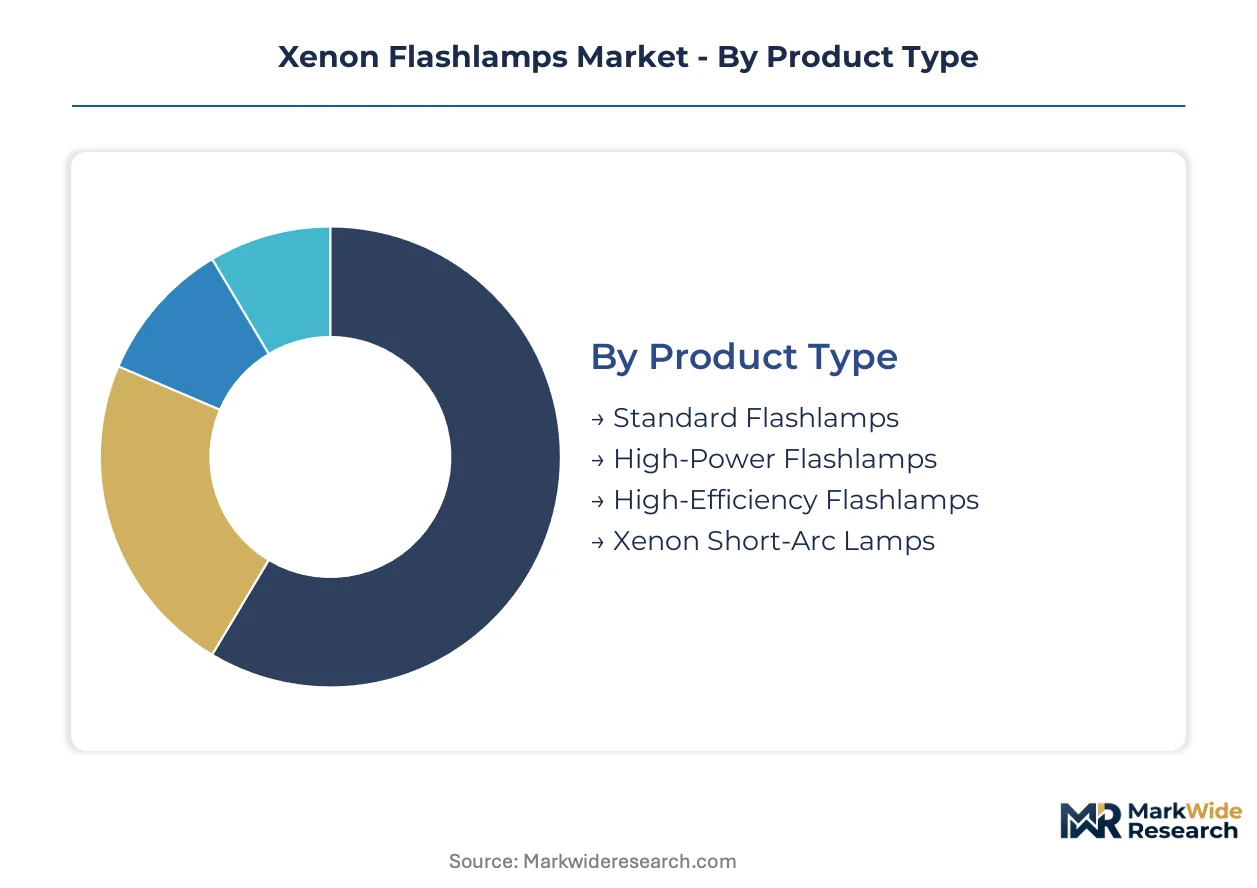
Xenon flashlamp manufacturers configure product portfolios around pulse energy thresholds and envelope geometries that determine which regulatory pathways and replacement cycles apply. Segmentation choices directly dictate certification investments and channel access across medical, industrial, and scientific verticals.
Product Type:
Premium margins concentrate in high-power architectures where thermal management and arc stability justify specialized electrode engineering and fused silica sourcing.
- Standard Flashlamps:Pulse energies below 500 joules with borosilicate or standard fused silica envelopes serve cost-sensitive signaling and strobe applications. Procurement concentrates in photography studios and legacy industrial inspection systems where LED substitution pressure is strongest.
- High-Power Flashlamps:Kilojoule-class pulse outputs with engineered thermal shock resistance dominate semiconductor wafer inspection and dermatological surgical equipment. German and Japanese OEMs specify these for EUV lithography precursor systems where arc jitter tolerance falls below 100 nanoseconds.
- High-Efficiency Flashlamps:Optimized electrode geometries and gas fill pressures reduce energy consumption per pulse for battery-powered portable devices.
- Xenon Short-Arc Lamps:Continuous-wave operation with compact arc gaps serves cinema projection and solar simulation chambers.
The dominant share belongs to Standard Flashlamps, while High-Power Flashlamps is closing the gap fastest.
Application:
End-use concentration follows regulatory burden intensity, with medical channels commanding the steepest compliance premiums and longest contract durations.
- Medical Imaging:Fluoroscopy and endoscopy systems require pulse-to-pulse stability for diagnostic image consistency. Replacement cycles tighten as FDA 510(k) and EU MDR standards force hospital networks to refresh optical subsystems on accelerated timelines.
- Phototherapy:Narrowband UVB protocols for psoriasis and vitiligo treatment demand precise spectral filtering at 311 nanometers. Outpatient dermatology clinics in Germany and the United States drive procurement as narrowband systems displace broadband UV alternatives.
- Industrial Applications:Laser pumping and materials processing rely on high-repetition-rate architectures.
- Scientific Research:Spectroscopy and pump-probe experiments require broadband spectral outputs with microsecond timing precision.
Medical Imaging captures the largest revenue pool, though Phototherapy is expanding most quickly as clinic networks proliferate.
End User:
Customer type determines whether procurement flows through OEM captive service subsidiaries or independent distribution channels.
- Hospitals:Consolidated health networks in the United States bundle flashlamp replacement contracts with full imaging system service agreements. Vertical integration of maintenance contracts has accelerated since 2022, squeezing independent lamp distributors out of radiology department access.
- Research Institutions:University and national laboratory procurement operates on grant-funded cycles with extended qualification timelines.
- Manufacturing Units:Semiconductor fabs and industrial laser operators prioritize uptime guarantees over unit cost.
- Photography Studios:Price-sensitive buyers in creative services face persistent LED substitution pressure below 50 joules per pulse.
Hospitals dominate procurement volume, while Manufacturing Units are gaining share fastest on semiconductor inspection equipment demand.
Technology:
Technology selection determines which ignition architectures and regulatory exemptions apply, with gas discharge retaining medical certification advantages.
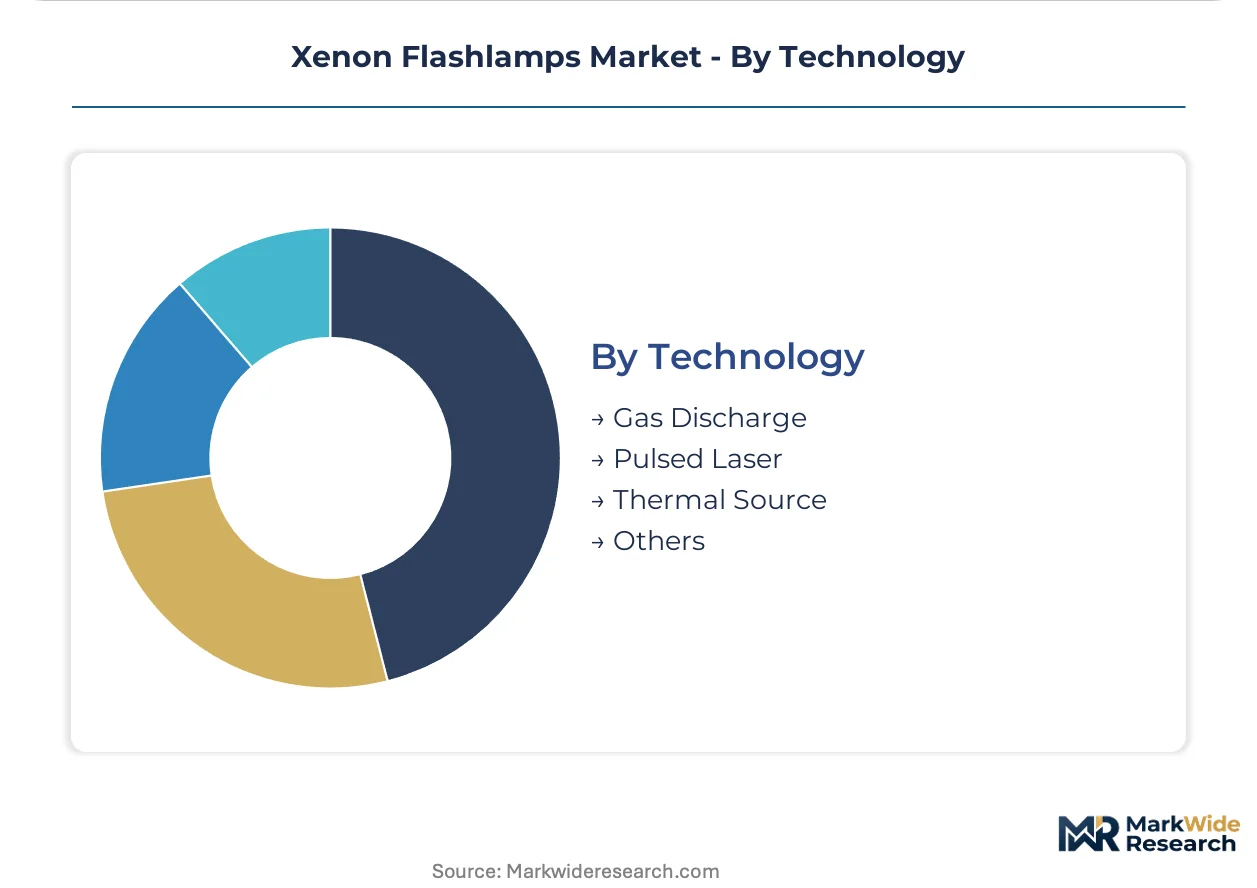
- Gas Discharge:Electrical excitation of xenon gas in sealed envelopes produces broadband optical pulses from ultraviolet through near-infrared. FDA-registered production lines and ISO 13485 certification requirements favor this mature architecture for medical device integration.
- Pulsed Laser:Solid-state and fiber laser alternatives compete in high-precision materials processing.
- Thermal Source:Incandescent and halogen technologies persist in low-cost applications.
- Others:Emerging LED and laser diode architectures capture segments where spectral purity outweighs broadband requirements.
Gas Discharge holds the installed base majority, though Pulsed Laser is climbing the fastest in industrial precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is attracting component suppliers to establish local assembly operations. Germany's EU MDR enforcement accelerates replacement demand in fluoroscopy systems. Japan's PMDA inspection timelines create procurement bottlenecks for imported optical sources.
United States
Hospital procurement consortia bundle flashlamp replacement contracts with imaging system service agreements. FDA 510(k) premarket notification requirements constrain market entry for non-certified lamp architectures. Precision photonics manufacturing clusters in Massachusetts and California serve regulated medical device supply chains with vertically integrated production.
Germany
REACH substance restrictions on tungsten halide byproducts force electrode chemistry revisions across manufacturing facilities. EU MDR clinical evidence mandates accelerate hospital refresh cycles for fluoroscopy optical subsystems. Baden-Württemberg's precision engineering corridor hosts CE-marked lamp assembly operations for European medical OEM channels.
Japan
Semiconductor inspection OEMs adopt ceramic metal halide pre-ionization sources for microsecond jitter stability. METI coordinates domestic supply chain resilience initiatives for critical photonics components. Hamamatsu anchors scientific instrumentation demand with proprietary electrode designs manufactured in Shizuoka Prefecture.
India
Domestic imaging OEMs reduce import dependency through localized component sourcing under medical device PLI incentives. CDSCO quality system requirements align with ISO 13485 standards for component suppliers. Karnataka's Bengaluru-Tumkur corridor attracts lamp assembly investments to serve South Asian dermatology clinic networks.
China
NMPA medical device registration reforms streamline approval pathways for imported optical subsystems. MIIT industrial policy prioritizes domestic photonics capabilities for semiconductor inspection equipment. Yangtze River Delta manufacturing hubs integrate xenon flashlamp production with laser pumping system supply chains.
Xenon Flashlamps Market Competitive Landscape
Listed leaders compete with private specialists across certification-intensive medical channels, creating a tiered structure where regulatory access separates premium-tier suppliers from commodity-positioned competitors. Three archetypes dominate: vertically integrated quartz-to-lamp manufacturers, specialized electrode engineering houses, and regional assembly operations serving cost-sensitive segments. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms absorb dual-certification capex burdens.
Within the vertically integrated tier, Excelitas Technologies Corp. and Heraeus Noblelight GmbH exemplify archetypes of regulatory-compliant production, while Hamamatsu Photonics occupies a position among specialized scientific instrumentation suppliers. These three entities represent distinct geographic anchors—North American, European, and Japanese respectively—each sitting within certification regimes that determine competitive access to medical OEM procurement channels.
| Leading Market Players |
|---|
| Excelitas Technologies Corp. |
| Hamamatsu Photonics |
| PerkinElmer Inc. |
| Heraeus Noblelight GmbH |
| Ushio America Inc. |
| Amglo Kemlite Laboratories Inc. |
| Xenon Corporation |
| Sarspec LDA |
| Sugawara Laboratories Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Russian and Ukrainian xenon extraction facilities anchors global price floors for high-power flashlamp manufacturers. Scale concentration in these upstream gas sources compresses margins for mid-tier lamp assemblers while granting premium pricing power to vertically integrated quartz-to-lamp producers with captive supply arrangements.
Pricing Analysis
Certification level (ISO 13485/FDA-registered/CE-marked) creates the primary spread between premium and commodity tiers. Three-tier pricing structure across medical-grade, industrial-grade, and standard signaling applications reflects differential compliance burdens. Cost compression in standard flashlamp tiers is intensifying because LED substitution erodes volume scale for borosilicate envelope producers. Photography studios and legacy industrial buyers exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for sub-100 nanosecond arc stability guarantees.
Supply Chain Analysis
Strategic stockpiling of xenon gas reserves dominates inventory strategy among Japanese and German OEMs facing PMDA and EU MDR inspection bottlenecks. Raw material sourcing draws from Russia, Ukraine, and South Africa for xenon extraction; fused silica envelope fabrication concentrates in Germany, Japan, and the United States. Single-source vulnerability in Eastern European gas refining exposes lamp manufacturers to geopolitical supply interruptions. Distribution runs through OEM captive service subsidiaries for hospital networks, with independent distributors retaining access only in research and photography segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Xenon flashlamp demand sits in early-cycle expansion as dermatology clinic networks proliferate narrowband UVB phototherapy protocols across outpatient settings. Penetration headroom remains substantial in India and Southeast Asia where localized assembly incentives attract component suppliers.
For Market Incumbents: Compound certification investments across dual FDA-EU MDR pathways to lock out non-compliant competitors from hospital procurement consortia. Deepen backward integration into fused silica envelope production to offset electrode chemistry revision costs from REACH tungsten halide restrictions. Prioritize capacity addition in Karnataka and Baden-Württemberg to serve regionalized medical OEM supply chains. For New Entrants and Emerging Players: Lead with semiconductor inspection equipment as the most penetrable vertical, where ceramic metal halide pre-ionization source adoption creates supplier churn opportunities. Target India's PLI-supported medical device corridor for local assembly partnerships that bypass 12-18 month PMDA import timelines. Position through direct engagement with independent dermatology clinic networks outside consolidated hospital procurement systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrode engineering specialists with proprietary emitter coating IP over commodity lamp assemblers. Five-to-ten year viability hinges on mercury-free alternative positioning as RoHS exemptions expire for legacy discharge sources. Watch EU MDR enforcement intensity in German hospital networks as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Parallel FDA 510(k) and EU MDR pathways secure access to premium hospital procurement channels in Germany and the United States. |
| Backward Integration into Fused Silica | Captive quartz envelope production insulates margin pressure from REACH substance restrictions on European manufacturing. |
| Ceramic Pre-Ionization Module Development | Microsecond jitter stability specifications from Japanese semiconductor OEMs drive adoption away from legacy trigger transformers. |
| India PLI Localization | Karnataka assembly operations reduce import dependency for domestic imaging OEMs serving South Asian dermatology networks. |
| Mercury-Free Alternative Positioning | RoHS exemption expiration timelines create procurement mandates for xenon architectures in regulated medical device segments. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and dermatology clinic procurement leads and refined through secondary validation. Primary fieldwork combined structured interviews with flashlamp OEM technical directors and aftermarket service heads. Secondary sources encompassed FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and semiconductor equipment capex disclosures. Bottom-up unit demand estimates and top-down market sizing were triangulated to reconcile volume projections.
Variance decomposition across product type, application vertical, end-user category, and geographic regulatory cluster informed the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included replacement cycle compression from EU MDR clinical evidence mandates, LED substitution thresholds in sub-50 joule segments, and xenon gas supply concentration risk premiums.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and Japan PMDA regimes; material policy shifts would require re-modeling approval timeline assumptions and biocompatibility testing burdens. Revision becomes warranted when xenon gas supply disruptions or REACH substance restriction expansions cross thresholds that alter input cost structures or manufacturing location economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Lighting Fixture Market
Lighting
OLED Lightening Panels Market
Lighting
Photocell Market
Lighting
Wireless Lighting Market
Lighting
Digital Light Processing Technology Market
Lighting
Residential Lighting Fixtures Market
Lighting
Dimmers Market
Lighting
UV Lamps Market
Lighting
High-End Lighting Market
Lighting
LED Solar Lighting Market
Lighting
Global Work Lights Market
Lighting
Flexible Lighting Foils Market
Lighting
Solar Rope Light Market
Lighting
Battery Operated Lights Market
Lighting
Solid State Lighting System Market
Lighting
North America Smart Lighting Market