
 Lighting As a Service (Laas) Market | 2026-2036
Lighting As a Service (Laas) Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting As a Service (Laas) Market Intelligence
The integration of IoT and cloud-based platforms by traditional luminaire manufacturers in Europe and North America is realigning the competitive landscape. Signify N.V. leverages its extensive portfolio of connected lighting systems to secure large municipal contracts. General Electric Company competes by offering comprehensive energy solutions that bundle LaaS with other building management services. Osram Licht AG specializes in advanced sensor technology integrated within its lighting fixtures, differentiating on performance analytics.
Lighting As a Service (LaaS) is a business model where customers pay for lighting as a service rather than purchasing and owning the lighting equipment outright. The service typically includes design, installation, ongoing maintenance, and guaranteed light levels, often specified in lux, for a fixed subscription term. Within service models, contract-based and managed service agreements dominate the commercial and industrial end-user segments. The adoption of IoT and cloud-based technologies is a key differentiator, enabling features like remote monitoring and predictive maintenance.
Regulatory frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) and China's dual carbon goals compel corporations to adopt energy-efficient solutions like LaaS. In the United States, programs such as the EPA's ENERGY STAR certification for buildings create incentives for upgrading lighting systems under service models. Stakeholder success will hinge on navigating the complex interplay between evolving hardware technology, software platform capabilities, and client-specific service level agreements.
Market Dynamics
The convergence of stringent energy efficiency regulations and the maturation of IoT platforms is the central force shaping the market. This dynamic transforms lighting from a capital asset into a data-driven utility service, aligning operational costs with sustainability goals.
Growth Catalysts
- EU Green Deal:A strong regulatory push for building energy efficiency under frameworks like the EU Green Deal compels commercial real estate owners to adopt performance-based lighting solutions to meet mandates.
- Smart City Initiatives:Demand is concentrating within large-scale smart city projects in the United States, Singapore, and the UAE, which prioritize connected infrastructure and operational efficiency for public spaces.
- IoT and Cloud Integration:The fusion of IoT sensors and cloud-based analytics platforms enables advanced features like predictive maintenance and space utilization monitoring, enhancing the service value proposition.
Market Restraints
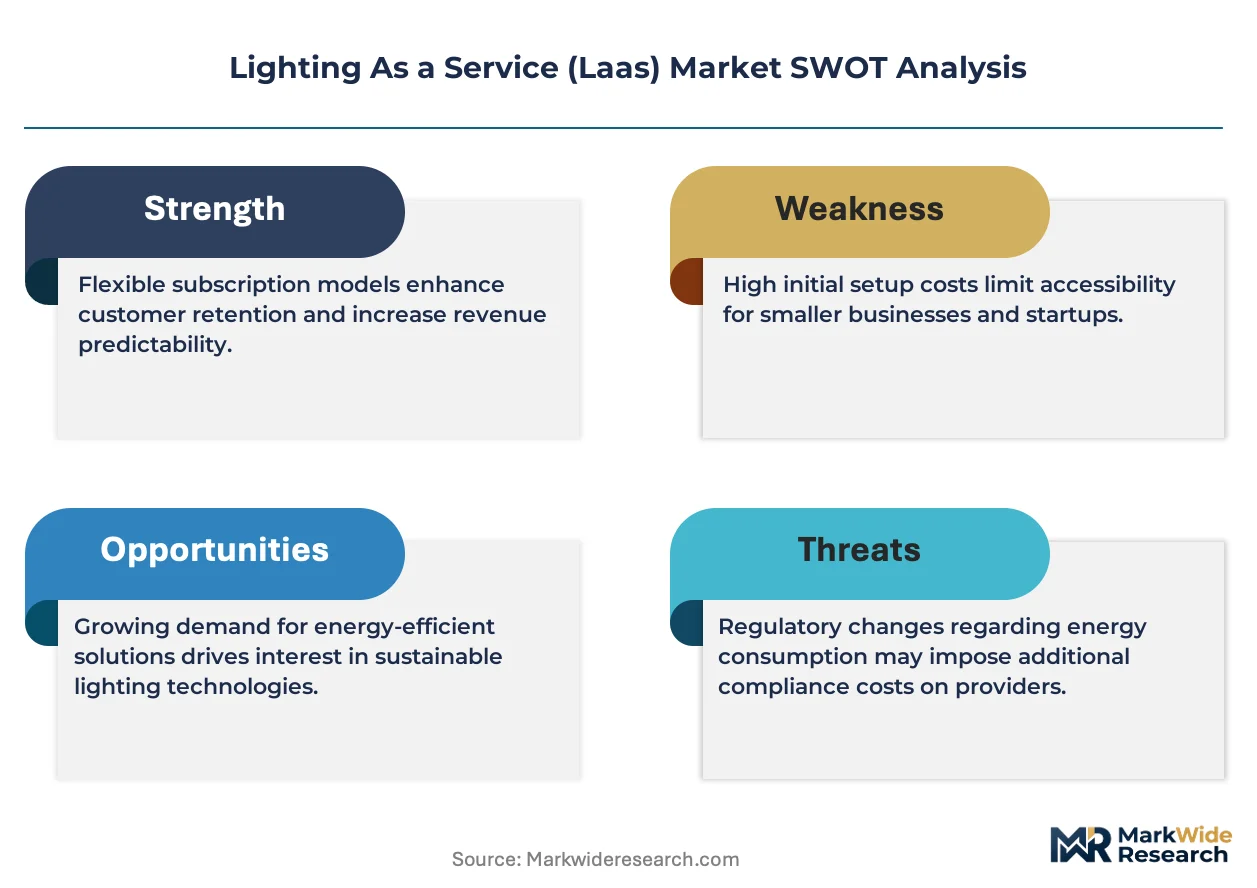
- High Provider Capex:Service providers face significant upfront capital investment for advanced LED luminaires, sensors, and control systems, which can be a barrier to entry for smaller firms.
- Data Security Concerns:The collection of occupancy and operational data via connected lighting systems raises client concerns regarding data privacy and the cybersecurity of building networks.
- CapEx Model Inertia:A persistent preference for traditional capital expenditure purchasing and asset ownership, particularly among small and medium-sized enterprises, slows subscription model adoption.
Strategic Opportunities
- Building Management Integration:Bundling LaaS with other building services like HVAC and security controls offers a path to creating a unified, data-driven smart building management platform for clients.
- Industrial Sector Penetration:There is significant white space for tailored LaaS solutions in the industrial sector, including manufacturing facilities and logistics centers in markets such as India and Brazil.
- Human-Centric Lighting Services:Developing specialized service packages focused on human-centric lighting to improve productivity and well-being in corporate offices presents a high-value, differentiated opportunity.
Industry Challenges
- Specialized Skill Gaps:A shortage of technicians with dual expertise in electrical lighting installation and IT network management complicates deployment and ongoing service delivery for providers.
- Interoperability Standards:The absence of universal communication protocols between different manufacturers' IoT platforms creates significant integration challenges for clients with mixed-vendor environments.
- SLA Complexity:Structuring and enforcing long-term service level agreements that guarantee specific performance metrics, such as lux levels and system uptime, is operationally complex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting As a Service (Laas) Market |
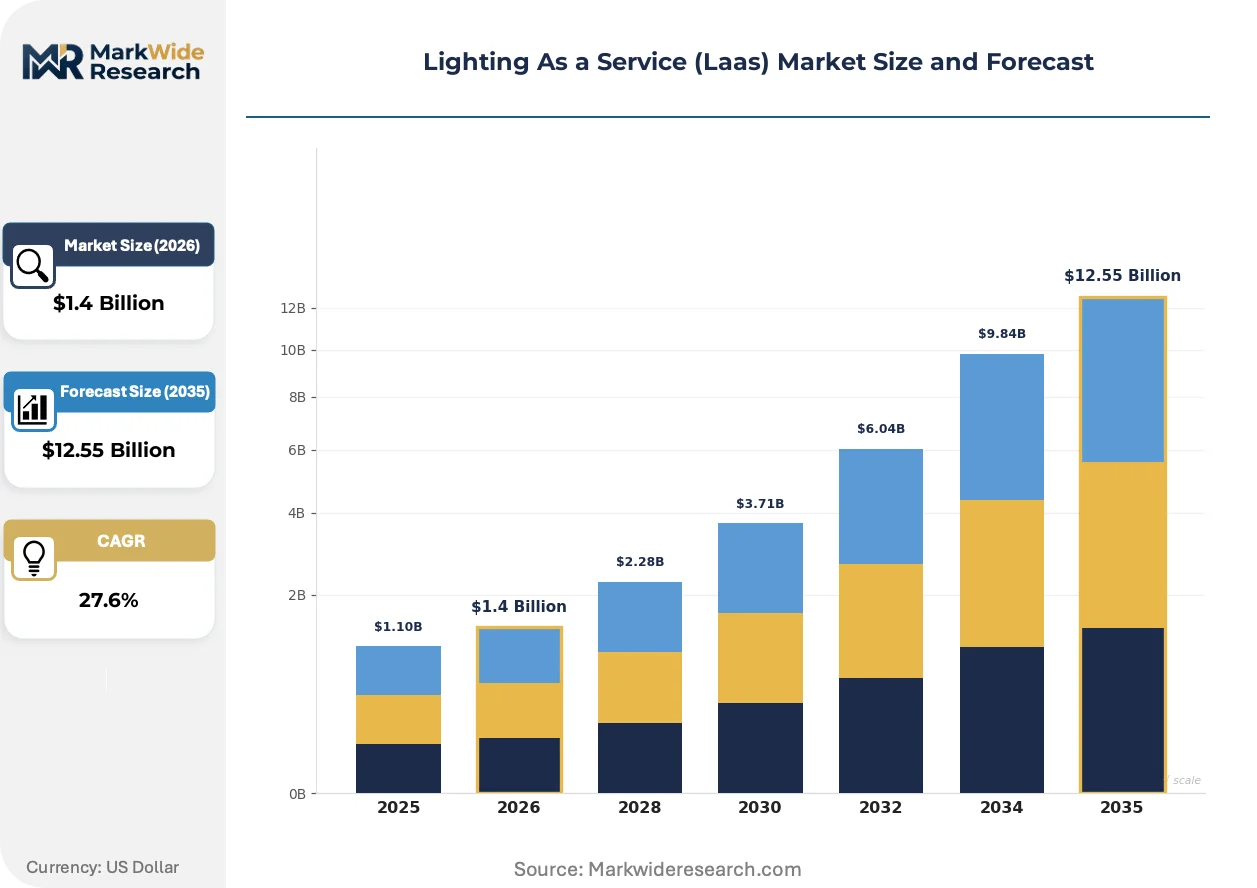
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 27.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Smart Lighting, Traditional Lighting, Solar Lighting Service Model: Subscription, Pay-Per-Use, Contract-Based, Managed Service End User: Commercial, Industrial, Residential, Government Technology: IoT, Wireless, Cloud-Based, Automation |
| Companies Covered | Signify N.V., Koninklijke Philips N.V., General Electric Company, Eaton Corporation, Lutron Electronics Co., Digital Lumens, Osram Licht AG, Cree Inc., RCG Lighthouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting As a Service (Laas) Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from selling physical luminaires to delivering guaranteed lighting outcomes. This shift is enabled by software, data analytics, and new service-oriented business models that prioritize performance and efficiency over hardware ownership.
Integration of advanced sensors for occupancy, daylight harvesting, and environmental monitoring is a core product evolution. Commercial office buildings and large-scale retail spaces are the primary adopters of these intelligent fixtures. This fusion of sensing and lighting hardware is electrifying the value proposition, transforming luminaires into data-gathering nodes for optimizing building operations.
Regulatory frameworks like China's dual carbon goals compel large industrial entities to pursue aggressive energy reduction targets. This policy directly encourages adopting LaaS as an operational expense to meet sustainability mandates without large capital outlays. The manufacturing sector is responding by initiating large-scale lighting retrofits under service agreements.
A behavioral shift toward OpEx-based consumption for building systems is underway among corporate clients. This supplants the traditional capital purchase of lighting equipment with long-term, managed service contracts that include maintenance. This pattern is most pronounced in multinational corporations aiming to standardize facility costs and technology across their global property portfolios.
Lighting As a Service (Laas) Market Segmentation
Understanding the diverse segments within the Lighting As a Service market reveals how providers tailor solutions to specific client needs. This segmentation highlights varied approaches to technology adoption and service delivery across different end-user environments. Analyzing these distinctions clarifies where value creation and competitive differentiation are most pronounced.
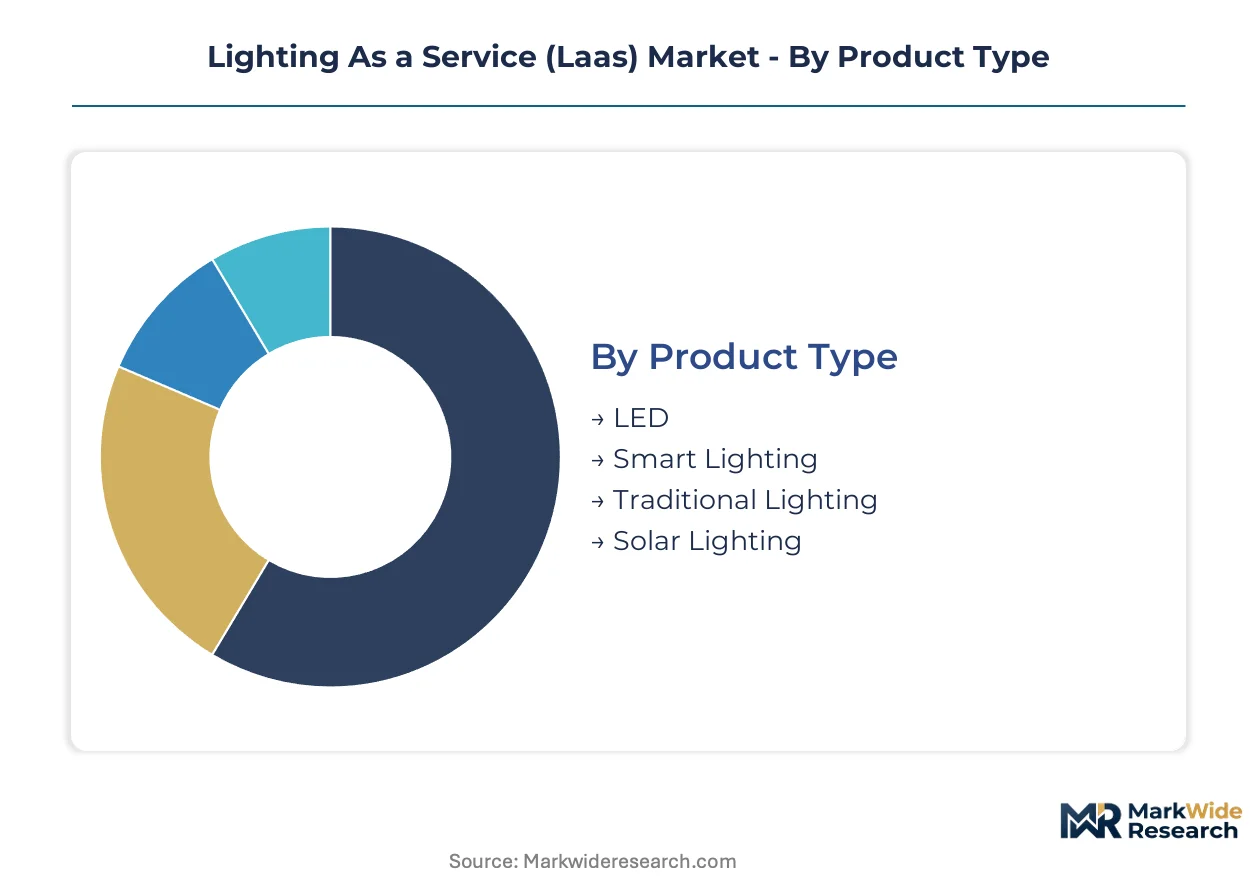
Product Type:
Supply concentration within the Lighting As a Service market primarily centers on the advanced product types, which offer superior energy efficiency and integration capabilities.
- LED:Light Emitting Diodes (LEDs) form the foundational technology for modern LaaS offerings, providing high energy efficiency and long operational lifespans. Demand for LED solutions concentrates in commercial office buildings, driven by stringent energy efficiency mandates like those under the EU Green Deal.
- Smart Lighting:Smart lighting systems integrate sensors, controls, and connectivity to enable dynamic adjustments and data collection. Large-scale smart city initiatives in the United States and Singapore are driving adoption, aiming for enhanced public safety and operational efficiency.
- Traditional Lighting:Traditional lighting, including fluorescent and incandescent options, still exists but is rapidly being displaced by more efficient alternatives.
- Solar Lighting:Solar lighting solutions leverage photovoltaic panels for energy independence, finding niches in off-grid or remote installations.
LED technology absorbs the bulk of installed capacity; Smart Lighting is expanding most quickly.
Service Model:
The choice of service model within LaaS directly reflects the client's operational expenditure preferences and risk appetite.
- Subscription:Subscription models involve regular, fixed payments for lighting services, bundling equipment, maintenance, and performance guarantees. Commercial clients, particularly multinational corporations, favor this model for predictable budgeting and standardized global deployments.
- Managed Service:Managed service agreements provide comprehensive oversight of a client's lighting infrastructure, including proactive maintenance and system upgrades. Industrial facilities in Germany and the United States adopt this for ensuring continuous, high-performance operations without internal resource strain.
- Pay-Per-Use:Pay-Per-Use models charge clients based on actual lighting consumption or operational hours, offering flexibility.
- Contract-Based:Contract-Based agreements define specific terms and service levels over a fixed period, common in large infrastructure projects.
The Subscription model dominates commercial engagements, while Managed Service agreements are gaining significant traction in industrial settings.
End User:
Application-specific requirements significantly influence the design and delivery of LaaS solutions across different end-user environments.
- Commercial:The commercial segment includes office buildings, retail spaces, and hospitality venues, prioritizing energy efficiency, aesthetic appeal, and smart building integration. Regulatory frameworks like the EU's Corporate Sustainability Reporting Directive compel commercial real estate owners to adopt LaaS for sustainability reporting.
- Industrial:Industrial end-users, such as manufacturing plants and logistics centers, require robust, high-performance lighting for safety and productivity in challenging environments. China's dual carbon goals accelerate LaaS adoption in this sector for achieving aggressive energy reduction targets.
- Residential:Residential adoption remains nascent, primarily focused on smart home integration and premium lighting experiences.
- Government:Government entities leverage LaaS for public infrastructure, including street lighting and municipal buildings, focusing on cost savings and smart city integration.
Commercial applications command the largest market share, with the Industrial sector showing substantial growth potential.
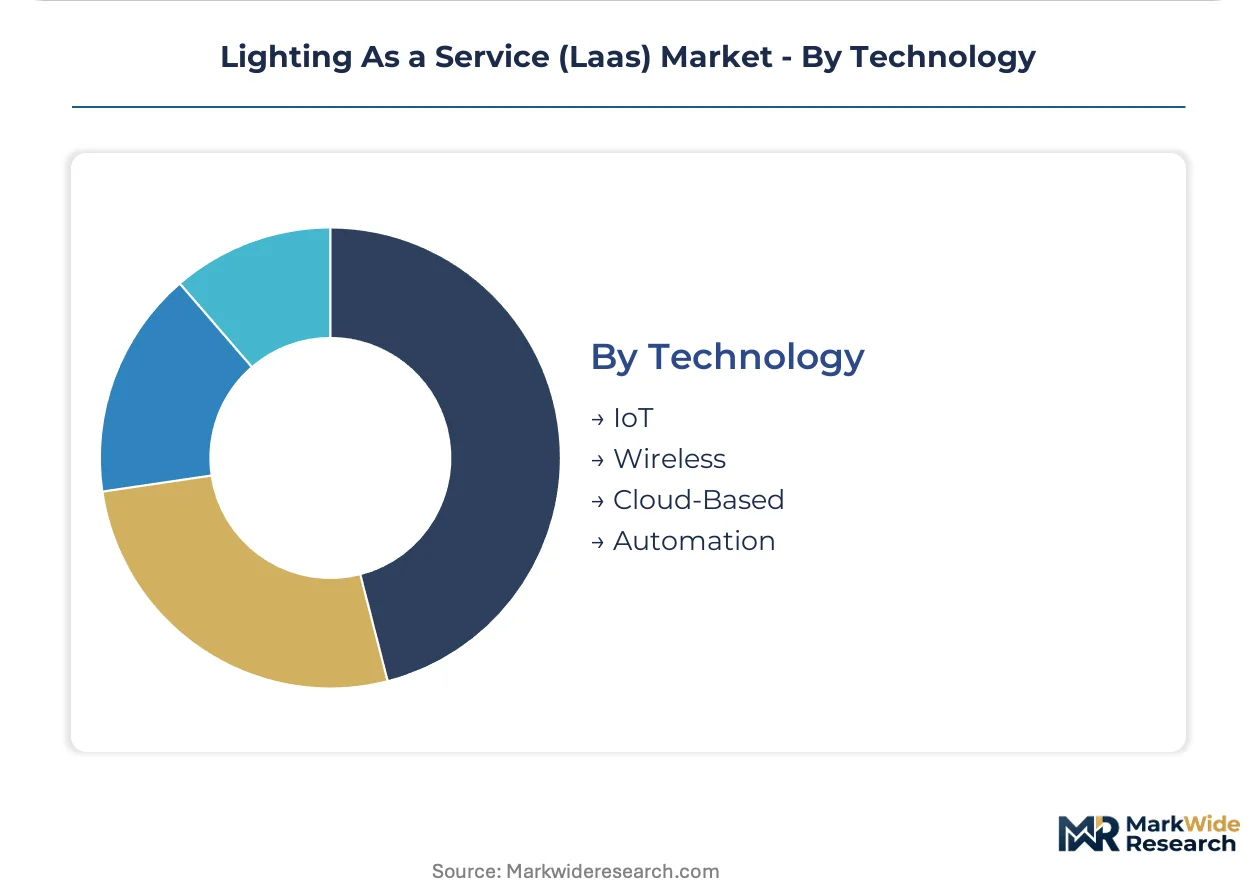
Technology:
The maturity and interoperability of underlying technologies dictate the sophistication and value proposition of LaaS offerings.
- IoT:Internet of Things (IoT) platforms enable connected lighting systems to gather data on occupancy, daylight, and energy consumption, facilitating remote monitoring. Smart city initiatives globally rely on IoT integration for comprehensive urban management and operational efficiency.
- Cloud-Based:Cloud-based platforms provide the computational backbone for LaaS, enabling data analytics, predictive maintenance, and centralized control of lighting networks. Providers like Signify N.V. leverage these platforms for managing extensive municipal contracts and diverse client portfolios.
- Wireless:Wireless technologies, such as Bluetooth and Zigbee, provide flexible and scalable connectivity for lighting networks.
- Automation:Automation in LaaS involves programmed responses to environmental changes or schedules, optimizing energy use without human intervention.
IoT integration is foundational for advanced LaaS features, while cloud-based solutions underpin scalable service delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand for advanced Lighting As a Service solutions, driven by expansive smart city initiatives and commercial real estate upgrades. Regulatory incentives and corporate sustainability targets further accelerate adoption across diverse geographies. This global market exhibits varied growth patterns influenced by regional policies and technological maturity.
United States
Smart city initiatives and commercial building retrofits drive demand for LaaS solutions across the United States. The EPA's ENERGY STAR certification for buildings creates incentives for upgrading lighting systems under service models. Major metropolitan areas like New York City are actively deploying smart infrastructure projects, integrating connected lighting for enhanced urban management.
Germany
Industrial facilities and commercial properties in Germany increasingly adopt LaaS to meet stringent energy efficiency mandates. The EU Green Deal and the Corporate Sustainability Reporting Directive (CSRD) compel businesses to invest in performance-based lighting. Industrial complexes within North Rhine-Westphalia are implementing managed service agreements for continuous high-performance operations.
Singapore
Singapore's ambitious smart nation initiatives heavily influence LaaS adoption, particularly within public infrastructure and urban development. National sustainability plans prioritize energy-efficient solutions for public spaces and commercial buildings. Integrated smart lighting systems are being deployed extensively in areas such as Marina Bay, enhancing both safety and operational efficiency.
China
China's industrial sector undergoes massive LaaS adoption, driven by aggressive energy reduction targets and urban expansion. The country's dual carbon goals accelerate demand for operational expense-based lighting retrofits in manufacturing plants. Major manufacturing hubs in the Yangtze River Delta are seeing significant investments in service-based lighting solutions.
India
India's industrial sector and emerging smart city projects represent substantial growth potential for tailored LaaS solutions. National energy conservation policies and the Smart Cities Mission encourage the deployment of modern lighting infrastructure. Logistics centers and industrial parks around Mumbai and Delhi are increasingly adopting LaaS for improved efficiency and cost management.
Lighting As a Service (Laas) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated smart building management. The market structure is tiered, with traditional luminaire manufacturers evolving their offerings to include service models. Strategic archetypes include hardware-centric providers, comprehensive energy solution integrators, and software-focused analytics specialists. Companies are increasingly engaging in portfolio diversification and technology integration to enhance their market position.
Specialists in connected lighting systems and comprehensive energy solutions include Signify N.V. and General Electric Company. Signify N.V. leverages its extensive portfolio of connected lighting systems, while General Electric Company competes by offering comprehensive energy solutions that bundle LaaS with other building management services. Osram Licht AG, a German-based company, focuses on advanced sensor technology integrated within its lighting fixtures, differentiating on performance analytics.
| Leading Market Players |
|---|
| Signify N.V. |
| Koninklijke Philips N.V. |
| General Electric Company |
| Eaton Corporation |
| Lutron Electronics Co. |
| Digital Lumens |
| Osram Licht AG |
| Cree Inc. |
| RCG Lighthouse |
| Others |
Cost & Logistics Intelligence
Large-scale smart city initiatives in the United States and Singapore concentrate demand, driving contract-based pricing models for Lighting As a Service solutions. These projects often involve long-term agreements that bundle equipment, installation, and ongoing maintenance. The complexity of these deployments influences both pricing structures and supply chain configurations.
Pricing Analysis
Service-level agreement guarantees and bundled maintenance define the core value proposition in LaaS pricing. Contract-based and subscription models dominate commercial engagements, offering predictable operational expenses. Pricing differentiation stems from the level of IoT integration and the comprehensiveness of performance analytics provided. Pricing softness emerges from persistent CapEx model inertia, particularly among small and medium-sized enterprises. Multinational corporations exhibit the lowest price sensitivity due to their focus on global standardization and sustainability reporting, while SMEs remain highly sensitive to upfront costs.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers for advanced sensors and LED drivers, often concentrated in China. Geographic supply concentration for core LED components and advanced sensor modules primarily centers in China, with sophisticated software platforms often originating from the United States and Europe. Raw material dependencies include rare earth elements for LEDs and specialized semiconductors for IoT devices. Geopolitical tensions affecting critical component supply lines pose a significant structural risk. Distribution runs through direct sales channels and specialized system integrators who manage complex project deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lighting As a Service market remains a supply-constrained opportunity, with specialized skill gaps in dual electrical and IT expertise propping up service pricing. This scarcity creates both challenges for providers and opportunities for focused investment.
For Market Incumbents: Lock in long-term municipal and commercial contracts by offering comprehensive smart building management integration. Consolidate market position through strategic acquisitions of software-centric analytics providers, mitigating the threat from emerging pure-play tech firms. Invest heavily in advanced IoT platform development and interoperability standards to maintain a competitive edge. Secure critical component supply chains through multi-year agreements to reduce geopolitical risks.
For New Entrants and Emerging Players: Underserved industrial facilities in India and Brazil present significant white space for tailored LaaS solutions. Target niche applications such as human-centric lighting in corporate offices, differentiating through specialized service packages and performance guarantees. Penetrate the small and medium-sized enterprise segment by simplifying subscription models and emphasizing immediate operational expense savings. Focus on robust, easy-to-deploy IoT solutions with clear return-on-investment metrics.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term growth across a 5-10 year horizon. Target software-focused analytics specialists and system integrators with strong recurring revenue models. These firms often possess critical intellectual property in data interpretation and predictive maintenance. A key signal to watch for inflection is the widespread adoption of universal interoperability standards, which will accelerate market consolidation and platform dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure long-term municipal contracts | Establishes stable revenue streams and large-scale deployment opportunities for providers. |
| Integrate comprehensive building management | Expands service offerings beyond lighting, creating unified smart building platforms for clients. |
| Invest in advanced IoT platform development | Enhances data analytics capabilities and enables superior remote monitoring for LaaS providers. |
| Target industrial sector penetration in India | Captures growth in an underpenetrated market with high energy efficiency needs. |
| Acquire software-centric analytics specialists | Strengthens data interpretation capabilities and competitive positioning for LaaS providers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, providing a robust foundation. The study triangulated this information with primary interviews conducted with lighting engineers, facility managers, smart city planners, and procurement officers. We utilized reports from the EU Green Deal, EPA ENERGY STAR data, company annual reports, and industry journals, ensuring a comprehensive view through bottom-up and top-down validation.
Market granularity was modeled across product type, service model, end-user, technology, and specific regional adoption patterns throughout the analysis window. This framework allowed for detailed segmentation and accurate projection of market dynamics. Compound Annual Growth Rates were derived from an assessment of historical trends, regulatory impacts, and future technological advancements. Key forecast inputs included evolving energy efficiency mandates and smart city investment cycles.
Revisions become necessary when unforeseen technological shifts or significant changes in data privacy regulations materialize, impacting market trajectory. Forecasts inherently reflect a set of assumptions about future conditions and market behavior. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Eye-Illuminating Gadgets Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
LED Solar Lighting Market
Lighting
GCC Smart Lighting Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Xenon Lights Market
Lighting
Hazardous Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
North America Smart Lighting Market
Lighting
Solar Column Headlight Market
Lighting
Plasma Lighting Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Industrial Lighting Market
Lighting
Smart Lamp Market
Lighting
Digital Light Processing Technology Market