
 Delayed Coker Unit Process Technology Market | 2026-2036
Delayed Coker Unit Process Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Delayed Coker Unit Process Technology Market Analytics
API 934-A qualification for coke drum materials is redrawing the competitive landscape for delayed coker unit process technology. Lummus Technology leverages its proprietary LC-FINING integration to sustain engineering leadership in residuum upgrading. Bechtel Corporation anchors large-scale EPC execution across North American refinery retrofits. Technip Energies N.V. competes through modular coker delivery models that compress project schedules.
Delayed coker unit process technology converts heavy residual oil into lighter distillates through thermal cracking in insulated drums operating at approximately 480°C and 15-20 psig, producing petroleum coke as a byproduct. The primary purpose is maximizing liquid yield from bottom-of-the-barrel fractions in complex refineries. Vertical cokers dominate existing installed base due to their structural simplicity and decades of operational history, while modular cokers represent the fastest-growing configuration as refiners prioritize phased capital deployment and reduced construction risk at congested sites. Thermal cracking technology leads in unit count globally, though hydrocracking integration is capturing margin pools where refiners seek deeper conversion and cleaner product slates.
The EPA enforces Maximum Achievable Control Technology standards for coke drum venting and decoking operations, compelling refiners to retrofit emissions control systems or face operating restrictions. OSHA's process safety management requirements govern coke drum switching cycles and unheading procedures, directly influencing automation system demand and training expenditures. Stakeholders must monitor how carbon border adjustments and clean fuel regulations in multiple jurisdictions reshape the economics of high-sulfur coke production against alternative residuum destruction pathways.
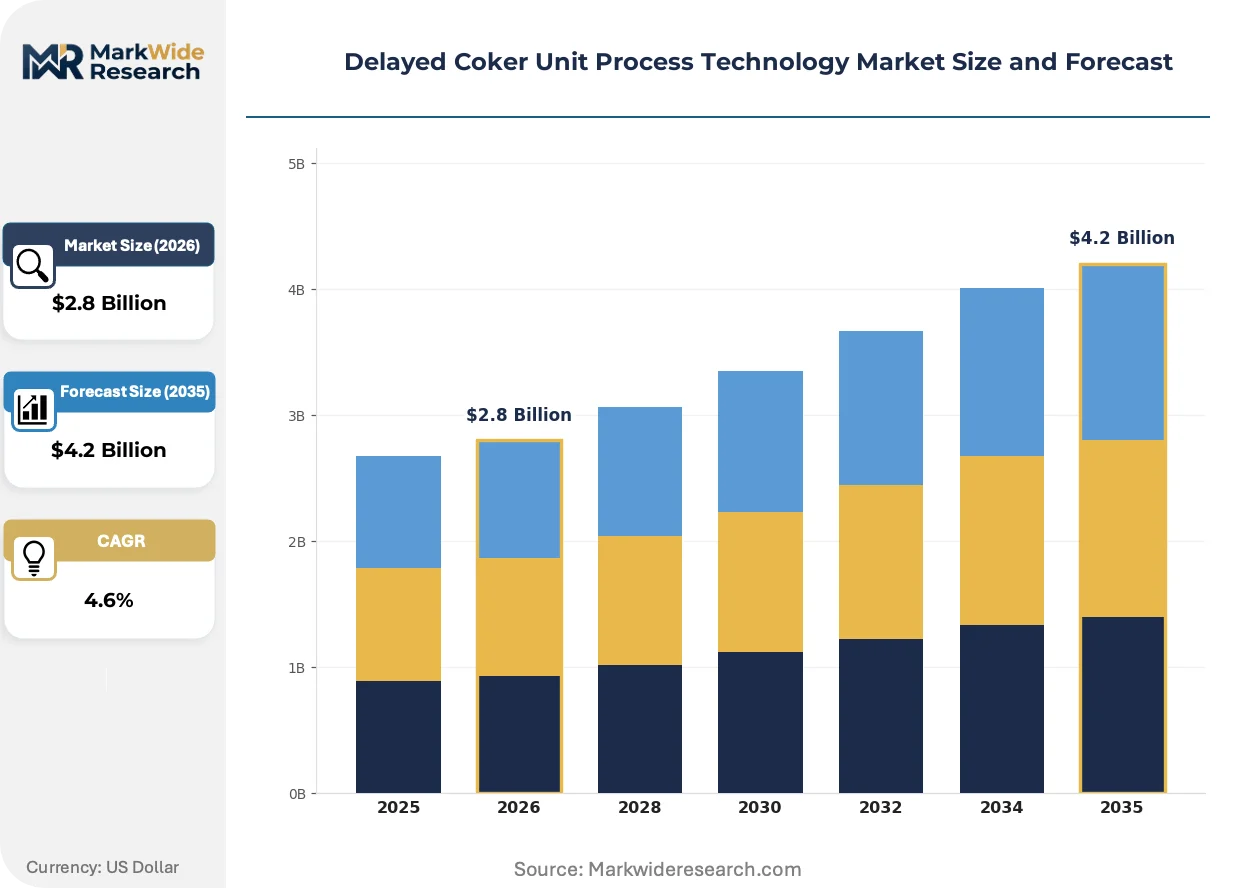
Market Dynamics
API 934-A qualification requirements for coke drum materials are forcing simultaneous metallurgical upgrades across installed bases, compressing equipment replacement cycles while elevating engineering specifications for new unit construction.
Growth Catalysts
- Heavier Crude Processing Mandates:Saudi Aramco and ADNOC residuum upgrading programs are expanding coker capacity to handle denser feedstocks from mature fields. National oil companies in the Middle East are funding downstream integration projects that require thermal cracking capacity.
- Emissions Control Retrofits:EPA Maximum Achievable Control Technology standards for coke drum venting operations compel North American refiners to install closed-loop decoking systems. These mandates sustain replacement demand for legacy units lacking vapor recovery infrastructure.
- Modular Deployment Models:Phased capital deployment at congested refinery sites accelerates adoption of skid-mounted coker configurations. Engineering contractors report compressed project schedules and reduced construction risk as primary adoption drivers.
Market Restraints
- Chromium-Molybdenum Steel Volatility:API 934-A qualified plate and forging supply concentrates among specialty mills in Japan and Germany. Input cost fluctuations for these high-alloy materials compress fabricator margins during project bidding cycles.
- Residuum Destruction Alternatives:Hydrocracking integration and solvent deasphalting technologies capture margin pools where refiners prioritize liquid yield over coke production. These pathways threaten thermal cracking demand in complex refinery configurations.
- Construction Labor Scarcity:Skilled welder availability for field-erected coke drums remains constrained across US Gulf Coast and Rotterdam refining clusters. Project delays from craft labor shortages extend payback periods for capital-intensive upgrades.
Strategic Opportunities
- Digital Twin Integration:Predictive maintenance platforms for coke drum fatigue monitoring converge with distributed control systems from automation vendors. Refinery operators in South Korea and Singapore pilot these converged technologies to optimize switching cycles.
- Low-Carbon Coke Valorization:Carbon border adjustment mechanisms in the EU and forthcoming clean fuel regulations create premium pricing tiers for anode-grade coke production. Coker operators with calcining integration capture these regulatory tailwinds.
- India Downstream Expansion:Reliance Industries and Indian Oil Corporation residuum upgrading projects at Jamnagar and Paradip represent underpenetrated demand for large-scale delayed coker units. Domestic engineering capacity gaps create openings for technology licensors.
Industry Challenges
- API 934-A Certification Timelines:Material qualification protocols for clad and solid alloy drums extend procurement lead times to 18-24 months. Fabricators face compressed delivery windows as refinery turnaround schedules fix in-place dates.
- Coke Drum Unheading Automation:OSHA process safety management requirements for remote decoking procedures demand specialized mechanical and instrumentation expertise. Refinery maintenance departments report persistent gaps in automated cutting system troubleshooting capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delayed Coker Unit Process Technology Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Cokers, Modular Cokers, Batch Cokers, Continuous Cokers Technology: Hydrocracking, Thermal Cracking, Catalytic Cracking, Fluidized Bed Cracking Application: Fuels, Chemicals, Petrochemicals, Asphalt End User: Oil Refineries, Chemical Plants, Petrochemical Complexes, Energy Companies |
| Companies Covered | Bechtel Corporation, Lummus Technology, Wood Plc, Honeywell International Inc., Sulzer, CNPC, Technip Energies N.V., KBR Inc., WorleyParsons Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delayed Coker Unit Process Technology Market Evolving Landscape
Equipment miniaturization, emissions containment architectures, and procurement model evolution are converging to reshape how delayed coker technology is specified, delivered, and operated across refinery complexes.
Modular coker skids are miniaturizing field construction scope by shifting structural welding and pressure boundary completion to controlled shop environments. EPC contractors in the US Gulf Coast and Middle East report 30-40% schedule compression on congested sites where crane availability and laydown space constrain traditional stick-built execution. This prefabrication shift is compressing project risk profiles while elevating quality assurance standards for critical welds.
REACH restrictions on hexavalent chromium surface treatments are forcing European fabricators to adopt alternative passivation chemistries for coke drum internals. The industrial consequence extends material qualification timelines and elevates coating specification complexity for units serving EU-destined product slates. German and Dutch refiners are responding by consolidating procurement with vendors holding pre-validated alternative coating certifications.
After-sales service unbundling is fragmenting traditional lump-sum maintenance contracts into discrete inspection, repair, and spare parts transactions. Specialist coke drum service providers in Texas and Louisiana are capturing this disintermediation through mobile heat treatment and on-site machining capabilities. This pattern is most visible among independent US refiners seeking to reduce fixed maintenance overhead during margin compression cycles.
Delayed Coker Unit Process Technology Market Segmentation
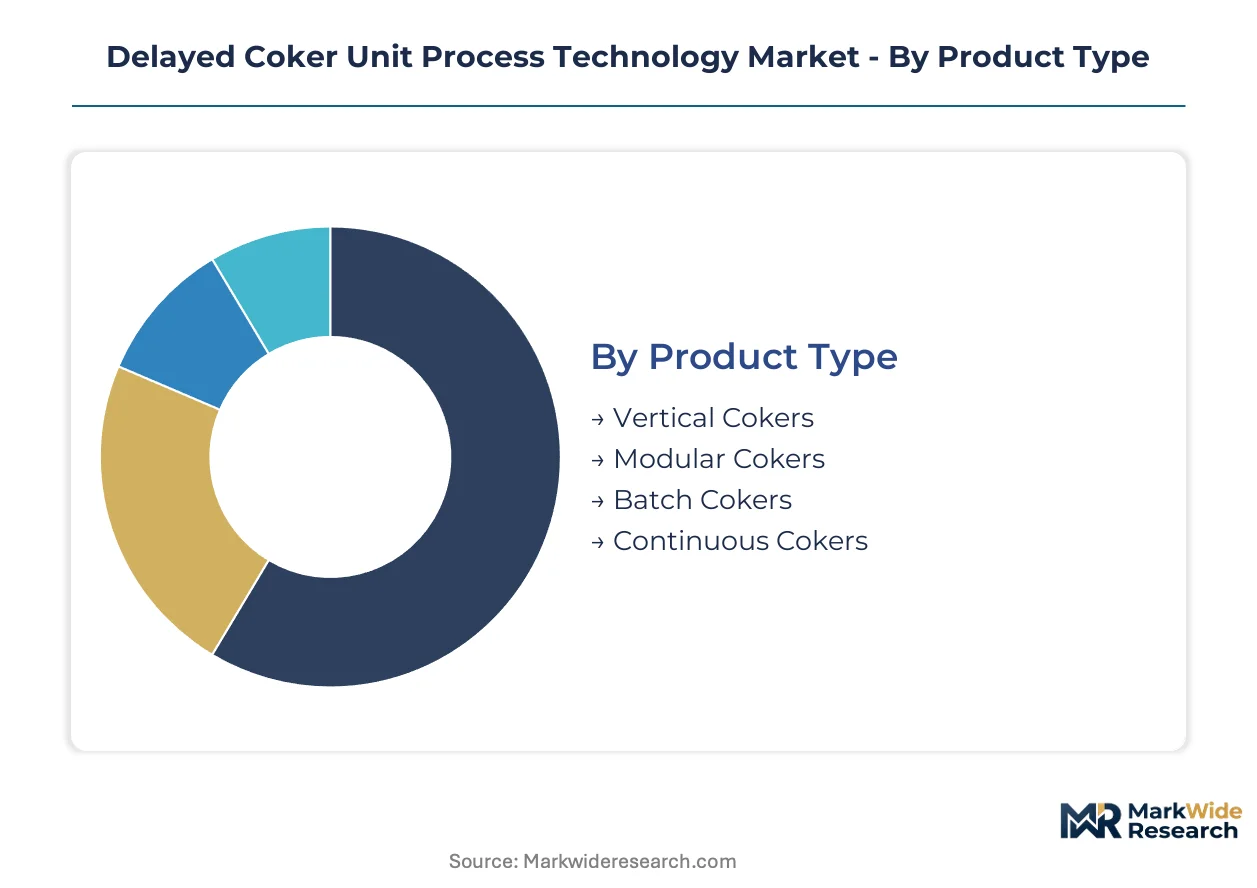
Segmentation in delayed coker technology reveals distinct procurement patterns tied to project scale and site constraints. Refinery operators select configurations based on turnaround schedules, plot space availability, and integration complexity with existing residuum upgrading trains.
Product Type:
Vertical cokers dominate domestic retrofit demand across North American refineries, while modular configurations capture export-led orders from Middle Eastern national oil companies seeking phased deployment.
- Vertical Cokers:These cylindrical vessels with top-mounted vapor lines and bottom unheading systems process residual feedstocks through batch thermal cracking cycles. Demand concentrates at US Gulf Coast refineries where existing infrastructure supports stick-built construction, though OSHA process safety mandates are accelerating automation retrofits for drum switching sequences.
- Modular Cokers:Skid-mounted configurations with pre-assembled drum pairs, coke handling systems, and integrated utilities reduce field construction labor by shifting welding to shop environments. Saudi Aramco and ADNOC downstream expansions favor these units for congested sites where crane availability and laydown space constrain traditional execution.
- Batch Cokers:Smaller-capacity units serving specialty asphalt producers and regional refiners with intermittent residuum processing requirements.
- Continuous Cokers:Emerging configurations targeting chemical plant integration where steady-state coke production supports carbon black or electrode manufacturing feedstocks.
Vertical cokers command the established base. The steepest expansion runs through modular cokers.
Technology:
Technology selection tracks margin optimization priorities, with thermal cracking anchoring high-volume fuel production while hydrocracking integration climbs fastest in chemical-oriented complexes.
- Hydrocracking:Combines thermal cracking with catalytic hydrogenation to maximize liquid yield and produce cleaner distillate slates with reduced sulfur content. Demand concentrates at complex refineries in South Korea and Singapore where clean fuel regulations and carbon border adjustments favor deeper conversion over coke production.
- Thermal Cracking:Pure thermal decomposition without catalyst addition operates at approximately 480°C and 15-20 psig in insulated drums, producing petroleum coke as unavoidable byproduct. This pathway retains cost advantage at independent US refineries prioritizing capital efficiency over yield optimization.
- Catalytic Cracking:Residuum fluid catalytic cracking units compete for heavy feedstock processing where gasoline and light olefin yields justify higher operating complexity.
- Fluidized Bed Cracking:Emerging technology for continuous coke gasification applications where integrated power or hydrogen production justifies higher capital intensity.
Thermal cracking anchors the installed capacity base. Hydrocracking integration is climbing the fastest as margin pools shift toward liquid yield maximization.
Application:
Application segmentation reflects divergent product slate economics, with fuels production dominating volume and petrochemicals offering premium pricing for anode-grade coke derivatives.
- Fuels:Gasoline, diesel, and jet fuel production from coker naphtha and gas oil fractions represents the core value proposition for residuum upgrading. US independent refiners and Middle Eastern export-oriented complexes prioritize this pathway where transportation fuel margins support thermal cracking economics.
- Petrochemicals:Anode-grade coke production for aluminum smelting electrodes and needle coke for electric arc furnace graphite electrodes commands premium pricing tiers under EU carbon border adjustment mechanisms. Coker operators with calcining integration at Rotterdam and Antwerp clusters capture these regulatory tailwinds.
- Chemicals:Carbon black feedstock and specialty carbon products from shot coke fractions serve tire manufacturing and conductive materials applications.
- Asphalt:Residual coker bottoms and decant oil blending components for paving and roofing materials, primarily at refineries with integrated asphalt terminals.
Fuels processing commands the established base. Petrochemicals integration shows the steepest expansion trajectory.
End User:
End user segmentation tracks capital deployment scale, with oil refineries anchoring large-unit demand and chemical plants emerging as specialized niche purchasers.
- Oil Refineries:Complex and simple refineries with residuum conversion requirements represent the core demand pool, spanning integrated majors and independent operators across the US Gulf Coast, Rotterdam, and Middle Eastern hubs. EPA Maximum Achievable Control Technology standards and OSHA process safety mandates sustain replacement cycles for legacy units lacking closed-loop decoking systems.
- Petrochemical Complexes:Ethylene crackers and aromatics units seeking heavy feedstock flexibility or anode-grade coke integration for aluminum smelter supply chains. Reliance Industries at Jamnagar and SABIC affiliates in Jubail Industrial City are expanding coker capacity for chemical-grade coke production.
- Chemical Plants:Carbon black producers and specialty carbon manufacturers with dedicated coker units for consistent feedstock quality.
- Energy Companies:Integrated utilities exploring petroleum coke gasification for power generation or blue hydrogen production at sites with carbon capture infrastructure.
Oil refineries command the established base. Petrochemical complexes are gaining share fastest as downstream integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Maximum Achievable Control Technology standards are compelling North American refiners to retrofit emissions control systems, while Middle Eastern national oil companies fund downstream integration projects requiring thermal cracking capacity. Saudi Aramco and ADNOC residuum upgrading programs anchor regional demand shifts.
United States
US Gulf Coast refineries process heavier domestic and Canadian crude slates through existing coker infrastructure. EPA coke drum venting regulations sustain replacement demand for legacy units lacking closed-loop decoking systems. Houston and Port Arthur clusters concentrate retrofit activity where OSHA process safety mandates accelerate automation procurement.
Saudi Arabia
Saudi Aramco downstream expansion at Jazan and Ras Tanura drives large-scale coker procurement for denser feedstock processing. The country's national oil company funds residuum upgrading integration with export-oriented refining complexes. Jubail Industrial City hosts concentrated fabrication and engineering activity supporting domestic capacity builds.
United Arab Emirates
ADNOC Ruwais Derivatives Complex expansion requires modular coker configurations for congested site deployment. MOHAP industrial safety frameworks govern pressure equipment certification timelines. Abu Dhabi refining clusters prioritize phased capital deployment through skid-mounted thermal cracking units.
India
Reliance Industries Jamnagar and Indian Oil Corporation Paradip projects represent underpenetrated demand for delayed coker technology. The country's petroleum regulator enforces pressure vessel standards through BIS certification requirements. Gujarat and Odisha refining corridors concentrate engineering procurement for residuum upgrading capacity.
South Korea
GS Caltex and S-Oil complex refineries pursue hydrocracking integration alongside thermal cracking for margin optimization. MFDS industrial safety protocols influence coke drum automation specifications. Yeosu and Ulsan petrochemical clusters pilot digital twin platforms for fatigue monitoring and switching cycle optimization.
Delayed Coker Unit Process Technology Market Competitive Landscape
Player mix skews toward integrated engineering-procurement-construction contractors and specialized technology licensors. Market structure concentrates around firms with API 934-A material qualification capabilities and proprietary residuum upgrading process packages. Two strategic archetypes dominate: full-service EPCs executing large-scale refinery retrofits, and technology specialists licensing modular configurations with compressed delivery schedules. Competitive moves center on modular delivery model expansion and metallurgical upgrade service bundling for installed base retrofits.
Within the technology licensor tier, Lummus Technology and Technip Energies N.V. exemplify contrasting execution models—proprietary integration approaches versus modular skid delivery. Bechtel Corporation anchors the EPC archetype for North American refinery retrofits. Chinese state-affiliated fabricators including CNPC occupy positions in domestic and selected export markets. These three named entities represent the competitive spectrum from process technology ownership through large-scale construction execution.
| Leading Market Players |
|---|
| Bechtel Corporation |
| Lummus Technology |
| Wood Plc |
| Honeywell International Inc. |
| Sulzer |
| CNPC |
| Technip Energies N.V. |
| KBR Inc. |
| WorleyParsons Limited |
| Others |
Value Network & Pricing Analysis
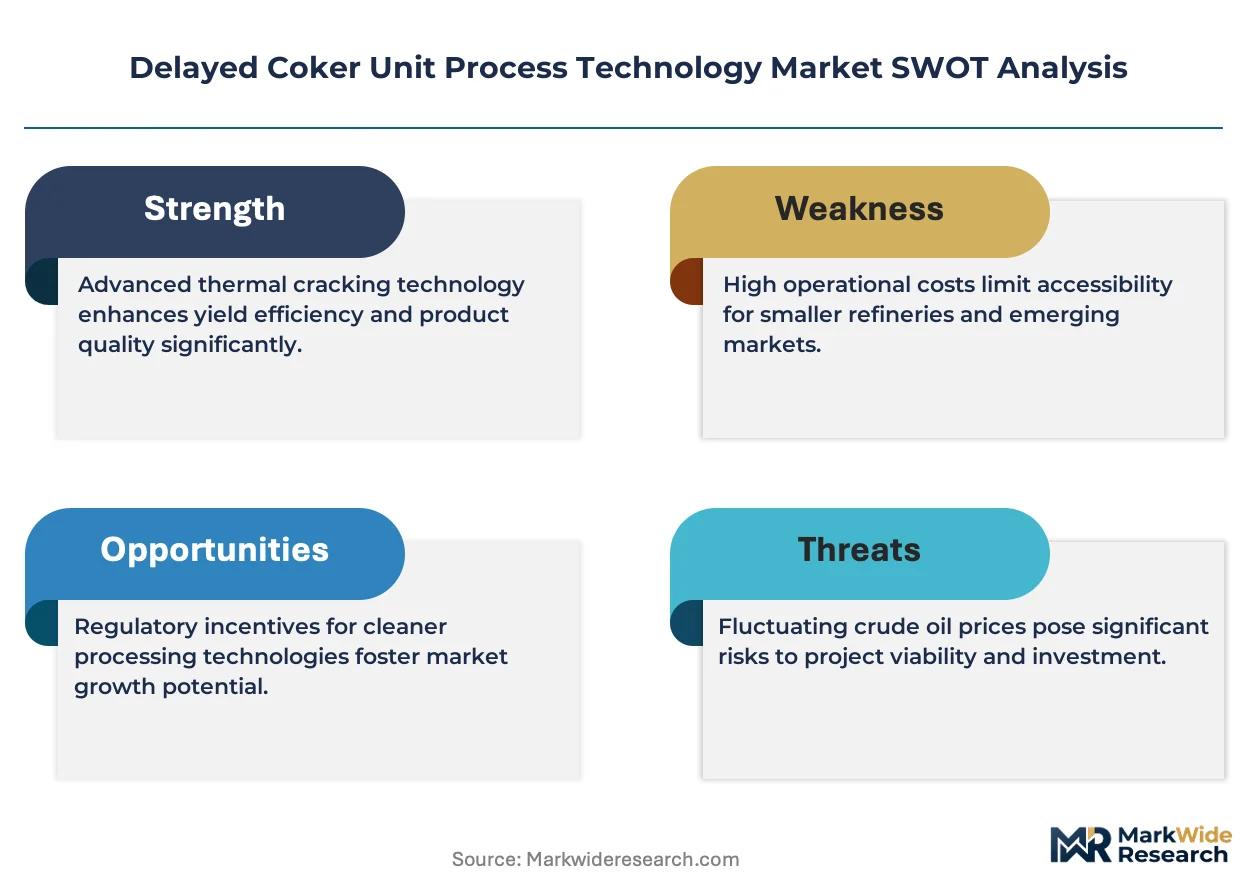
Eighteen-to-twenty-four-month procurement lead times for API 934-A qualified clad and solid alloy drums concentrate pricing power with specialty mills in Japan and Germany, while compressing fabricator margins during project bidding cycles. This inventory constraint elevates the cost of high-alloy materials and forces refiners to fix turnaround schedules well ahead of equipment delivery, reshaping how EPC contractors structure payment milestones and risk allocation.
Pricing Analysis
Certification level (API 934-A qualified versus standard chromium-molybdenum grades) creates the primary spread between premium and standard project tiers. Project-based lump-sum contracting dominates large refinery retrofits, while modular coker deliveries favor milestone-based payment structures tied to shop completion and field acceptance. Cost compression in standard-grade fabrication is intensifying because Chinese state-affiliated fabricators are expanding export capacity. Independent US refiners exhibit the highest price sensitivity due to margin compression cycles, whereas Middle Eastern national oil companies prioritize schedule certainty over unit cost.
Supply Chain Analysis
Extended material qualification timelines stretch fabricator order books and elevate work-in-progress inventory across specialty mills in Japan, Germany, and South Korea. API 934-A qualified plate and forging supply draws from concentrated metallurgical capacity, with cladding operations and forging presses anchoring fabrication networks. Single-source vulnerability runs through Japanese specialty steel producers holding proprietary heat-treatment protocols. Distribution runs through engineering-procurement-construction contractors who bundle material procurement with construction execution, disintermediating direct refiner-to-mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Delayed coker technology procurement is shifting toward platform-based vendor ecosystems where automation system interoperability and digital twin integration determine long-term contract value. This ecosystem evolution rewards licensors who bundle process technology with predictive maintenance platforms.
For Market Incumbents: Fortify metallurgical upgrade service bundling for installed base retrofits to counter displacement from hydrocracking integration and solvent deasphalting alternatives. Expand API 934-A certification capabilities in-house to reduce dependency on Japanese and German specialty mills. Deepen backward integration into clad plate fabrication to capture margin pools currently flowing to third-party metallurgical suppliers. For New Entrants and Emerging Players: Lead with modular skid delivery models targeting congested refinery sites in the UAE and India where phased capital deployment creates white-space demand. Target digital twin integration partnerships with South Korean and Singaporean refiners piloting fatigue monitoring platforms. Position through automation system specialization for OSHA-compliant coke drum unheading retrofits, where maintenance departments report persistent capability gaps. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA Maximum Achievable Control Technology standards and OSHA process safety mandates sustain replacement demand regardless of crude price cycles. Acquisition candidates include specialist coke drum service providers with mobile heat treatment and on-site machining capabilities in Texas and Louisiana. Monitor API 934-A certification timeline compression as an inflection signal—accelerated qualification protocols would unlock capacity expansion and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| API 934-A Certification Expansion | Japanese and German specialty mills extending qualified material capacity capture premium pricing tiers from North American retrofit demand. |
| Modular Skid Deployment | Saudi Aramco and ADNOC downstream projects favoring phased capital deployment compress project schedules and reduce construction risk. |
| Digital Twin Integration | South Korean refiners piloting predictive maintenance platforms for fatigue monitoring create new service revenue pools for automation vendors. |
| Closed-Loop Decoking Retrofit | EPA Maximum Achievable Control Technology compliance sustains replacement demand for legacy units lacking vapor recovery infrastructure. |
| Low-Carbon Coke Valorization | EU carbon border adjustment mechanisms create premium pricing tiers for anode-grade coke production at Rotterdam calcining clusters. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, EPC procurement leads, coke drum fabrication specialists, and automation system engineers, and refined through secondary validation against EPA enforcement databases, OSHA incident reports, SEC filings from engineering contractors, and pressure equipment certification records. Bottom-up unit-level demand estimates triangulated with top-down refinery capacity utilization projections to anchor volume forecasts.
Variance decomposition across technology type, configuration format, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand modeling incorporating residuum upgrading project pipelines, turnaround schedules, and emissions compliance deadlines. Industry-specific inputs included crude slate gravity trends and API 934-A material qualification timelines.
The analysis sits within stated boundaries; outcomes outside sustained heavy crude processing mandates or accelerated hydrocracking adoption would require recalibration. Forecasts reflect assumptions about regulatory enforcement continuity and specialty mill capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Coal Mining Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Nigeria Oil and Gas Midstream Market