
 Wireline Services Market | 2026-2036
Wireline Services Market Size, Share, and Industry Trends Forecast 2026-2036
Wireline Services Market Intelligence
Project finance and asset-light leasing structures are fragmenting capital barriers across the wireline services landscape. Schlumberger Limited leverages its integrated technology platform to bundle logging and perforating packages, while Baker Hughes Company sustains deepwater market presence through proprietary electric line systems. Halliburton Company anchors North American land operations with extensive slickline and e-line fleets deployed across major shale basins.
Wireline services encompass the deployment of specialized cables—typically single-conductor or multi-conductor electromechanical lines rated for pressures exceeding 20,000 psi and temperatures above 350°F—to convey downhole tools for well logging, perforating, and intervention operations. These services enable real-time formation evaluation and zonal isolation verification critical to optimizing hydrocarbon recovery. Well intervention applications dominate value generation due to the accelerating shift toward brownfield asset management, while real-time data acquisition technology captures the fastest expansion trajectory as operators prioritize instantaneous decision-making over post-run memory downloads. Slickline services occupy a mature, cost-sensitive niche focused on mechanical gauge cutting and plug setting rather than electronic diagnostics.
The US Bureau of Safety and Environmental Enforcement mandates real-time pressure monitoring during subsea interventions, tightening equipment certification requirements for offshore wireline contractors. EPA methane emissions rules and state-level well integrity standards in Texas and New Mexico compel operators to verify cement bond and casing conditions through validated logging suites. Stakeholders must weigh capital commitments against service outsourcing flexibility as regulatory complexity and downhole tool specialization intensify.
Market Dynamics
Real-time data acquisition technology is compressing decision cycles across wireline operations, forcing contractors to retire memory-based logging systems and retrain field crews for instantaneous telemetry interpretation.
Growth Catalysts
- Permian Basin infill drilling:Texas and New Mexico operators sustain service intensity through re-entry programs and multistage hydraulic fracturing diagnostics requiring continuous wireline deployment.
- EPA methane emissions rules:Federal mandates compel operators to verify cement bond and casing integrity through validated logging suites, expanding mandatory service volumes.
- Deepwater real-time telemetry:Subsea intervention contractors adopt electric line systems rated for pressures exceeding 20,000 psi to satisfy instantaneous formation evaluation requirements.
Market Restraints
- Specialized cable supply concentration:Multi-conductor electromechanical lines rated above 350°F depend on a limited supplier base concentrated in North American manufacturing clusters.
- High-specification tool certification costs:US Bureau of Safety and Environmental Enforcement mandates tighten equipment validation timelines for offshore contractors, extending capital recovery periods.
- Slickline substitution ceiling:Mechanical gauge cutting and plug setting applications resist electronic diagnostics upgrade, capping premium service penetration in mature well intervention segments.
Strategic Opportunities
- Brownfield asset management convergence:Accelerating shift toward well intervention applications creates bundled service openings combining logging, perforating, and zonal isolation verification.
- Asset-light leasing structures:Project finance innovations fragment capital barriers, enabling regional contractors to access high-pressure rated cable systems without fleet ownership.
- India unconventional exploration:Basins with emerging shale potential present first-mover advantages for real-time formation evaluation technology transfer from North American operational templates.
Industry Challenges
- Telemetry interpretation skill gaps:Field crews trained on post-run memory downloads require retraining for instantaneous decision-making workflows, compressing workforce transition timelines.
- Legacy fleet integration complexity:Single-conductor cable systems must interface with multi-conductor electric line architectures, creating operational friction during technology migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireline Services Market |
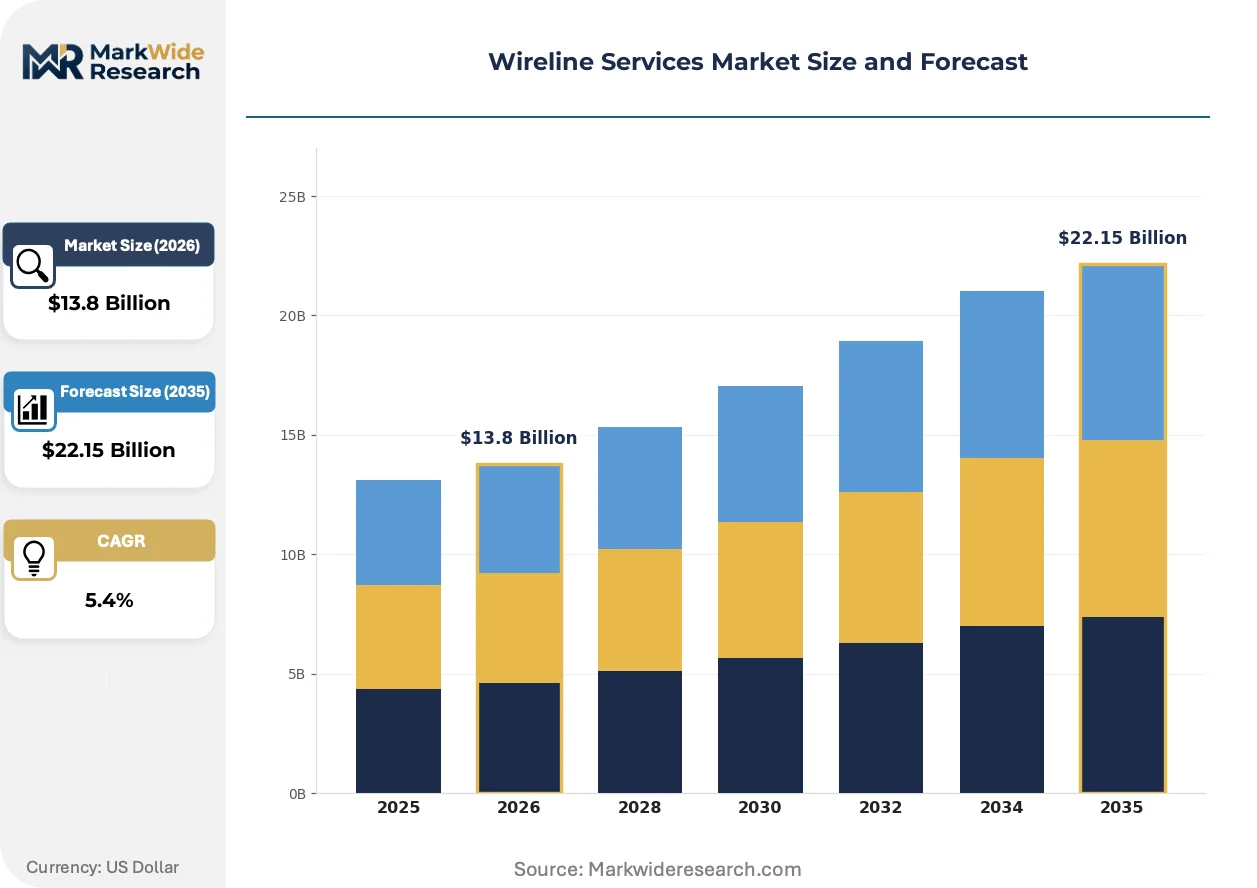
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cable Severs, Fishing Services, Perforating Services, Well Logging, Slickline Services Technology: Electric Line, Electro-Mechanical Line, Combination Line, Memory Logging, Real-Time Data Acquisition Application: Well Intervention, Formation Evaluation, Reservoir Monitoring, Production Optimization, Completion Operations End User: Oil & Gas Operators, Drilling Contractors, Completion Companies, Service Providers, National Oil Companies |
| Companies Covered | Weatherford International PLC, China Oilfield Services Limited, Schlumberger Limited, Archer Ltd, Superior Energy Services, Baker Hughes Company, Expro International Group PLC, NOV Inc., Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireline Services Market Strategic Shifts & Innovations
Digital telemetry architectures are displacing conventional data retrieval methods across wireline operations, compressing formation evaluation cycles from days to hours and restructuring contractor-operator commercial relationships.
Intelligent cable telemetry systems are digitizing downhole signal transmission through embedded fiber-optic and electrical conductor hybrids. Deepwater operators in the Gulf of Mexico adopt these platforms for instantaneous reservoir monitoring during extended-reach completions. The technology is digitizing legacy logging workflows by eliminating surface retrieval delays and enabling real-time perforation adjustment decisions.
The US Bureau of Safety and Environmental Enforcement mandates continuous pressure monitoring during subsea wireline interventions. Offshore contractors must certify electric line systems for simultaneous pressure containment and data transmission. Deepwater segments face compressed deployment windows as regulatory validation timelines extend, forcing earlier procurement commitments for high-specification equipment.
Operators now unbundle logging services from integrated drilling contracts, creating direct procurement relationships with specialized wireline contractors. Major shale producers in Texas and New Mexico negotiate standalone performance-based agreements tied to zonal isolation verification outcomes. This purchasing pattern shift concentrates service selection authority with reservoir engineering teams rather than drilling procurement functions.
Wireline Services Market Segmentation
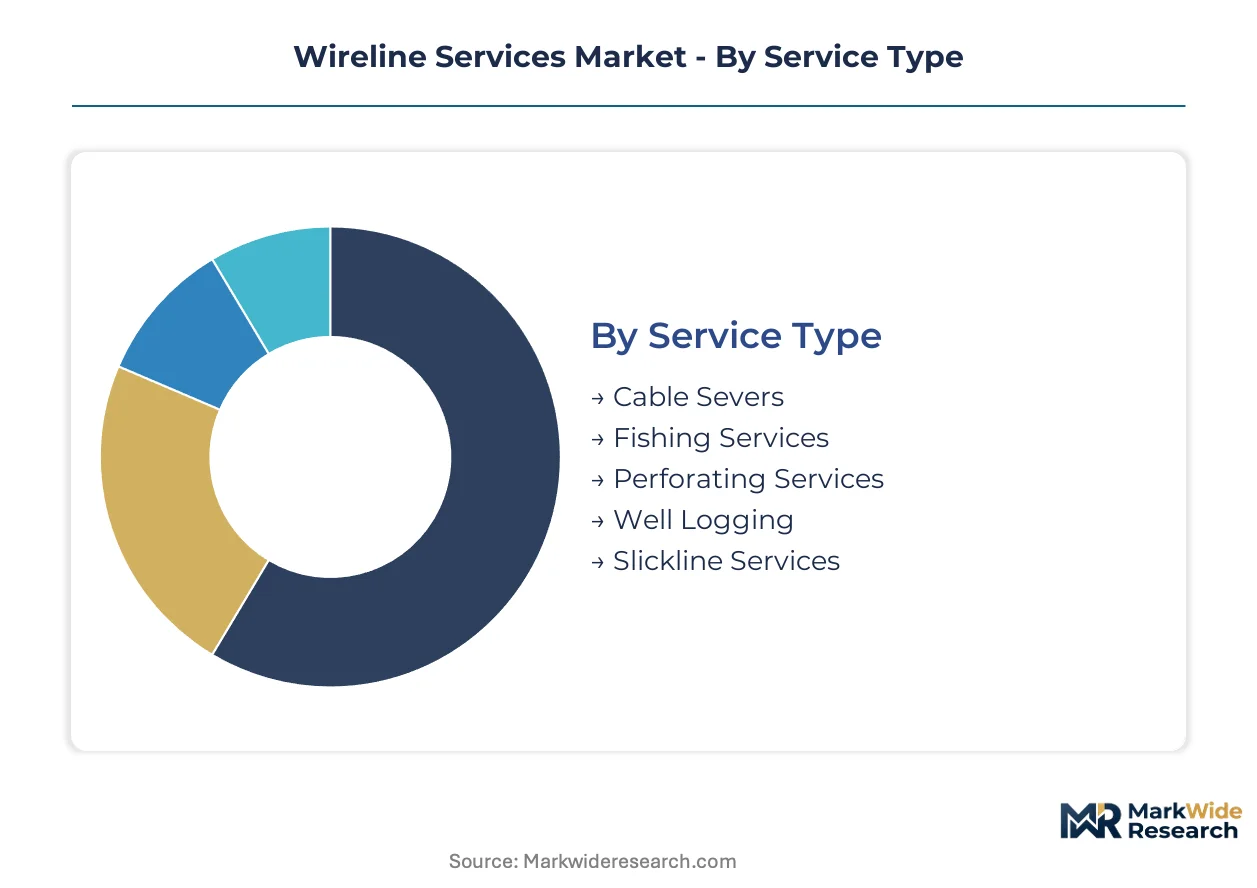
Wireline services segmentation reflects divergent capital intensity, technology sophistication, and regulatory exposure across the value chain. Service type and technology categories capture the steepest margin differentiation, while application and end-user splits reveal procurement authority shifts reshaping vendor relationships.
Service Type:
Cost tier stratification separates commoditized mechanical interventions from premium electronic diagnostics requiring specialized crews and real-time interpretation capabilities.
- Well Logging:Multi-conductor electromechanical conveyance systems rated above 350°F enable real-time formation evaluation through gamma ray, resistivity, and sonic measurements. Demand concentrates in the Permian Basin of Texas and New Mexico where infill drilling programs require continuous porosity and saturation verification.
- Perforating Services:Shaped-charge deployment via electric line creates controlled casing penetrations for hydraulic fracturing initiation. Gulf of Mexico deepwater operators specify high-pressure rated systems exceeding 20,000 psi for subsea completions where instantaneous detonation timing optimizes cluster efficiency.
- Slickline Services:Single-conductor mechanical interventions for gauge cutting and plug setting occupy mature, price-sensitive well intervention segments.
- Cable Severs:Explosive and mechanical severing tools enable well abandonment and slot recovery operations.
- Fishing Services:Retrieval of stuck tools and debris through specialized downhole grappling and milling assemblies.
Well logging commands the established base. The steepest expansion runs through perforating services.
Technology:
Application maturity separates legacy memory-based workflows from digitized telemetry architectures compressing decision cycles from days to hours.
- Real-Time Data Acquisition:Embedded fiber-optic and electrical conductor hybrids transmit instantaneous downhole signals to surface acquisition units. EPA methane emissions rules mandating cement bond verification accelerate displacement of post-run memory downloads across Texas and New Mexico shale operations.
- Electric Line:Multi-conductor cables rated for simultaneous pressure containment and data transmission satisfy US Bureau of Safety and Environmental Enforcement subsea intervention mandates. Deepwater contractors in the Gulf of Mexico face compressed deployment windows as certification timelines extend for high-specification equipment.
- Electro-Mechanical Line:Hybrid conveyance systems combining electrical conductors with mechanical strength members for demanding wellbore geometries.
- Combination Line:Configurable cable architectures adaptable across slickline and electric line operational modes.
- Memory Logging:Conventional post-run data retrieval persists in cost-constrained brownfield environments where real-time telemetry premiums are uneconomic.
Memory logging retains volume concentration in mature basins. The steepest expansion trajectory belongs to real-time data acquisition.
Application:
Customer workflow integration determines whether wireline services operate as bundled drilling accessories or standalone reservoir engineering procurements.
- Well Intervention:Brownfield asset management combining logging, perforating, and zonal isolation verification dominates value generation as operators prioritize production maintenance over greenfield exploration.
- Formation Evaluation:Real-time porosity, permeability, and fluid saturation measurements guide completion design decisions in multistage hydraulic fracturing programs.
- Reservoir Monitoring:Continuous pressure and temperature surveillance through permanent downhole gauges conveyed via wireline installation.
- Production Optimization:Diagnostic tools identifying flow restrictions and water breakthrough enable targeted remediation.
- Completion Operations:Perforating and plug setting services integrated with fracturing fleet deployments.
Well intervention anchors revenue stability. Formation evaluation is climbing the fastest as operators unbundle logging from integrated drilling contracts.
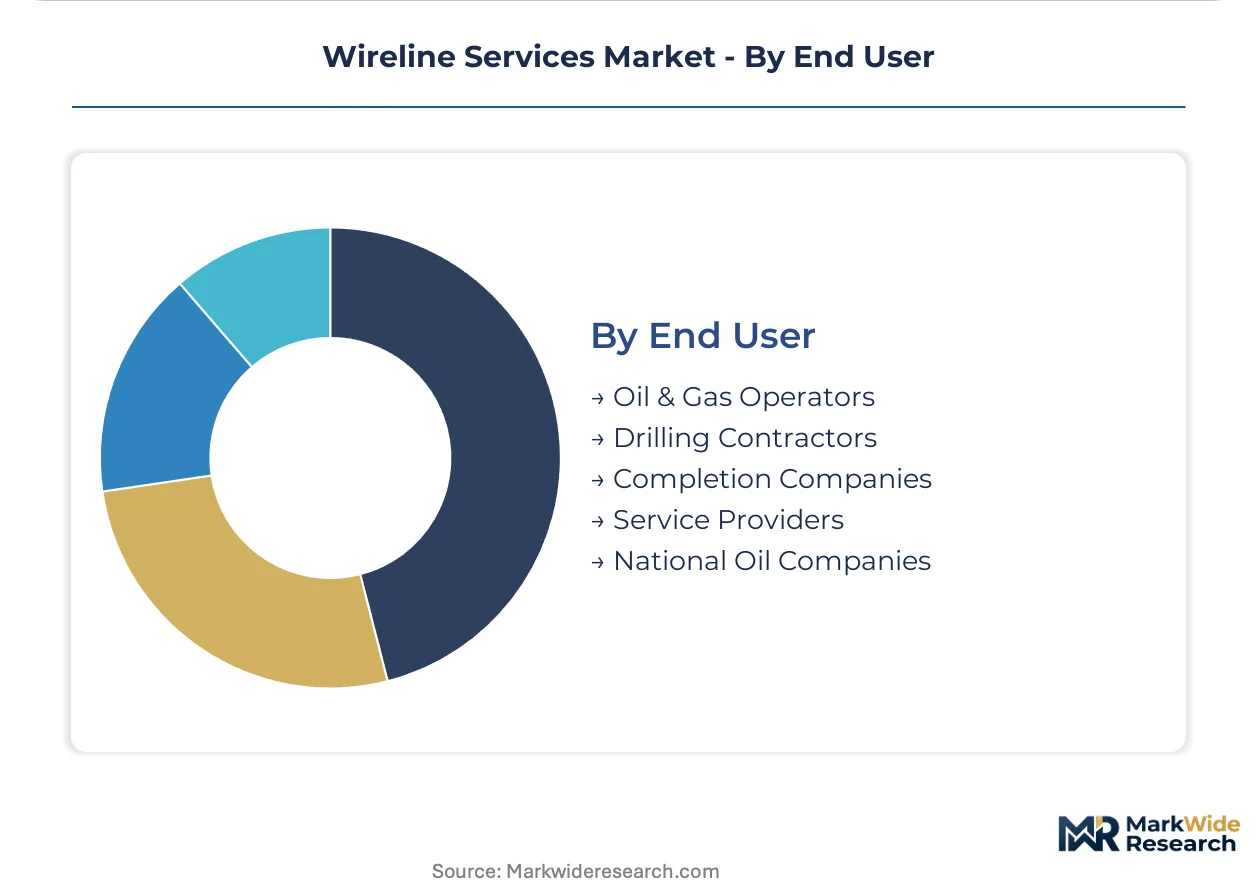
End User:
Procurement authority concentration shapes contract structures, with reservoir engineering teams displacing drilling procurement functions in service selection decisions.
- Oil & Gas Operators:Supermajors and independents negotiate performance-based agreements tied to zonal isolation verification outcomes rather than day-rate pricing.
- National Oil Companies:State-owned entities in emerging shale basins seek technology transfer partnerships replicating North American operational templates.
- Drilling Contractors:Integrated service providers bundling wireline within broader rig-based offerings.
- Completion Companies:Specialized fracturing operators requiring coordinated perforating and plug deployment services.
- Service Providers:Regional contractors accessing high-pressure rated cable systems through asset-light leasing structures.
Oil & gas operators control premium service selection. National oil companies are gaining share fastest through unconventional exploration commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Gulf of Mexico deepwater corridor while onshore shale basins compete on cost efficiency and fleet utilization rates.
United States
Permian Basin infill drilling and re-entry programs sustain wireline service intensity across Texas and New Mexico. The EPA mandates cement bond verification under methane emissions rules, expanding mandatory logging volumes. Houston anchors the deepwater supply chain, with contractors certifying electric line systems for pressures exceeding 20,000 psi.
Saudi Arabia
Unconventional exploration in the Jafurah shale basin drives demand for real-time formation evaluation technology transfer. The national oil company prioritizes horizontal well completion diagnostics requiring continuous wireline deployment. Dhahran industrial clusters host service facilities supporting high-temperature rated cable systems.
Norway
North Sea subsea intervention contractors adopt intelligent cable telemetry for extended-reach completions. Petroleum Safety Authority Norway tightens equipment certification timelines for offshore electric line operations. Stavanger concentrates specialist engineering capacity for simultaneous pressure containment and data transmission systems.
Brazil
Pre-salt carbonate formations require high-pressure perforating services for multistage hydraulic fracturing initiation. ANP regulatory frameworks mandate real-time pressure monitoring during subsea wireline interventions. Rio de Janeiro service bases coordinate deepwater fleet deployment across the Santos Basin.
United Arab Emirates
Offshore brownfield asset management expands well intervention contracts combining logging and zonal isolation verification. ADNOC technical specifications prioritize instantaneous telemetry interpretation over conventional memory logging. Abu Dhabi industrial zones concentrate regional headquarters for integrated wireline service providers.
Wireline Services Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying rated cables and downhole tools. Market structure consolidates around integrated oilfield service conglomerates with captive technology platforms, while regional contractors lease high-specification equipment through asset-light structures. Three archetypes dominate: full-service platform bundlers, electric line technology licensors, and slickline mechanical intervention specialists. Competitive moves center on portfolio diversification into real-time telemetry and strategic partnerships for unconventional basin entry.
Among Houston-based integrated service conglomerates, Schlumberger Limited and Halliburton Company occupy positions as platform bundlers anchoring North American land and deepwater segments. Baker Hughes Company exemplifies the electric line technology tier with proprietary subsea system certification. China Oilfield Services Limited represents the national oil company affiliate archetype, leveraging domestic unconventional exploration commitments for technology scale.
| Leading Market Players |
|---|
| Weatherford International PLC |
| China Oilfield Services Limited |
| Schlumberger Limited |
| Archer Ltd |
| Superior Energy Services |
| Baker Hughes Company |
| Expro International Group PLC |
| NOV Inc. |
| Halliburton Company |
| Others |
Cost & Logistics Intelligence
Single-source dependency on North American multi-conductor cable manufacturing clusters determines both tiered pricing spreads across premium electric line and economy slickline segments and supply chain vulnerability to EPA certification bottlenecks. Operators face compressed procurement timelines as US Bureau of Safety and Environmental Enforcement mandates extend validation cycles for high-temperature rated systems.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Permian Basin and Gulf of Mexico deepwater corridors. Price differentiation separates API-certified premium electric line packages from standard slickline mechanical interventions, with certification grade and volume scale as primary tiering mechanisms. Cost compression in the standard tier intensifies because regional contractors access high-specification cable systems through asset-light leasing structures without fleet ownership. National oil companies exhibit lowest price sensitivity due to technology transfer partnership requirements, while independent shale operators in Texas and New Mexico demonstrate highest sensitivity to day-rate fluctuations.
Supply Chain Analysis
Specialized alloy feedstock for pressure-rated conductors draws from manufacturing clusters concentrated in the United States, Norway, and China. Raw material dependencies center on high-tensile steel strength members, copper electrical conductors, and fiber-optic signal transmission cores. Single-source vulnerability persists for multi-conductor electromechanical lines rated above 350°F, where limited qualified suppliers face tariff exposure on specialty alloy imports. Distribution runs through Houston-anchored equipment certification facilities for deepwater contractors and regional service bases for onshore shale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireline services market sits at an early-cycle recovery phase driven by Permian Basin infill drilling intensity and EPA methane compliance mandates expanding mandatory logging volumes.
For Market Incumbents: Entrench platform bundling advantages by integrating real-time telemetry interpretation capabilities with legacy electric line fleets, countering asset-light regional contractors that lease high-specification equipment without capital ownership. Prioritize backward integration into proprietary cable manufacturing to secure supply continuity against North American supplier concentration risks. For New Entrants and Emerging Players: Build out India unconventional exploration basins as the most penetrable geography, transferring North American real-time formation evaluation operational templates to state-owned entities seeking technology partnerships. Target brownfield asset management service unbundling as the entry wedge, offering standalone zonal isolation verification contracts directly to reservoir engineering teams rather than drilling procurement functions. For Investors and Strategic Acquirers: The market sits at a capacity-tightening phase that favors electric line technology licensors with certified subsea systems. Long-term viability over the next decade hinges on regulatory compliance service mandates rather than discretionary exploration spending. Acquisition target archetype: regional contractors with established EPA certification relationships and scalable asset-light leasing platforms. The signal to watch is US Bureau of Safety and Environmental Enforcement timeline extensions for high-pressure equipment validation, which compress deployment windows and concentrate procurement authority with pre-certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Telemetry Platform Integration | Schlumberger and Baker Hughes bundle logging-perforating packages to displace memory-based workflows. |
| Asset-Light Leasing Structure Expansion | Regional contractors access 20,000 psi rated cable systems without fleet ownership capital barriers. |
| India Unconventional Basin Entry | Technology transfer partnerships replicate Permian operational templates for Jafurah shale development. |
| EPA Certification Pre-Positioning | Early procurement commitments secure validation timelines ahead of methane rule enforcement deadlines. |
| Brownfield Service Unbundling | Standalone zonal isolation contracts shift procurement authority from drilling to reservoir engineering teams. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wireline service executives, reservoir engineering directors at Permian Basin operators, EPA compliance officers, and subsea intervention project managers. Secondary validation drew from US Bureau of Safety and Environmental Enforcement equipment certification databases, EPA methane emissions rulemaking dockets, SEC filings of integrated oilfield service conglomerates, and trade customs data on high-temperature cable imports. Bottom-up fleet deployment counts across Texas and New Mexico shale basins were triangulated against top-down market value estimates.
Calibration against historical electric line and slickline utilization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type, technology tier, application workflow integration, and end-user procurement authority concentration. CAGRs were derived from regression analysis of infill drilling intensity correlated with regulatory compliance service mandates, incorporating deepwater project sanctioning timelines and unconventional exploration commitments by national oil companies.
Stress conditions across commodity price volatility, EPA certification timeline extensions, and single-source cable supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Permian Basin drilling persistence and methane rule enforcement continuity. Cross-checking against Baker Hughes rotary rig count data and US Energy Information Administration production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
Middle-East and Africa Pigging Services Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
United States Oil and Gas Separation Market