
 Subsea Well Access System Market | 2026-2036
Subsea Well Access System Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Well Access System Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD), alongside stricter US EPA rules on offshore methane emissions, is pivoting the competitive landscape toward systems with verifiable environmental performance data. TechnipFMC leverages its integrated project management capabilities for complex deepwater projects. Aker Solutions specializes in developing all-electric systems to meet these new standards. Schlumberger competes through its extensive digital and intervention service portfolio.
A subsea well access system comprises the hardware and control modules that enable intervention and maintenance activities on underwater oil and gas wells. These systems, including well intervention systems and subsea lubricators, are designed to operate under extreme pressures exceeding 10,000 psi in deepwater environments. Electro-hydraulic technology remains the dominant control method, but all-electric systems are gaining share due to lower maintenance and environmental risk. While oil extraction applications form the base demand, enhanced production and deepwater drilling represent the fastest-growing segments.
International standards like ISO 13628-7 define design and operational requirements for subsea wellhead and tree equipment, ensuring global interoperability. National regulators, such as Brazil's ANP and Norway's Petroleum Safety Authority, enforce stringent safety case approvals and local content requirements, shaping market access. Vendor selection will increasingly hinge on the ability to provide digitally-enabled, lower-carbon solutions that maximize reservoir recovery and minimize operational downtime.
Market Dynamics
The imperative to lower the carbon intensity and operational risk of offshore production is the central force shaping the subsea well access system market. This pressure manifests as a clear technological pivot towards all-electric systems and a commercial preference for solutions with verifiable environmental performance data.
Growth Catalysts
- Deepwater Exploration:Sustained investment in deepwater fields, particularly in Brazil's pre-salt basins and emerging plays in Guyana, requires advanced well access systems capable of operating under extreme pressure and temperature conditions.
- Enhanced Oil Recovery:The need to maximize output from mature offshore fields drives demand for frequent well intervention activities, stimulating the market for the associated well access hardware and control systems.
- Environmental Regulation:Stricter rules on offshore emissions, such as those from the US EPA concerning methane, create demand for newer, leak-proof systems, particularly all-electric designs that eliminate hydraulic fluid discharge risk.
Market Restraints
- High Capital Expenditure:The design, manufacturing, and deployment of deepwater well access systems rated for pressures over 10,000 psi involve immense upfront costs, acting as a significant barrier for smaller operators or marginal field developments.
- Technical Complexity:Electro-hydraulic control systems, while dominant, face reliability and maintenance challenges in ultra-deepwater environments, including hydraulic fluid degradation and complex umbilical connections that increase potential failure points.
- Regulatory Approval Cycles:National regulators like Norway's Petroleum Safety Authority enforce long and rigorous safety case approval processes for new subsea equipment, which can significantly delay project timelines and add costs.
Strategic Opportunities
- System Modularization:Developing standardized, modular all-electric systems offers a path to reduce manufacturing costs, shorten lead times, and improve interoperability between components from different vendors, lowering the total cost of ownership.
- Energy Transition Applications:Adapting well access and intervention technologies for emerging sectors like subsea carbon capture and storage (CCS) well monitoring or future subsea hydrogen production infrastructure opens new revenue streams.
- Digital Twin Integration:Offering systems with fully integrated digital twins enables predictive maintenance, remote operational support, and performance simulation, providing a high-value service layer on top of hardware sales.
Industry Challenges
- Specialized Skills Gap:A shortage of technicians and engineers with the dual expertise in high-pressure mechanical systems and advanced digital or all-electric controls hampers the deployment and maintenance of next-generation equipment.
- Legacy System Integration:Integrating modern all-electric well access systems with older, existing subsea production infrastructure and topside electro-hydraulic control units presents significant technical and operational hurdles for operators.
- Interoperability Standards:While standards like ISO 13628-7 exist, their slow evolution to cover all-electric and digital interfaces creates uncertainty for vendors and can lead to proprietary, locked-in ecosystems, hindering market-wide efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Well Access System Market |
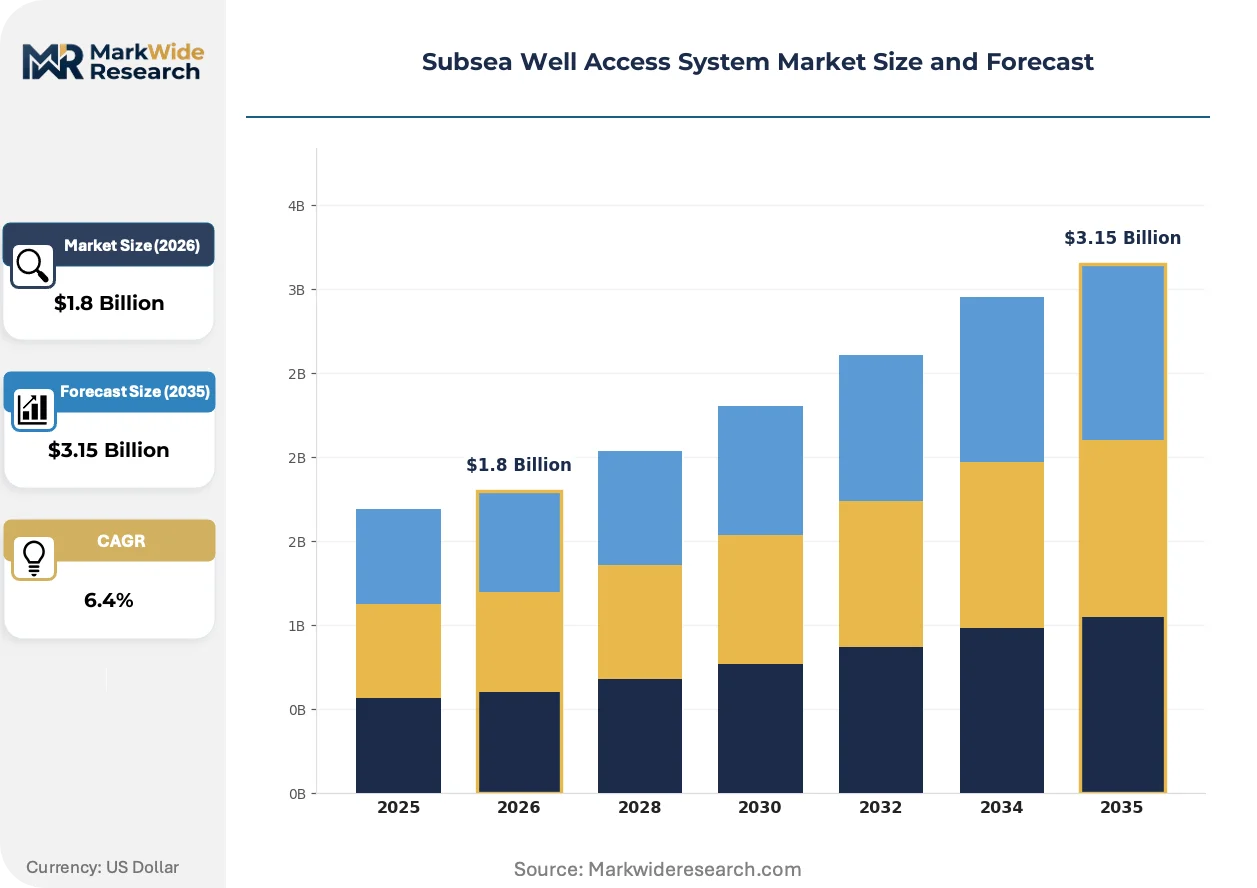
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrate Inhibitors, Well Control, Chemical Injection, Subsea Lubricators, Well Intervention Systems Technology: Hydraulic, Electric, Pneumatic, Electro-Hydraulic, Fiber Optic Application: Oil Extraction, Gas Production, Deepwater Drilling, Enhanced Production, Pipeline Maintenance End User: Oil Majors, Service Contractors, Exploration Companies, Independent E&P Firms |
| Companies Covered | TechnipFMC, Aker Solutions, Schlumberger, National Oilwell Varco, Baker Hughes, Weatherford, Oceaneering International, Halliburton, Dril-Quip, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Well Access System Market Strategic Shifts & Innovations
The market's evolution reflects a convergence of digitalization and decarbonization objectives. System selection is expanding beyond mechanical reliability and pressure ratings to include data generation capabilities and a verifiable environmental footprint, fundamentally changing the value proposition for offshore operators.
All-electric technology utilizes electric actuators for valve and choke control, removing the need for hydraulic fluids and complex umbilical lines. Deepwater operators are adopting these systems to eliminate the environmental risk of hydraulic fluid leaks and reduce the substantial cost and complexity of topside hydraulic power units. This technology is rewriting the maintenance economics and operational risk profile of subsea field development and intervention campaigns.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates granular, audited reporting on corporate environmental impacts. This regulation compels offshore operators to collect and verify performance data from their equipment, including energy consumption and potential fluid discharges from subsea systems. The directive most acutely affects projects in the North Sea and those supplying energy to Europe, accelerating demand for systems with built-in environmental monitoring.
Operators are modifying procurement patterns, moving to acquire subsea systems within broader, integrated service contracts instead of as discrete hardware purchases. This shift favors vendors that can bundle equipment with installation, long-term maintenance, intervention services, and data analytics. This trend is most visible in complex, large-scale deepwater projects, such as those in the pre-salt basins of Brazil, where lifetime asset performance is the primary focus.
Subsea Well Access System Market Segmentation
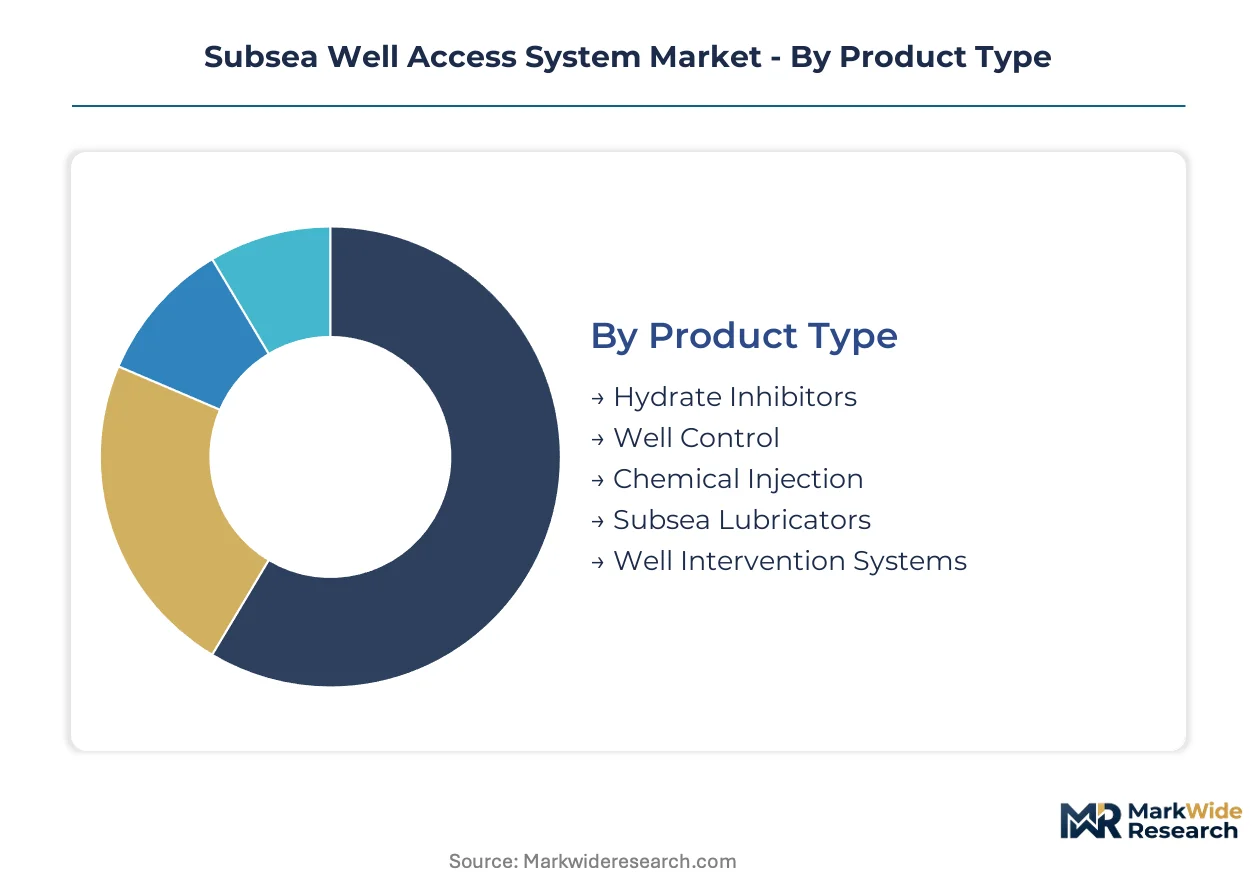
Understanding the segmentation of the subsea well access system market is critical for identifying specific operational requirements and regulatory compliance challenges. The intricate nature of deepwater operations demands specialized hardware and control modules, each facing distinct performance criteria and market dynamics.
Product Type:
Different product types within subsea well access systems face varying certification burdens, particularly for extreme pressure ratings and environmental compliance.
- Well Intervention Systems:These systems deploy tools and equipment into subsea wells for maintenance, repair, and diagnostic operations. Demand is high in Brazil's pre-salt basins, driven by the need for enhanced production from complex deepwater reservoirs.
- Subsea Lubricators:Critical components that enable the safe passage of tools into a pressurized wellbore without fluid loss, often operating at pressures exceeding 10,000 psi. Demand for these systems is significant in deepwater drilling projects, where high-pressure integrity is paramount for operational safety.
- Hydrate Inhibitors:Systems designed to prevent the formation of gas hydrates in subsea pipelines and wellbores, crucial for flow assurance in cold deepwater environments.
- Well Control:Equipment and procedures used to maintain hydrostatic pressure balance within a wellbore, preventing uncontrolled fluid flow to the surface.
- Chemical Injection:Systems that deliver various chemicals into subsea wells or flowlines for corrosion prevention, scale inhibition, or flow assurance.
Leading the category by volume: Well Control. Growing fastest: Well Intervention Systems.
Technology:
The technological landscape for subsea well access systems reflects diverse approaches, each with distinct cost profiles and operational complexities for offshore operators.
- Electro-Hydraulic:These hybrid systems combine hydraulic power for actuation with electrical signals for control, representing the dominant technology for deepwater subsea operations. Demand is strong in established offshore fields, balancing proven reliability with increasing digital integration.
- Electric:All-electric systems utilize electric actuators for valve and choke control, eliminating hydraulic fluids and reducing environmental risk. Their adoption is accelerating in new deepwater projects, driven by stricter environmental regulations like the US EPA methane rules.
- Hydraulic:Traditional systems relying solely on hydraulic fluid pressure for both power and control, often found in older subsea installations.
- Pneumatic:Technologies using compressed gas for actuation, typically limited to shallower water or specific low-power applications due to pressure constraints.
- Fiber Optic:Systems incorporating fiber optics for high-bandwidth data transmission and sensing, enhancing monitoring capabilities and remote diagnostics in subsea infrastructure.
Electric technology is gaining share fastest, while Electro-Hydraulic systems maintain the largest installed base.
Application:
Application segments for subsea well access systems delineate where the primary demand volume originates, reflecting specific operational needs across the offshore industry.
- Deepwater Drilling:This application involves accessing newly drilled wells in ultra-deepwater environments, requiring systems rated for extreme pressures and temperatures. Investment in new deepwater plays, particularly in Guyana, fuels a significant portion of this demand.
- Enhanced Production:Activities focused on maximizing hydrocarbon recovery from mature offshore fields through various intervention techniques, driving demand for frequent well access. Brazil's pre-salt basins represent a major market for these systems due to complex reservoir characteristics.
- Oil Extraction:The foundational application covering routine access and maintenance for producing oil wells throughout their operational lifecycle.
- Gas Production:Similar to oil extraction but tailored for natural gas wells, involving specific considerations for gas flow assurance and pressure management.
- Pipeline Maintenance:Applications related to the inspection, repair, and cleaning of subsea pipelines, ensuring integrity and efficient transport of hydrocarbons.
Oil Extraction forms the base demand, yet Deepwater Drilling and Enhanced Production exhibit the steepest expansion trajectory.
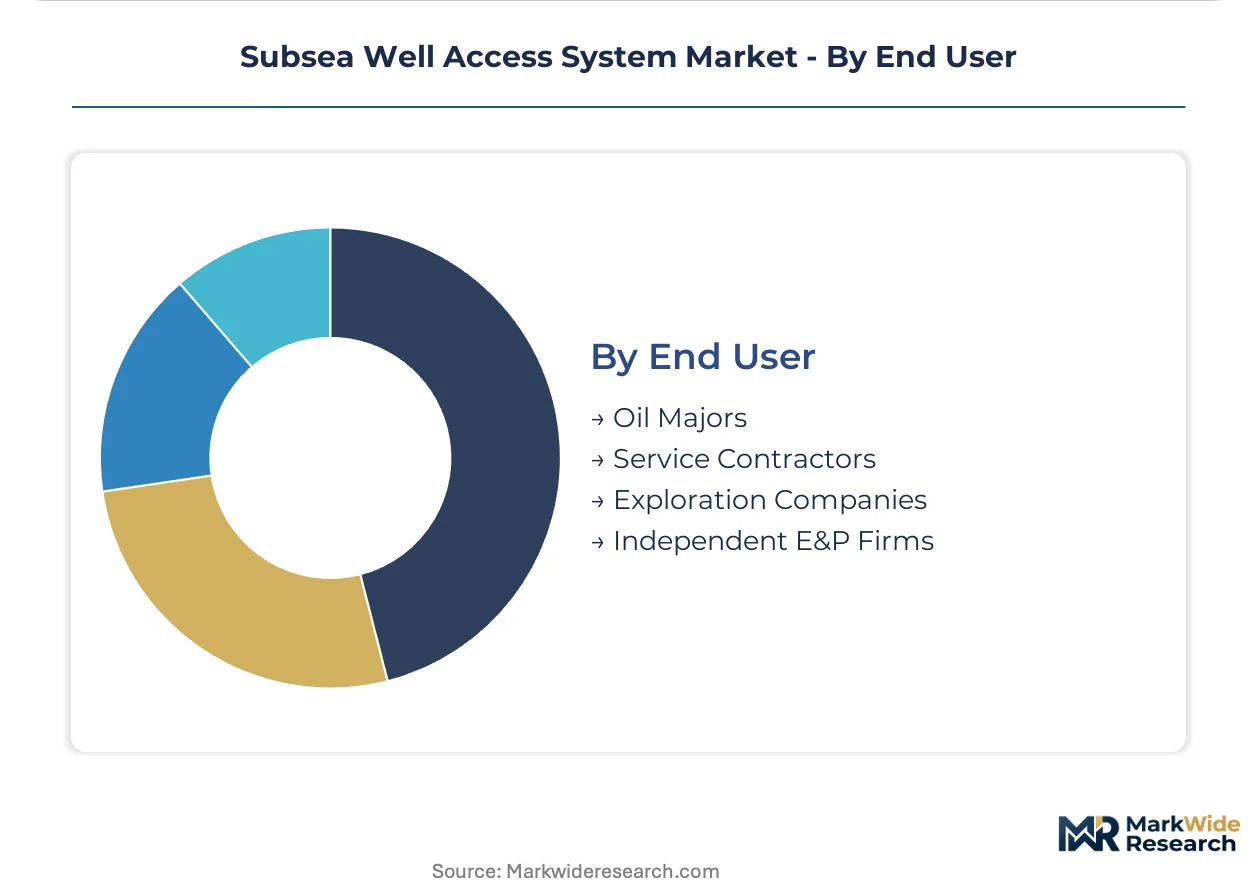
End User:
End-user segments illustrate distinct procurement patterns and operational scales, influencing vendor selection and service contract structures in the subsea well access market.
- Oil Majors:Large multinational corporations with extensive offshore portfolios, typically procuring integrated solutions for complex, long-term deepwater projects. Their procurement patterns increasingly favor vendors offering bundled equipment, maintenance, and data analytics services.
- Service Contractors:Companies specializing in providing equipment, personnel, and services for drilling, completion, and intervention activities to various operators. They often require modular and interoperable systems to serve a diverse client base effectively.
- Exploration Companies:Firms primarily focused on identifying new hydrocarbon reserves, requiring well access systems for appraisal drilling and initial well testing.
- Independent E&P Firms:Smaller to mid-sized companies involved in exploration and production, often operating in mature fields or marginal developments with specific cost-efficiency requirements.
Oil Majors exert significant market influence through large-scale project commitments, while Service Contractors adapt to varied client needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt basins, a significant tax-incentive zone for hydrocarbon exploration, drive substantial concentration in the subsea well access system market. This region, alongside other deepwater frontiers, demands advanced systems for extreme pressure and temperature conditions. Global investment in offshore projects continues to shape regional demand patterns.
Brazil
Sustained deepwater exploration in Brazil's pre-salt basins fuels demand for robust well intervention systems. The country's ANP enforces stringent local content and safety case approvals for new equipment. Rio de Janeiro and the Santos Basin serve as operational hubs for complex deepwater projects.
Norway
Norway's mature North Sea fields require advanced subsea well access for enhanced oil recovery and maintenance. The Petroleum Safety Authority mandates rigorous safety standards and approvals for all offshore technology. Stavanger and Bergen host key subsea technology providers and operational support centers.
United States
Deepwater drilling in the U.S. Gulf of Mexico necessitates high-pressure well control and intervention systems. Stricter US EPA rules on offshore methane emissions drive adoption of leak-proof, all-electric designs. Houston acts as a global center for oil and gas engineering and subsea equipment manufacturing.
Guyana
Emerging deepwater plays off the coast of Guyana represent a significant growth catalyst for subsea well access systems. The country's Environmental Protection Agency oversees new project approvals and environmental compliance. Georgetown is rapidly expanding its infrastructure to support offshore exploration and production activities.
United Kingdom
The United Kingdom's North Sea region requires continuous investment in well intervention for mature asset optimization. OPRED regulations influence equipment choices, emphasizing environmental performance and decommissioning planning. Aberdeen remains a vital hub for North Sea oil and gas operations and subsea engineering expertise.
Subsea Well Access System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the subsea well access system market, creating a dynamic competitive environment. The landscape exhibits a tiered structure, with large integrated service providers offering comprehensive solutions alongside niche technology developers. Strategic archetypes include integrated solution providers, specialized equipment manufacturers focusing on specific hardware, and digital service innovators enhancing operational efficiency. Portfolio diversification into new energy applications and strategic partnerships for technology co-development are dominant competitive moves among market participants.
Within the integrated service provider archetype, TechnipFMC exemplifies capabilities in complex deepwater project management and integrated subsea solutions, addressing the full lifecycle of offshore assets. Aker Solutions, a Norwegian company, occupies a position focused on developing advanced all-electric systems to meet evolving environmental standards and reduce operational risk in sensitive marine environments. Schlumberger, a globally recognized service company, anchors its competitive offering through extensive digital and intervention service portfolios, leveraging data analytics for predictive maintenance and enhanced reservoir recovery.
| Leading Market Players |
|---|
| TechnipFMC |
| Aker Solutions |
| Schlumberger |
| National Oilwell Varco |
| Baker Hughes |
| Weatherford |
| Oceaneering International |
| Halliburton |
| Dril-Quip |
| Others |
Cost & Logistics Intelligence
All-electric subsea control technology adoption simultaneously reshapes cost economics and concentrates manufacturing capabilities among specialized vendors. This transition emphasizes lifetime operational savings over upfront hardware costs, influencing procurement strategies.
Pricing Analysis
Expedited delivery for customized deepwater systems often commands premium pricing, while standard components see discounts for longer lead times. Project-based contracting dominates for complex subsea well access systems. Certification level for extreme pressure ratings and comprehensive after-sales service bundles drive price differentiation. Pricing softness emerges in standard components reflecting increased competition. Oil Majors prioritize long-term asset performance, making exploration companies the most price-sensitive segment.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers for ultra-deepwater equipment, particularly for all-electric system actuators. Key subsea technology providers concentrate in Norway, the United States, and the United Kingdom. Supply relies on high-grade alloys for pressure vessels and specialized electronics. Regulatory restrictions on technology transfer pose a structural risk to global supply chains. Distribution runs through direct sales to operators and service contractors, often bundled with installation and support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The subsea well access market presents a supply-constrained story due to limited global manufacturing capacity for extreme-pressure-rated equipment. This bottleneck props pricing for specialized systems, particularly for deepwater applications.
For Market Incumbents: Deepen vertical integration into critical component manufacturing to secure supply of specialized high-pressure and all-electric system parts. Incumbents must expand integrated service contracts, bundling hardware with long-term maintenance and data analytics. This strategy mitigates threats from emerging pure-play all-electric specialists. Investment in certification for new environmental standards, such as US EPA methane rules, strengthens market position.
For New Entrants and Emerging Players: Independent E&P firms operating in marginal fields represent an underserved buyer archetype for cost-efficient subsea solutions. Target modular, standardized all-electric systems designed for smaller deepwater projects or mature field enhanced production applications. Penetrate the market by offering flexible, outcome-based intervention service models rather than large capital expenditures. This approach lowers entry barriers for operators with constrained budgets.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized all-electric technology developers given stricter environmental regulations and the broader energy transition. The market shows long-term viability from sustained deepwater exploration and enhanced recovery demand over the next decade. Target niche providers offering digital twin integration or subsea CCS well monitoring technology. Increased regulatory enforcement of methane emission reductions serves as a key inflection indicator for investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in All-Electric Manufacturing | Increases supply resilience for critical components and meets rising demand for lower-carbon solutions. |
| Partnerships for Digital Twin Integration | Enhances predictive maintenance capabilities and offers high-value data analytics services to operators. |
| Acquisition of Subsea CCS Technology Firm | Diversifies revenue streams into emerging energy transition applications beyond traditional oil and gas. |
| Investment in Modular System Design | Reduces manufacturing costs and shortens lead times, improving interoperability for diverse projects. |
| Geographic Expansion into Guyana/Brazil | Captures growth from rapidly expanding deepwater exploration and production activities in key regions. |
Research Approach
Multi-period observation of subsea equipment installations, deepwater drilling project approvals, and environmental compliance records anchored the trend analysis, supplemented by interviews. Primary research involved discussions with subsea engineers, procurement managers at Oil Majors, regulatory affairs specialists, and service contractors. Secondary validation drew from International Energy Agency reports, national oil company disclosures, and industry association whitepapers. This approach utilized both bottom-up and top-down data triangulation.
Segment-weighting by product type, technology, application, end-user, and regional demand formed the core of the analytical framework across the modeling period. Operating pressure rating was a critical industry-specific dimension. Compound annual growth rates were derived from historical data and projected market expansion drivers. Key forecast inputs included deepwater drilling rig utilization rates and global offshore investment commitments.
Revisions become necessary when significant shifts in global oil prices or major regulatory changes materialize. Forecasts reflect assumptions regarding sustained deepwater investment and technological adoption. Geopolitical instability or unforeseen technological breakthroughs represent key risk factors; outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Japan AI in Oil and Gas Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Slickline Services Market