
 Oil and Gas Data Management Market | 2026-2036
Oil and Gas Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Data Management Market Analysis
Exploration companies is bifurcating demand away from legacy production-only buyers as seismic data volumes and reservoir complexity outpace on-premise storage limits. Halliburton leverages its subsurface software heritage to anchor deepwater analytics workflows across the Gulf of Mexico. Baker Hughes differentiates through integrated digital twin platforms that merge sensor telemetry with predictive maintenance models. Kongsberg Digital specializes in offshore asset visualization, sustaining competitive position among North Sea operators through high-fidelity simulation environments.
Oil and gas data management encompasses the systematic collection, validation, storage, and analysis of subsurface, operational, and commercial datasets spanning exploration through decommissioning, typically governed by ISO 8000 data quality standards and requiring sub-second latency for real-time drilling optimization. The discipline serves to reduce unplanned downtime, extend field economics, and satisfy regulatory disclosure requirements across hydrocarbon value chains. Cloud solutions now capture the fastest expansion as supermajors migrate petabyte-scale seismic libraries to distributed architectures, while analytics tools command the deepest margin pools where proprietary algorithms translate raw signals into actionable completion designs. AI analytics within the technology dimension is concentrating vendor R&D budgets, though IoT solutions retain structural importance for edge-computing deployments on remote well pads.
The US EPA mandates greenhouse gas reporting protocols that force production firms to instrument methane detection networks, directly stimulating demand for real-time monitoring data architectures. Norway's Petroleum Safety Authority imposes barrier management documentation standards that require digital audit trails, shaping Norwegian Continental Shelf procurement specifications. Stakeholders must weigh sovereign data residency requirements against cloud provider geographic coverage when architecting multi-jurisdiction deployment strategies.
Market Dynamics
Cloud-native architectures are decomposing legacy on-premise data silos as petabyte-scale seismic libraries migrate to distributed computing environments, forcing vendors to reprice storage and analytics bundles around consumption rather than perpetual licensing.
Growth Catalysts
- US EPA methane reporting mandates:Greenhouse gas protocols compel production firms to deploy real-time detection networks, stimulating demand for edge-computing data architectures that capture continuous emissions telemetry.
- Reservoir complexity escalation:Unconventional shale formations and deepwater carbonate targets generate multi-terabyte seismic datasets that overwhelm conventional storage, accelerating platform refresh cycles among exploration operators.
- ISO 8000 data quality frameworks:Standardized validation protocols reduce interoperability friction between subsurface, drilling, and production systems, lowering integration costs for multi-vendor environments.
Market Restraints
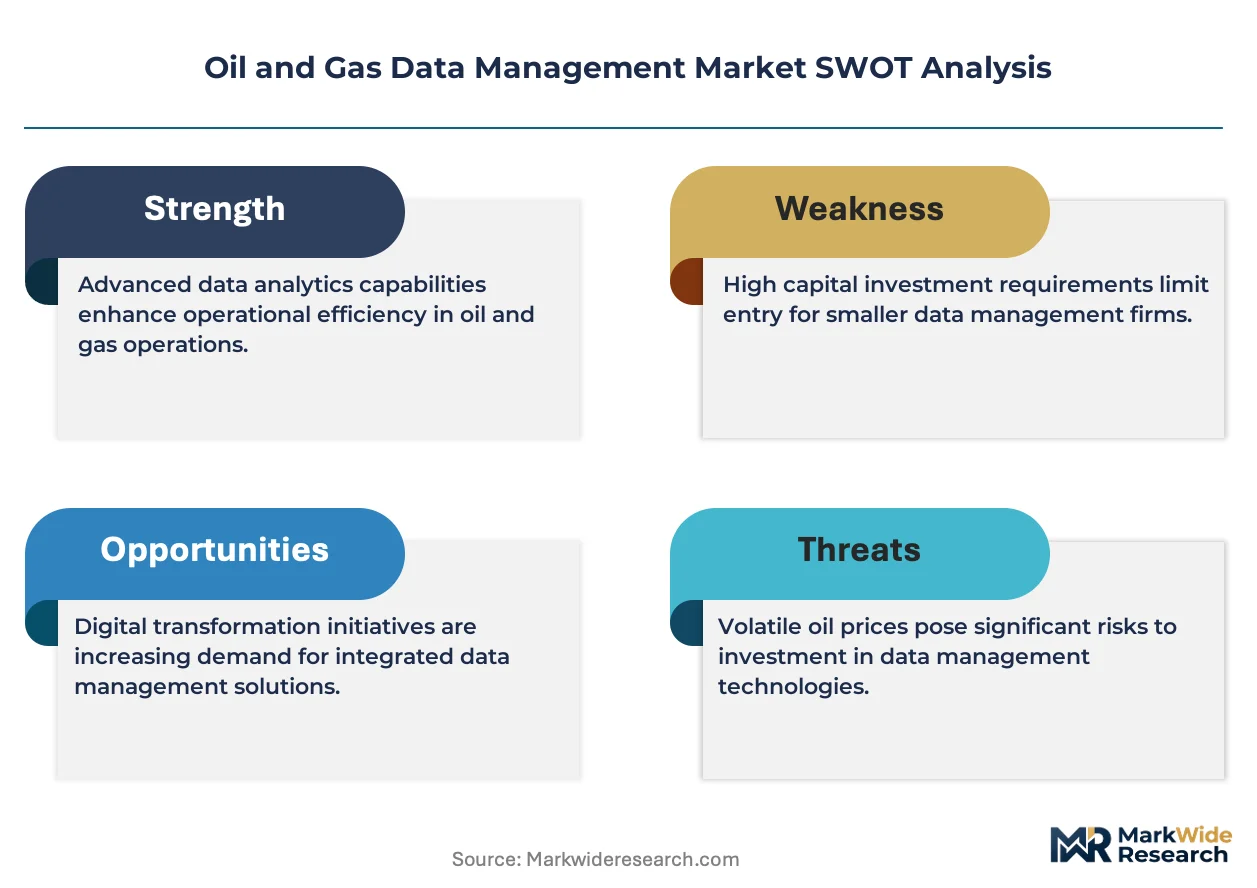
- Sovereign data residency requirements:Norwegian Continental Shelf operators face Petroleum Safety Authority audit-trail mandates that conflict with hyperscaler geographic coverage gaps, forcing hybrid architectures that inflate total cost of ownership.
- Specialized geoscientist scarcity:Reservoir simulation and seismic interpretation expertise concentrates among aging professional cohorts, constraining implementation velocity for advanced analytics platforms.
- Legacy system entrenchment:Decades of proprietary data formats in subsurface software create switching costs that delay cloud migration timelines for mature producing assets.
Strategic Opportunities
- Decommissioning data monetization:North Sea asset retirement obligations generate demand for digital twin archives that preserve structural integrity records for liability transfer and regulatory closure.
- AI-driven completion optimization:Machine learning models that translate real-time drilling parameters into actionable frac designs command premium pricing in Permian Basin unconventional plays.
- EU CSRD sustainability disclosure:Scope 3 emissions tracking requirements create openings for integrated carbon accounting modules within existing production data management suites.
Industry Challenges
- Cyber-physical security integration:Converging IT and OT networks expose upstream operations to ransomware vectors that target drilling control systems through compromised data pipelines.
- Subsurface data harmonization:Seismic, well log, and core sample formats lack universal translation standards, forcing expensive manual curation before analytics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Data Management Market |
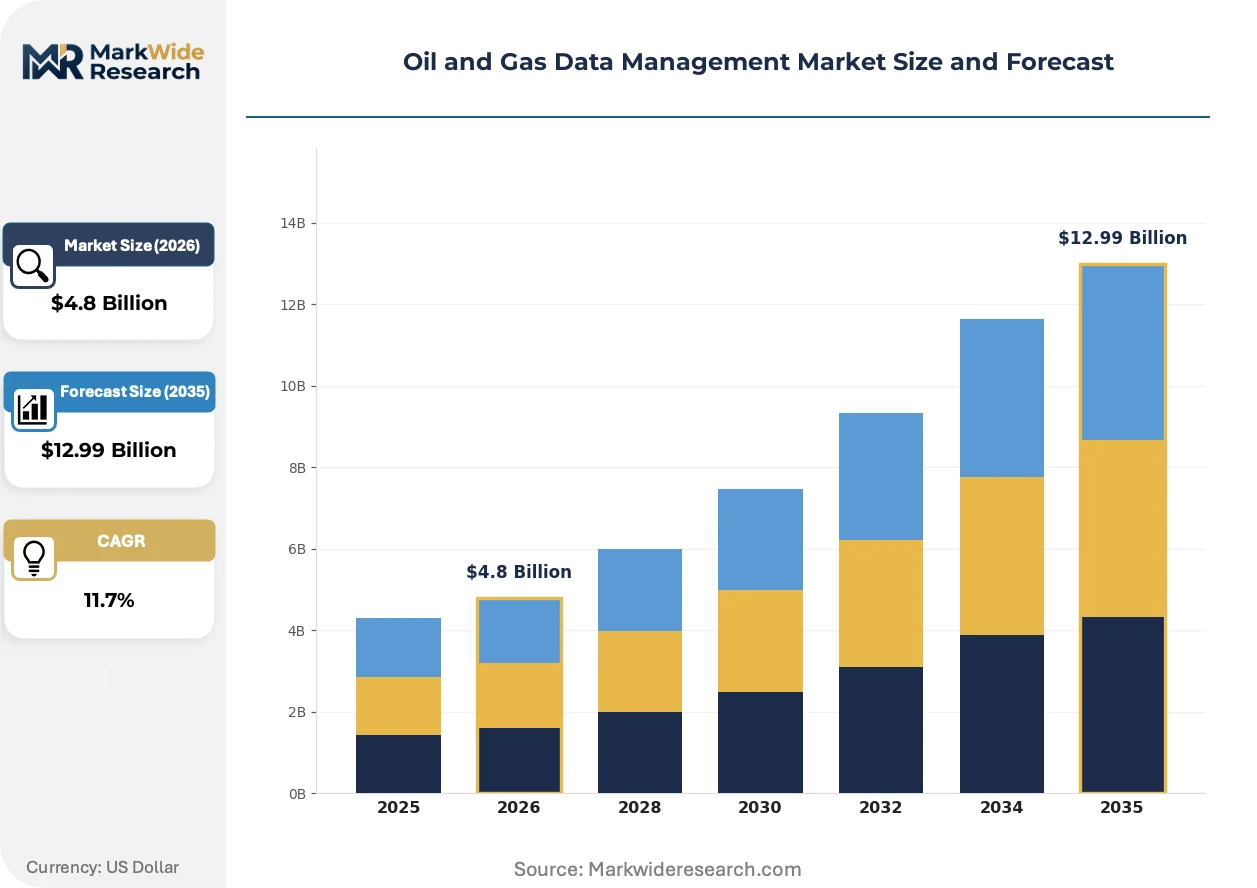
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Integration, Analytics Tools, Cloud Solutions, Real-time Monitoring End User: Exploration Companies, Production Firms, Service Providers, Regulatory Agencies Technology: IoT Solutions, Big Data Platforms, AI Analytics, Cloud Computing Application: Asset Management, Performance Optimization, Risk Management, Compliance |
| Companies Covered | AspenTech, Code District, Halliburton, TIBCO Software, Entrans Technologies, Baker Hughes, Kongsberg Digital, Wipro, Informatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Data Management Market Emerging Trajectories
Real-time telemetry and predictive algorithms are compressing decision cycles from weeks to hours across drilling and production workflows, restructuring how operators value data platform capabilities.
Edge computing infrastructure is decomposing centralized data processing models by enabling local analytics execution on remote well pads. Exploration companies in West Texas shale formations deploy containerized computing clusters that preprocess sensor streams before cloud transmission, reducing bandwidth costs and latency for critical drilling parameters. This distributed architecture is compressing the addressable market for traditional hub-and-spoke data center configurations.
Norway's Petroleum Safety Authority barrier management documentation standards mandate digital audit trails for safety-critical equipment, compelling operators to instrument valves, blowout preventers, and subsea trees with continuous monitoring. Norwegian Continental Shelf producers now require vendors to demonstrate ISO 8000-compliant data lineage capabilities as a procurement prerequisite, reshaping competitive evaluation criteria for platform selection.
Subscription consumption models are displacing perpetual license arrangements as supermajors demand elasticity for seismic processing workloads that spike during exploration campaigns. Data management vendors respond with usage-based pricing that aligns costs to active project phases, transferring capital expenditure risk from buyers to providers. This shift is most pronounced among Gulf of Mexico deepwater operators managing irregular appraisal drilling schedules.
Oil and Gas Data Management Market Segmentation
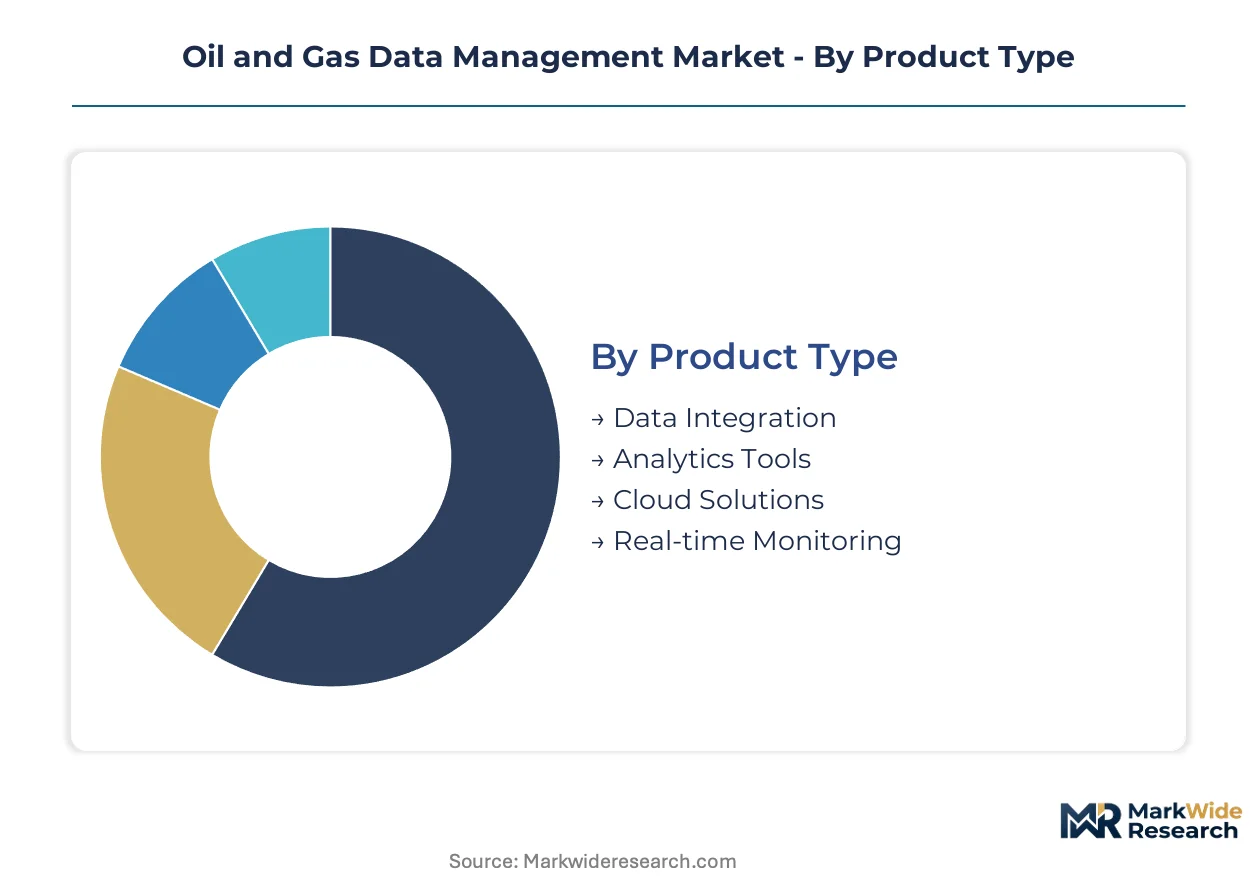
Segmentation in oil and gas data management reveals how procurement priorities diverge between upstream operators seeking reservoir intelligence and midstream players optimizing throughput. Technology choices increasingly bifurcate between cloud-native architectures for new developments and hybrid systems for brownfield retrofits.
Product Type:
Margin pools concentrate in analytics tools where proprietary algorithms command premium pricing, while cloud solutions capture volume through consumption-based scaling.
- Data Integration:Middleware platforms harmonize seismic, well log, and production telemetry into unified schemas. Norwegian Continental Shelf operators prioritize ISO 8000-compliant lineage engines to satisfy Petroleum Safety Authority audit requirements.
- Analytics Tools:Reservoir simulation and predictive maintenance modules translate raw signals into completion designs and equipment health forecasts. Permian Basin shale producers drive demand for machine learning frac optimization as lateral lengths extend beyond 15,000 feet.
- Cloud Solutions:Distributed storage architectures host petabyte-scale seismic libraries with elastic compute for processing spikes.
- Real-time Monitoring:Edge-computing pipelines capture continuous drilling parameters and emissions telemetry for immediate intervention.
The dominant share belongs to analytics tools, while cloud solutions are closing the gap fastest.
End User:
Procurement authority shifts toward exploration companies as seismic data volumes overwhelm legacy infrastructure budgets.
- Exploration Companies:Seismic acquisition firms and appraisal drilling operators manage multi-terabyte subsurface datasets spanning basin-scale surveys. Gulf of Mexico deepwater campaigns require sub-second latency for geosteering decisions in high-pressure carbonate targets.
- Production Firms:Operating companies instrument mature fields with IoT sensor networks to extend plateau rates and reduce unplanned downtime. US onshore operators face EPA methane reporting mandates that force real-time detection architecture upgrades.
- Service Providers:Drilling contractors and completion specialists deploy white-label data platforms to differentiate integrated service offerings.
- Regulatory Agencies:National petroleum regulators and environmental authorities mandate standardized disclosure formats for production and emissions data.
Exploration companies command the largest procurement budgets, though production firms are expanding their data management spending most aggressively.
Technology:
Vendor R&D concentrates on AI analytics as differentiation shifts from storage capacity to interpretive accuracy.
- IoT Solutions:Edge devices and sensor networks capture physical equipment states at remote well pads and offshore platforms. West Texas shale operators deploy containerized preprocessing clusters to reduce bandwidth costs before cloud transmission.
- Big Data Platforms:Distributed computing frameworks process historical production records and real-time streams at scale. Middle Eastern national oil companies leverage these architectures for mature field redevelopment across giant carbonate reservoirs.
- AI Analytics:Machine learning models identify patterns in drilling parameters, production decline curves, and equipment vibration signatures.
- Cloud Computing:Hyperscaler infrastructure delivers elastic storage and compute without capital-intensive data center builds.
AI analytics captures the steepest expansion trajectory, while cloud computing provides the foundational infrastructure layer.
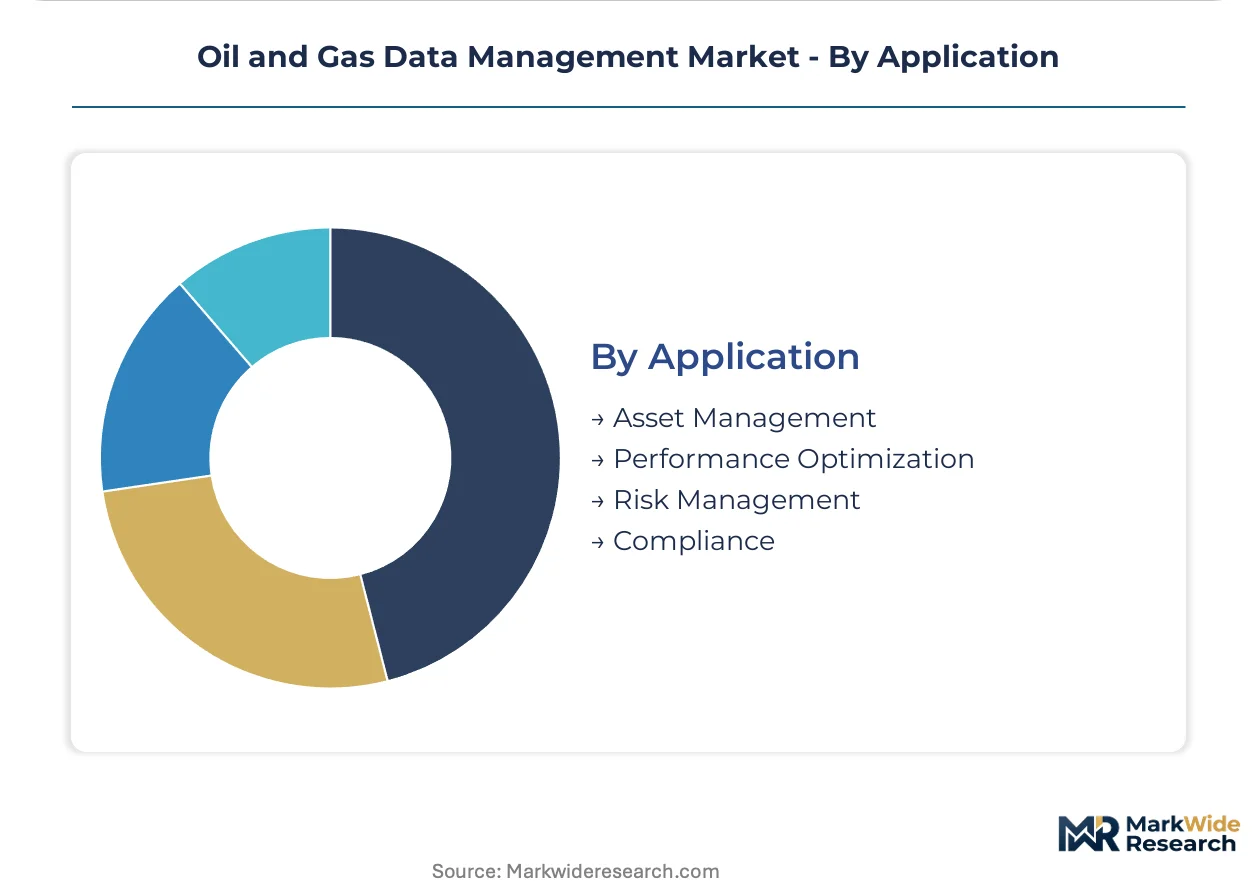
Application:
Value realization varies sharply between operational efficiency gains and regulatory risk mitigation.
- Asset Management:Digital twin platforms model structural integrity and equipment lifecycle for offshore platforms and subsea infrastructure. North Sea operators approaching decommissioning deadlines prioritize archive systems that preserve liability records for decades.
- Performance Optimization:Real-time drilling analytics and production surveillance systems maximize recovery factors and minimize non-productive time. Unconventional shale developers use these tools to standardize best practices across dispersed well portfolios.
- Risk Management:Predictive models forecast equipment failures, wellbore stability issues, and reservoir containment risks.
- Compliance:Automated reporting modules satisfy EPA greenhouse gas protocols, EU CSRD sustainability disclosures, and national petroleum regulator filing requirements.
Asset management holds the dominant position, with compliance applications gaining share fastest as disclosure mandates multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network and Gulf Coast export terminals anchor United States capacity for seismic data processing and real-time drilling analytics. Norwegian subsea cable infrastructure connects North Sea platforms to onshore computing clusters. Saudi Aramco's East-West Pipeline corridor enables centralized data aggregation from Eastern Province fields.
United States
Shale operators in West Texas and New Mexico drive edge-computing deployments for frac optimization and methane detection. EPA greenhouse gas reporting mandates compel real-time emissions monitoring architectures across Permian and Bakken basins. Houston hosts the dominant concentration of subsurface software vendors and cloud service provider regional nodes.
Norway
Deepwater producers on the Norwegian Continental Shelf require sub-second latency for geosteering in high-pressure carbonate reservoirs. The Petroleum Safety Authority imposes barrier management documentation standards that mandate ISO 8000-compliant digital audit trails. Stavanger and Bergen clusters specialize in offshore asset visualization and digital twin development for subsea infrastructure.
Saudi Arabia
National oil company field redevelopment programs generate petabyte-scale seismic processing demand across giant carbonate reservoirs. The kingdom's data residency requirements shape hybrid cloud procurement for production surveillance systems. Dhahran's technology cluster concentrates vendor R&D partnerships for reservoir simulation and predictive maintenance platforms.
United Kingdom
North Sea decommissioning obligations stimulate demand for digital twin archives preserving structural integrity records for liability transfer. The North Sea Transition Authority mandates standardized data formats for asset retirement documentation. Aberdeen's technology hub specializes in legacy data migration and offshore platform digitalization services.
Canada
Oil sands operators deploy big data platforms for steam-assisted gravity drainage optimization and emissions intensity tracking. Environment and Climate Change Canada protocols require continuous monitoring of fugitive methane from in-situ extraction sites. Calgary's energy technology corridor hosts analytics vendors serving both oil sands and conventional Western Canadian Sedimentary Basin producers.
Oil and Gas Data Management Market Vendor Landscape
Listed leaders compete with private specialists across cloud infrastructure and subsurface software domains. The vendor landscape organizes around three strategic tiers: integrated oilfield service conglomerates with software heritage, pure-play data management platforms, and hyperscaler cloud providers with energy vertical specializations. Dominant competitive moves include strategic partnerships between seismic acquisition firms and analytics vendors, plus vertical integration into edge-computing hardware for remote well pad deployments.
Within the integrated services tier, Halliburton and Baker Hughes exemplify archetypes that leverage decades of subsurface expertise to anchor enterprise data management workflows. Kongsberg Digital occupies a specialist position among North Sea-focused offshore asset visualization providers. These three entities represent contrasting geographic and functional emphases—Houston-based conglomerate breadth, Houston-based digital twin integration, and Kongsberg-headquartered offshore simulation fidelity—without implying specific market share or strategic initiative claims.
| Leading Market Players |
|---|
| AspenTech |
| Code District |
| Halliburton |
| TIBCO Software |
| Entrans Technologies |
| Baker Hughes |
| Kongsberg Digital |
| Wipro |
| Informatica |
| Others |
Supply Flow & Price Mechanics
Ninety-day implementation cycles for cloud-native data platforms concentrate procurement leverage among North American shale operators with standardized well pad configurations, compressing vendor margins while amplifying pricing power for buyers with multi-year seismic processing commitments. This lead-time asymmetry between brownfield retrofit complexity and greenfield deployment speed is reshaping contract structures across the value chain.
Pricing Analysis
Volume-discount tiering separates enterprise-wide platform commitments from single-basin deployments, with three-tier pricing structure across premium, standard, and economy levels anchoring vendor revenue models. Price differentiation rests on data residency certification tiers and after-sales implementation support depth. Pricing pressure stems from hyperscaler infrastructure commoditization, which erodes storage margin pools. Production firms exhibit highest price sensitivity due to capital discipline mandates, while exploration companies accept premium tiers for sub-second latency guarantees in geosteering applications.
Supply Chain Analysis
Subsea cable landing stations at Stavanger, Houston, and Singapore constitute chokepoints that tether offshore platform connectivity to terrestrial computing clusters. Hardware componentry draws from Taiwan for edge-computing silicon, Germany for precision sensor instrumentation, and the United States for cloud infrastructure orchestration. Single-source vulnerability concentrates in specialized seismic processing accelerators. Distribution runs through systems integrators with petroleum industry vertical expertise rather than direct vendor-to-operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed analytics services and continuous data quality assurance represent the fastest-expanding recurring-revenue layers, outpacing perpetual license hardware sales as supermajors prioritize outcome-based consumption over capital-intensive platform ownership.
For Market Incumbents: Shield installed base erosion by embedding ISO 8000-compliant lineage engines deeply into Norwegian Continental Shelf operator workflows, creating switching-cost moats against cloud-native challengers. Prioritize backward integration into edge-computing hardware for remote Permian Basin well pads to capture preprocessing margin pools currently leaking to third-party device vendors. For New Entrants and Emerging Players: Lead with AI-driven completion optimization modules targeting West Texas shale operators extending lateral lengths beyond 15,000 feet, where incumbent platforms exhibit interpretive latency gaps. White-label partnerships with drilling contractors offer lower customer acquisition friction than direct enterprise sales to supermajors. For Investors and Strategic Acquirers: Long-term, this sits as a subscription-conversion play because consumption-based pricing aligns vendor incentives with exploration campaign volatility, reducing revenue cyclicality versus perpetual license models. Target acquisition candidates with proven hyperscaler partnership architectures and established Petroleum Safety Authority compliance track records. Monitor EPA methane reporting mandate enforcement intensity as inflection indicator for real-time monitoring data architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Supermajors transferring petabyte-scale seismic libraries to distributed architectures reduce capital expenditure burdens. |
| Edge-Computing Hardware Integration | Containerized preprocessing clusters on remote well pads capture bandwidth cost savings before cloud transmission. |
| AI Analytics Module Development | Machine learning frac optimization commands premium pricing in Permian Basin unconventional plays. |
| Regulatory Compliance Certification | ISO 8000 data lineage capabilities satisfy Norwegian Petroleum Safety Authority procurement prerequisites. |
| Strategic Hyperscaler Partnership | Elastic compute arrangements align seismic processing costs to irregular exploration campaign spikes. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with subsurface software executives, drilling data officers, and cloud infrastructure procurement leads at North American shale operators and Norwegian offshore producers; and secondary validation against SEC filings from listed oilfield service conglomerates, EPA greenhouse gas reporting protocols, and Norwegian Petroleum Safety Authority barrier management documentation standards. Bottom-up triangulation across deployment size bands and top-down reconciliation against seismic data volume growth curves anchored market sizing.
Across the analysis window, forecasts modeled technology segmentation spanning IoT solutions, big data platforms, AI analytics, and cloud computing; end-user bifurcation between exploration companies and production firms; and application differentiation across asset management, performance optimization, risk management, and compliance. CAGRs derived from elasticity-adjusted adoption curves incorporating reservoir complexity escalation rates and regulatory mandate implementation timelines. Industry-specific inputs included petabyte-scale seismic library migration velocities and edge-computing container deployment densities per well pad.
Forecasts assume regulatory continuity in EPA methane reporting protocols and Norwegian Petroleum Safety Authority audit-trail mandates; material policy shifts would require re-modeling demand trajectories for real-time monitoring architectures. Scenario boundaries incorporate hyperscaler geographic coverage expansion rates and specialized geoscientist workforce demographics as structural constraint variables. Practitioners should keep alternative scenarios live as sovereign data residency enforcement intensity and cloud provider energy vertical specialization depth evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Planned LNG Market
Oil & Gas
Well Cementing Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Drilling Services Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Middle East and Africa Coiled Tubing Market