
 Off-Highway Engine Market | 2026-2036
Off-Highway Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Engine Market Outlook
EPA Tier 4 Final and EU Stage V emissions certification is reorganizing competitive access across the off-highway engine landscape. Kubota Corporation leverages compact diesel expertise to dominate sub-75 hp segments in agricultural equipment. Caterpillar sustains its position through backward integration into fuel systems and aftertreatment hardware. Cummins anchors North American construction demand with modular engine platforms that span multiple equipment categories.
Off-highway engines are compression-ignition or spark-ignition power units purpose-built for mobile and stationary equipment operating outside public road networks, typically rated from 25 hp to over 750 hp with torque curves optimized for intermittent heavy loads. Diesel engines retain the largest installed base across mining vehicles and large construction machinery where energy density and refueling infrastructure remain critical. Hybrid engines represent the fastest-growing product type as OEMs face dual pressure from underground emissions rules and total cost-of-ownership scrutiny from fleet owners. Electric engines gain traction in stationary industrial equipment and confined-site applications where grid access exists.
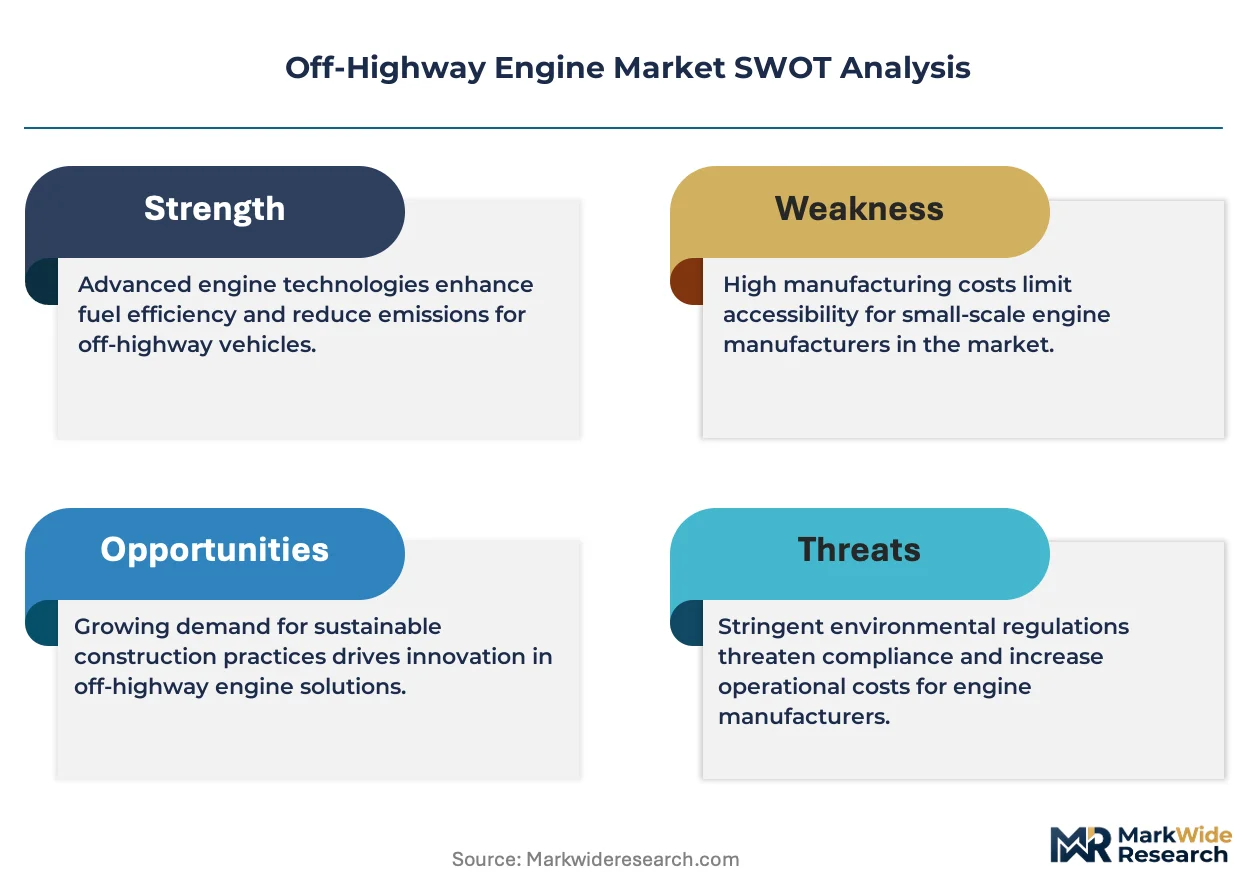
EPA, the EU's F-Gas Regulation, and China's MEE enforce diverging but equally stringent pollutant caps that fragment product portfolios and extend development cycles. Engine manufacturers must now certify platforms across multiple regulatory jurisdictions simultaneously, raising fixed costs and favoring scaled producers. Stakeholders should monitor how battery-hybrid architectures displace pure diesel in medium-duty construction and agricultural segments as charging infrastructure spreads beyond urban cores.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are forcing simultaneous powertrain redesigns across construction, agriculture, and mining equipment, compressing development cycles while multiplying certification costs for engine manufacturers.
Growth Catalysts
- Underground Mining Emissions Caps:MEE regulations in China and EPA mandates in the US are accelerating diesel-electric hybrid adoption in confined extraction environments where ventilation costs dominate operating economics.
- India:The country's national infrastructure regulator has approved $1.4 trillion in capital projects through 2030, pulling demand for 75-300 hp engines in earthmoving and road construction equipment.
- Aftertreatment Integration:Compact selective catalytic reduction systems are enabling sub-75 hp engines to meet Stage V without bulky external hardware, opening agricultural mechanization in emission-sensitive European markets.
Market Restraints
- Platinum Group Metal Volatility:Diesel oxidation catalysts and particulate filters require palladium and platinum inputs whose price swings compress margin predictability for aftertreatment suppliers.
- High-Pressure Common Rail Supply Concentration:Precision fuel injection systems for 150+ hp engines concentrate among three German and Japanese component specialists, creating single-source vulnerability.
- Battery Energy Density Ceiling:Lithium-ion packs at 250-300 Wh/kg remain insufficient for 12-hour continuous duty cycles in large mining haulers, preserving diesel lock-in despite total-cost pressures.
Strategic Opportunities
- Brazil:ANVISA-aligned agricultural safety standards and expanding soy mechanization create unmet demand for 50-100 hp Tier 3-compliant engines as domestic manufacturing capacity lags replacement needs.
- Grid-Tethered Stationary Power:Permanent magnet synchronous motors with onboard inverters are penetrating compressor and pump applications in North American oilfield services where shore power availability is expanding.
- EU Green Deal Industrial Emissions Directive:The framework's 2030 interim targets for non-road mobile machinery are accelerating fleet renewal incentives in German and French rental equipment channels.
Industry Challenges
- Embedded Software Validation:Engine control unit codebases now exceed 10 million lines for Tier 4 Final compliance, stretching verification teams and delaying platform launches.
- Dual-Certification Parallelism:Manufacturers must simultaneously validate engines for EPA, EU Stage V, and China's MEE Type I standards, tripling homologation engineering headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Engine Market |
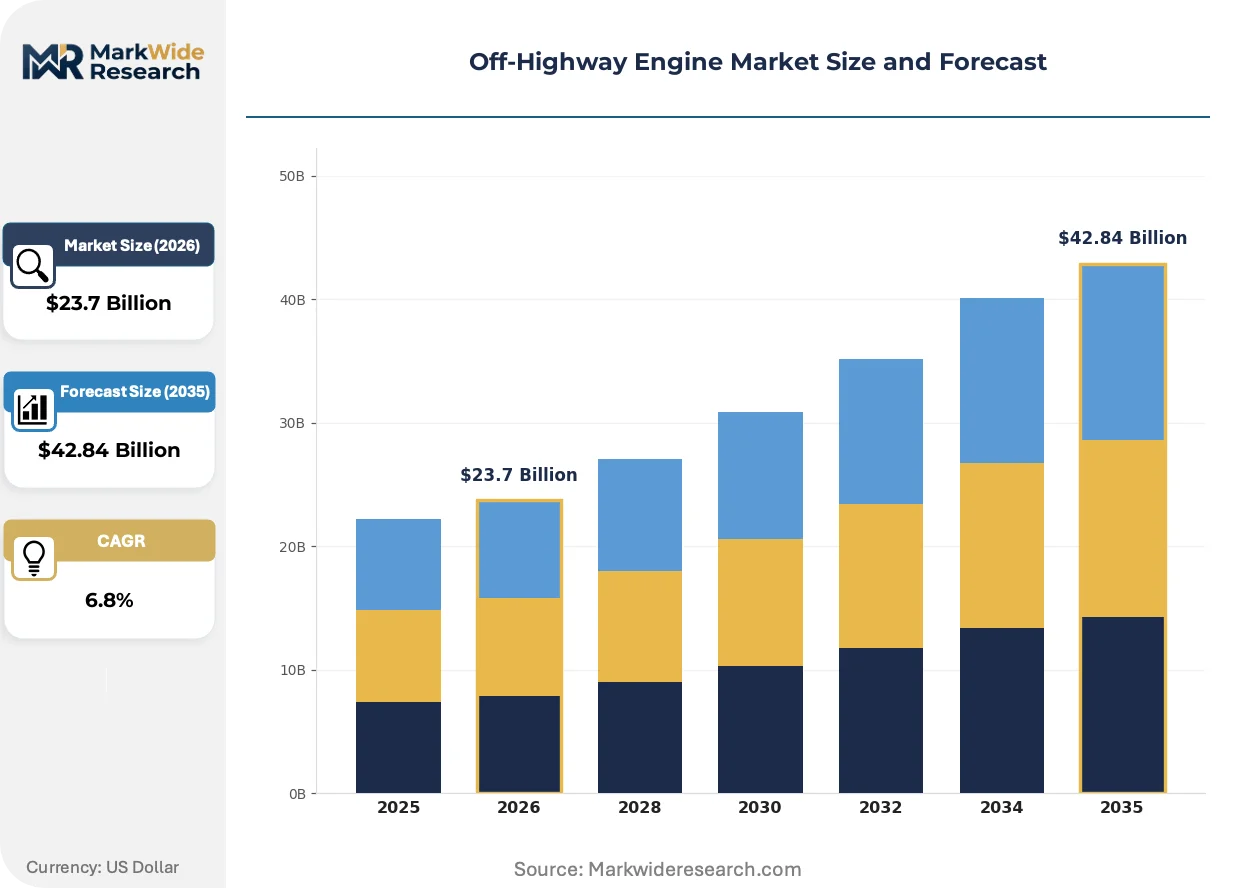
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Engines, Natural Gas Engines, Electric Engines, Hybrid Engines Application: Agriculture Equipment, Construction Machinery, Mining Vehicles, Industrial Equipment End User: OEMs, Fleet Owners, Rental Services, Aftermarket Providers Installation: Stationary, Mobile, Portable, Integrated |
| Companies Covered | Kubota Corporation, John Deere, Caterpillar, Weichai Power, Yanmar, Cummins, Volvo Group, AGCO Corporation, Deutz AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Engine Market Strategic Shifts
Modular hybrid architectures and digital powertrain management are compressing the traditional diesel-engine value chain, enabling new entrants to compete without legacy manufacturing scale.
Modular battery-diesel hybrid powertrains are decomposing the historical link between engine displacement and equipment productivity. Underground mining OEMs in Canada and Australia are adopting 48V mild-hybrid systems at the fastest clip, enabling smaller prime movers to deliver equivalent tractive effort through electric boost. This architecture is decomposing the traditional supplier hierarchy by allowing battery integrators to capture value previously held by engine manufacturers.
REACH and the EU F-Gas Regulation are tightening refrigerant and lubricant specifications for off-highway engines operating in European protected zones. Industrial consequence includes mandatory biodegradable hydraulic fluids and sealed crankcase ventilation systems in equipment deployed near water tables. Agricultural tractors above 175 hp face the steepest compliance cost escalation, driving consolidation among smaller European equipment brands.
Fleet data monetization is restructuring how construction and mining operators evaluate powertrain investments. Equipment managers now prioritize telematics-ready engines that feed predictive maintenance platforms, displacing historical reliance on dealer service networks for uptime assurance. This pattern concentrates in Australian iron ore operations and US shale basins where unplanned downtime costs exceed $15,000 per hour.
Off-Highway Engine Market Segmentation
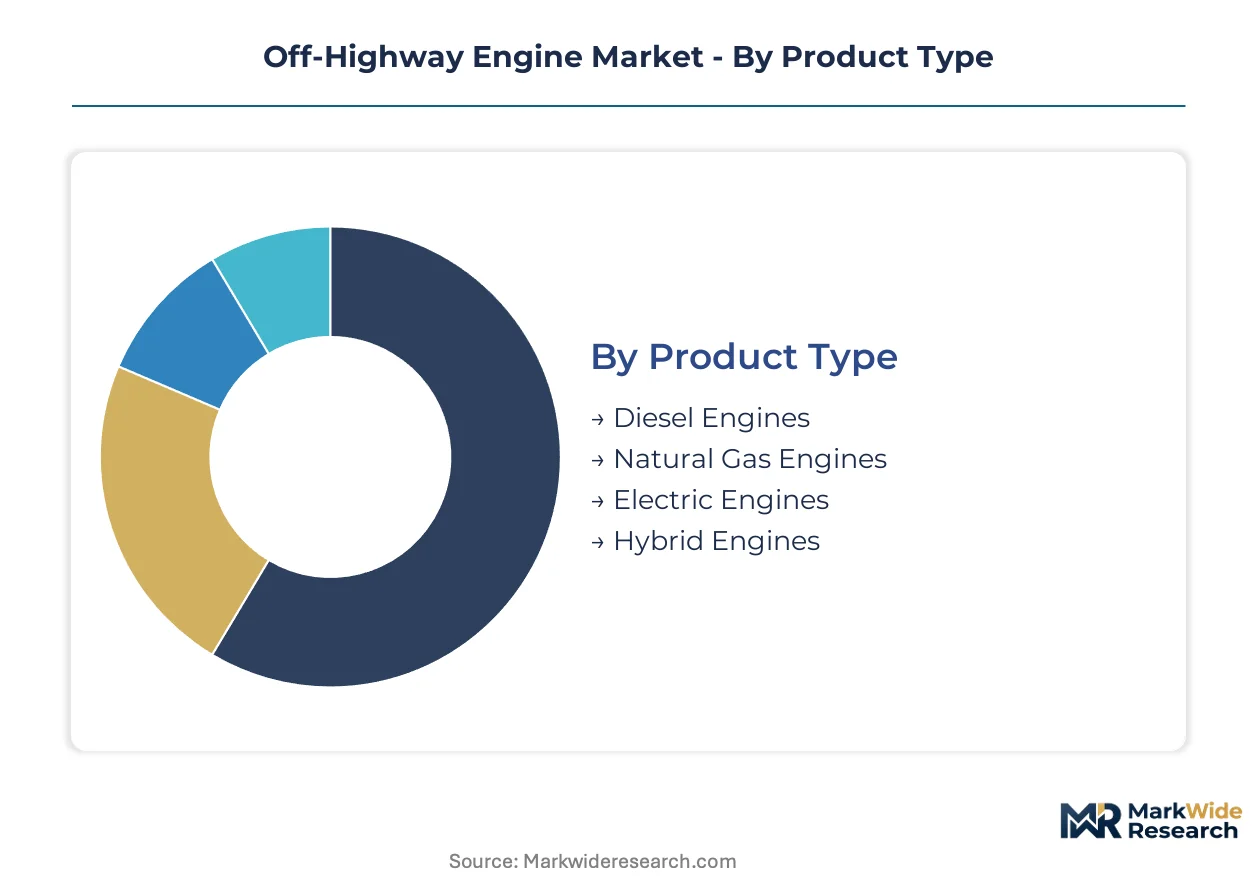
Segmentation in off-highway engines reveals how powertrain specifications align with equipment duty cycles and regulatory exposure. Channel dynamics vary sharply across product types and installation modes.
Product Type:
Diesel and hybrid power units flow through OEM captive channels and independent distributors, while electric engines concentrate in direct fleet sales where charging infrastructure planning is required.
- Diesel Engines:Compression-ignition power units from 25 hp to 750+ hp with high-pressure common rail injection and integrated aftertreatment. Demand concentrates in Chinese mining operations and Indian road construction where refueling infrastructure and 12-hour continuous duty cycles predominate. EPA Tier 4 Final compliance costs have compressed margin pools for sub-75 hp agricultural variants.
- Hybrid Engines:Modular battery-diesel architectures combining prime movers with 48V mild-hybrid or full-electric boost systems. Underground mining fleets in Canada and Australia are adopting these most aggressively to cut ventilation costs in confined extraction environments. Dual power paths allow smaller displacement engines to maintain tractive performance.
- Electric Engines:Permanent magnet synchronous motors with onboard inverters for grid-tethered or battery-electric operation. Stationary compressor and pump applications in North American oilfield services represent the primary pull.
- Natural Gas Engines:Spark-ignition power units adapted for compressed or liquefied methane fueling. Pipeline-adjacent stationary installations and select mining haulage corridors in the US and Australia show concentrated deployment.
Diesel engines dominate installed base. Hybrid engines are where expansion concentrates.
Application:
Equipment category determines power density requirements and emissions exposure, with construction machinery facing the steepest regulatory compliance cost escalation.
- Construction Machinery:Earthmoving, lifting, and compaction equipment requiring 75-300 hp engines with torque curves optimized for intermittent heavy loads. India's infrastructure buildout and China's urban renewal projects generate concentrated demand pull for this segment.
- Agriculture Equipment:Tractors, harvesters, and implements spanning sub-25 hp compact units to 300+ hp row-crop machines. European Stage V compliance has driven selective catalytic reduction integration into sub-75 hp engines, opening mechanization in emission-sensitive markets.
- Mining Vehicles:Surface and underground haul trucks, loaders, and drills operating in 12-hour continuous cycles. Diesel-electric hybrid adoption accelerates fastest in Canadian and Australian underground operations where ventilation energy costs dominate operating economics.
- Industrial Equipment:Stationary compressors, pumps, and generators with fixed installation requirements. Grid-tethered electric motors penetrate this segment most deeply where shore power availability expands.
Construction machinery commands the largest revenue pool. Mining vehicles show the steepest technology shift trajectory.
End User:
Procurement authority determines specification complexity, with OEMs driving platform standardization and fleet owners prioritizing total-cost-of-ownership metrics.
- OEMs:Original equipment manufacturers integrating engines into complete machines, wielding volume leverage to enforce modular platform compliance across multiple equipment categories. Caterpillar and Cummins anchor this channel with backward-integrated fuel system and aftertreatment capabilities.
- Fleet Owners:Construction, mining, and agricultural operators purchasing engines for replacement or fleet expansion. Telematics integration and predictive maintenance readiness now dominate procurement criteria in Australian iron ore and US shale basins.
- Rental Services:Equipment leasing companies prioritizing uptime assurance and standardized maintenance protocols. EU Green Deal fleet renewal incentives in German and French rental channels accelerate replacement demand.
- Aftermarket Providers:Independent rebuilders and remanufacturers serving equipment life extension demand. Brazil's lagging domestic manufacturing capacity creates unmet replacement engine demand for 50-100 hp Tier 3-compliant units.
OEMs control specification authority. Fleet owners are driving telematics penetration fastest.
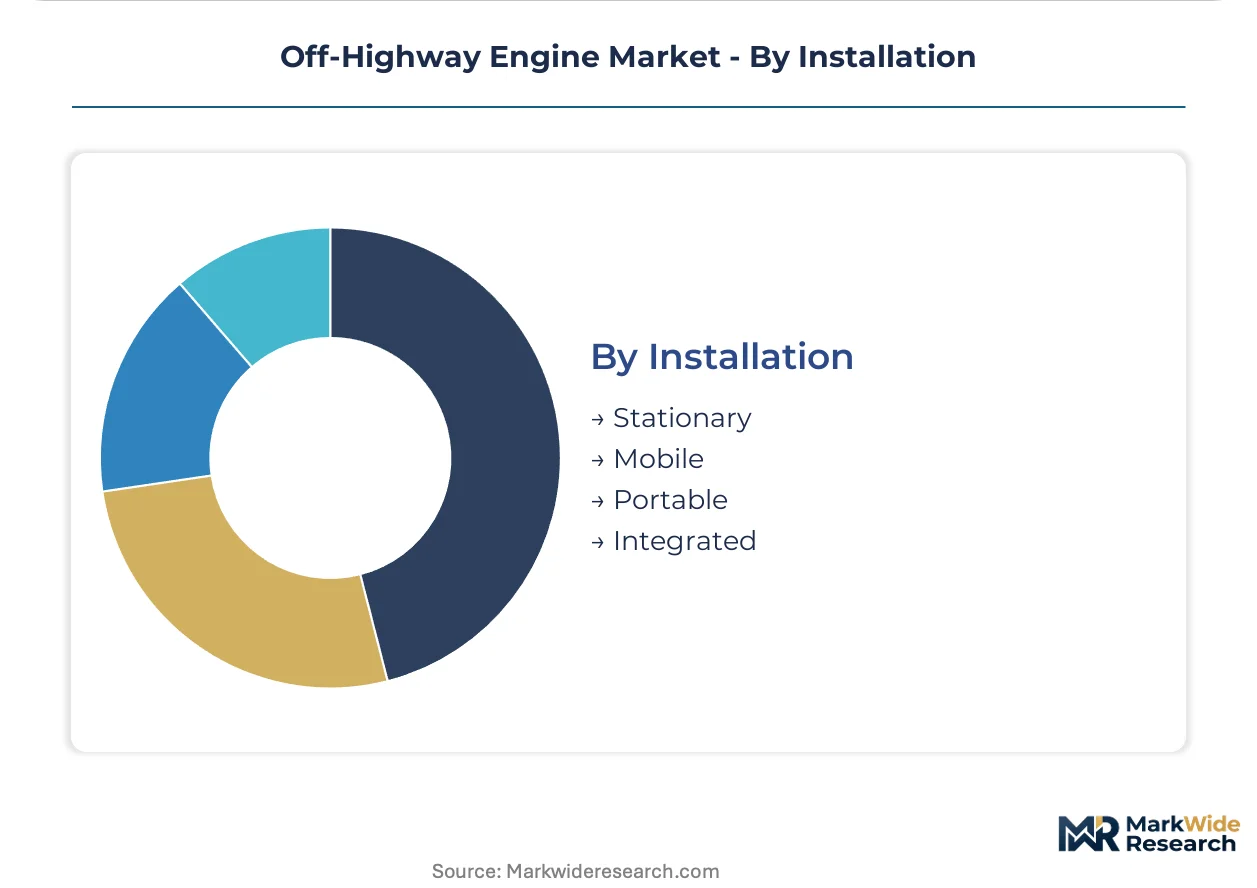
Installation:
Physical mounting configuration determines cooling architecture, emissions exposure, and service access patterns across the value chain.
- Mobile:Self-propelled equipment with onboard power units subject to full EPA, EU Stage V, and China MEE emissions certification. Construction and mining machinery represent the core demand concentration.
- Stationary:Fixed-site installations including compressors, pumps, and generators with grid connection options. Oilfield services in North America show expanding shore power availability enabling electric motor substitution.
- Portable:Trailer-mounted or skid-mounted equipment requiring rapid deployment capability. Emergency power and temporary construction applications sustain diesel dominance despite electrification pressure.
- Integrated:Power units embedded within specialized machinery with custom mounting and cooling interfaces. OEM-engine collaboration is tightest in this configuration, favoring scaled producers with application engineering depth.
Mobile installations retain volume leadership. Stationary configurations are gaining electric share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao Port intermodal terminal connects inland manufacturing clusters to global equipment markets, cementing China's position as the primary demand center for high-displacement diesel and hybrid power units.
China
Infrastructure investment through the national development bank funds earthmoving fleet expansion across 75-300 hp segments. MEE Type I emissions standards force simultaneous engine redesigns with selective catalytic reduction integration. Shandong Province manufacturing corridors near Weifang concentrate domestic engine production capacity serving both domestic OEMs and export markets.
United States
Shale basin oilfield services and iron ore mining operations in Minnesota's Mesabi Range sustain demand for 12-hour continuous duty cycle engines. EPA Tier 4 Final mandates compress development timelines for construction and agricultural equipment powertrains. The Permian Basin in Texas anchors stationary compressor applications where grid-tethered electric motors gain share alongside diesel backup systems.
Germany
EU Stage V compliance costs drive agricultural tractor fleet renewal above 175 hp, with rental equipment channels absorbing premium-engine inventory. The EU Green Deal Industrial Emissions Directive accelerates replacement incentives through 2030 interim targets. Baden-Württemberg engineering clusters around Stuttgart supply precision fuel injection components to global engine manufacturers.
India
National infrastructure regulator capital commitments of $1.4 trillion through 2030 pull demand for earthmoving and road construction equipment powertrains. Central Pollution Control Board Bharat Stage V-equivalent norms for non-road mobile machinery tighten particulate limits. Gujarat industrial corridors near Ahmedabad concentrate domestic equipment manufacturing requiring 75-300 hp engine supply.
Australia
Underground hard-rock mining operations in Western Australia's Pilbara region adopt diesel-electric hybrid systems to cut ventilation energy costs. State-level mine safety regulators enforce confined-space emissions caps that accelerate 48V mild-hybrid adoption. Queensland coal basins sustain surface haul truck demand where battery energy density limitations preserve diesel lock-in for 12-hour duty cycles.
Off-Highway Engine Market Competitive Environment
Listed leaders compete with private specialists across aftertreatment integration and modular platform development. The market structure concentrates around scaled producers with captive fuel system capabilities and tiered component suppliers serving regional equipment manufacturers. Three archetypes dominate: backward-integrated OEMs controlling fuel injection and emissions hardware, independent engine specialists licensing modular architectures across equipment categories, and hybrid system integrators capturing value from battery-diesel powertrain decomposition. Competitive moves center on dual-certification engineering capacity expansion and telematics-ready control unit development.
Within the backward-integrated tier, Kubota Corporation and Caterpillar exemplify archetypes of compact diesel expertise and full-system integration respectively. Cummins occupies a position as the independent specialist anchoring North American construction demand through modular platform strategies. These three entities represent the dominant competitive anchors against which hybrid entrants and regional challengers position alternative powertrain architectures.
| Leading Market Players |
|---|
| Kubota Corporation |
| John Deere |
| Caterpillar |
| Weichai Power |
| Yanmar |
| Cummins |
| Volvo Group |
| AGCO Corporation |
| Deutz AG |
| Others |
Value Chain & Pricing Dynamics
Ninety-day platinum group metal inventory cycles at aftertreatment suppliers compress margin buffers when palladium spot prices spike, concentrating pricing power among German and Japanese fuel injection specialists who control 150+ hp high-pressure common rail supply. OEM procurement teams face asymmetric leverage: scaled producers like Caterpillar and Cummins negotiate volume discounts on modular platforms while regional equipment manufacturers absorb premium pricing for low-volume Tier 4 Final certification.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA Tier 4 Final-certified engines with integrated selective catalytic reduction from Tier 3-compliant units for export markets and remanufactured alternatives. Price differentiation hinges on certification grade and after-sales service bundling, with OEM captive channels commanding 15-20% premiums over independent distributors. Cost compression in sub-75 hp agricultural variants intensifies because platinum group metal volatility in diesel oxidation catalysts erodes supplier margins. Fleet owners in Australian iron ore operations show least price sensitivity due to $15,000-per-hour downtime costs, while Brazilian aftermarket providers face acute margin pressure from lagging domestic manufacturing capacity.
Supply Chain Analysis
Strait of Malacca transit routes carry 60% of global rare earth shipments for permanent magnet synchronous motors, creating chokepoint exposure for electric engine producers targeting North American oilfield services. Manufacturing concentrates in China, Germany, and Japan, with Shandong Province engine corridors and Baden-Württemberg precision component clusters anchoring respective supply bases. Raw material dependencies span palladium for oxidation catalysts, neodymium for traction motors, and high-grade steel for common rail injection systems. Single-source vulnerability in high-pressure common rail supply among three specialists amplifies disruption risk. Distribution runs through OEM captive channels for diesel and hybrid platforms, while electric engines flow direct to fleet operators requiring charging infrastructure coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Off-highway engine incumbents face sustained substitution pressure from battery-hybrid architectures as 48V mild-hybrid systems decompose traditional value capture. Defense requires strategic consolidation around certification capacity and aftertreatment integration.
For Market Incumbents: Consolidate backward integration into fuel systems and emissions hardware to defend margin pools against modular hybrid entrants. Lock in dual-certification engineering capacity for simultaneous EPA Tier 4 Final, EU Stage V, and China MEE validation. Prioritize telematics-ready control unit development to capture fleet data monetization revenue streams displacing dealer service networks. For New Entrants and Emerging Players: Aftermarket service gaps in Brazil's Tier 3-compliant engine replacement market offer immediate white-space access where domestic manufacturing lags soy mechanization demand. Target grid-tethered stationary power applications in Permian Basin oilfield services where shore power expansion enables electric motor substitution. Pursue battery-diesel hybrid integration partnerships with underground mining OEMs in Western Australia's Pilbara region, leveraging 48V architecture to bypass scale disadvantages in prime mover manufacturing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded off-highway engine divisions lacking hybrid R&D investment. Long-term viability hinges on exposure to electrification-ready segments rather than pure diesel lock-in. Monitor battery energy density progression as the critical inflection signal: sustained ceiling above 300 Wh/kg would accelerate displacement in 12-hour mining hauler duty cycles currently preserving diesel dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Engineering Expansion | Simultaneous EPA Tier 4 Final and EU Stage V validation compresses development timelines for construction equipment OEMs. |
| Aftertreatment Hardware Backward Integration | Captive selective catalytic reduction production insulates margin pools from platinum group metal price volatility. |
| Telematics Platform Development | Predictive maintenance readiness displaces historical dealer service revenue in Australian iron ore operations. |
| Hybrid System Joint Venture | Battery-diesel architecture partnerships enable smaller prime movers to match tractive performance in underground mining. |
| Brazilian Aftermarket Channel Buildout | Tier 3-compliant engine distribution addresses unmet replacement demand from ANVISA-aligned agricultural safety standards. |
Study Parameters
A spread of perspectives from engine platform directors, OEM procurement teams, aftermarket service heads, and fleet maintenance managers converged on the working assumptions driving segment-level demand projections. Primary fieldwork combined structured interviews with secondary validation through EPA certification databases, EU Type Approval records, China MEE emission standard filings, and customs trade data on engine component flows. Bottom-up equipment production forecasts triangulated against top-down infrastructure investment commitments from India's national regulator and China's national development bank.
Segmentation dimensions modeled span product type (diesel, hybrid, electric, natural gas), application category (construction machinery, agriculture equipment, mining vehicles, industrial equipment), end-user archetype (OEMs, fleet owners, rental services, aftermarket providers), and installation configuration (mobile, stationary, portable, integrated). CAGRs derived from regression analysis against historical equipment production data, infrastructure capital deployment schedules, and regulatory phase-in timelines. Industry-specific forecast inputs include underground mining ventilation cost curves and lithium-ion battery energy density progression assumptions.
Forecasts assume regulatory continuity in EPA Tier 4 Final, EU Stage V, and China MEE Type I regimes; material policy shifts would require re-modeling demand trajectories across construction and agricultural segments. Practitioners should keep alternative scenarios live as battery-hybrid cost parity and charging infrastructure deployment patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
Off Highway Vehicle Lighting Market