
 Global Electric Off-Highway Equipment Market | 2026-2036
Global Electric Off-Highway Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Off-Highway Equipment Market Foresight
Heavy machinery contractors are rotating toward electrified fleets as mining corporations and agricultural enterprises scale back diesel procurement. Caterpillar Inc. leverages its integrated powertrain R&D to anchor North American demand for electric excavators. Komatsu Ltd. competes through deep specialization in battery-powered loaders for underground mining applications. Volvo Construction Equipment differentiates via its proprietary energy management systems that extend runtime in construction site deployments.
Electric off-highway equipment comprises self-propelled machinery operating outside public road networks, powered by electrochemical storage systems typically rated between 100 kWh and 600 kWh for heavy-duty cycles, designed to perform earthmoving, material handling, and lifting tasks without direct carbon emissions at the point of use. Battery-powered loaders and electric excavators command the dominant share of current revenue as infrastructure contractors prioritize zero-emission compliance on urban job sites. Solid state batteries represent the fastest-growing technology segment due to their energy density advantages for mining operations requiring extended duty cycles.
EPA tailpipe standards, EU Stage V emission regulations, and China's MIIT new-energy equipment mandates collectively restrict diesel-powered machinery access to regulated work zones, directly conditioning purchase eligibility for contractors serving public projects. OSHA and EU machinery safety directives further shape battery enclosure standards and high-voltage operator protection protocols. Stakeholders must monitor regulatory phase-in timelines and charging infrastructure interoperability standards to align fleet procurement with evolving compliance boundaries.
Market Dynamics
EPA Tier 4 Final and EU Stage V emission regulations are compressing diesel equipment residual values while battery energy density improvements above 300 Wh/kg unlock viable electrification for heavy-duty mining cycles previously considered unreachable for electrochemical powertrains.
Growth Catalysts
- Underground mining ventilation economics:Battery-powered loaders eliminate diesel particulate exposure, reducing ventilation infrastructure capex by 40-60% in deep shaft operations across Canada and Australia.
- MIIT new-energy equipment mandates:China's Ministry of Industry and Information Technology requires 30% electric penetration in construction machinery procurement for state-funded infrastructure projects by 2028.
- Renewable energy project bundling:Wind and solar developers specify zero-emission construction fleets as contract preconditions, pulling demand from Denmark, Germany, and California utility-scale sites.
Market Restraints
- Lithium carbonate price volatility:Cathode material cost swings above $30,000/tonne compress battery pack margins and delay OEM pricing stability.
- Charging infrastructure concentration:High-power depot charging equipment manufacturing clusters in South Korea and Japan create supply vulnerability for European and North American fleet operators.
- Energy density ceiling for solid-state:Current solid-state cell prototypes fail to achieve cycle life targets above 1,500 deep discharges required for 16-hour mining shifts.
Strategic Opportunities
- India's National Infrastructure Pipeline:$1.4 trillion in planned projects through 2030 lacks established electric equipment supply relationships, opening first-mover positioning for battery-swapping service models.
- Agricultural electrification gap:Electric tractors and harvesters remain under 2% penetration in Brazilian soybean operations, presenting whitespace for range-extended hybrid architectures.
- CE marking fast-track for remanufactured equipment:EU machinery directives increasingly recognize battery retrofits as new product categories, accelerating diesel-to-electric conversion pathways for mid-life asset owners.
Industry Challenges
- High-voltage technician scarcity:OEMs and contractors compete for electricians certified to 1,000V DC battery systems, with training programs lagging deployment timelines by 18-24 months.
- Multi-standard charging interoperability:CCS, CHAdeMO, and emerging megawatt charging system (MCS) protocols create fleet configuration complexity for cross-border operators in Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Off-Highway Equipment Market |
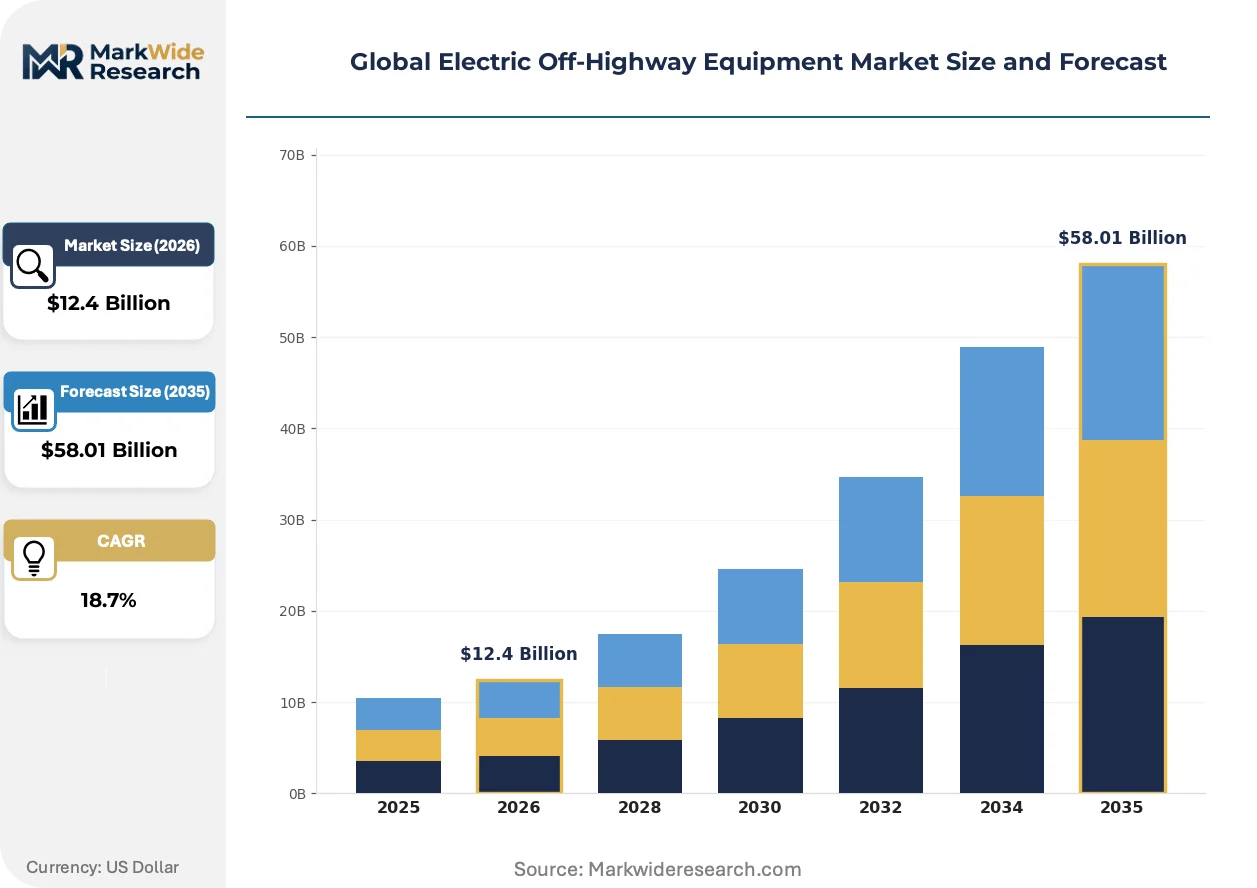
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Excavators, Battery-Powered Loaders, Electric Forklifts, Electric Tractors, Electric Cranes Technology: Li-Ion Batteries, Nickel-Metal Hydride, Lead Acid, Supercapacitors, Solid State Batteries Application: Construction Sites, Mining Operations, Agriculture Fields, Material Handling Yards, Forestry Sites End User: Heavy Machinery Contractors, Mining Corporations, Agricultural Enterprises, Warehousing Companies, Logging Firms |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Liebherr International AG, Hitachi Construction Machinery Co., Ltd., Deere & Company, SANY Heavy Industry Co., Ltd., Doosan Infracore, JCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Off-Highway Equipment Market Shifts & Advancements
Battery chemistry evolution and power electronics integration are compressing total cost of ownership gaps against diesel while regulatory compliance deadlines force accelerated fleet turnover decisions across mining and construction verticals.
Solid-state lithium-metal cells are displacing conventional NMC packs in underground mining equipment specifications due to intrinsic safety advantages and 40% volume reduction. Caterpillar and Komatsu validation programs target 2026-2027 production integration for 300-kWh class loaders. The technology is displacing liquid electrolyte architectures in premium equipment tiers where thermal runaway tolerance commands price premiums.
EU Stage V and EPA Tier 4 Final tailpipe limits are tightening particulate matter and NOx thresholds to near-zero levels, rendering aftertreatment complexity uneconomical for sub-75hp equipment classes. German and Italian municipalities now ban pre-Stage V machinery from urban construction zones. Underground mining operations in Poland and Sweden are responding with accelerated battery-electric procurement to avoid ventilation system upgrades.
Rental and leasing channels are capturing electric off-highway equipment demand as contractors defer ownership risk during technology transition periods. United Rentals and Loxam are expanding electric fleet allocations to 15-20% of construction equipment portfolios. This shift concentrates most visibly in California and Netherlands urban infrastructure projects where emission compliance guarantees are contractually mandated.
Global Electric Off-Highway Equipment Market Segmentation
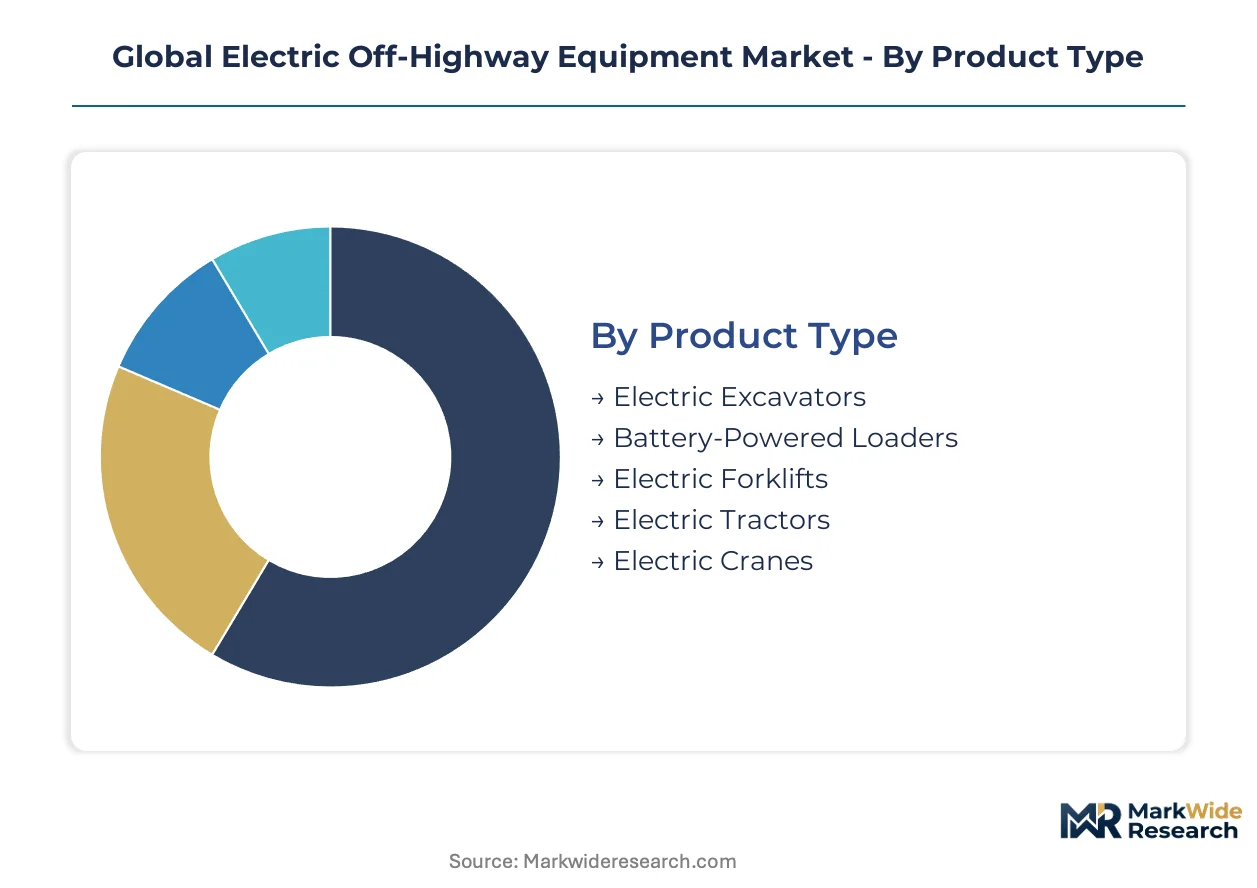
Equipment electrification paths diverge sharply across duty cycles and energy density requirements. Segmentation reveals which machinery categories face imminent diesel displacement versus those where battery economics remain marginal.
Product Type:
Battery-powered loaders face the most acute substitution pressure as underground mining ventilation costs render diesel economically unviable, while electric tractors confront the steepest energy density barriers for extended field operations.
- Battery-Powered Loaders:Underground mining specifications demand 300-600 kWh packs operating in confined ventilation-constrained environments. Canadian and Australian hard-rock operations now mandate zero-emission fleets for new shaft developments, eliminating diesel particulate exposure while cutting ventilation infrastructure investment by 40-60%.
- Electric Excavators:Urban construction deployment dominates, with 100-300 kWh systems optimized for intermittent duty cycles and opportunity charging. German municipalities and California transit agencies specify zero-emission excavation equipment for public infrastructure contracts, pulling OEM development resources toward this segment.
- Electric Forklifts:Warehouse and logistics yard applications with predictable routes and overnight depot charging. Material handling yards in Netherlands and Denmark achieve full electrification through standardized battery form factors.
- Electric Cranes:Port and heavy-lift applications requiring stationary grid connection or massive onboard storage. Grid-tethered configurations dominate European container terminals.
- Electric Tractors:Agricultural field operations with seasonal intensity and remote charging constraints. Brazilian soybean and Midwest US corn operations remain diesel-dependent due to range requirements.
Battery-powered loaders anchor the volume base while electric excavators gain share at the steepest rate.
Technology:
Cost tier stratification separates premium solid-state architectures from commoditized lead-acid systems, with chemistry selection directly determining applicable duty cycles and end-use eligibility.
- Solid State Batteries:Lithium-metal cells with ceramic electrolytes achieve 40% volume reduction and intrinsic thermal stability. Caterpillar and Komatsu validation programs target underground mining integration where safety premiums justify cost multiples over conventional packs.
- Li-Ion Batteries:NMC and LFP chemistries dominate current production, with energy density improvements above 300 Wh/kg unlocking heavy-duty construction applications previously considered uneconomical for electrification.
- Nickel-Metal Hydride:Declining share in material handling equipment as lithium-ion costs compress. Limited to legacy forklift fleets with replacement battery procurement.
- Supercapacitors:High-power burst applications in hybrid excavators requiring rapid charge acceptance during deceleration events. Japanese port machinery trials demonstrate cycle life advantages.
- Lead Acid:Cost-minimized stationary applications and emerging market price-sensitive procurement. Indian construction rental fleets utilize for short-duty equipment classes.
Li-ion systems capture the dominant installed base while solid-state configurations expand most quickly in premium mining specifications.
Application:
Geographic regulatory intensity shapes application-level electrification sequencing, with emission-controlled urban zones forcing conversion ahead of remote rural operations.
- Mining Operations:Underground hard-rock and potash extraction in Canada, Poland, and Sweden drive battery-electric procurement to avoid ventilation system upgrades mandated by EU Stage V and national occupational exposure limits.
- Construction Sites:Urban infrastructure projects in Germany, California, and Netherlands specify zero-emission fleets contractually. German municipalities ban pre-Stage V machinery from city centers.
- Material Handling Yards:Port terminals and distribution centers with predictable duty cycles and depot charging infrastructure. Danish and Netherlands logistics hubs achieve near-complete electrification.
- Agriculture Fields:Seasonal intensity and remote charging constraints limit penetration. Brazilian soybean and Australian wheat operations lack grid infrastructure for fleet-scale conversion.
- Forestry Sites:Remote access and high-power demands restrict current battery viability. Swedish and Finnish trials focus on tethered cable-electric systems for cut-to-length harvesters.
Construction sites generate the largest equipment procurement volume while mining operations demonstrate the steepest electrification trajectory.
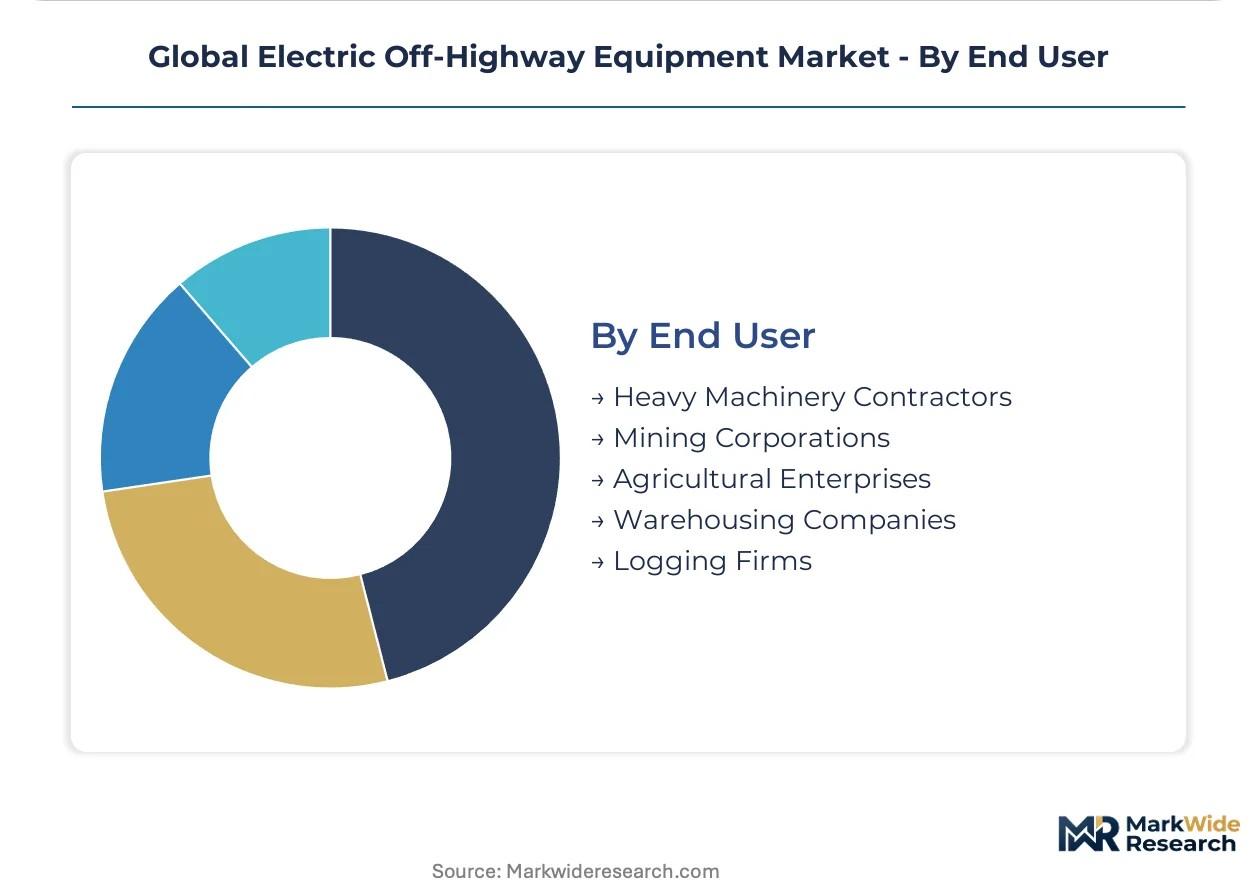
End User:
Customer scale and capital access determine electrification timing, with large corporate fleets converting ahead of fragmented owner-operator bases.
- Mining Corporations:BHP, Rio Tinto, and Glencore deploy capital for integrated ventilation and charging infrastructure. Australian and Canadian operations lead procurement with dedicated sustainability targets.
- Heavy Machinery Contractors:Public infrastructure specialists in Germany and California face contractual zero-emission mandates. Rental channel growth allows technology risk transfer to fleet lessors.
- Warehousing Companies:Amazon, DHL, and Maersk terminal operations standardize electric material handling through centralized procurement. Automated guided vehicle integration accelerates pack standardization.
- Agricultural Enterprises:Large cooperatives in Denmark and Netherlands trial electric tractors. Brazilian and US Midwest operations lack charging infrastructure for field-scale deployment.
- Logging Firms:Fragmented ownership and remote site access constrain conversion. Nordic cable-electric trials depend on utility partnership for grid extension.
Mining corporations anchor capital deployment while heavy machinery contractors expand procurement most rapidly through rental channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports electric excavators and battery-powered loaders to Germany, Australia, and Canada as mining corporations and infrastructure contractors accelerate diesel-to-electric fleet conversions. Equipment flows concentrate through Shanghai and Tianjin ports toward resource extraction hubs in Western Australia and Alberta.
China
State-funded infrastructure projects under MIIT mandates require 30% electric machinery procurement by 2028. SANY Heavy Industry and XCMG anchor production in Jiangsu and Shandong provinces, supplying domestic high-speed rail construction and exporting to Belt and Road sites in Southeast Asia and Africa.
Germany
Municipal zero-emission zones in Berlin, Munich, and Hamburg ban pre-Stage V diesel equipment from urban construction sites. The EU Green Deal and national KfW green financing programs subsidize electric excavator leasing for Mittelstand contractors, concentrating deployment in the Rhine-Ruhr industrial corridor.
United States
California Air Resources Board mandates and federal Buy Clean procurement policies drive electric loader adoption in Los Angeles and San Francisco transit projects. EPA Tier 4 Final enforcement compresses diesel residual values, pushing United Rentals and Sunbelt Rentals to expand electric allocations in Southwest infrastructure corridors.
Australia
BHP and Rio Tinto deploy battery-powered loaders in Western Australian iron ore and Queensland coal operations to eliminate diesel particulate exposure. The country's Work Health and Safety Act ventilation requirements make electric fleets economically superior in deep-shaft developments across the Pilbara and Bowen Basin.
Canada
Ontario and Quebec potash mining operations adopt electric equipment to avoid ventilation infrastructure upgrades under provincial occupational exposure limits. Toronto and Vancouver municipal contracts now specify zero-emission construction fleets, pulling demand through Canadian rental channels serving public transit expansion projects.
Global Electric Off-Highway Equipment Market Competitive Landscape
Player mix skews toward integrated industrial conglomerates with captive powertrain development capabilities. Market structure concentrates around three to five vertically anchored OEMs controlling battery pack integration and thermal management IP. Strategic archetypes separate into full-line diversified manufacturers, mining-specialized underground equipment builders, and regional cost-optimized fabricators. Dominant competitive moves include backward integration into cell supply partnerships and geographic expansion through rental channel alliances.
Within the diversified full-line tier, Caterpillar Inc. and Komatsu Ltd. occupy positions exemplifying integrated powertrain control, while Volvo Construction Equipment anchors the European energy management specialization vector. These three corporations represent contrasting geographic footprints and technical positioning without overlapping core competencies. Deere & Company and SANY Heavy Industry Co., Ltd. sit within the agricultural and emerging-market cost-optimized archetypes respectively, reflecting divergent customer access strategies. Hitachi Construction Machinery Co., Ltd. and Doosan Infracore exemplify Asia-Pacific regional concentration with mining-specific equipment heritage.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| Liebherr International AG |
| Hitachi Construction Machinery Co., Ltd. |
| Deere & Company |
| SANY Heavy Industry Co., Ltd. |
| Doosan Infracore |
| JCB |
| Others |
Supply & Pricing Matrix
Solid-state battery chemistry substitution for conventional NMC packs simultaneously relocates cathode procurement toward South Korean and Japanese material refiners while compressing pricing premiums for thermal-runaway-safe configurations in underground mining specifications.
Pricing Analysis
Next-generation solid-state pricing premiums over current Li-ion NMC systems and prior-generation lead-acid architectures stratify across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation stems from UL 2580 battery safety certification requirements and OEM captive powertrain integration depth. Cost compression in economy-tier lead-acid replacements is intensifying because Chinese manufacturers are expanding export capacity for construction rental fleets. Mining corporations demonstrate the least price sensitivity due to ventilation cost avoidance, while Indian infrastructure contractors exhibit acute sensitivity to upfront capital outlays.
Supply Chain Analysis
High-power charging equipment manufacturing chokepoints in South Korea and Japan tether European and North American fleet operators to concentrated supplier bases for depot infrastructure. Cell production draws from China, South Korea, and Japan, with lithium carbonate and cobalt sulfate as critical cathode material dependencies. Single-source vulnerability in ceramic electrolyte substrates for solid-state architectures threatens production scaling timelines. Distribution runs through Shanghai and Tianjin port clusters toward Western Australian mining hubs and German construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric off-highway equipment constitutes a high-growth disruption as EPA Tier 4 Final and EU Stage V regulations compress diesel residual values below economic repair thresholds, forcing accelerated fleet turnover across mining and construction verticals.
For Market Incumbents: Fortify captive battery pack integration through backward integration into cell supply partnerships with South Korean and Japanese cathode material suppliers. Secure thermal management IP against emerging Chinese OEM cost-optimized entrants by accelerating solid-state validation programs for 300-kWh class underground loaders.
For New Entrants and Emerging Players: Lead with battery-swapping service models targeting India's National Infrastructure Pipeline where electric equipment supply relationships remain unestablished. Agricultural electrification gaps in Brazilian soybean operations present the most penetrable whitespace for range-extended hybrid tractor architectures deployed through equipment-as-a-service contracting.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated powertrain specialists with captive charging infrastructure partnerships. Long-term viability over the next decade rests on solid-state chemistry commercialization timelines and regulatory enforcement consistency across EU Stage V and EPA Tier 4 Final jurisdictions. Monitor lithium carbonate price volatility as the critical inflection signal for battery pack margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Caterpillar and Komatsu secure South Korean lithium supply chains against price volatility. |
| Battery-Swapping Infrastructure Deployment | First-mover positioning in India's infrastructure corridor bypasses charging grid limitations. |
| Solid-State Validation Acceleration | Underground mining safety premiums justify cost multiples over conventional NMC architectures. |
| Rental Channel Alliance Expansion | United Rentals and Loxam transfer technology risk from contractors to fleet lessors. |
| CE Marking Fast-Track for Retrofits | EU machinery directives recognize battery retrofits as new product categories for mid-life assets. |
Research Methodology
A spread of perspectives from OEM powertrain engineers, mining fleet procurement directors, rental channel operations managers, and construction contractor project leads converged on the working assumptions through structured primary interviews validated against secondary sources including EPA enforcement databases, EU Stage V certification registries, MIIT procurement mandate disclosures, and customs trade flow records. Bottom-up equipment shipment tallies triangulated against top-down market sizing derived from mining corporation capital expenditure disclosures and infrastructure project pipeline databases.
Segmentation dimensions modeled span equipment type, battery chemistry architecture, application duty cycle intensity, end-user scale category, and regional regulatory framework cluster across the projection horizon. CAGRs were derived from equipment replacement cycle analysis, diesel residual value compression trajectories, and battery energy density improvement curves. Forecast inputs incorporated ventilation infrastructure cost avoidance economics for underground mining and municipal zero-emission zone enforcement schedules.
Underlying assumptions cover regulatory phase-in consistency, lithium carbonate supply elasticity, and charging infrastructure deployment rates, with deviation risk concentrated in solid-state cycle life achievement timelines and multi-standard charging protocol interoperability. Practitioners should keep alternative scenarios live as EPA enforcement intensity and EU Green Deal subsidy allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Global Automotive Off Highway Engine Market