
 Off-Highway Actuators Market | 2026-2036
Off-Highway Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Actuators Market Analytics
Equipment leasing and project finance for autonomous construction fleets is reconfiguring capital deployment across the off-highway actuator supply base. Parker Hannifin Corporation leverages its integrated motion control portfolio to serve rental fleet operators seeking standardized actuator architectures. Bosch Rexroth AG anchors European supply through its deep manufacturing footprint in linear drives and electrohydraulic systems. SKF Motion Technologies differentiates via precision rotary bearing integration with smart actuator modules for predictive maintenance contracts.
Off-highway actuators are electromechanical, hydraulic, or pneumatic devices that convert energy into controlled linear or rotary motion, typically delivering forces from 500 N to over 500 kN with positioning accuracy within ±0.1 mm for precision agriculture and mining applications. Their primary purpose is to enable remote or automated control of implements, booms, and drivetrain components in vehicles operating beyond regulated road networks. Electric actuators now lead product type demand as construction and agriculture OEMs pursue fuel efficiency targets and simplified maintenance intervals. Smart actuators with embedded position sensing and CAN bus connectivity represent the fastest-growing technology segment, commanding margin premiums through reduced wiring complexity and real-time diagnostics capability.
The EPA Tier 4 Final and EU Stage V emissions frameworks restrict diesel particulate output from off-highway engines, indirectly compelling actuator electrification to reduce parasitic hydraulic pump loads. ISO 25119 safety standards for agricultural machinery mandate redundant position feedback in steering and implement control systems, creating compliance-driven replacement cycles. OSHA and MSHA guidelines for mining equipment operator protection further specify fail-safe actuator behavior in emergency stop scenarios. Stakeholders must monitor evolving battery-electric vehicle architectures in construction equipment, as high-voltage platforms will demand isolated actuator designs and new supplier qualification pathways.
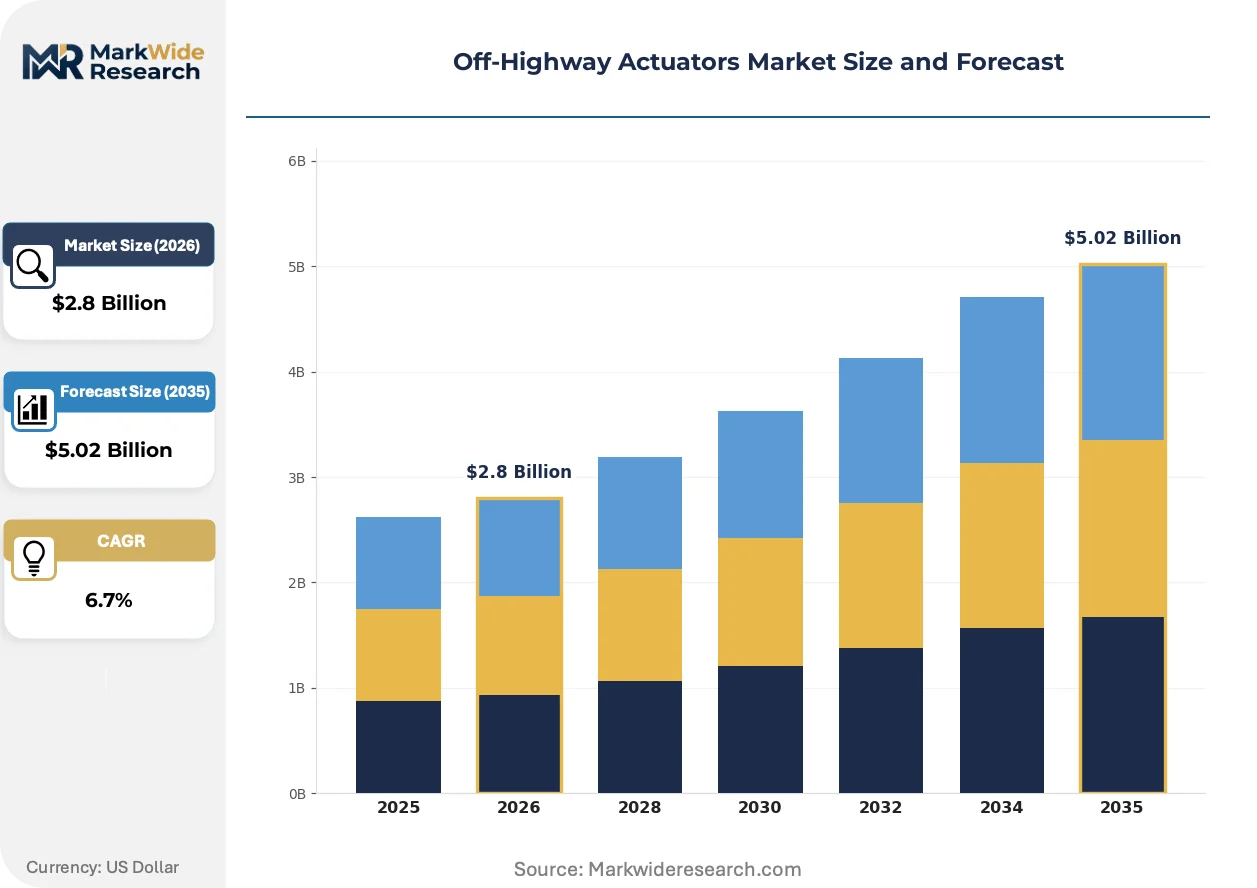
Market Dynamics
Electric actuation architectures are compressing the installed base of hydraulic systems across construction and agriculture equipment fleets, as OEMs redesign implement control around high-voltage platforms and integrated motion electronics.
Growth Catalysts
- Stage V compliance deadlines:European emissions frameworks mandate particulate reduction, forcing diesel-dependent hydraulic pumps toward electrified alternatives.
- Autonomous grading systems:Construction machinery OEMs require precision linear motion for machine-controlled blade positioning in earthmoving applications.
- German manufacturing clusters:Concentrated actuator production around Stuttgart and Lohr am Main accelerates supplier qualification cycles for Tier 1 integrators.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings destabilize electric actuator bill-of-materials forecasting for high-force linear drives.
- Hydraulic incumbent concentration:Mature service networks and technician familiarity with fluid power systems slow fleet conversion timelines in North American rental markets.
- Thermal management limitations:Continuous-duty cycle applications in underground mining exceed current IP69K-rated electric actuator heat dissipation capacity.
Strategic Opportunities
- India agricultural mechanization:Tractor OEMs seek cost-optimized smart actuators for precision seeding and variable-rate fertilization in Punjab and Haryana.
- Battery-electric construction equipment:High-voltage architectures eliminate engine-driven hydraulic pumps, creating demand for isolated electromechanical implement controls.
- CANopen over EtherCAT convergence:Unified industrial Ethernet protocols enable single-cable actuator networks with embedded diagnostics for predictive maintenance contracts.
Industry Challenges
- Mechatronics skill scarcity:Field service technicians trained in hydraulic troubleshooting lack competency in motor drive tuning and encoder calibration.
- ISO 25119 certification timelines:Agricultural machinery safety validation for redundant position feedback extends product development cycles by months.
- Legacy controller integration:Proprietary CAN bus implementations in existing equipment fleets resist standardization to open protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Actuators Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators End User: Agriculture Equipment, Construction Machinery, Mining Equipment, Forestry Equipment Application: Control Systems, Automation, Steering Mechanisms, Safety Systems Technology: Sensor-Based, Smart Actuators, Linear Technology, Rotary Technology |
| Companies Covered | Emerson Electric Co., Actuant Corporation, Parker Hannifin Corporation, Thomson Linear Motion Systems, Webtec Products Ltd., Bosch Rexroth AG, SMC Corporation, SKF Motion Technologies, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Actuators Market Evolving Landscape
Actuator intelligence is migrating from centralized controllers to edge-embedded systems, compressing wiring harness complexity while enabling real-time condition monitoring across distributed implement networks.
Integrated servo motors with hollow-shaft rotary actuators are collapsing the mechanical stack height in compact loader and skid-steer applications. Compact equipment OEMs in Japan and South Korea are adopting these units for boom and bucket curl functions. The elimination of separate gearbox and motor housings is collapsing envelope constraints that previously favored hydraulic cylinders in tight chassis layouts.
EPA Tier 4 Final enforcement is accelerating particulate filter regeneration strategies that increase parasitic engine load, indirectly rewarding electric actuation that removes hydraulic pump demand. Off-highway engine manufacturers are downsizing displacement to meet NOx limits, reducing available auxiliary power for conventional hydraulics. Mining and quarrying segments in the US Mountain West are responding with pilot deployments of electrohydraulic hybrids that preserve force density while cutting fuel consumption.
Fleet operators are unbundling actuator maintenance from full-machine service contracts, creating standalone predictive service agreements based on vibration and current-signature analytics. Rental companies with standardized actuator architectures across mixed fleets are displacing OEM-captive service networks. This pattern is most visible in German-speaking European markets where telematics penetration in construction equipment exceeds comparable North American deployments.
Off-Highway Actuators Market Segmentation
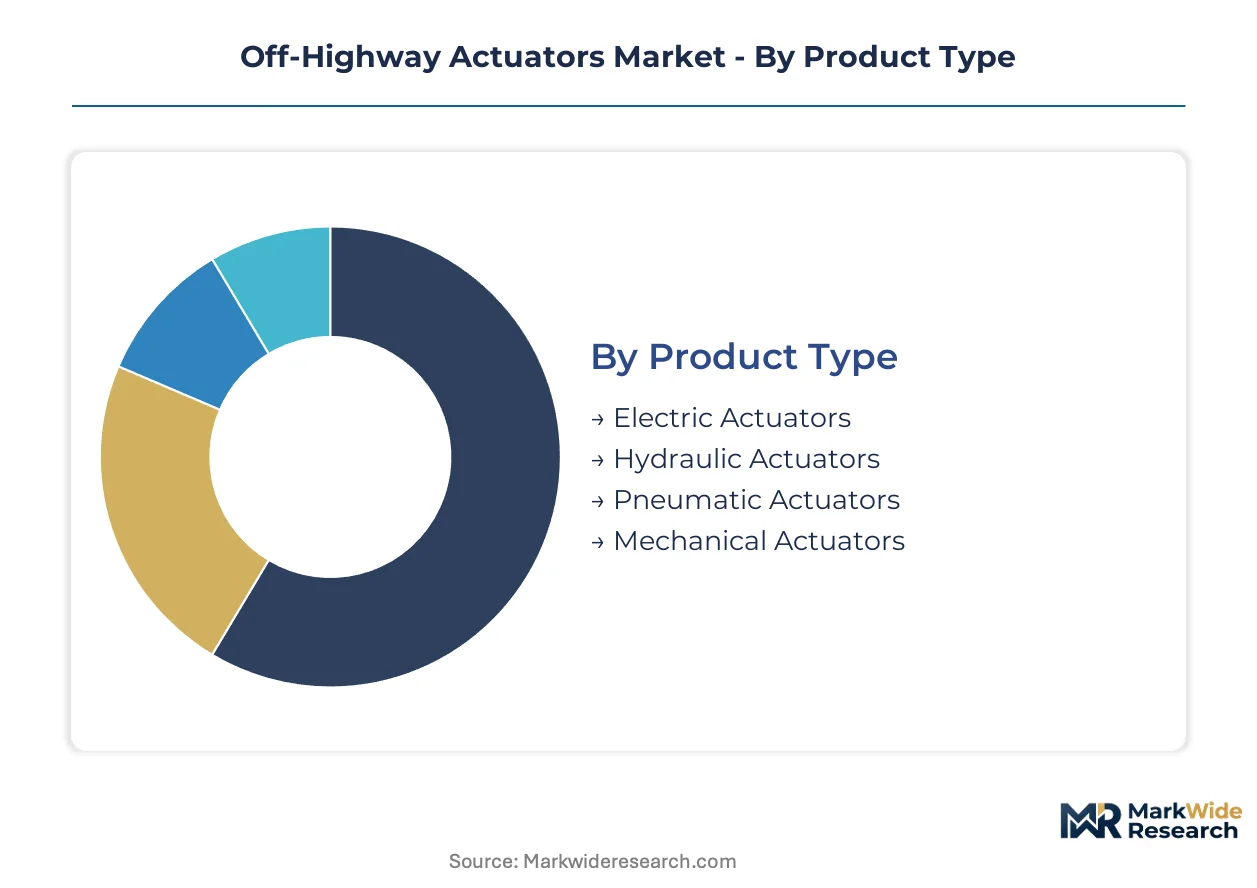
Off-highway actuator segmentation reveals how electrification pressures and emissions compliance reshape procurement across equipment categories. Product architecture choices now cascade through end-use specifications, application requirements, and technology integration levels.
Product Type:
Mature hydraulic systems dominate installed fleet value while electric architectures capture new equipment specification share fastest.
- Electric Actuators:Brushless DC and servo motor designs with integrated position feedback deliver precision motion without hydraulic fluid maintenance. Construction OEMs in Germany and Japan specify these for autonomous grading platforms where CAN bus connectivity enables real-time blade positioning. Tier 4 Final compliance pressures accelerate substitution for engine-driven hydraulic pumps.
- Hydraulic Actuators:Cylinder-based fluid power systems remain entrenched in high-force mining and heavy construction applications exceeding 200 kN output requirements. North American rental fleets maintain hydraulic dominance due to technician familiarity and established service networks. Thermal management limitations in underground mining slow electrification timelines.
- Pneumatic Actuators:Compressed-air systems serve limited forestry and agricultural niches where explosion safety and cost minimization outweigh precision needs.
- Mechanical Actuators:Screw jack and linkage mechanisms persist in low-duty cycle agricultural implements where manual override remains essential.
Hydraulic actuators handle the majority of throughput; electric actuators are expanding most quickly on specification share.
End User:
Cost tier separation runs from precision agriculture automation to bulk mining force density requirements.
- Construction Machinery:Earthmoving equipment OEMs demand redundant position feedback for autonomous blade and bucket control. German manufacturers specify smart actuators with embedded diagnostics to reduce wiring complexity in compact excavators and wheel loaders. Battery-electric platform development eliminates hydraulic pump loads entirely.
- Agriculture Equipment:Tractor and implement manufacturers pursue variable-rate seeding and fertilization precision in Punjab and Haryana mechanization zones. ISO 25119 safety mandates drive redundant encoder specifications for steering and hitch control systems. Cost optimization pressures differentiate commodity grain markets from premium horticulture automation.
- Mining Equipment:Underground and surface extraction machinery requires fail-safe positioning in emergency stop scenarios per MSHA guidelines. Continuous-duty thermal loads exceed current IP69K electric actuator ratings in deep shaft applications.
- Forestry Equipment:Harvester and forwarder OEMs balance hydraulic force density with electrification for boom and grapple functions in Nordic and North American markets.
Construction machinery commands premium specification value; agriculture equipment is climbing the fastest on unit volume expansion.
Application:
Volume concentration centers on control systems while safety systems drive margin expansion through certification requirements.
- Control Systems:Implement positioning and drivetrain management consume the largest actuator deployment volumes across all equipment categories. CANopen and EtherCAT protocol convergence enables single-cable networked architectures with embedded diagnostics.
- Automation:Machine-controlled grading, seeding, and excavation demand sub-millimeter positioning accuracy with real-time feedback loops. Autonomous fleet trials in German construction markets validate smart actuator reliability.
- Steering Mechanisms:Articulated chassis and implement guidance require redundant position sensing under ISO 25119 agricultural and OSHA mining safety frameworks.
- Safety Systems:Emergency stop actuation and fail-safe positioning command margin premiums through extended validation timelines and liability engineering.
Control systems handle the majority of throughput; safety systems are gaining share fastest on compliance-driven replacement cycles.
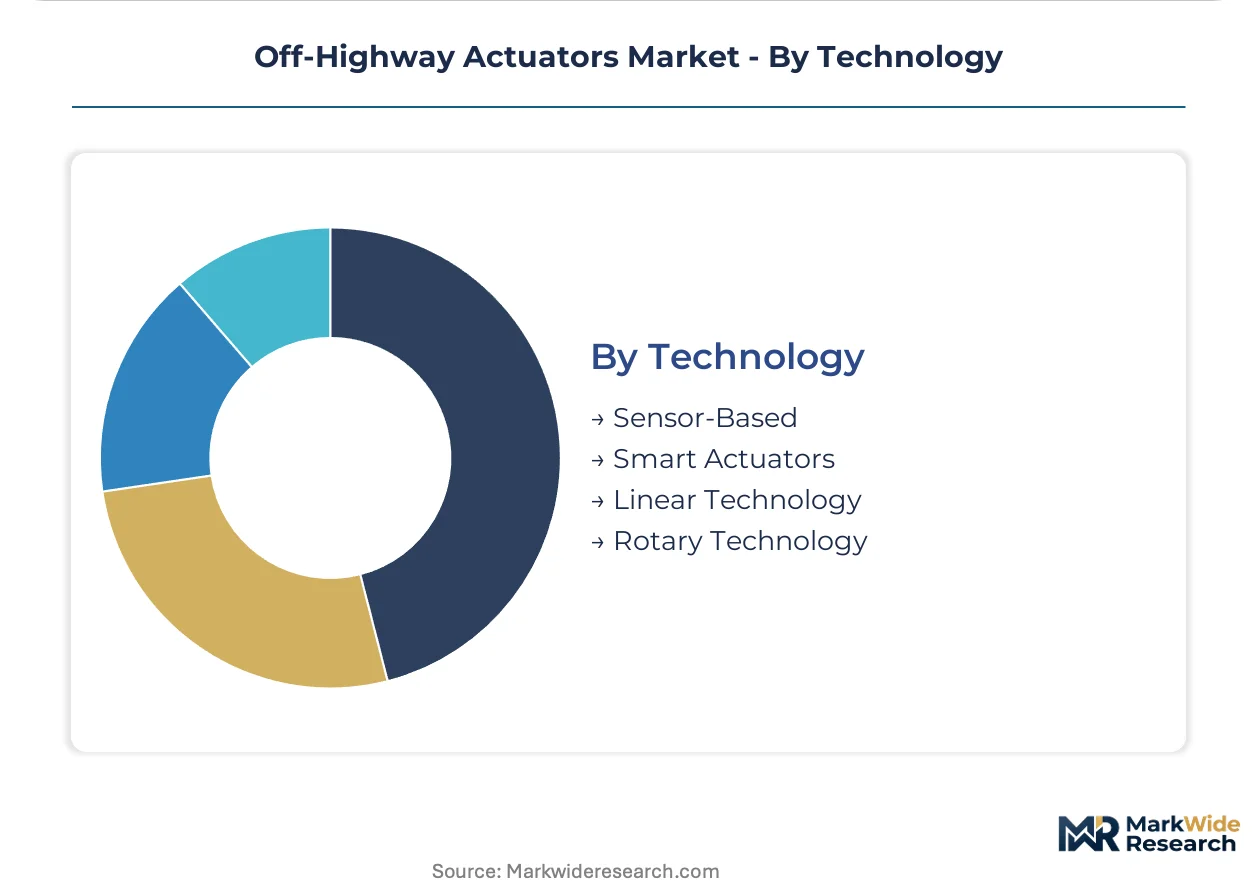
Technology:
Supply concentration clusters around sensor integration while smart architectures capture specification premiums.
- Smart Actuators:Edge-embedded motor drives with integrated position sensing and condition monitoring collapse wiring harness complexity. Predictive maintenance contracts based on vibration and current-signature analytics unbundle service from OEM-captive networks.
- Sensor-Based:Rotary and linear encoders with CAN bus output enable closed-loop positioning in legacy controller retrofits. Proprietary bus implementations in existing fleets resist standardization to open protocols.
- Linear Technology:Ball screw and roller screw mechanisms serve precision agriculture and compact construction applications with envelope constraints.
- Rotary Technology:Hollow-shaft servo motors collapse mechanical stack height in Japanese and South Korean compact loader designs.
Sensor-based architectures handle the majority of throughput; smart actuators represent the steepest expansion trajectory on margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rental fleet operators and construction OEMs concentrate procurement authority in Germany, the United States, and Japan, with emerging demand from Indian agricultural mechanization zones reshaping supplier qualification priorities.
Germany
EPA Tier 4 Final-equivalent EU Stage V compliance deadlines force diesel-dependent hydraulic pumps toward electrified alternatives in earthmoving equipment. The KBA enforces emissions certification timelines that compress product development cycles for actuator manufacturers. Stuttgart and Lohr am Main anchor concentrated production clusters where Bosch Rexroth AG and Parker Hannifin Corporation accelerate supplier qualification for Tier 1 integrators.
United States
OSHA and MSHA guidelines for mining equipment operator protection specify fail-safe actuator behavior in emergency stop scenarios across surface and underground extraction operations. The EPA enforces Tier 4 Final particulate reduction mandates that indirectly reward electric actuation by reducing parasitic hydraulic pump loads. The Mountain West mining belt sees pilot deployments of electrohydraulic hybrids that preserve force density while cutting fuel consumption.
Japan
METI industrial automation initiatives drive compact equipment OEM adoption of hollow-shaft rotary actuators for boom and bucket curl functions in tight chassis layouts. JIS standards govern precision positioning requirements in construction and agricultural machinery exports. Japanese manufacturers in the Kanto and Chubu regions specify integrated servo motors that collapse mechanical stack height in skid-steer and compact loader applications.
India
Tractor OEMs in Punjab and Haryana seek cost-optimized smart actuators for precision seeding and variable-rate fertilization as agricultural mechanization accelerates. The BIS certification framework governs safety and performance standards for agricultural machinery components entering domestic and export markets. Manufacturing clusters in Maharashtra and Gujarat attract component suppliers targeting price-sensitive implement control systems for commodity grain markets.
China
Dual carbon goals and MIIT industrial upgrading directives pressure construction equipment manufacturers toward electrified implement controls on battery-electric platforms. GB standards establish electromagnetic compatibility and safety requirements for smart actuators with embedded position sensing. Yangtze River Delta manufacturing zones concentrate actuator assembly capacity serving both domestic OEM demand and export markets across Southeast Asia.
Off-Highway Actuators Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated motion control conglomerates with captive distribution networks dominate premium specification segments, while regional fabricators serve price-sensitive agricultural and rental fleet replacement markets. Specialist archetypes include precision linear motion engineers, electrohydraulic hybrid developers, and predictive maintenance service unbundlers. Competitive moves center on strategic partnerships for high-voltage platform qualification and geographic expansion into Indian agricultural mechanization zones.
Among diversified industrial conglomerates, Emerson Electric Co. and Eaton Corporation exemplify channel-controlling archetypes with integrated portfolios spanning electrical and hydraulic actuation technologies. Parker Hannifin Corporation anchors the precision motion tier with North American rental fleet penetration and standardized actuator architectures. Bosch Rexroth AG represents the European manufacturing cluster model with deep linear drive and electrohydraulic system capabilities concentrated in German production facilities.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Actuant Corporation |
| Parker Hannifin Corporation |
| Thomson Linear Motion Systems |
| Webtec Products Ltd. |
| Bosch Rexroth AG |
| SMC Corporation |
| SKF Motion Technologies |
| Eaton Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese electric motor manufacturing is compressing export pricing for standard-grade actuators while concentrating bargaining power among German and Japanese suppliers serving precision-automation contracts. This utilization asymmetry splits the market into commodity spot purchasing for agricultural implements and long-term offtake agreements for mining safety systems.
Pricing Analysis
Certification level creates the primary spread between ISO 25119-compliant redundant encoders and basic position sensors. The dominant structure is contract-based long-term offtake for Tier 1 OEMs, with spot purchasing filling aftermarket gaps. Price differentiation stems from CE marking tier and volume scale, with German manufacturing clusters commanding premiums for Stage V validation documentation. Pricing pressure stems from rare earth magnet cost volatility destabilizing electric actuator forecasts. Rental fleet operators exhibit highest price sensitivity, while mining safety procurement shows lowest due to MSHA liability exposure.
Supply Chain Analysis
Export controls on high-performance rare earth magnet technology limit flows from Chinese processors to Western actuator manufacturers, forcing supply chain reconfiguration. Production concentrates in Germany, Japan, and China. The supply chain draws from neodymium magnets, precision ball screws, and CAN bus controller chips. Single-source vulnerability in rare earth processing creates structural risk. Distribution runs through OEM captive networks and independent aftermarket distributors serving rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The off-highway actuators market is entering cyclical recovery driven by construction equipment replacement cycles following pandemic-deferred capital expenditure. Equipment leasing normalization and autonomous fleet deployment timelines will determine amplitude.
For Market Incumbents: Build certification moats around ISO 25119 and Stage V validation documentation to lock out commodity competitors. Deepen backward integration into rare earth magnet sourcing through offtake agreements with Australian and Vietnamese processors. Channel control through telematics-embedded service contracts displaces independent aftermarket distributors. For New Entrants and Emerging Players: Build out precision agriculture automation in Punjab and Haryana where tractor OEMs seek cost-optimized smart actuators for variable-rate seeding. Target electrohydraulic hybrid architectures for underground mining applications where thermal management limitations preserve hydraulic force density. Go-to-market through equipment leasing operators unbundling actuator maintenance from full-machine contracts. For Investors and Strategic Acquirers: Capital is best deployed toward predictive maintenance service unbundlers with vibration and current-signature analytics capabilities. Long-term viability hinges on qualification pathways for high-voltage battery-electric construction platforms. Monitor Indian BIS certification timeline acceleration as inflection signal for agricultural mechanization investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures neodymium and dysprosium flows against Chinese export restrictions for high-force linear drives. |
| Predictive Maintenance Service Unbundling | Captures standalone contracts from rental fleets using vibration analytics, displacing OEM-captive networks. |
| High-Voltage Platform Qualification | Positions suppliers for battery-electric construction equipment architectures eliminating hydraulic pumps. |
| ISO 25119 Certification Investment | Opens agricultural steering and implement control markets requiring redundant position feedback validation. |
| Indian Manufacturing Footprint Expansion | Reduces landed cost for Punjab and Haryana tractor OEMs pursuing precision seeding automation. |
Research Methodology
Initial hypotheses were tested against primary input from construction OEM procurement directors, agricultural equipment R&D heads, mining safety compliance officers, and rental fleet maintenance managers, then refined against secondary validation. Sources included SEC 10-K filings from diversified industrial conglomerates, EPA Tier 4 Final enforcement documentation, EU Stage V certification databases, and customs trade data for rare earth magnet flows. Bottom-up equipment production forecasts and top-down emissions compliance-driven replacement estimates were triangulated.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by actuation architecture, end-use equipment category, application function, and technology integration level. CAGRs were derived from equipment production forecasts, regulatory compliance deadline clustering, and technology substitution elasticity estimates. Industry-specific inputs included rare earth price volatility indices and telematics penetration rates in construction equipment fleets.
Practitioners should monitor rare earth export control expansion, Indian BIS certification acceleration, and battery-electric construction equipment pilot deployment scale for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automobile AC Condensers Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Automotive Glass Market
Automotive Components
France Automotive Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Distributor Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Fender Market