
 Global Automotive Water Valve Market | 2026-2036
Global Automotive Water Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Water Valve Market Analysis
Asset-light manufacturing partnerships and contract assembly models is reconfiguring capital requirements for tier suppliers entering the water valve space. Mahle GmbH leverages captive foundry capacity to anchor cost positions in aluminum valve housings. Denso Corporation sustains technology leadership through integrated electronic actuator designs that merge thermal and electric valve architectures.
Automotive water valves regulate coolant flow across engine blocks, battery packs, and HVAC circuits, typically operating within temperature ranges of minus forty to one hundred thirty degrees Celsius with pressure ratings exceeding two bar. Their primary purpose centers on optimizing thermal efficiency and preventing component overheating in conventional and electrified powertrains. Electric valve segments lead growth trajectories as battery thermal management demands precision flow modulation, while stainless steel material categories command margin concentration due to corrosion resistance specifications in hybrid cooling loops. OEM end-user channels dominate volume absorption, though aftermarket providers compete on replacement cycle compression in aging vehicle parcs.
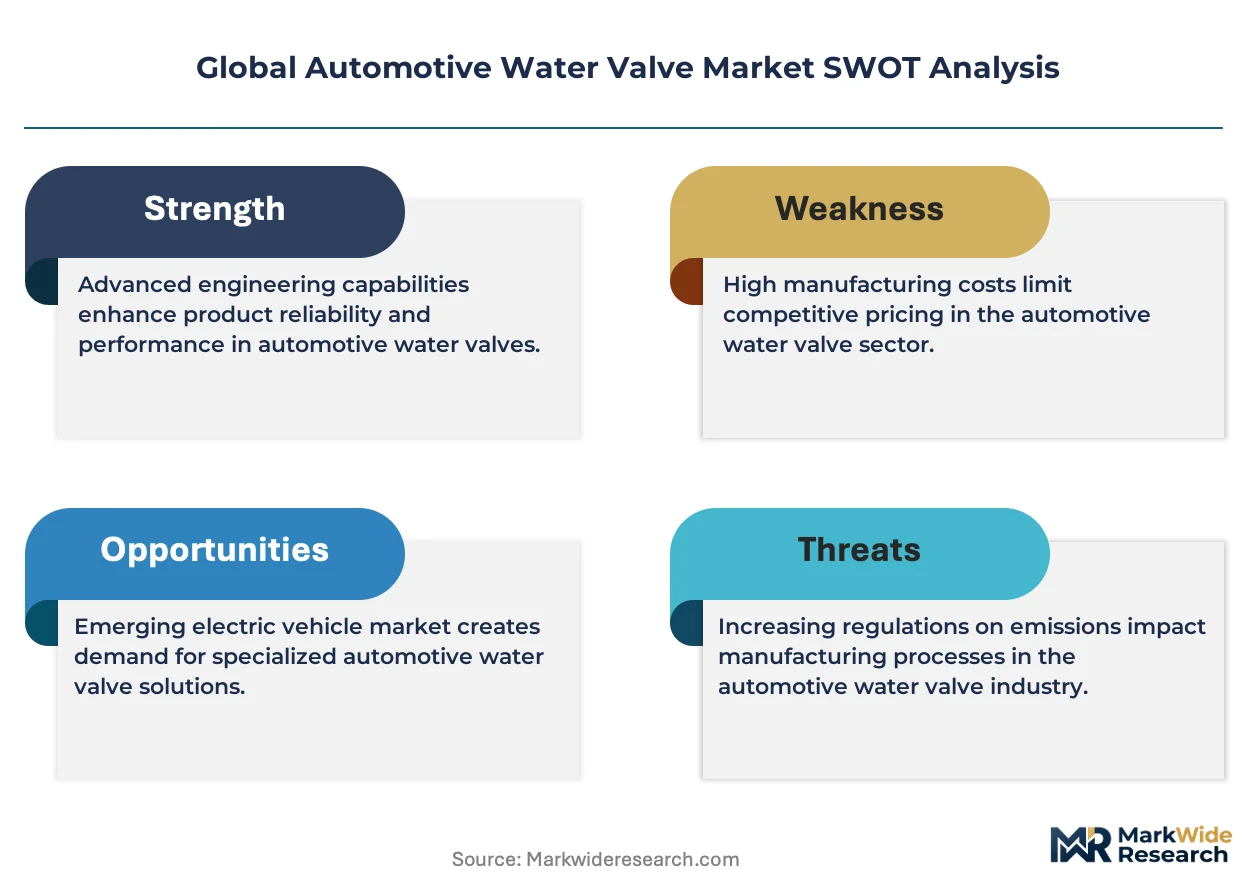
EPA emission mandates and EU F-Gas Regulation tighten coolant system leakage thresholds, forcing redesigns of valve sealing interfaces and actuator housing geometries. NHTSA vehicle safety standards in the United States and MIIT technical guidelines in China further shape product certification pathways for thermal management components. Stakeholders must monitor divergence between regional refrigerant phase-down schedules and battery-electric platform thermal architectures to align R&D pipelines with compliance deadlines.
Market Dynamics
Electrification of powertrain architectures is compressing thermal management system design cycles, forcing valve suppliers to reconcile precision flow control with high-voltage isolation requirements and reduced engine bay packaging space.
Growth Catalysts
- Battery thermal management platforms:Electric vehicle manufacturers require multi-circuit coolant distribution systems that modulate flow across battery packs, inverters, and electric motors with sub-degree accuracy.
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants tightens leakage thresholds for HVAC-integrated coolant loops, mandating upgraded valve sealing technologies.
- China's NEV mandate:MIIT production quotas for new energy vehicles create sustained procurement volume for precision water valves in domestic BEV and PHEV assembly plants.
Market Restraints
- Aluminum alloy price volatility:Die-cast valve housings consume A356 and A380 grades whose London Metal Exchange pricing swings compress foundry margins unpredictably.
- Actuator motor supply concentration:Precision stepper motors for electronic valves source predominantly from East Asian suppliers, creating single-source vulnerability for tier-two valve assemblers.
- Stainless steel substitution limits:Corrosion-resistant grades 316L and 17-4 PH command three-to-four times the raw material cost of aluminum, constraining adoption in cost-sensitive ICE applications.
Strategic Opportunities
- India's PLI scheme for auto components:The production-linked incentive framework subsidizes capital equipment for thermal management component manufacturing, attracting valve suppliers to Gujarat and Tamil Nadu industrial corridors.
- Integrated thermal-electric valve architectures:Convergence of traditional coolant valves with refrigerant expansion valves enables single-module solutions for heat-pump-equipped BEVs.
- Digital aftermarket channels:Direct-to-workshop e-commerce platforms bypass traditional distributor markups for replacement valves in aging European and North American vehicle parcs.
Industry Challenges
- High-voltage safety certification:Valve actuators operating adjacent to 400V and 800V battery systems require ISO 6469 and OEM-specific validation protocols that extend development timelines.
- Cross-platform thermal architecture integration:Suppliers must engineer valve families compatible with both legacy internal combustion cooling loops and emerging immersion-cooled battery designs without duplicating tooling investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Water Valve Market |
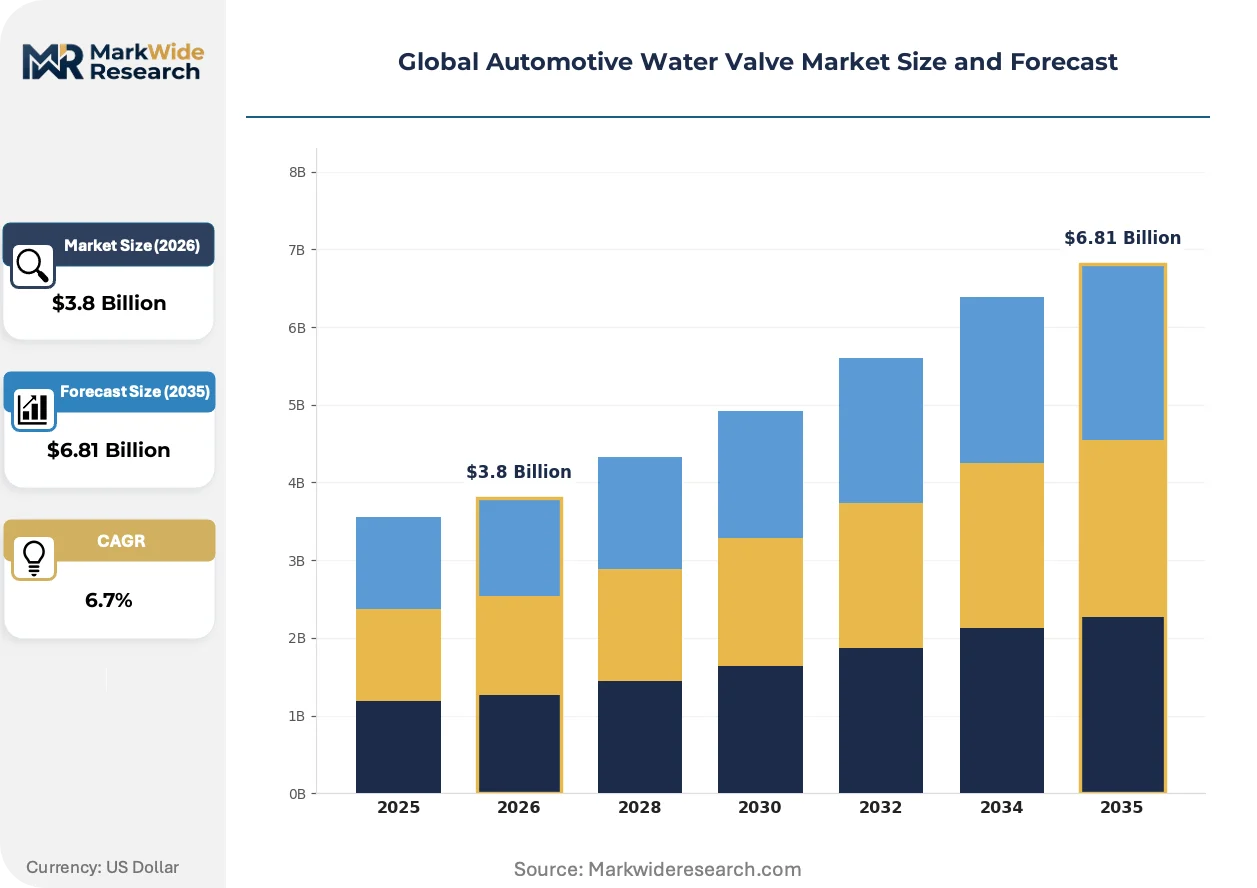
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Electric, Pneumatic, Mechanical End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Material: Plastic, Brass, Aluminum, Stainless Steel Installation: Direct Mount, Remote Mount, Integrated, Modular |
| Companies Covered | Mahle GmbH, Denso Corporation, BorgWarner Inc., Robert Bosch GmbH, AISIN Corporation, Valeo SE, Schaeffler AG, Continental AG, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Water Valve Market Emerging Trajectories
Digital twin methodologies and predictive thermal modeling are compressing prototype validation cycles, while material science advances enable thinner-walled, higher-pressure valve housings. These forces collectively reduce time-to-market for next-generation coolant management systems.
Smart valve actuators with embedded temperature and pressure sensors are virtualizing traditional mechanical thermostat functions, enabling real-time coolant flow optimization through CAN bus integration. Tier-one thermal system suppliers deploy these units across premium BEV platforms first. The technology is virtualizing decades of fixed-orifice hydraulic design practice into software-calibrated thermal architectures.
EPA vehicle emission standards and the complementary California Air Resources Board LEV IV regulations mandate faster engine warm-up protocols to reduce cold-start emissions. This forces redesign of bypass valve actuation speeds and heater control valve response curves. Passenger vehicle OEMs in the United States absorb the bulk of compliance engineering costs.
Fleet operators and vehicle-as-a-service providers now specify total-cost-of-ownership clauses in thermal system procurement contracts, prioritizing valve durability metrics over upfront piece price. Long-haul trucking and ride-hail electrification fleets in Germany and the United States drive this specification shift. Suppliers respond with extended-warranty valve designs and predictive maintenance data feeds.
Global Automotive Water Valve Market Segmentation
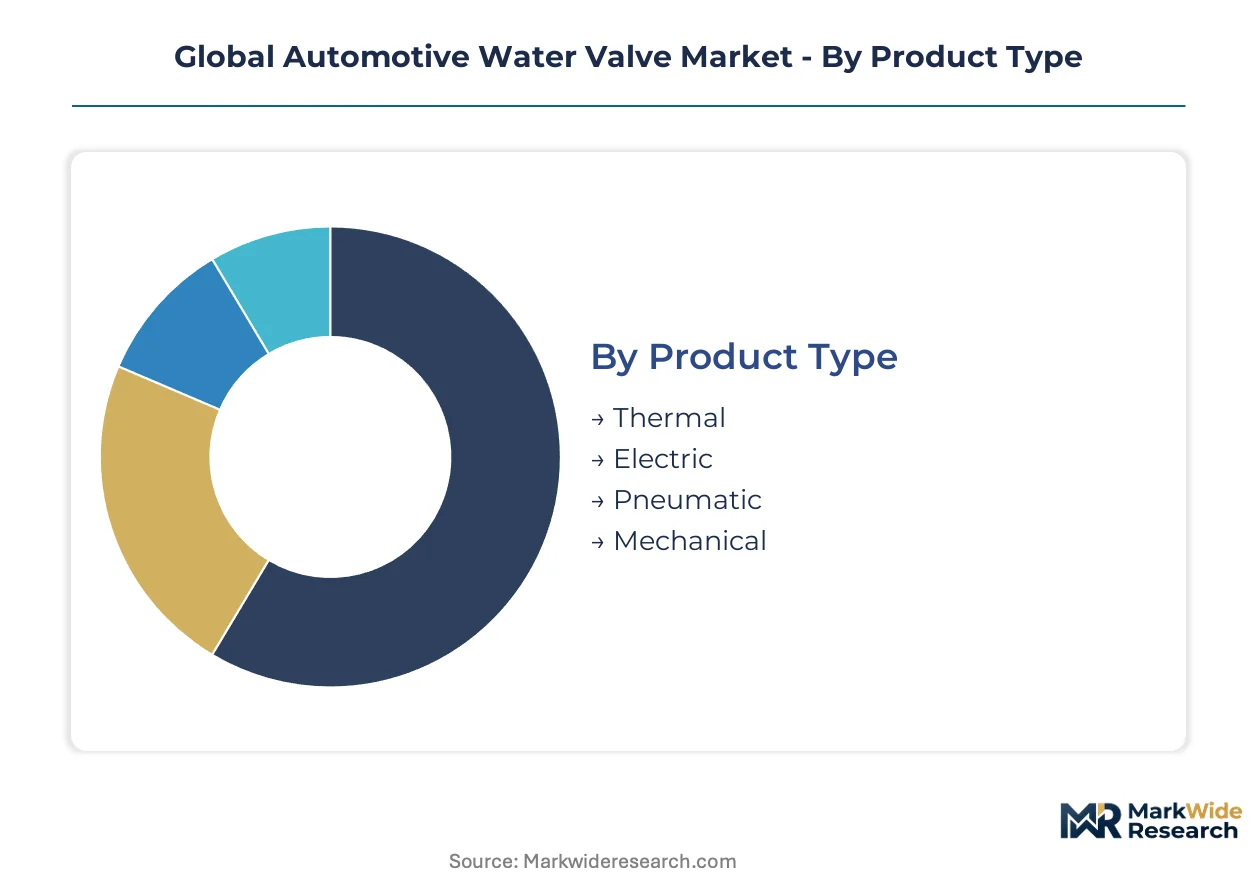
Automotive water valve segmentation reflects divergent thermal management requirements across electrified and conventional powertrains. Suppliers must align product architectures with distinct pressure tolerances, response speeds, and corrosion resistance specifications demanded by battery-electric, hybrid, and internal combustion platforms.
Product Type:
Valve actuation mechanisms span a spectrum from passive thermal response to precision electronic control, each addressing distinct thermal modulation scenarios in modern vehicle architectures.
- Electric:Stepper-motor-driven actuators enable millisecond-level flow modulation with CAN bus feedback integration. Battery-electric vehicle manufacturers in Germany and China specify these for battery pack thermal loops where sub-degree temperature uniformity prevents cell degradation.
- Thermal:Wax-element expansion mechanisms respond passively to coolant temperature changes without external power. These dominate cost-sensitive ICE applications in India and Southeast Asia where electronic complexity adds unacceptable bill-of-materials burden.
- Pneumatic:Compressed-air actuation serves heavy-duty commercial vehicle cooling systems where robust environmental sealing exceeds electronic actuator reliability.
- Mechanical:Cable-linked rotary valves persist in legacy vehicle parcs and budget segment replacements where electronic integration offers marginal value.
Established volume favors thermal valves; emerging adoption favors electric actuation.
End User:
Procurement authority concentrates differently across direct vehicle assembly, component system integration, and post-warranty service channels.
- OEMs:Original equipment manufacturers specify valve performance curves, sealing standards, and validation protocols during platform development. German and US passenger vehicle OEMs drive specification tightening for 800V-compatible thermal architectures.
- Tier-1 Suppliers:Thermal system integrators procure valve subassemblies for incorporation into complete coolant modules. These suppliers in Japan and South Korea consolidate sourcing to capture scale economies in electronic valve procurement.
- Aftermarket Providers:Independent distributors serve aging vehicle populations with replacement valves calibrated to original equipment pressure and flow characteristics. European and North American parc age sustains this channel.
- Dealerships:Authorized service networks handle warranty-period valve replacements with OEM-captured parts margins.
Volume concentration sits with OEMs; margin expansion sits with aftermarket channels.
Material:
Housing and flow-path material selection trades corrosion resistance, thermal conductivity, and die-cast processability against raw material cost volatility.
- Aluminum:A356 and A380 die-cast alloys deliver heat dissipation and weight reduction for engine-adjacent installations. Foundry capacity in China and Mexico anchors supply for high-volume ICE thermal modules.
- Stainless Steel:316L and 17-4 PH grades withstand galvanic corrosion in hybrid cooling loops where aluminum housings contact copper busbars. Premium BEV platforms in Germany and California specify these for battery immersion cooling interfaces.
- Brass:Lead-free brass formulations serve low-pressure HVAC integration points where machinability exceeds strength requirements.
- Plastic:Glass-reinforced polyamide housings reduce weight in auxiliary coolant circuits with minimal pressure cycling.
Cost-driven applications favor aluminum; corrosion-critical systems favor stainless steel.
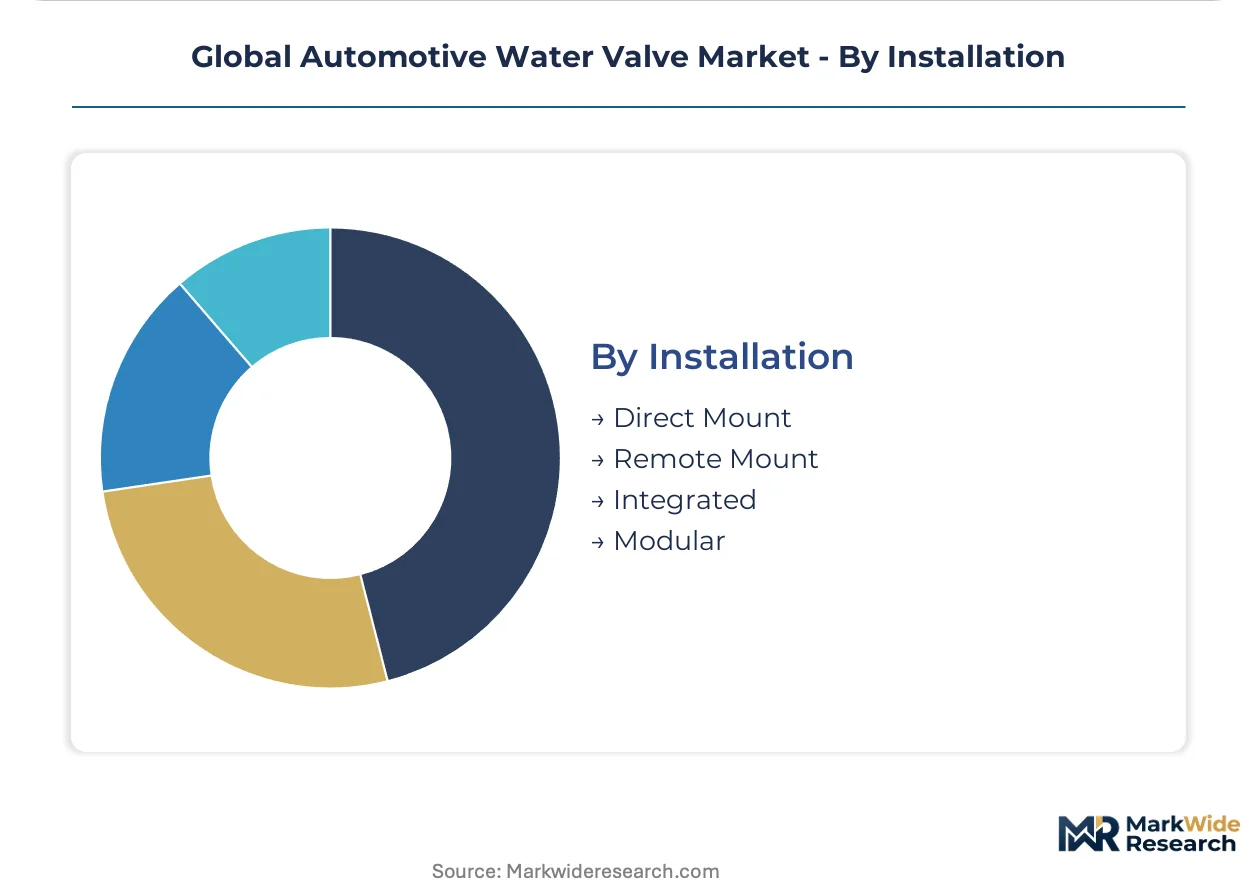
Installation:
Physical mounting topology determines packaging flexibility, service accessibility, and integration with adjacent thermal components.
- Integrated:Valve bodies cast directly into cylinder heads or battery pack manifolds eliminate joint interfaces and leakage paths. German OEMs specify these for compact BEV skateboard platforms where packaging volume commands premium engineering attention.
- Modular:Standardized flange interfaces enable valve replacement without disturbing surrounding plumbing. Fleet operators in the United States prioritize these designs to minimize service downtime in commercial vehicle thermal systems.
- Direct Mount:Single-point attachment to engine blocks or radiator tanks serves conventional ICE cooling architectures with predictable thermal expansion matching.
- Remote Mount:Flexible hose connections position valves away from heat sources or vibration nodes in complex multi-circuit thermal networks.
Platform-integrated designs favor integrated valves; serviceability priorities favor modular architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in automotive water valves track the geographic dispersion of battery-electric vehicle assembly capacity. Germany and China maintain trade surpluses in precision electronic valve subassemblies, while the United States and India absorb significant import volumes to support domestic BEV production scale-up.
China
MIIT production quotas for new energy vehicles sustain procurement volumes for multi-circuit thermal management valves. The country's national automotive regulator enforces GB standards for coolant system safety in high-voltage architectures. Valve foundries cluster in Guangdong and Jiangsu provinces, where die-cast aluminum capacity serves both domestic OEMs and export markets for Southeast Asian assembly plants.
Germany
Premium BEV platforms from Stuttgart and Munich OEMs specify 800V-compatible stainless steel valves for battery immersion cooling. The EU F-Gas Regulation mandates leakage thresholds that tighten sealing specifications across HVAC-integrated coolant loops. Suppliers concentrate in Baden-Württemberg and Bavaria, anchoring precision machining capacity for thermal-electric valve architectures.
United States
EPA vehicle emission standards and CARB LEV IV protocols accelerate demand for fast-actuating bypass valves that reduce cold-start emissions. NHTSA safety validation extends development timelines for high-voltage adjacent actuator designs. Manufacturing activity concentrates in Michigan and Ohio, where tier-one thermal system integrators serve Detroit-based OEM electrification programs.
India
The PLI scheme for auto components subsidizes capital equipment for thermal management manufacturing in Gujarat and Tamil Nadu. BIS certification requirements shape product qualification pathways for domestic valve suppliers. Industrial corridors in Pune and Chennai attract contract assembly models for cost-sensitive thermal valve production serving ASEAN export markets.
Japan
Domestic OEM thermal system integrators consolidate electronic valve sourcing to capture scale economies in precision stepper motor supply. METI technical guidelines influence battery thermal management component standards across Asia-Pacific supply chains. Nagoya-area manufacturing clusters specialize in integrated actuator designs that merge coolant and refrigerant valve functions.
Global Automotive Water Valve Market Vendor Landscape
On the supply side, the industry is tiered between integrated thermal system suppliers and specialized valve component fabricators. Consolidation pressures concentrate among electronic actuator specialists, while aluminum foundry capacity remains geographically fragmented. Two strategic archetypes dominate: captive foundry operators leveraging backward integration into housing production, and electronics-integrated platform providers merging thermal and refrigerant valve architectures. Competitive moves center on asset-light manufacturing partnerships and cross-platform thermal architecture engineering that spans legacy ICE and emerging BEV cooling loops.
Within the integrated thermal systems tier, Mahle GmbH and Denso Corporation exemplify divergent strategic positions. The Stuttgart-based GmbH anchors cost positions through captive aluminum foundry capacity for valve housings. The Japanese Corporation occupies a position defined by integrated electronic actuator designs that merge thermal and electric valve architectures. BorgWarner Inc. represents the North American archetype of portfolio diversification across powertrain electrification components. These three entities collectively illustrate how geographic origin and corporate structure shape competitive positioning in precision coolant flow modulation.
| Leading Market Players |
|---|
| Mahle GmbH |
| Denso Corporation |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| AISIN Corporation |
| Valeo SE |
| Schaeffler AG |
| Continental AG |
| Eaton |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese aluminum foundries compresses die-cast housing margins and forces tier-two assemblers toward contract manufacturing partnerships that surrender pricing autonomy. German and Japanese valve suppliers exploit captive precision machining capacity to defend premium positioning against this deflationary pressure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments across platform development cycles. Three-tier pricing structure across premium, standard, and economy levels separates 800V-compatible stainless steel valves from aluminum thermal units and legacy mechanical replacements. Cost compression in the aluminum die-cast tier is intensifying because London Metal Exchange price volatility transfers risk downstream to foundry-dependent suppliers. Fleet operators and vehicle-as-a-service providers demonstrate lowest price sensitivity, prioritizing total-cost-of-ownership durability metrics over upfront piece price.
Supply Chain Analysis
Extended payment terms from German and US OEMs strain working capital for tier-two valve assemblers, accelerating consolidation toward integrated thermal system suppliers with balance-sheet depth. Manufacturing concentrates in China, Germany, and Mexico, with die-cast aluminum capacity anchored in Guangdong and Jiangsu provinces and precision machining clustered in Baden-Württemberg. Supply chains draw from A356/A380 aluminum grades, precision stepper motors, and 316L stainless steel feedstock. Single-source vulnerability around East Asian stepper motor suppliers creates structural risk for electronic valve production. Distribution runs through tier-one thermal system integrators who consolidate sourcing to capture scale economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance data feeds and extended-warranty valve designs constitute a service-attach layer expanding faster than hardware replacement volumes, particularly among electrified fleet operators in Germany and the United States.
For Market Incumbents: Entrench backward integration into aluminum foundry capacity to anchor cost positions against Chinese price competition. Capture electronic actuator design leadership through integrated thermal-electric valve architectures that merge coolant and refrigerant functions. ISO 6469 high-voltage safety certification investment creates switching costs that lock OEM relationships across platform generations. For New Entrants and Emerging Players: Pursue India's PLI-subsidized manufacturing corridors in Gujarat and Tamil Nadu to serve ASEAN export markets with cost-sensitive thermal valve production. Target aftermarket digital channels for aging European and North American vehicle parcs where direct-to-workshop e-commerce bypasses traditional distributor markups. White-space opportunity concentrates in stainless steel immersion-cooling interfaces for 800V battery platforms where incumbent capacity remains constrained. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated thermal system suppliers with captive actuator design capabilities and long-term OEM platform contracts. Five-to-ten year viability favors entities with cross-platform engineering competence spanning legacy ICE and emerging BEV cooling loops. Acquisition priority targets electronic valve specialists with validated high-voltage safety protocols. The signal to monitor is divergence between regional refrigerant phase-down schedules and battery-electric thermal architecture deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Thermal-Electric Valve Architecture | Merges coolant and refrigerant functions for heat-pump-equipped BEVs from Stuttgart and Munich OEMs. |
| Captive Aluminum Foundry Capacity | Anchors cost positions in A356 valve housings against Chinese price competition. |
| 800V High-Voltage Safety Certification | ISO 6469 validation extends development timelines but locks OEM relationships across platform generations. |
| Digital Aftermarket Channel Development | Direct-to-workshop platforms bypass distributor markups in aging European and North American vehicle parcs. |
| India PLI Manufacturing Footprint | Subsidized capital equipment in Gujarat and Tamil Nadu corridors serves ASEAN export markets. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with tier-one supplier procurement directors, OEM platform thermal engineers, aftermarket distributors, and foundry operations managers; and secondary validation through vehicle production databases, IHS Markit registration data, MIIT production quota disclosures, and SEC filings from listed thermal system suppliers. Bottom-up triangulation across valve content-per-vehicle assumptions and top-down reconciliation against OEM thermal system procurement volumes anchored market sizing.
Forecast inputs considered propulsion architecture segmentation across battery-electric, hybrid, and internal combustion platforms; material grade tiering between aluminum and stainless steel specifications; and regional production cluster concentration in Germany, China, and the United States. CAGRs were derived from annualized growth rate calculations across the projection horizon. Industry-specific inputs included battery pack thermal management valve penetration rates and EU F-Gas Regulation compliance timelines.
Sensitivities concentrate around aluminum alloy price volatility, stepper motor supply disruption, and divergence between regional refrigerant phase-down schedules. Forecasts reflect documented assumptions regarding BEV production scale-up and thermal architecture standardization. Macroeconomic contraction, regulatory delay, or immersion-cooling technology displacement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Automotive Comfort Actuators Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
China Automotive Composites Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Automotive Commutator Market
Automotive Components
Global Automotive Selector Lever Market