
 Automotive Interconnecting Shaft Market | 2026-2036
Automotive Interconnecting Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Interconnecting Shaft Market Outlook
Fleet operators and electric vehicle OEMs is redrawing procurement priorities away from traditional passenger car programs. GKN Driveline leverages hollow shaft expertise for battery electric platforms, while Dana Incorporated anchors North American commercial vehicle supply through vertically integrated forging capacity. ZF Friedrichshafen competes on mechatronics integration, combining shaft systems with active torque management.
An automotive interconnecting shaft transmits rotational torque between drivetrain components, typically manufactured from case-hardened alloy steel with spline interfaces rated for fatigue cycles exceeding 500,000 revolutions. The component maintains driveline synchronization across axle differentials, transfer cases, and electric motor reductions. Hollow shafts lead the product type category due to mass reduction imperatives, while carbon fiber material variants represent the fastest-growing segment as EV range optimization intensifies. Aftermarket providers occupy mature, price-sensitive channels, whereas OEM direct supply concentrates margin pools at specification-setting manufacturers.
NHTSA and EPA regulations in the United States enforce fuel economy and safety standards that mandate lighter, stronger shaft architectures. China's SAMR and GB standards authorities impose homologation requirements affecting material traceability and fatigue testing protocols. The EU's F-Gas Regulation and REACH framework indirectly pressure supply chains through fluoropolymer coating restrictions and substance disclosure mandates. Stakeholders must monitor evolving powertrain electrification roadmaps to align R&D spending with torque vectoring and e-axle integration requirements.
Market Dynamics
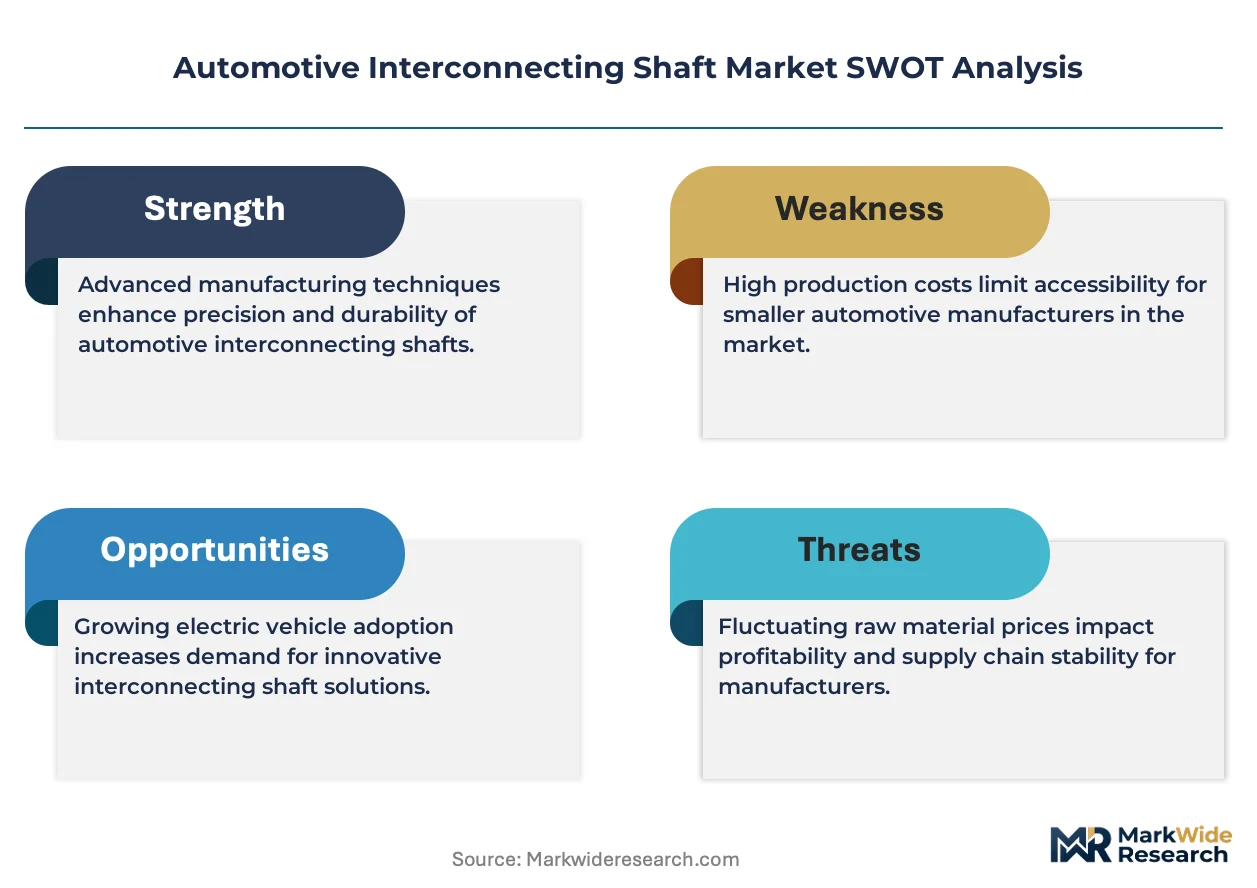
Powertrain electrification is compressing traditional driveline architectures, forcing hollow shaft designs to accommodate higher torque densities from e-axle motors while shedding mass to preserve EV range. Material substitution and topology optimization now dominate supplier engineering roadmaps.
Growth Catalysts
- EPA Fuel Economy Mandates:United States fleet efficiency targets compel OEMs to specify hollow shafts over solid variants, reducing unsprung mass and improving regenerative braking efficiency.
- Battery Electric Platforms:European EV manufacturers are standardizing integrated e-axle modules that require lightweight torque tubes with spline interfaces rated for instantaneous motor torque spikes.
- China GB Vehicle Safety Standards:Homologation protocols for fatigue testing and material traceability are elevating specification barriers, favoring suppliers with certified heat-treatment capabilities.
Market Restraints
- Alloy Steel Price Volatility:Case-hardening grade steel feedstock costs fluctuate with scrap metal and alloying element markets, compressing forging margins without pass-through mechanisms.
- German Supply Concentration:Tier 1 forging and machining capacity clusters along the Rhine-Ruhr corridor, creating geographic single-point vulnerability for European OEM supply security.
- Carbon Fiber Substitution Ceiling:Composite shaft alternatives face cost and repairability constraints that limit penetration below premium performance tiers despite mass advantages.
Strategic Opportunities
- Indian Commercial Vehicle Electrification:Bus and last-mile delivery fleet operators under BIS efficiency mandates present unserved demand for locally manufactured hollow prop shafts.
- Torque Vectoring Convergence:Integration of active differentials with interconnecting shafts enables mechatronic suppliers to capture value previously held by discrete component vendors.
- United States IRA Clean Vehicle Credits:Domestic content requirements for battery and drivetrain assemblies incentivize reshoring of shaft forging and finishing operations.
Industry Challenges
- Heat Treatment Skill Scarcity:Case-hardening process engineers with expertise in controlled atmosphere carburizing are retiring faster than vocational programs replenish the talent pipeline.
- E-Axle Integration Complexity:Shaft suppliers must coordinate spline interfaces with motor reduction gearsets from competing Tier 1s, multiplying validation cycles and tooling costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Interconnecting Shaft Market |
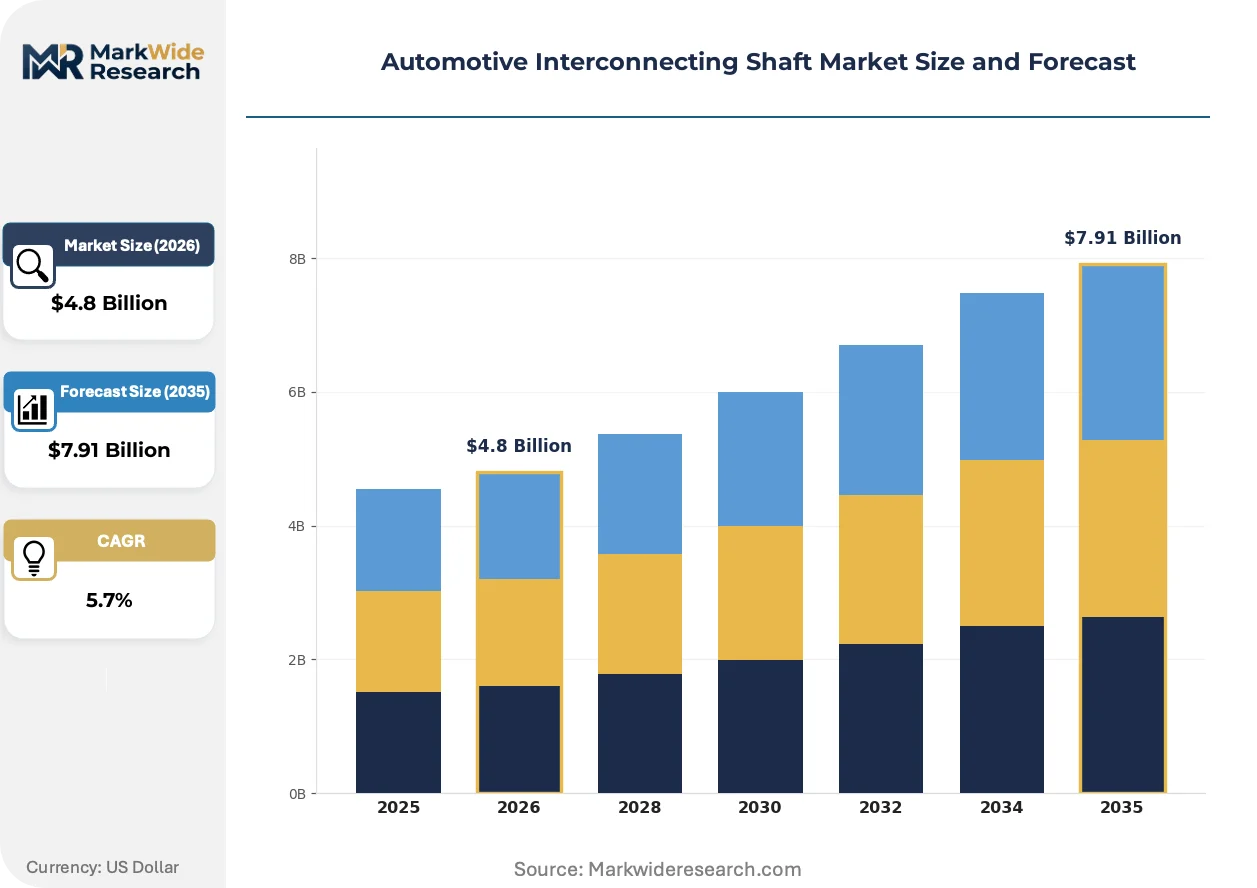
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Shafts, Hollow Shafts, Flexible Shafts, Composite Shafts End User: OEMs, Aftermarket Providers, Component Manufacturers, Fleet Operators Material: Steel, Aluminum, Carbon Fiber, Polymer Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles |
| Companies Covered | GKN Driveline, Dana Incorporated, ZF Friedrichshafen, Meritor, Neapco, JTEKT Corporation, American Axle & Manufacturing, SKF, Bharat Forge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Interconnecting Shaft Market Strategic Shifts
Manufacturing process digitization and material science advances are converging to redefine shaft performance benchmarks. Three developments are restructuring competitive capability requirements.
Topology-optimized hollow shafts with variable wall thickness are supplanting constant-section designs in premium EV platforms. European luxury OEMs specify these components for their dual-motor configurations, enabling 15-20% mass reduction without sacrificing torsional stiffness. The shift is compressing demand for conventional seamless tube suppliers lacking finite-element-driven forging expertise.
REACH substance disclosure mandates and the EU F-Gas Regulation are restricting fluoropolymer coating chemistries used for corrosion protection. Shaft manufacturers must reformulate surface treatments or qualify alternative plasma-deposited barriers. German Tier 1 suppliers are accelerating validation of chromium-free coating systems to maintain CE marking eligibility for European vehicle programs.
Fleet operators are consolidating specification authority previously dispersed across regional maintenance divisions. North American commercial vehicle lessors now mandate common shaft part numbers across tractor-trailer configurations, forcing suppliers to absorb customization costs or exit volume contracts. This concentration is visible most acutely in long-haul trucking corridors between Detroit and Dallas-Fort Worth.
Automotive Interconnecting Shaft Market Segmentation
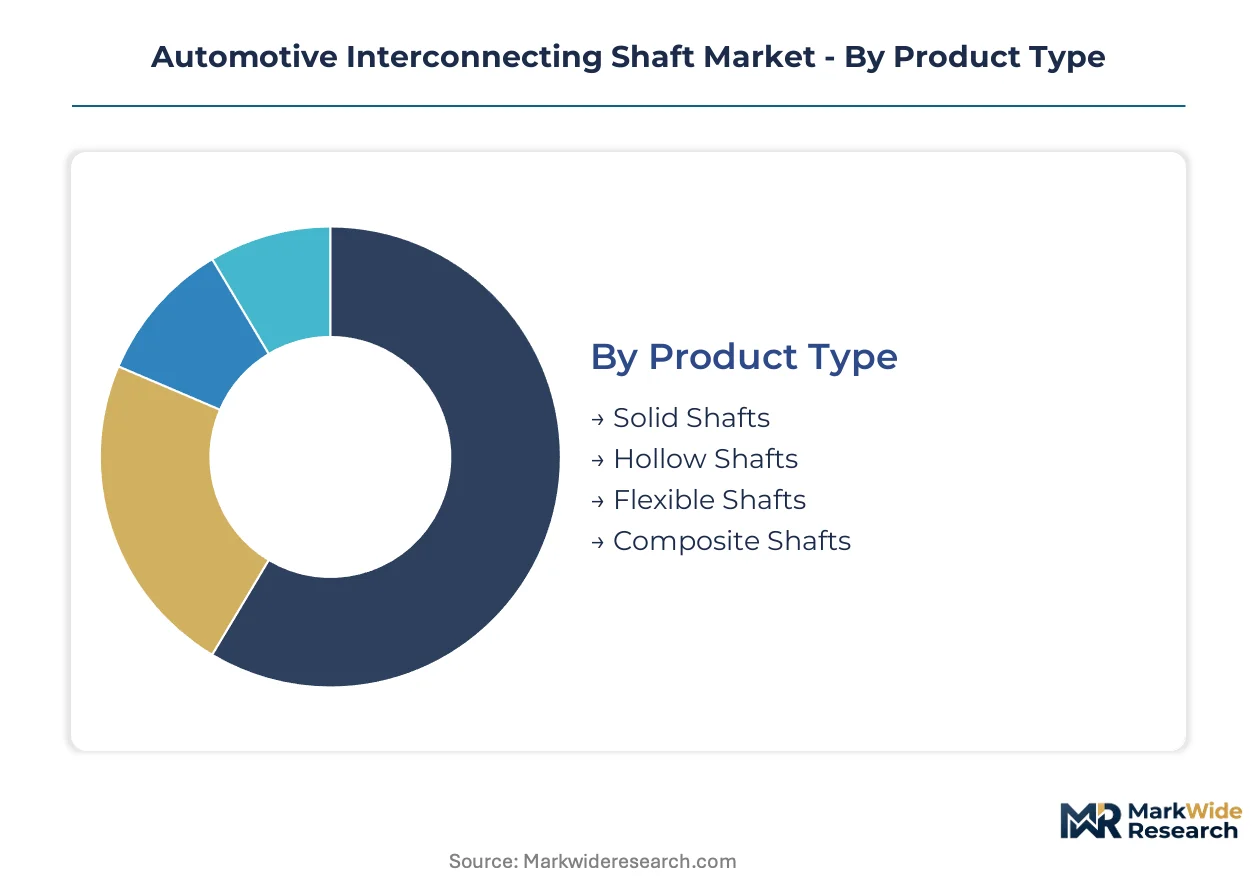
Segmentation in the Automotive Interconnecting Shaft Market reveals how powertrain electrification and material substitution are fragmenting traditional supply structures. Procurement patterns diverge sharply between legacy internal combustion platforms and emerging e-axle architectures, forcing suppliers to maintain parallel capability portfolios.
Product Type:
Composite shaft variants face the most acute substitution pressure from hollow steel designs, as cost-performance trade-offs favor proven metallurgy across volume segments.
- Hollow Shafts:Manufactured from case-hardened alloy steel with variable wall thickness optimized through finite-element analysis. European EV manufacturers specify these for dual-motor platforms where mass reduction preserves range without sacrificing torsional stiffness ratings.
- Solid Shafts:Conventional seamless construction dominates commercial vehicle and entry passenger car programs where cost minimization outweighs unsprung mass considerations. Indian bus manufacturers under BIS efficiency mandates retain solid designs for drivetrain simplicity.
- Flexible Shafts:Accommodate angular misalignment in multi-axle configurations and off-road applications requiring suspension articulation.
- Composite Shafts:Carbon fiber-reinforced polymer construction serves premium performance tiers where repairability constraints limit broader penetration.
Hollow shafts retain volume leadership; composite shafts hold the steepest expansion curve.
End User:
Procurement authority is consolidating downstream, with fleet operators and OEM specification engineers displacing traditional component distributor influence.
- OEMs:Direct supply relationships concentrate margin pools at specification-setting manufacturers who control spline interface standards and validation protocols for integrated e-axle modules.
- Fleet Operators:North American commercial vehicle lessors now mandate common part numbers across tractor-trailer configurations, forcing suppliers to absorb customization costs or exit volume contracts.
- Aftermarket Providers:Mature channels serve replacement demand with price-sensitive sourcing from certified remanufacturers.
- Component Manufacturers:Sub-tier suppliers perform heat treatment and finishing operations under OEM-directed material traceability requirements.
OEMs command specification authority; fleet operators are gaining procurement leverage fastest.
Material:
REACH substance disclosure and F-Gas Regulation restrictions are forcing surface treatment reformulation across metallic substrate categories.
- Steel:Case-hardening grade alloys remain dominant due to established fatigue performance exceeding 500,000 cycles and certified heat-treatment infrastructure in German manufacturing corridors.
- Carbon Fiber:Mass advantages of 40-60% versus steel attract EV range optimization programs, though repairability and end-of-life recycling constraints limit adoption below premium tiers.
- Aluminum:Intermediate density solution for hybrid architectures requiring moderate mass reduction without carbon fiber cost premiums.
- Polymer:Specialized applications in corrosion-resistant auxiliary drives and lightweight coupling elements.
Steel maintains installed base dominance; carbon fiber is climbing the fastest.
Application:
Vehicle electrification roadmaps are compressing demand concentration toward integrated e-axle platforms while fragmenting legacy segment growth trajectories.
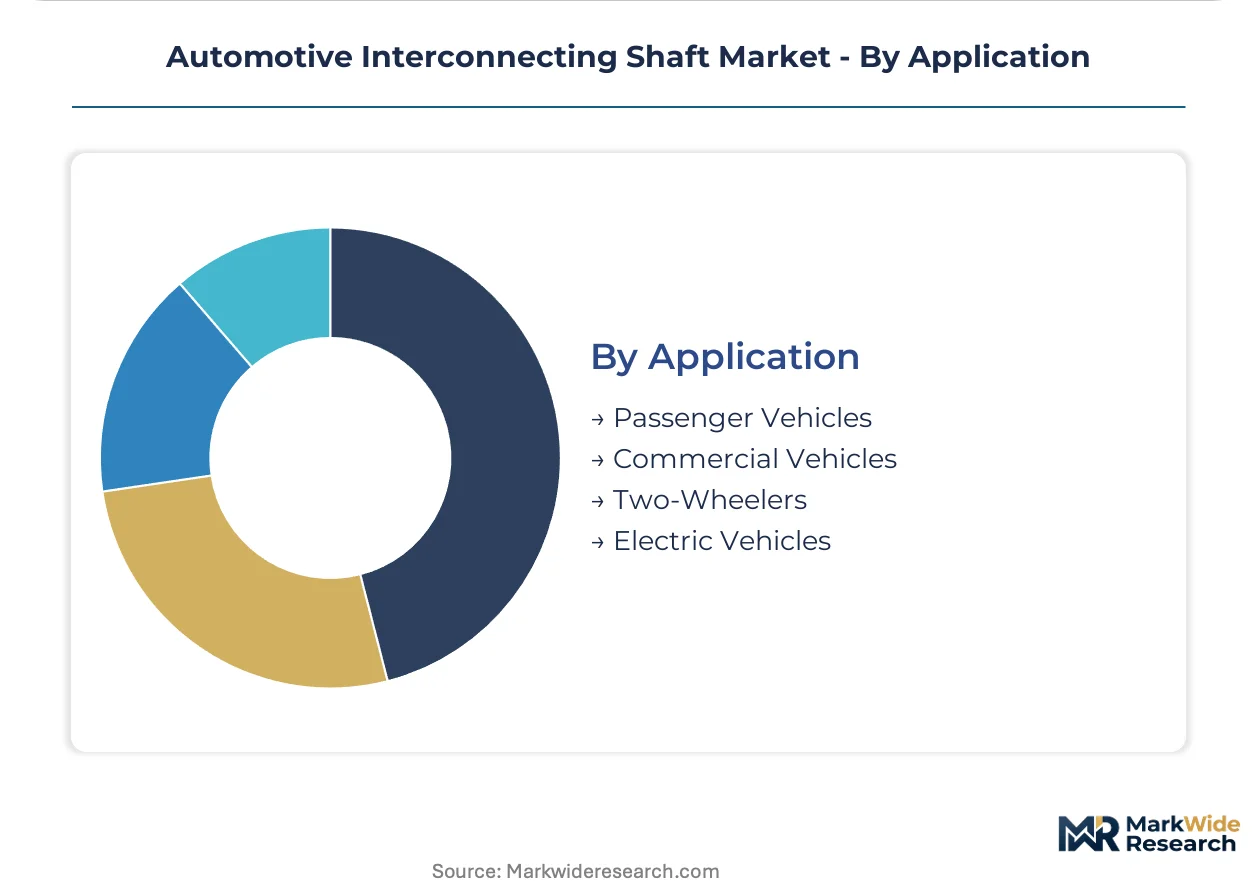
- Electric Vehicles:Battery electric platforms require hollow torque tubes with spline interfaces rated for instantaneous motor torque spikes and regenerative braking reversals. European luxury OEMs standardize these for dual-motor configurations.
- Commercial Vehicles:Heavy-duty forging requirements and vertical load ratings sustain demand for solid shaft architectures in long-haul corridors between Detroit and Dallas-Fort Worth.
- Passenger Vehicles:Declining internal combustion production is shifting procurement toward modular e-axle-compatible designs.
- Two-Wheelers:Lightweight shaft requirements for electric scooters and motorcycles under China's GB standards.
Commercial vehicles retain current volume leadership; electric vehicles hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr freight corridor and Port of Rotterdam container terminals sustain European automotive component flows, while China's Ningbo-Zhoushan port complex handles alloy steel feedstock for Asian forging operations.
Germany
Dual-motor EV platforms from Stuttgart and Munich OEMs require hollow torque tubes with variable wall thickness. KBA homologation protocols enforce fatigue testing standards exceeding 500,000 cycles. The Rhine-Ruhr corridor anchors Tier 1 forging capacity, with heat-treatment facilities clustered around Dortmund and Essen supplying e-axle modules.
United States
Long-haul commercial vehicle electrification between Detroit and Dallas-Fort Worth sustains solid shaft demand for heavy-duty applications. NHTSA crashworthiness standards and EPA fuel economy mandates compel hollow shaft specifications for passenger EV programs. Michigan-based forging operations serve domestic OEMs under IRA clean vehicle credit domestic content requirements.
China
GB standards from SAMR mandate material traceability and fatigue testing for electric two-wheeler and passenger vehicle shafts. The Yangtze River Delta manufacturing belt concentrates CNC machining capacity for spline interface production. Shanghai and Suzhou-based suppliers export hollow torque tubes to European EV platforms.
India
BIS efficiency mandates for commercial vehicle electrification drive bus and last-mile delivery fleet procurement. BIS certification requirements for heat-treated alloy steel elevate specification barriers for local manufacturers. Tamil Nadu and Maharashtra automotive corridors attract forging investments targeting domestic EV supply chains.
Japan
JIS standards govern spline interface tolerances for hybrid and battery electric powertrains. METI technology roadmaps prioritize mass reduction in drivetrain components. The Chubu region around Nagoya maintains precision forging expertise serving domestic and export OEM programs.
Automotive Interconnecting Shaft Market Competitive Environment
Listed leaders compete with private specialists across capital access and engineering agility. The supplier base concentrates around three strategic tiers: integrated driveline systems houses, standalone forging specialists, and material-science-focused component vendors. Consolidation pressure intensifies as e-axle integration demands expand validation capabilities. Dominant competitive moves include captive forging capacity expansion and mechatronics portfolio diversification.
Within the integrated systems tier, GKN Driveline and ZF Friedrichshafen exemplify full-driveline capability positions. Dana Incorporated anchors North American commercial vehicle supply. Bharat Forge represents scale-driven forging expertise from Indian manufacturing corridors. These three occupy archetype-defining positions across the competitive spectrum.
| Leading Market Players |
|---|
| GKN Driveline |
| Dana Incorporated |
| ZF Friedrichshafen |
| Meritor |
| Neapco |
| JTEKT Corporation |
| American Axle & Manufacturing |
| SKF |
| Bharat Forge |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber substitution dynamics in premium EV torque tubes simultaneously compress German forging margins and relocate value capture toward composite specialists in Japan and the United States, fragmenting pricing power across material tiers while EPA fuel economy mandates accelerate hollow steel specification in volume segments.
Pricing Analysis
Volume-discount tiering structures separate OEM direct supply contracts from aftermarket remanufacturer sourcing, with pricing stratifying across premium hollow shafts with variable wall thickness, standard seamless tube designs, and economy solid shafts for commercial vehicles. Price differentiation rests on KBA fatigue certification tiers and spline interface precision grades, with Tier 1 suppliers commanding premiums for e-axle validated designs. Cost compression in the aftermarket tier is intensifying because fleet operators now mandate common part numbers across tractor-trailer configurations. Aftermarket providers exhibit highest price sensitivity, while European luxury OEMs prioritize performance certification over unit cost.
Supply Chain Analysis
Rhine-Ruhr corridor heat-treatment capacity underwrites European e-axle supply security, with case-hardening grade alloy steel feedstock drawing from Dortmund-Essen forging clusters and Chinese Ningbo-Zhoushan port alloy imports. Raw material dependencies center on scrap metal markets, nickel-chromium alloying elements, and certified carburizing atmosphere gases. Single-source vulnerability concentrates in controlled atmosphere carburizing engineering expertise, where retiring process specialists outnumber vocational program graduates. Distribution runs through OEM-directed Tier 1 supply with captive finishing operations, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive interconnecting shaft market sits at a cyclical recovery phase driven by battery electric platform ramp cycles, with procurement authority consolidating downstream toward fleet operators and OEM specification engineers.
For Market Incumbents: Secure captive heat-treatment capacity in Tamil Nadu and Maharashtra corridors before BIS certification barriers harden for Indian commercial vehicle electrification. Deepen backward integration into case-hardening grade steel feedstock to offset alloy price volatility compressing forging margins. Defend against carbon fiber substitution threats by accelerating topology-optimized hollow shaft validation for dual-motor European platforms. For New Entrants and Emerging Players: Aftermarket fleet maintenance software integration represents an under-served service layer where incumbents lack digital-native capability, creating entry paths for data-driven shaft lifecycle management platforms. Target North American commercial vehicle lessors between Detroit and Dallas-Fort Worth with predictive maintenance bundled torque tube offerings. Pursue white-label manufacturing partnerships with Yangtze River Delta CNC machining specialists to bypass German supply concentration. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap forging specialists with certified e-axle validation capabilities and geographic diversification outside Rhine-Ruhr concentration. Long-term viability over the next decade hinges on torque vectoring integration expertise and mechatronics portfolio breadth. Monitor IRA domestic content requirement enforcement as the primary inflection signal for reshoring investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| E-Axle Platform Standardization | Reduces validation cycle duplication across BMW, Mercedes-Benz, and Volkswagen Group EV architectures. |
| Backward Integration into Heat Treatment | Captures margin pools from carburizing operations currently concentrated in Essen-Dortmund supplier clusters. |
| Composite Shaft Manufacturing Scale-Up | Addresses 40-60% mass reduction requirements from METI drivetrain roadmaps for Japanese OEM export programs. |
| Long-Term Alloy Steel Supply Agreement | Insulates forging margins from scrap metal and nickel-chromium volatility affecting case-hardening grades. |
| Torque Vectoring System Partnership | Enables shaft suppliers to capture value previously held by discrete differential manufacturers in mechatronics integration. |
Study Parameters
Operator-level perspectives from Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and heat-treatment facility managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed driveline suppliers, and customs records tracking alloy steel feedstock flows. Bottom-up shaft demand modeling triangulated against top-down automotive production forecasts across the analysis window.
Sensitivity analysis tested volume and value outputs against alternative powertrain electrification trajectories, with segmentation dimensions spanning propulsion architecture, vehicle class, material substrate, and regional production cluster. CAGRs were derived from regression-based trending of historical shipment data and scenario-weighted projections. Industry-specific forecast inputs incorporated EPA fleet efficiency target compliance schedules and KBA homologation protocol evolution for fatigue testing standards.
Underlying assumptions cover stable alloy steel feedstock availability and gradual carbon fiber cost curve decline, with deviation risk concentrated in heat treatment engineering talent pipeline collapse and IRA domestic content requirement enforcement timing. Practitioners should keep alternative scenarios live as REACH substance disclosure mandates and F-Gas Regulation coating restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Automotive Resonator Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Automotive Smart Actuator Market