
 Cosmetic Laser Market | 2026-2036
Cosmetic Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Laser Market Intelligence
Diode pump sources are decoupling cosmetic laser system costs from legacy flashlamp architectures, compressing bill-of-materials for mid-range platforms. Cynosure leverages captive fiber-coupled diode production to defend margin structure across its hair removal portfolio. Lumenis anchors its position through vertical integration into holmium and thulium crystal growth for urology and aesthetic dual-use platforms. Alma Lasers competes by extending its wavelength multiplexing architecture across diode, Nd:YAG, and Alexandrite channels from a unified chassis design.
Cosmetic lasers are coherent light sources operating at specific wavelengths between 532 nm and 10,600 nm, selectively absorbed by chromophores in skin tissue to achieve photothermolysis with controlled thermal damage zones; their primary purpose is aesthetic modification of skin, hair, and vascular structures without invasive incision. Ablative laser platforms, particularly CO₂ and Er:YAG systems, command premium pricing in skin resurfacing due to their single-treatment efficacy profile and higher consumable attach rates. Non-ablative lasers and intense pulsed light systems occupy the volume tier, where dermatology clinics amortize equipment costs across high-frequency hair removal and pigmentation protocols. Home-use diode devices represent the fastest-growing technology tier, though margin pools remain concentrated in professional-installed base segments.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for laser systems marketed in Europe. China's NMPA classifies high-power aesthetic lasers as Class III medical devices, extending registration timelines for foreign manufacturers. Japan's PMDA maintains stringent adverse event reporting that shapes post-market surveillance obligations for imported platforms. Stakeholders must monitor evolving reimbursement classifications for aesthetic procedures across national health systems, as private-pay dynamics shift toward outcome-based clinic pricing models.
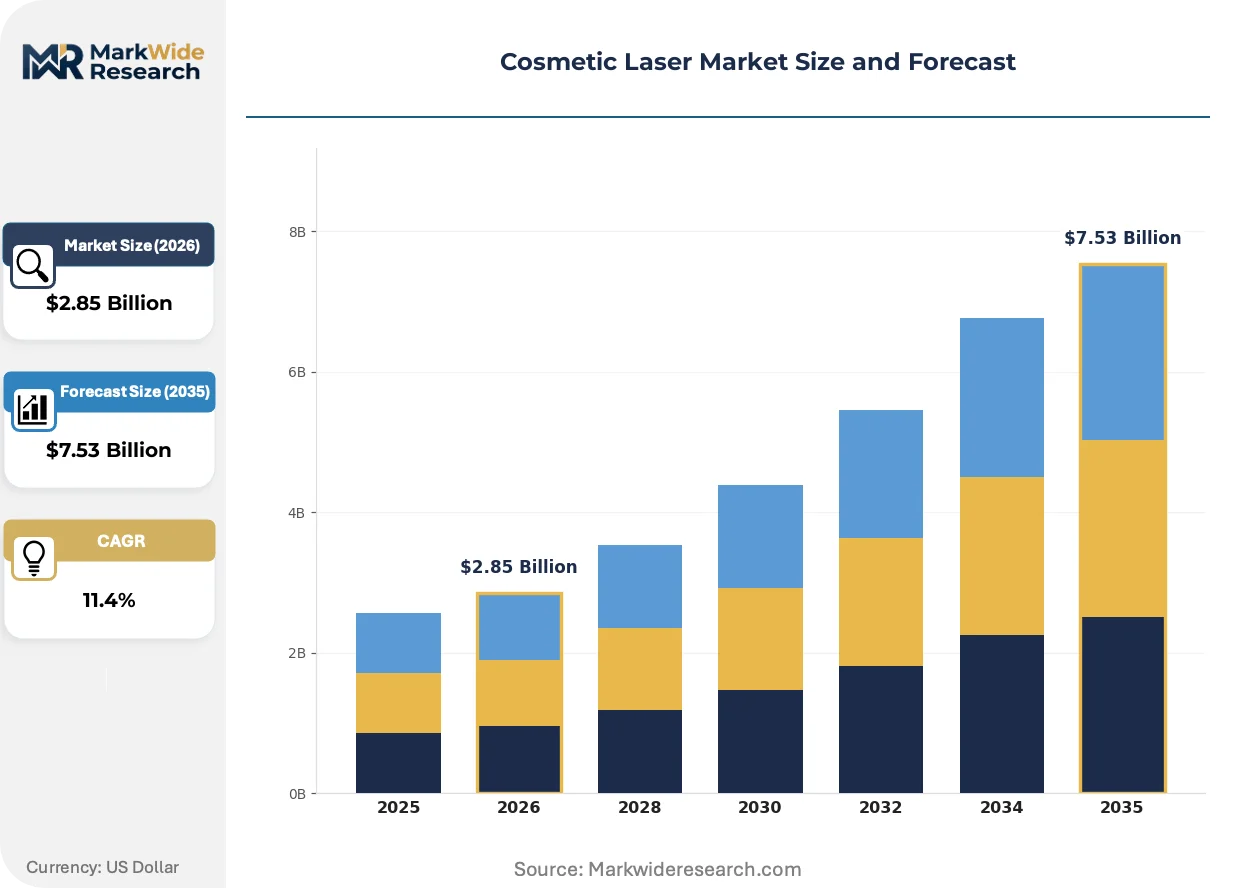
Market Dynamics
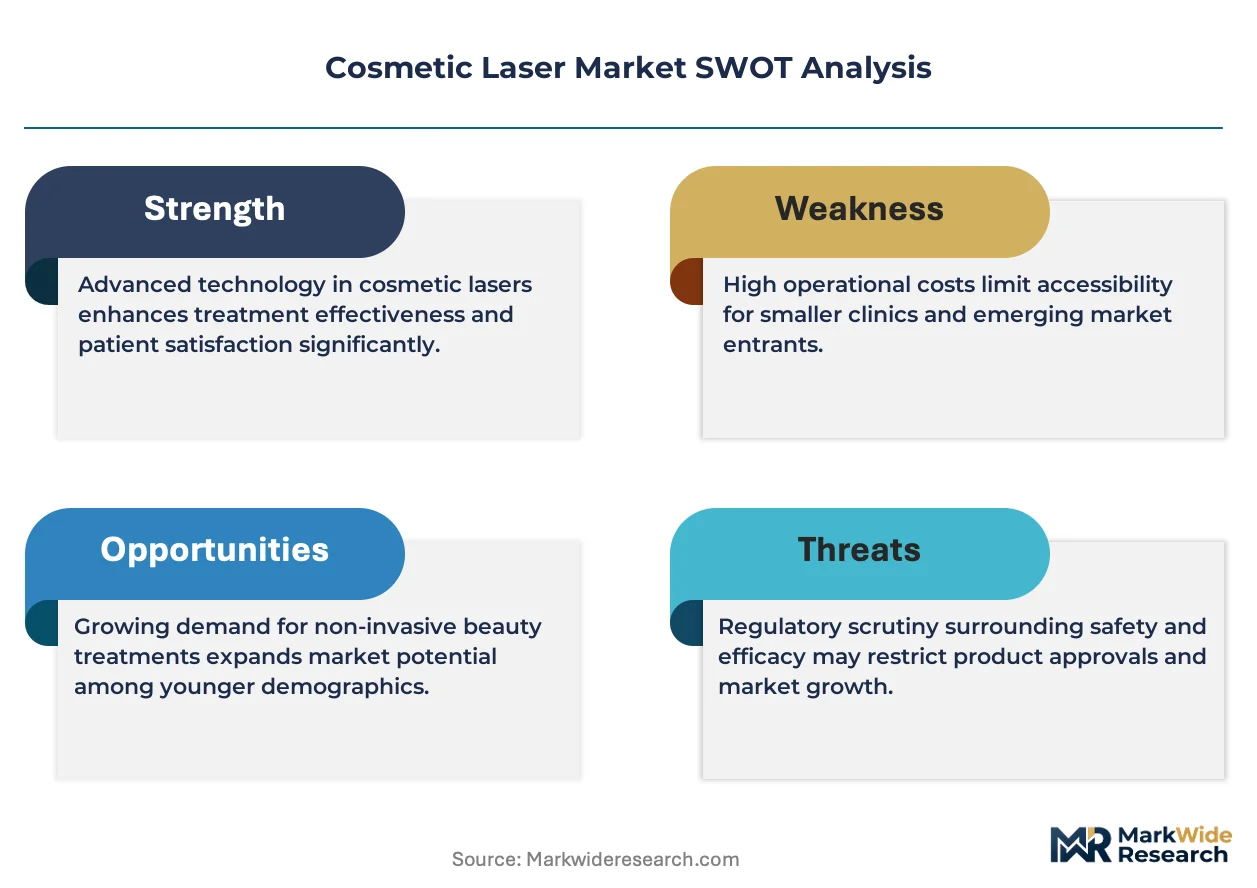
Diode pump sources are compressing system costs and decoupling mid-range platform economics from legacy flashlamp architectures, reshaping competitive positioning across hair removal and skin resurfacing segments.
Growth Catalysts
- FDA 510(k) pathway efficiency:Streamlined premarket notification for laser-assisted devices accelerates product launch timelines for manufacturers targeting the US aesthetic device market.
- Medical spa professionalization:China's tier-one cities are driving demand as facilities upgrade service offerings beyond traditional beauty salons toward clinical-grade protocols.
- Fractional laser adoption:Dermatology clinics in Seoul are expanding installed base capacity as patient demand for non-invasive skin resurfacing protocols intensifies.
Market Restraints
- Holmium/thulium crystal supply concentration:Upstream control over specialized laser crystal growth creates input cost volatility for dual-use urology and aesthetic platforms.
- China NMPA Class III registration:Extended timelines for foreign manufacturers create regulatory friction in the world's fastest-growing aesthetic device market.
- IPL substitution pressure:Non-laser intense pulsed light systems capture volume-tier hair removal and pigmentation protocols at lower equipment price points.
Strategic Opportunities
- Home-use diode penetration:Consumer-grade devices represent the fastest-growing technology tier as at-home hair removal protocols gain clinical credibility.
- Wavelength multiplexing expansion:Unified chassis designs spanning diode, Nd:YAG, and Alexandrite channels enable platform consolidation for multi-service clinics.
- EU MDR conformity positioning:Early notified body assessment completion creates first-mover advantage for European market access post-legacy directive sunset.
Industry Challenges
- Laser safety officer certification:Talent scarcity for certified clinical operators constrains clinic expansion velocity in high-growth metropolitan markets.
- Consumable attach rate engineering:Equipment manufacturers face capex intensity pressure to design systems with recurring revenue streams that amortize platform costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Laser Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ablative Lasers, Non-Ablative Lasers, Diode Lasers, Nd:YAG Lasers Application: Skin Resurfacing, Hair Removal, Pigmentation, Vascular Lesions End User: Dermatology Clinics, Medical Spas, Hospitals, Home Users Technology: Laser-assisted, Radiofrequency, Intense Pulsed Light, Fractional |
| Companies Covered | Cynosure, Lumenis, Candela Medical, Alma Lasers, Cutera, Fotona, Sciton, Solta Medical, El.En., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Laser Market Strategic Shifts & Innovations
Platform architecture unification and regulatory pathway optimization are compressing development cycles while reshaping how clinics procure and deploy aesthetic laser systems across service tiers.
Fractional laser technology is converging with radiofrequency delivery mechanisms to create hybrid platforms that address skin laxity and texture in single treatment sessions. Medical spas and dermatology groups in Seoul and Shanghai are piloting these dual-modality systems to differentiate premium service tiers. The convergence is compressing addressable market boundaries between standalone laser and energy-based device categories.
Japan's PMDA adverse event reporting mandates are tightening post-market surveillance obligations for imported aesthetic platforms. Manufacturers must now maintain localized clinical data repositories and rapid response protocols for device malfunction investigations. The regulation most heavily affects fractional CO₂ and ablative resurfacing systems where thermal injury risk profiles are elevated.
Clinic procurement patterns are rotating toward outcome-based equipment financing rather than traditional capital purchase or lease structures. Device manufacturers in Germany and South Korea are responding with performance-guaranteed placement models that tie payments to treatment utilization thresholds. This shift is most visible among multi-site dermatology chains seeking to reduce balance sheet exposure to technology obsolescence cycles.
Cosmetic Laser Market Segmentation
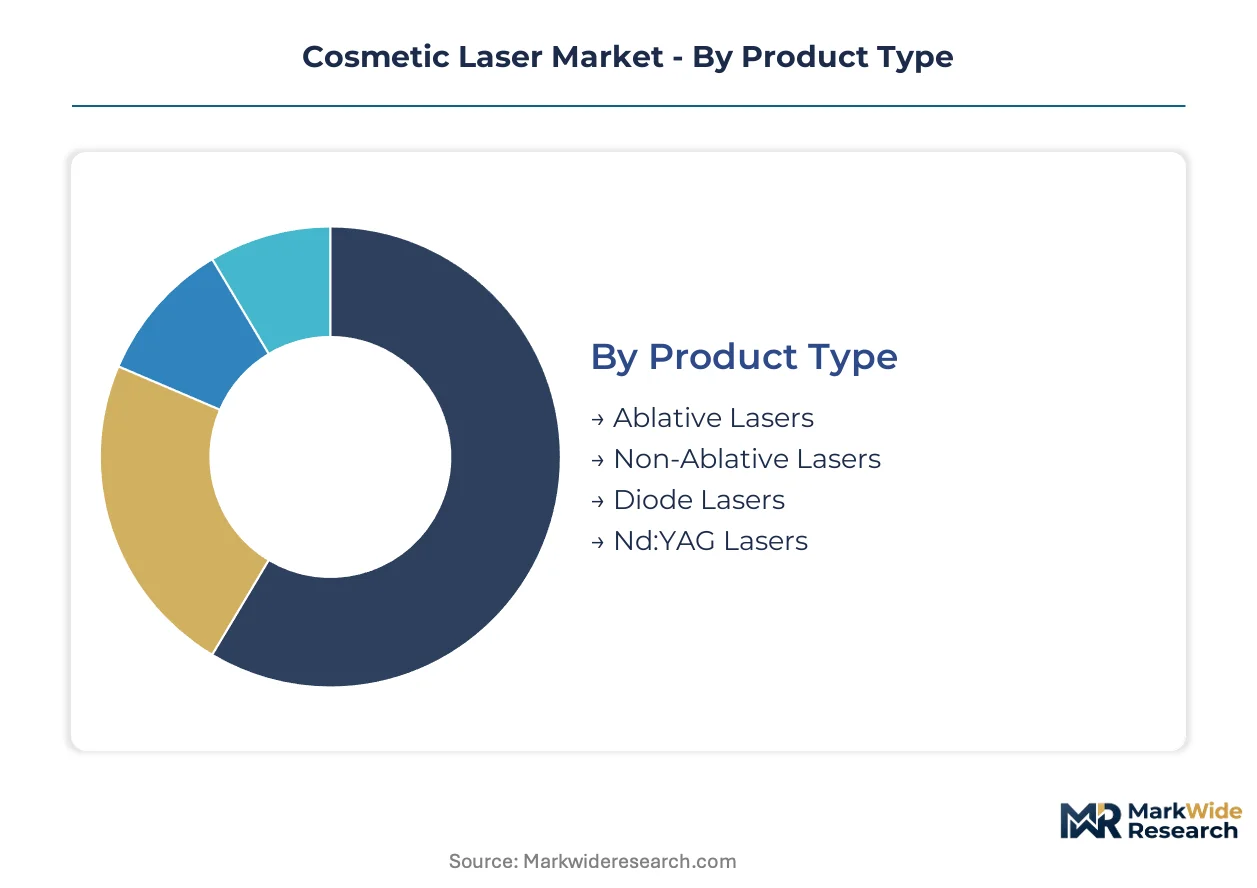
Cosmetic laser segmentation reveals how technology specialization and treatment setting dictate procurement patterns, pricing tiers, and regulatory exposure across the aesthetic device value chain.
Product Type:
Customization versus standardization tension runs deepest here, with configurable wavelength platforms commanding premium positioning against fixed-specification systems.
- Ablative Lasers:CO₂ and Er:YAG systems deliver controlled thermal injury to the epidermis and superficial dermis, triggering collagen remodeling through wound healing cascades. Dermatology clinics in Seoul prioritize these platforms for single-treatment efficacy protocols despite extended recovery windows.
- Non-Ablative Lasers:Subsurface heating without epidermal disruption enables minimal-downtime protocols for working professionals. Medical spas in China's tier-one cities are standardizing these systems as entry points for patient acquisition before upselling to ablative treatments.
- Diode Lasers:Compact, efficient pump sources dominate high-volume hair removal with lower consumable burdens than flashlamp architectures.
- Nd:YAG Lasers:Longer 1064 nm wavelength penetrates deeper for darker skin phototypes, expanding addressable patient populations in diverse metropolitan markets.
Leading the category by volume: Non-Ablative Lasers. Growing fastest: Diode Lasers.
Application:
Procedure reimbursement status and treatment frequency separate high-rotation revenue generators from premium episodic interventions.
- Skin Resurfacing:Fractional and fully ablative modalities address photodamage, scarring, and rhytides through controlled thermal column formation. FDA 510(k) clearance pathways for new resurfacing platforms remain rigorous given thermal injury risk profiles.
- Hair Removal:Diode and Alexandrite wavelengths target melanin in the hair bulb with repetitive pulse sequences. China's medical spa professionalization wave is concentrating demand here as facilities upgrade from IPL to laser-based permanent reduction protocols.
- Pigmentation:Q-switched lasers fragment melanin deposits for solar lentigines and post-inflammatory hyperpigmentation clearance.
- Vascular Lesions:Pulsed dye and long-pulse Nd:YAG systems coalesce hemoglobin for telangiectasia and hemangioma treatment.
Dominant by procedure volume: Hair Removal. Steepest expansion trajectory: Skin Resurfacing.
End User:
Capital intensity and clinical oversight requirements fragment procurement behavior across institutional and consumer purchasing contexts.
- Dermatology Clinics:Physician-supervised settings deploy multi-wavelength platforms across ablative, non-ablative, and vascular indications. Seoul's clinic density is driving installed base expansion for fractional resurfacing systems specifically.
- Medical Spas:Non-physician operated facilities in Shanghai and Beijing are migrating from beauty salon origins toward clinical-grade service tiers with certified laser safety officers.
- Hospitals:Academic medical centers maintain ablative platforms for scar revision and reconstructive applications.
- Home Users:Consumer-grade diode devices with reduced fluence settings are penetrating at-home hair removal with lower price points and simplified safety interlocks.
Highest equipment spend per site: Dermatology Clinics. Gaining share fastest: Home Users.
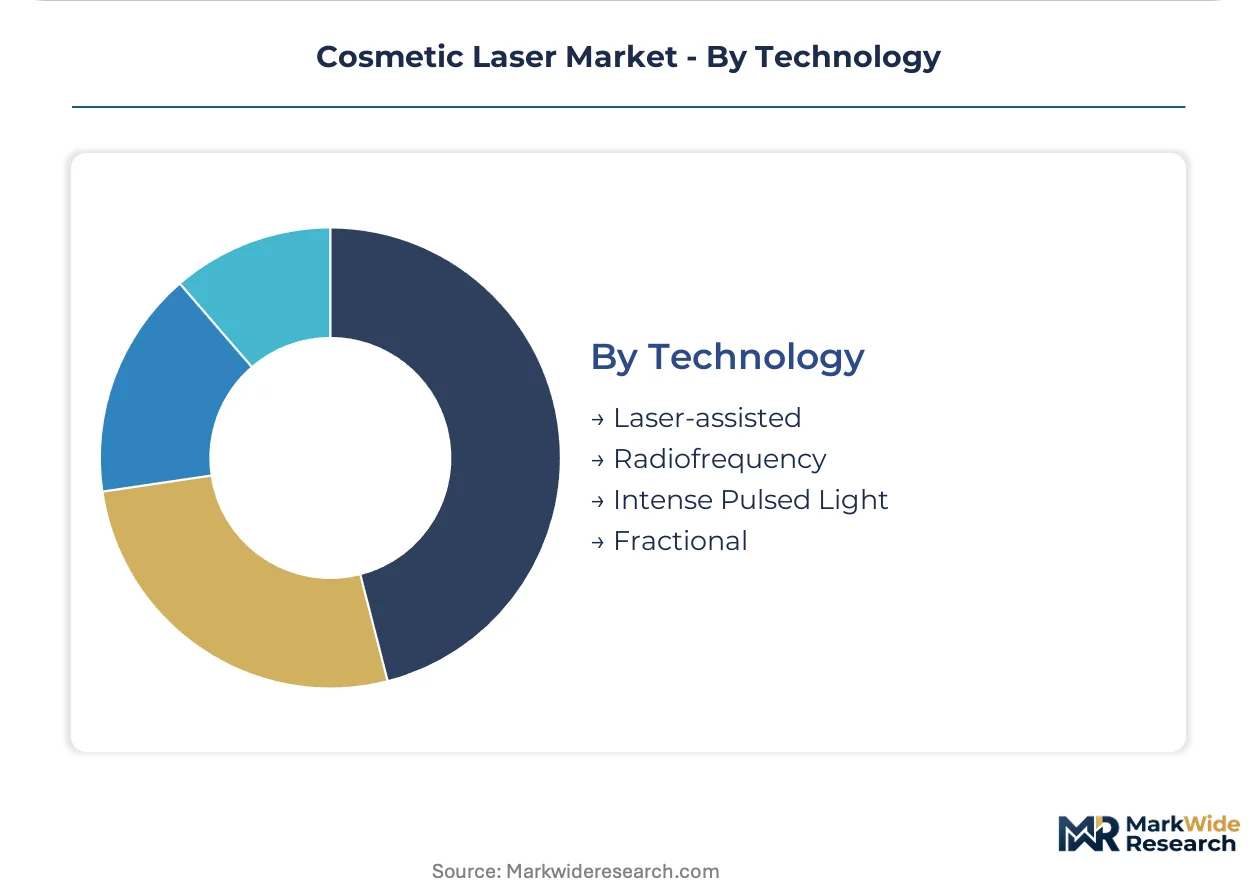
Technology:
Energy delivery mechanism determines regulatory classification, training burden, and competitive substitution risk from adjacent aesthetic device categories.
- Laser-assisted:Coherent, monochromatic emission enables precise chromophore targeting with minimal collateral thermal diffusion. NMPA Class III registration timelines in China create regulatory friction for foreign manufacturers introducing new laser platforms.
- Radiofrequency:Non-optical energy delivery addresses skin laxity through dermal heating independent of melanin absorption, expanding treatable skin phototypes.
- Intense Pulsed Light:Broadband emission captures volume-tier hair removal and pigmentation at lower equipment price points, pressuring laser substitution.
- Fractional:Microthermal zone delivery balances efficacy with recovery time, now converging with RF in hybrid platform architectures.
Installed base leader: Laser-assisted. Expanding most quickly: Fractional.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient demand concentrates in metropolitan clusters where medical spa professionalization and dermatology clinic density create concentrated equipment procurement. Regulatory divergence across national health authorities fragments market access timelines for platform manufacturers. Capital deployment patterns track urban disposable income gradients rather than national population aggregates.
United States
FDA 510(k) clearance efficiency accelerates product launch timelines for hair removal and resurfacing platforms targeting medical spas and dermatology groups. The FDA maintains rigorous thermal injury risk profiles for ablative systems, extending review cycles for fractional CO₂ devices. Clinic procurement concentrates in Miami, Los Angeles, and New York Metro where multi-site chains pilot outcome-based equipment financing models.
South Korea
Seoul's dermatology clinic density drives installed base expansion for fractional laser systems as non-invasive skin resurfacing protocols intensify patient throughput. The MFDS regulates high-power aesthetic lasers under medical device classification schemes that parallel FDA risk stratification. The Seoul Capital Area anchors domestic demand while Busan-Ulsan clusters support component fabrication for diode pump sources.
China
Tier-one cities including Shanghai and Beijing concentrate medical spa professionalization as facilities upgrade from beauty salon origins toward clinical-grade service tiers. NMPA Class III registration timelines for foreign manufacturers create regulatory friction in the world's fastest-growing aesthetic device market. The Yangtze River Delta and Pearl River Delta house the majority of domestic laser system assembly operations.
Germany
EU MDR conformity assessment completion creates first-mover advantage for European market access as legacy directive frameworks sunset. Notified body evaluation of laser-assisted devices mandates clinical evidence packages that extend preparation timelines for resurfacing platforms. Bavaria and Baden-Württemberg host precision optics clusters supplying crystal growth and fiber-coupled diode components.
Japan
PMDA adverse event reporting mandates tighten post-market surveillance obligations for imported fractional and ablative platforms. Thermal injury risk profiles for CO₂ systems trigger localized clinical data repository requirements and rapid response protocols for device malfunction investigations. The Kanto region surrounding Tokyo concentrates dermatology clinic demand and distributor headquarters for foreign manufacturers.
Cosmetic Laser Market Key Industry Players
Platform architecture unification dominates the current landscape as manufacturers compress development cycles and consolidate wavelength multiplexing across unified chassis designs. The vendor base stratifies between vertically integrated crystal growers, modular platform assemblers, and consumer-grade device specialists. Three archetypes anchor competitive positioning: captive supply chain operators, wavelength-agnostic chassis designers, and home-use penetration specialists. Technology licensing and outcome-based equipment financing represent the dominant competitive moves reshaping clinic relationships.
Within the integrated manufacturing tier, Lumenis exemplifies upstream control over specialized crystal growth for dual-use platforms, while Alma Lasers occupies a position as the wavelength multiplexing architect spanning diode, Nd:YAG, and Alexandrite channels. Cynosure anchors the captive component production archetype through in-house fiber-coupled diode supply for hair removal portfolios. These three entities represent divergent responses to cost compression pressures from diode pump source substitution.
| Leading Market Players |
|---|
| Cynosure |
| Lumenis |
| Candela Medical |
| Alma Lasers |
| Cutera |
| Fotona |
| Sciton |
| Solta Medical |
| El.En. |
| Others |
Cost & Logistics Intelligence
Holmium and thulium crystal spot pricing volatility cascades through aesthetic laser manufacturing into three-tier pricing stratification across premium ablative platforms, mid-range diode systems, and economy-tier IPL alternatives. Manufacturers with captive crystal growth capabilities in Bavaria and Baden-Württemberg capture margin insulation against input cost swings that squeeze modular assemblers dependent on merchant supply.
Pricing Analysis
Volume-tier hair removal equipment trades at compressed margins where diode pump source standardization erodes differentiation, while ablative resurfacing platforms maintain premium positioning through consumable attach rates and single-treatment efficacy claims. Price differentiation hinges on FDA 510(k) clearance tier and wavelength multiplexing capability, with certified clinical-grade systems commanding substantial premiums over unregistered salon-tier alternatives. Pricing pressure stems from IPL substitution in high-frequency protocols, eroding diode laser equipment margins in China's medical spa segment. Dermatology clinics exhibit lowest price sensitivity due to outcome-based patient billing, while independent medical spas in tier-two Chinese cities negotiate aggressively on capital equipment.
Supply Chain Analysis
Direct-to-clinic channels handle high-value ablative platform deployments, while distributor networks manage mid-range system logistics across fragmented medical spa markets. Geographic supply concentration centers on Germany for precision optics and crystal growth, South Korea for diode pump source fabrication, and China for final system assembly and domestic market distribution. Raw material dependencies include rare-earth doped crystals, fiber-coupled diode bars, and specialized optical coatings. Single-source vulnerability in holmium crystal growth creates procurement risk for dual-use urology and aesthetic platform manufacturers. Distribution runs through authorized service partners requiring laser safety officer certification, constraining channel expansion velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR notified body assessment timelines and NMPA Class III registration requirements erect barrier-to-entry moats favoring manufacturers with established regulatory affairs infrastructure and localized clinical data repositories.
For Market Incumbents: Acquire specialized laser crystal growth assets to secure input cost predictability against holmium supply concentration. Consolidate wavelength multiplexing IP through targeted licensing to defend platform architecture differentiation from emerging modular competitors. Channel control through certified service partner networks represents the critical defensive lever against price erosion in high-volume hair removal segments. For New Entrants and Emerging Players: Home-use consumer segments present the most penetrable white-space opportunity as clinical credibility for at-home diode protocols expands. Secondary targets include underserved medical spas in China's tier-two cities where professionalization waves lag Shanghai and Beijing. A software-companion go-to-market angle enabling treatment protocol customization differentiates against incumbent hardware-centric positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor wavelength-agnostic platform assemblers with EU MDR conformity completion in Germany and South Korea. Long-term viability across the analysis window hinges on recurring revenue model traction through consumable attach rates rather than pure equipment placement economics. The signal to monitor is NMPA registration timeline compression for foreign manufacturers, which would accelerate competitive entry dynamics in the world's fastest-growing aesthetic device market.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined premarket notification accelerates US market entry for resurfacing platforms against thermal injury risk scrutiny. |
| Wavelength Multiplexing Expansion | Unified chassis designs spanning diode, Nd:YAG, and Alexandrite channels reduce clinic capital intensity across service tiers. |
| Outcome-Based Equipment Financing | Performance-guaranteed placement models tie payments to utilization thresholds, reducing dermatology chain balance sheet exposure. |
| Home-Use Diode Penetration | Consumer-grade devices with simplified safety interlocks capture at-home hair removal demand with lower price points. |
| Laser Safety Officer Certification Programs | Talent pipeline development addresses operator scarcity constraining clinic expansion in high-growth metropolitan markets. |
Research Approach
Independent corroboration across regulatory filing databases, hospital procurement records, and medical spa operator surveys underwrites the qualitative findings in this analysis. Primary interviews with biomedical engineers, dermatology clinic purchasing committees, GPO contracts managers, and laser safety officers combined with secondary validation from FDA 510(k) databases, NMPA registration filings, and EU MDR notified body assessment records. Bottom-up equipment placement tracking and top-down market sizing triangulate volume estimates across the projection horizon.
Rate-of-change decomposition separates volume expansion from value growth across wavelength technology, application protocol, end-user setting, and regional regulatory cluster dimensions. CAGRs derive from installed base turnover modeling, procedure frequency assumptions, and equipment replacement cycle analysis. Industry-specific forecast inputs include NMPA Class III registration timeline trajectories for foreign manufacturers and medical spa professionalization velocity in China's urban hierarchy.
Revisions become necessary when NMPA regulatory pathway simplification, EU MDR notified body capacity expansion, or home-use device safety incident clusters materialize. Forecasts reflect documented assumptions regarding procedure reimbursement stability and private-pay clinic pricing model persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Germany Hair Transplant Market