
 PS Containers Market | 2026-2036
PS Containers Market Size, Share, and Industry Trends Forecast 2026-2036
PS Containers Market Analytics
Polystyrene extrusion technician availability is rotating toward thermoforming automation, tightening labor pools for conventional sheet-fed operations. Amcor Plc leverages its integrated resin-to-container platform across multiple geographies. Berry Global Group Inc. anchors North American thermoformed tray capacity through sustained capital deployment. Silgan Holdings Inc. specializes in thin-wall injection molding for food service applications.
PS containers are thermoformed or injection-molded vessels fabricated from general-purpose or high-impact polystyrene resin, typically offering clarity, rigidity, and moisture barrier properties at densities near 1.04–1.06 g/cm³; manufacturers process resin through sheet extrusion followed by vacuum forming, or direct injection into multi-cavity molds, to produce packaging for retail food, pharmaceutical, and consumer goods sectors. Rigid Containers dominate volume throughput due to entrenched dairy and deli packaging demand, while Flexible Containers capture emerging ready-meal and portion-control applications where downgauging reduces material intensity. Trays retain the densest margin pool because custom tooling and short-run flexibility command premium pricing from protein and prepared-food processors.
FDA food contact substance regulations govern resin purity and additive migration limits for US-bound PS containers, while REACH restricts styrene monomer residual thresholds in European supply chains, and China's GB standards mandate recyclability labeling that shapes export-oriented production decisions. ECHA substance evaluation protocols are extending scrutiny to flame retardant additives in expanded polystyrene variants, pressuring reformulation timelines. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure dual-market certification ahead of compliance phase-ins.
Market Dynamics
Thermoforming automation is fragmenting labor pools for conventional sheet-fed PS container operations, compressing technician availability while reshaping production economics across food packaging supply chains.
Growth Catalysts
- Single-use food packaging demand:Dairy and deli processors in Germany, China, and the United States sustain rigid container volume through entrenched retail distribution patterns.
- REACH compliance deadlines:European styrene monomer residual thresholds are forcing resin purification investments that upgrade material specifications for export markets.
- Downgauging technology:Flexible container formats for ready-meal applications reduce material intensity while preserving barrier performance.
Market Restraints
- Styrene feedstock volatility:Benzene price swings transmit directly to PS resin costs, squeezing converter margins without pricing power recovery mechanisms.
- Recyclability labeling mandates:China's GB standards create compliance friction for export-oriented manufacturers serving multiple jurisdictions.
- Paperboard substitution:Fiber-based alternatives capture prepared-food tray applications where moisture resistance requirements moderate.
Strategic Opportunities
- Portion-control packaging:Protein processors seek custom short-run tooling for single-serve formats that command premium positioning.
- Flame retardant reformulation:ECHA substance evaluation protocols create first-mover advantage for additive suppliers with compliant expanded polystyrene variants.
- Direct-to-retail channel expansion:Prepared-food brands bypass traditional distribution through captive thermoforming partnerships.
Industry Challenges
- Extrusion technician scarcity:Workforce rotation toward automated thermoforming lines leaves conventional sheet-fed operations understaffed.
- Dual-market certification complexity:FDA food contact substance rules and REACH thresholds require parallel testing protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PS Containers Market |
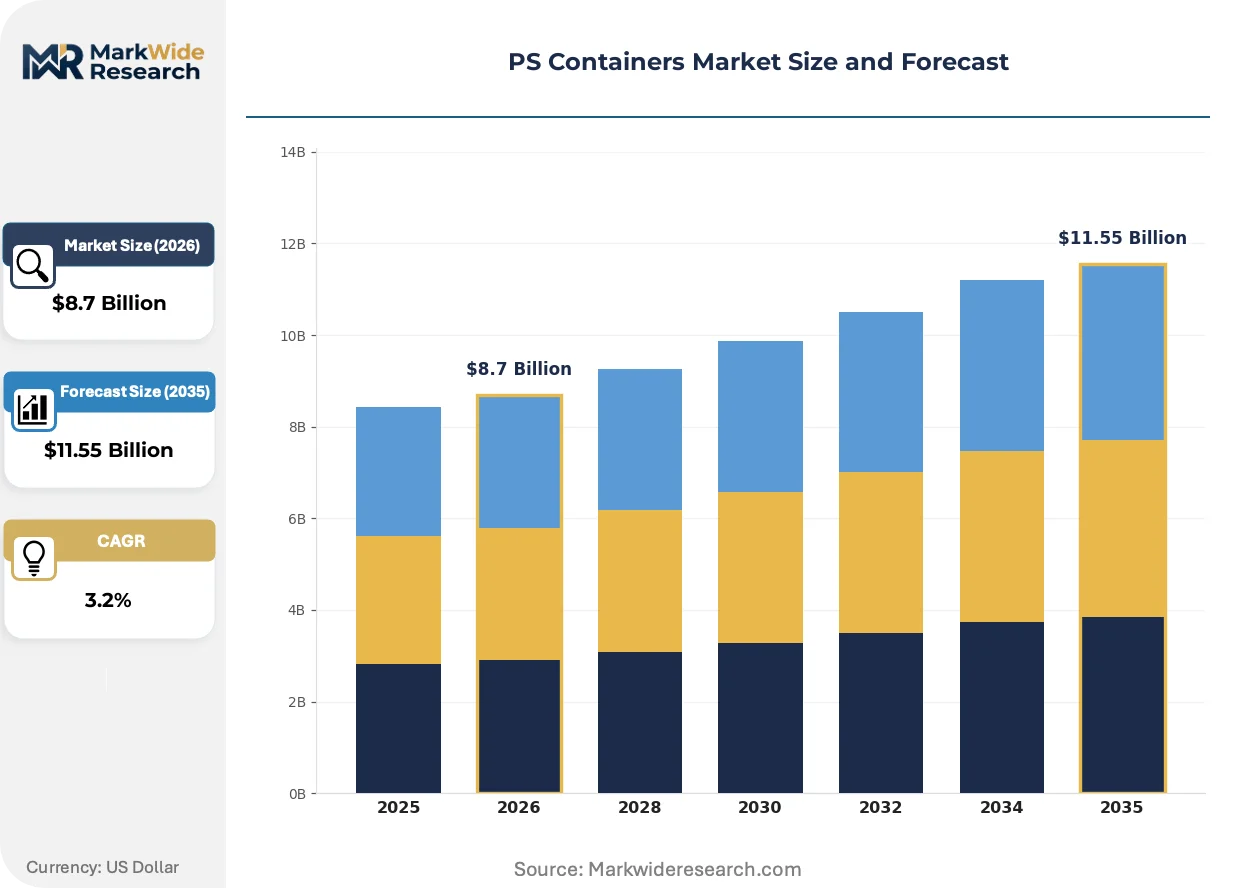
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Containers, Flexible Containers, Trays, Bottles Material: Polystyrene, Polyethylene, Polypropylene, PET End User: Food Industry, Pharmaceutical, Cosmetic, Household Products Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Distributors |
| Companies Covered | Amcor Plc, Berry Global Group Inc., Silgan Holdings Inc., Pactiv LLC, Sonoco Products Company, ALPLA, Plastipak Holdings Inc., DS Smith Plc, SIG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PS Containers Market Evolving Landscape
Automation, regulatory divergence, and channel restructuring are simultaneously compressing legacy operating models while opening specialized niches for adaptive converters.
Multi-cavity thin-wall injection molding is fragmenting equipment investment strategies across food service container manufacturing. QSR chains and institutional catering buyers are adopting these formats for cutlery and lid applications where weight reduction offsets material cost premiums. The technology is fragmenting regional supply patterns as toolmakers concentrate near major dairy processing clusters in Wisconsin and Bavaria.
REACH substance evaluation protocols are extending scrutiny to brominated flame retardants in expanded polystyrene insulation-to-packaging crossover applications. Industrial converters face 18-24 month reformulation windows to maintain European market access without supply interruption. Protein tray manufacturers serving German retail are accelerating additive substitution timelines ahead of formal restriction phase-ins.
Consolidated procurement by prepared-food brands is compressing supplier rosters toward converters with captive resin supply and in-house toolmaking capability. Regional dairy processors are shifting from spot purchasing to multi-year volume commitments that lock in capacity at integrated facilities. This concentration is most visible in the United States, where national deli chains now specify single-source thermoforming partnerships for private-label packaging programs.
PS Containers Market Segmentation
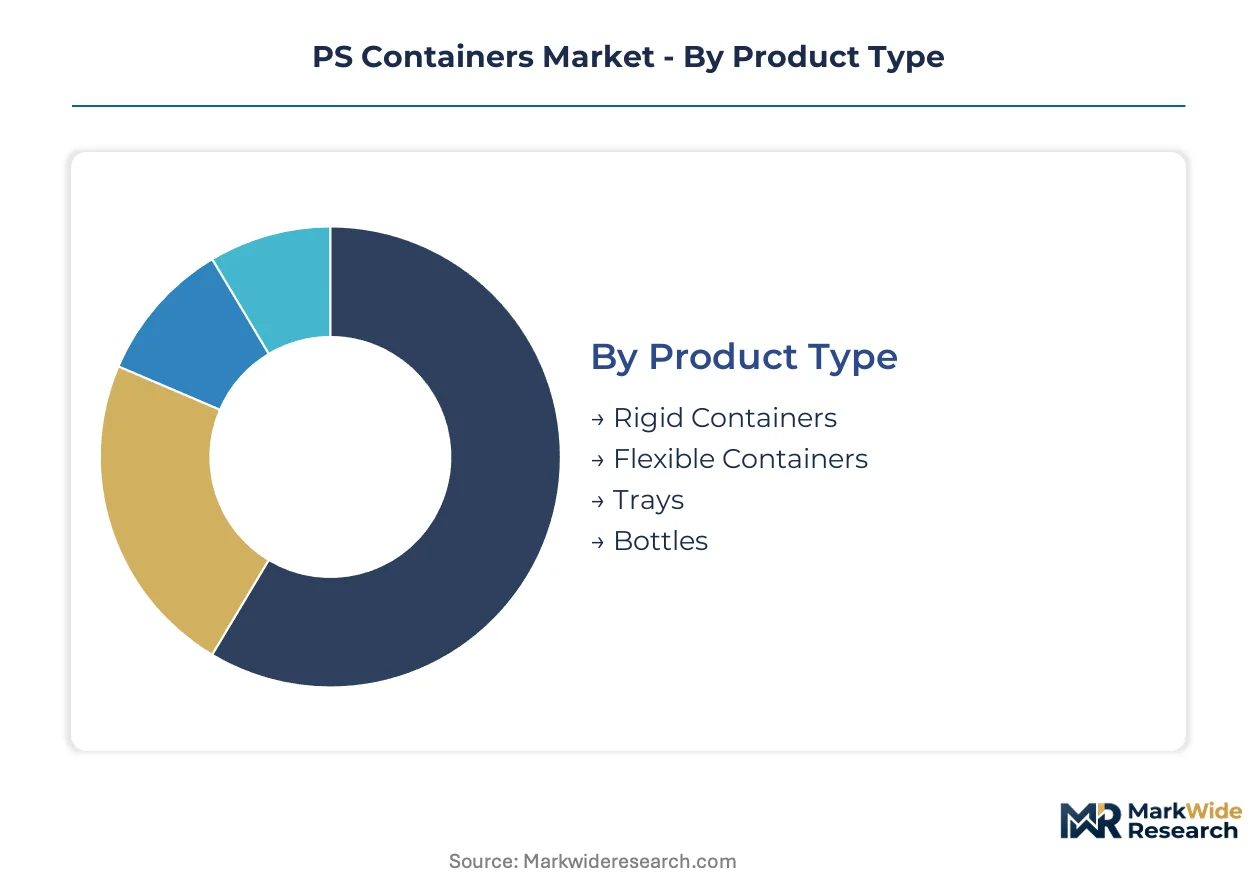
Segmentation in the PS containers market exposes vulnerability gradients across substitute materials and channel structures. Product format and resin selection determine exposure to paperboard and bioplastic displacement, while end-use concentration in food service creates asymmetric risk profiles.
Product Type:
Substitution pressure from fiber-based alternatives concentrates in formats where moisture resistance requirements moderate, leaving rigid formats most exposed to regulatory-driven material switching.
- Rigid Containers:Thermoformed or injection-molded vessels with wall thickness above 0.5mm serving dairy, deli, and institutional food service. Germany's retail chains specify these for extended shelf-life cheese and processed meat applications where dimensional stability under refrigerated distribution is non-negotiable.
- Trays:Custom-tooled shallow vessels for protein and prepared-food presentation, commanding premium positioning through short-run flexibility and proprietary cavity designs. Protein processors in Wisconsin and Bavaria lock in multi-year capacity commitments for these formats.
- Flexible Containers:Downgauged thermoformed films and hinged-lid formats for ready-meal portion control. QSR chains specify these for weight reduction targets.
- Bottles:Blow-molded or injection-stretch formats for condiments and dairy beverages. Limited PS penetration versus PET and HDPE alternatives.
Rigid containers anchor the volume base while flexible containers gain share at the steepest rate.
Material:
Cost tier stratification separates commodity resins from specification-grade polymers, with purification investments creating divergence between export-capable and domestic-only supply tiers.
- Polystyrene:General-purpose and high-impact grades at 1.04–1.06 g/cm³ density, offering clarity and rigidity for retail visibility. REACH styrene monomer residual thresholds force resin purification upgrades for European market access.
- PET:Crystalline polyester with superior barrier performance and established recycling infrastructure. Bottled water and beverage brands specify PET where post-consumer content mandates apply.
- Polyethylene:LDPE and HDPE variants for flexible pouch and lid applications. Lower modulus limits structural load-bearing capacity.
- Polypropylene:High-melt-flow grades for thin-wall injection molding in food service cutlery. Higher temperature resistance than PS enables microwaveable applications.
Polystyrene retains the densest margin pool through custom tooling integration while PET climbs the fastest on recyclability credentials.
End User:
Customer type concentration shapes procurement leverage, with consolidated retail chains extracting volume commitments from converters while fragmented cosmetic brands accept spot pricing.
- Food Industry:Dairy processors, deli chains, and prepared-food brands specifying thermoformed trays and rigid containers. National US deli chains now mandate single-source thermoforming partnerships for private-label programs.
- Pharmaceutical:Blister packs and unit-dose containers requiring USP Class VI resin certification and particulate control. Migration testing protocols extend product launch timelines.
- Cosmetic:Compacts and jars for color cosmetics and skincare. Shorter product lifecycles favor converters with rapid tool turnaround capability.
- Household Products:Clamshells and tubs for cleaning supplies and hardware. Price-sensitive procurement tolerates wider specification bands.
Food industry demand anchors the volume base while pharmaceutical applications expand most quickly on compliance-driven specification premiums.
Distribution Channel:
Geographic concentration of channel power creates regional procurement asymmetries, with German and US supermarket consolidation contrasting fragmented convenience store networks in emerging markets.
- Supermarkets:National and regional chains with centralized packaging specification and multi-year volume commitments. Category managers mandate recyclability labeling compliance ahead of regulatory phase-ins.
- Distributors:Independent foodservice supply houses serving institutional catering and QSR franchises. Inventory pooling reduces converter working capital requirements.
- Online Retail:Direct-to-consumer prepared-food brands bypassing traditional distribution through captive thermoforming partnerships. Subscription meal kit services specify portion-control formats.
- Convenience Stores:Fragmented owner-operator networks with spot purchasing and limited specification enforcement. Price competition from imported Asian supply intensifies.
Supermarket channels anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food contact substance regulations anchor the United States as the dominant geography, with REACH compliance deadlines and China's GB standards creating parallel certification requirements that shape regional production decisions.
United States
Dairy processors and national deli chains sustain rigid container demand through centralized procurement and private-label packaging programs. FDA migration limits and food contact substance rules govern resin purity specifications for domestic-bound production. Wisconsin's dairy processing corridor anchors thermoforming capacity commitments from protein tray manufacturers.
Germany
Extended shelf-life cheese and processed meat applications drive rigid container specifications through retail chain consolidation. ECHA substance evaluation protocols and REACH styrene monomer residual thresholds force resin purification investments. Bavaria's protein processing clusters concentrate custom-tooled tray capacity with multi-year volume lock-ins.
China
Export-oriented manufacturers balance domestic ready-meal growth against international compliance requirements for dual-market access. GB standards mandate recyclability labeling that shapes production decisions for foreign-bound shipments. Yangtze River Delta thermoforming facilities upgrade purification systems to meet European residual threshold specifications.
India
Institutional catering and QSR franchise expansion accelerate food service container adoption amid fragmented convenience store networks. FSSAI food safety regulations and BIS certification requirements extend product launch timelines for pharmaceutical and food-grade applications. Maharashtra's dairy cooperatives pilot thermoformed packaging for extended distribution reach.
Japan
Portion-control and ready-meal formats gain traction through convenience store channel density and single-serve consumption patterns. METI circular economy guidelines and JIS standards shape material selection criteria for recyclable packaging. Kanto region food manufacturers specify downgauged flexible containers for weight reduction targets.
PS Containers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated procurement by prepared-food brands compressing supplier rosters toward converters with captive resin supply and in-house toolmaking capability. The specialist tier fragments across regional dairy clusters and short-run custom applications. Strategic archetypes include integrated resin-to-container platforms, thin-wall injection molding specialists, and captive thermoforming partnerships for direct-to-retail channels. Capacity expansion at multi-cavity facilities and backward integration into resin purification represent the dominant competitive moves.
Among North American converters, Berry Global Group Inc. and Silgan Holdings Inc. exemplify divergent specialization strategies within the food service packaging tier. Amcor Plc occupies a position representing the integrated multinational archetype with geographic diversification. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Group Inc. |
| Silgan Holdings Inc. |
| Pactiv LLC |
| Sonoco Products Company |
| ALPLA |
| Plastipak Holdings Inc. |
| DS Smith Plc |
| SIG |
| Others |
Value Network & Pricing Analysis
Multi-cavity thermoforming scale economies in Wisconsin and Bavaria simultaneously compress unit costs and concentrate supply-side pricing power among integrated resin-to-container platforms. This concentration elevates price floors for spot purchasers while locking in volume discounts for national deli chains with multi-year commitments.
Pricing Analysis
Geographic price spreads between German REACH-compliant resin and standard-grade Asian supply exceed transport cost differentials alone. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified pharmaceutical grades from food-contact dairy specifications and commodity household formats. Cost compression in standard-grade rigid containers is intensifying because benzene feedstock volatility transmits directly without pricing power recovery. Household product buyers exhibit greatest price sensitivity, while pharmaceutical procurement tolerates specification premiums for USP Class VI certification.
Supply Chain Analysis
Benzene derivative supply from Gulf Coast petrochemical complexes underwrites North American PS resin availability. Manufacturing concentrates in Germany, China, and the United States, with each hub serving distinct regulatory compliance tiers. Raw material flows draw from styrene monomer purification facilities, high-impact polystyrene compounding operations, and custom colorant additive suppliers. Single-source vulnerability concentrates in European resin purification capacity serving REACH thresholds. Distribution runs through supermarket category managers, institutional foodservice distributors, and captive direct-to-retail thermoforming partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as channel restructuring by prepared-food brands fragments procurement across regional dairy clusters and online retail direct partnerships.
For Market Incumbents: Compound resin purification investments ahead of ECHA flame retardant evaluation deadlines to capture stranded competitor volume. Anchor capacity expansion in Wisconsin and Bavaria dairy corridors where multi-year commitments lock in utilization. Defend against paperboard substitution by embedding moisture-resistant coatings in proprietary tray designs. For New Entrants and Emerging Players: Anchor in Indian institutional catering and QSR franchise networks where fragmented convenience store procurement tolerates spot pricing. Target Maharashtra dairy cooperative pilot programs for thermoformed extended distribution packaging. Pursue captive thermoforming partnerships with subscription meal kit services seeking portion-control format differentiation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with in-house toolmaking and captive resin supply over pure-play sheet-fed operators. Long-term viability across the analysis window hinges on additive reformulation capability for expanded polystyrene variants and dual-market certification infrastructure. Watch ECHA substance evaluation protocol timelines as inflection indicators for stranded asset risk and acquisition discount opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Purification Capacity Expansion | REACH compliance deadlines in Germany force purification upgrades that upgrade material specifications for export markets. |
| Captive Thermoforming Partnerships | Direct-to-retail prepared-food brands bypass traditional distribution through dedicated capacity commitments. |
| Flame Retardant Reformulation | ECHA substance evaluation protocols create first-mover advantage for additive suppliers with compliant expanded polystyrene variants. |
| Multi-Cavity Thin-Wall Injection Molding | QSR chains adopt these formats for cutlery and lid applications where weight reduction offsets material cost premiums. |
| Dual-Market Certification Investment | Parallel FDA and REACH testing protocols extend product launch timelines but secure access to United States and European demand. |
Research Methodology
Desk research of customs trade data, SEC filings from packaging converters, and ECHA substance evaluation protocols preceded structured interviews with thermoforming plant managers, resin procurement leads at dairy processors, supermarket category buyers, and regulatory affairs specialists at additive suppliers. Primary fieldwork across Wisconsin, Bavaria, and Yangtze River Delta facilities combined with secondary validation from FDA food contact substance notifications and REACH registration dossiers. Bottom-up capacity utilization estimates and top-down demand aggregation triangulated volume figures.
Variance decomposition across product format, material grade, end-use concentration, and distribution channel shaped the analytical framework throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory phase-in schedules. Industry-specific inputs included benzene price elasticity assumptions and thermoforming automation adoption curves.
Material uncertainties — styrene monomer residual threshold revisions, ECHA flame retardant restriction timelines, and China's GB standards enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and substitution elasticity. Practitioners should keep alternative scenarios live as paperboard barrier coating advances and bioplastic scale economies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
ISO Ocean Containers Market
Containers
Acrylic Container Market
Containers
2 Piece Cans Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Popcorn Containers Market
Containers
Global Multi Pack Carriers Market
Containers
Screw Top Lids Market
Containers
Insert Trays Market
Containers
Bulk Containers Market
Containers
Stainless Steel Cask Market
Containers
Compartment Trays Market
Containers
Aluminum Foil Containers Market
Containers
Soup Containers Market
Containers
Roll Containers Market
Containers
Packaging Bins Market
Containers
North America Insulated Shipping Containers Market