
 Containerboard Market | 2026-2036
Containerboard Market Size, Share, and Industry Trends Forecast 2026-2036
Containerboard Market Analysis
Digital printing integration is fragmenting traditional containerboard converting workflows, enabling shorter runs and mass customization that legacy equipment cannot match. International Paper leverages its North American mill network to sustain integrated supply advantages across linerboard grades. Smurfit WestRock anchors European corrugated packaging through extensive recycling infrastructure and box plant density. Nine Dragons Paper dominates Asian recycled fiber sourcing, controlling cost positions that competitors struggle to replicate.
Containerboard denotes heavy paperboard grades manufactured from wood pulp or recovered fiber, typically ranging from 200 to 350 grams per square meter in basis weight, engineered specifically for corrugated packaging structures. Kraft pulping and semi-chemical processes yield the high burst strength and ring crush resistance required for stacked load-bearing performance. Linerboard commands the largest value share within product type segmentation, while recycled fiber production types are expanding fastest as mills retrofit to meet circular economy specifications. E-commerce end users represent the most dynamic demand pool, though food and beverage applications retain the deepest volume base.
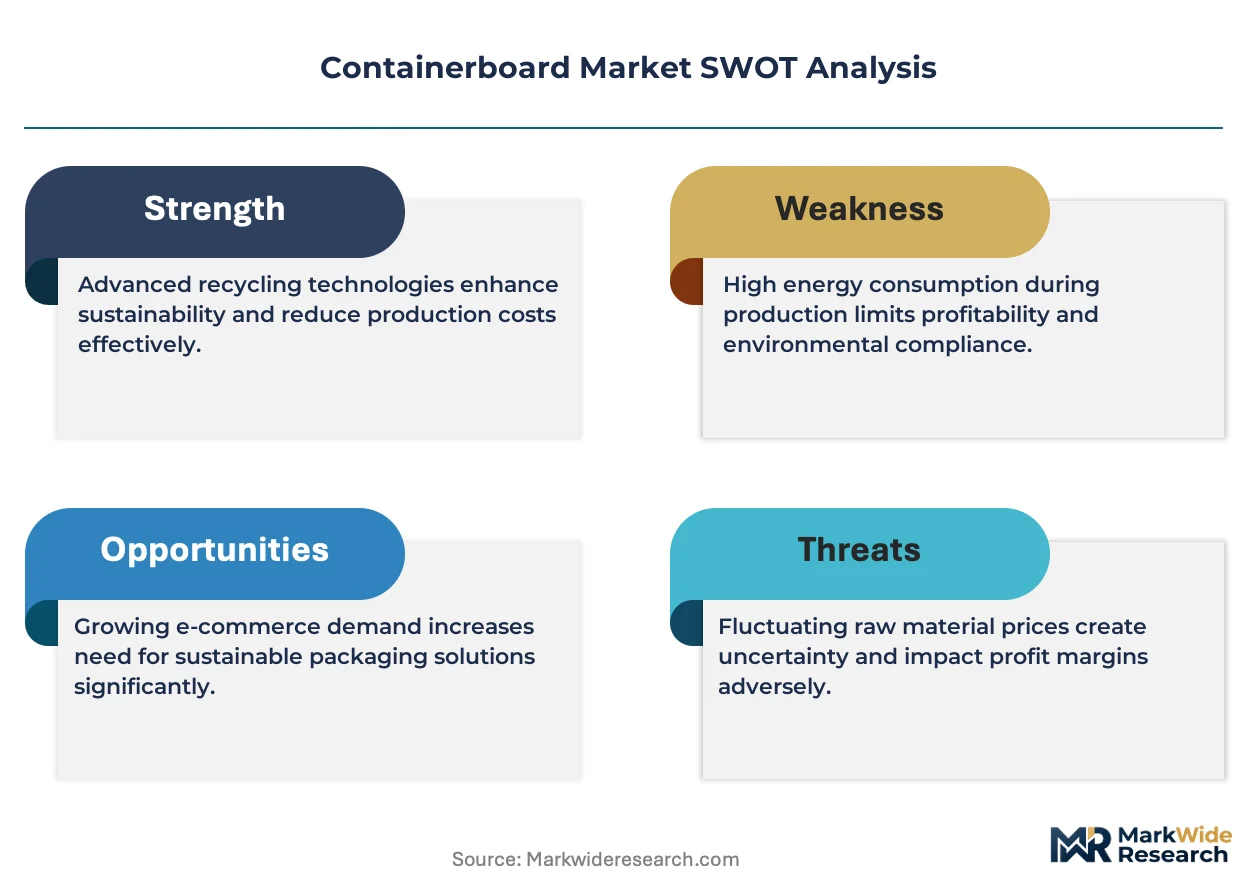
EPA emissions standards and OSHA workplace safety frameworks govern US mill operations, while the EU Green Deal and REACH chemical protocols shape fiber sourcing and coating formulations across European production. China's MEE enforces wastewater discharge limits that constrain small-scale recycled fiber operations, compressing supply toward larger integrated producers. Stakeholders must weigh virgin fiber price volatility against recycled fiber quality inconsistency when committing to multi-year capacity investments.
Market Dynamics
Recycled fiber mandates from the EU Green Deal and China's dual carbon goals are compressing virgin pulp demand while redirecting capital toward circular production systems. Mills face immediate retrofit pressure as regulatory deadlines harden.
Growth Catalysts
- E-commerce fulfillment networks:Corrugated box consumption accelerates as third-party logistics providers expand automated sortation hubs across North America and Europe.
- REACH chemical protocols:EU coating formulation standards favor water-based barrier technologies that integrate with recycled fiber streams.
- China's domestic packaging scale:Manufacturing corridor expansion in the Yangtze River Delta concentrates demand for high-performance linerboard grades.
Market Restraints
- Recovered fiber quality inconsistency:Contamination rates in post-consumer OCC streams degrade sheet strength, forcing mills to over-engineer basis weights.
- Natural gas price volatility:Drying energy costs swing mill operating margins by double-digit percentages in integrated European producers.
- Small-scale Chinese mill closures:MEE wastewater enforcement eliminates 15-20% of regional recycled fiber capacity, tightening furnish availability.
Strategic Opportunities
- India packaging underpenetration:Organized retail and quick-commerce growth in Mumbai and Bangalore outpaces domestic containerboard supply by wide margins.
- Digital printing convergence:Inkjet web presses combine with AI-driven nesting software to enable lot-size-one corrugated production for brand campaigns.
- EU Green Deal circularity incentives:Capital subsidies for closed-loop fiber recovery systems reward mills with captive box plant networks.
Industry Challenges
- Legacy converting equipment incompatibility:Short-run digital workflows strain mechanical folder-gluers designed for 50,000-unit minimums.
- Certification timeline compression:FSC chain-of-custody audits for multi-source recycled fiber supply chains extend 8-14 months.
- Automation skill scarcity:Predictive maintenance of robotic palletizing systems outpaces available technician training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Containerboard Market |
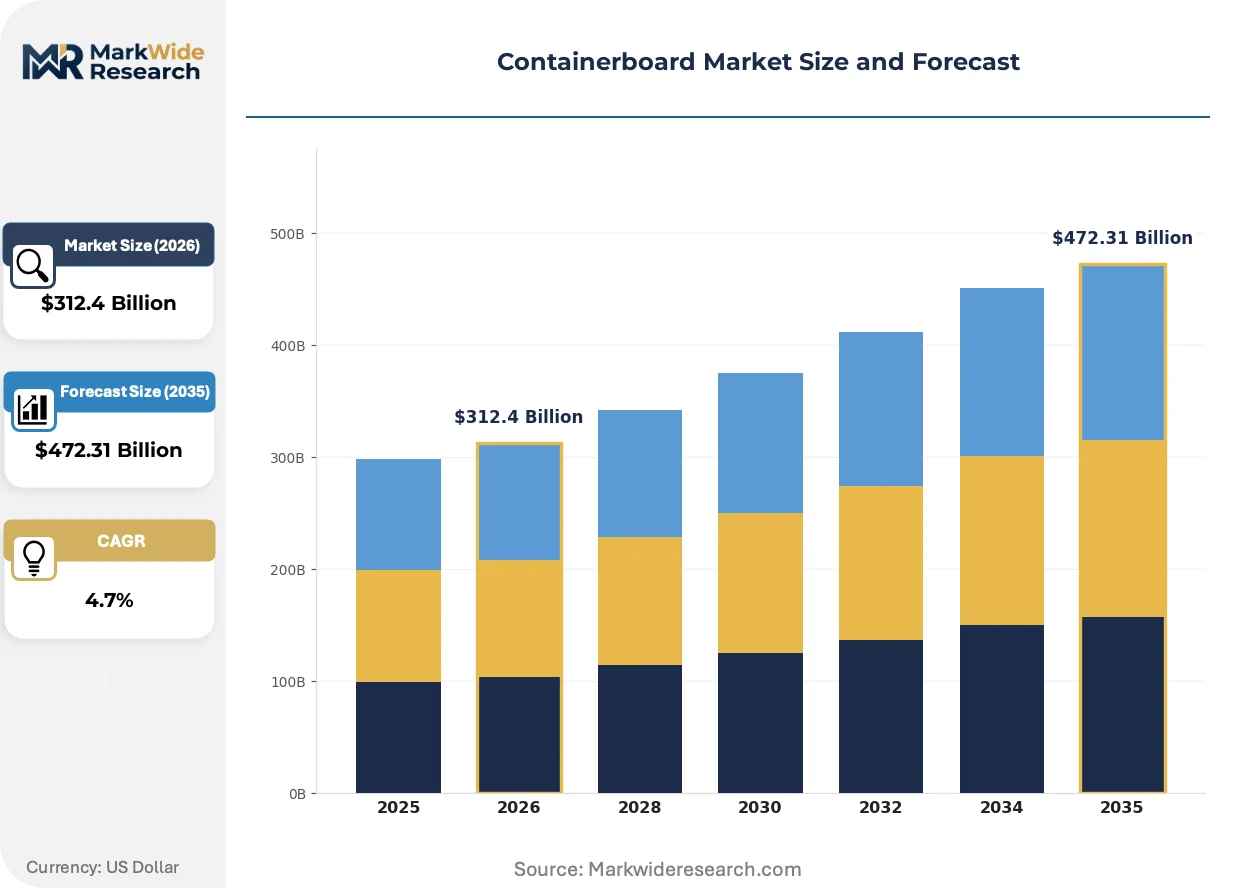
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $472.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Medium, Linerboard, Kraft Paper, Recycled Paper End User: Food & Beverage, Electronics, Consumer Goods, E-Commerce Form: Sheet, Roll, Box, Pad Production Type: Virgin Fiber, Recycled Fiber, Hybrid Fiber, Others |
| Companies Covered | Mondi Group, Packaging Corporation of America, International Paper, Georgia-Pacific LLC, DS Smith, Smurfit WestRock, Oji Holdings Corporation, Stora Enso Oyj, Nine Dragons Paper (Holdings) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Containerboard Market Emerging Trajectories
Digital manufacturing technologies and regulatory chemistry restrictions are dismantling century-old containerboard production paradigms. Equipment replacement cycles compress as capability gaps widen.
Single-pass inkjet web printing is rendering obsolete flexographic plate-making and makeready delays that consumed 45-90 minutes per job change. E-commerce fulfillment centers now specify 500-unit minimum runs with variable graphics. Mass customization capability separates integrated producers from commodity converters locked into analog workflows.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant fluorochemical coatings from food-contact linerboard by 2026. Barrier coating R&D pivots toward bio-based waxes and clay mineral composites. European dairy and ready-meal exporters accelerate qualification of alternative barrier structures to maintain export compliance.
Brand procurement teams now require supplier scorecards documenting Scope 3 emissions and fiber provenance. Retailers in Germany and France delist packaging suppliers lacking Science Based Targets initiative validation. Supplier consolidation follows as Tier 2 converters lack capital to deploy blockchain-tracked chain-of-custody systems demanded by multinational CPG accounts.
Containerboard Market Segmentation
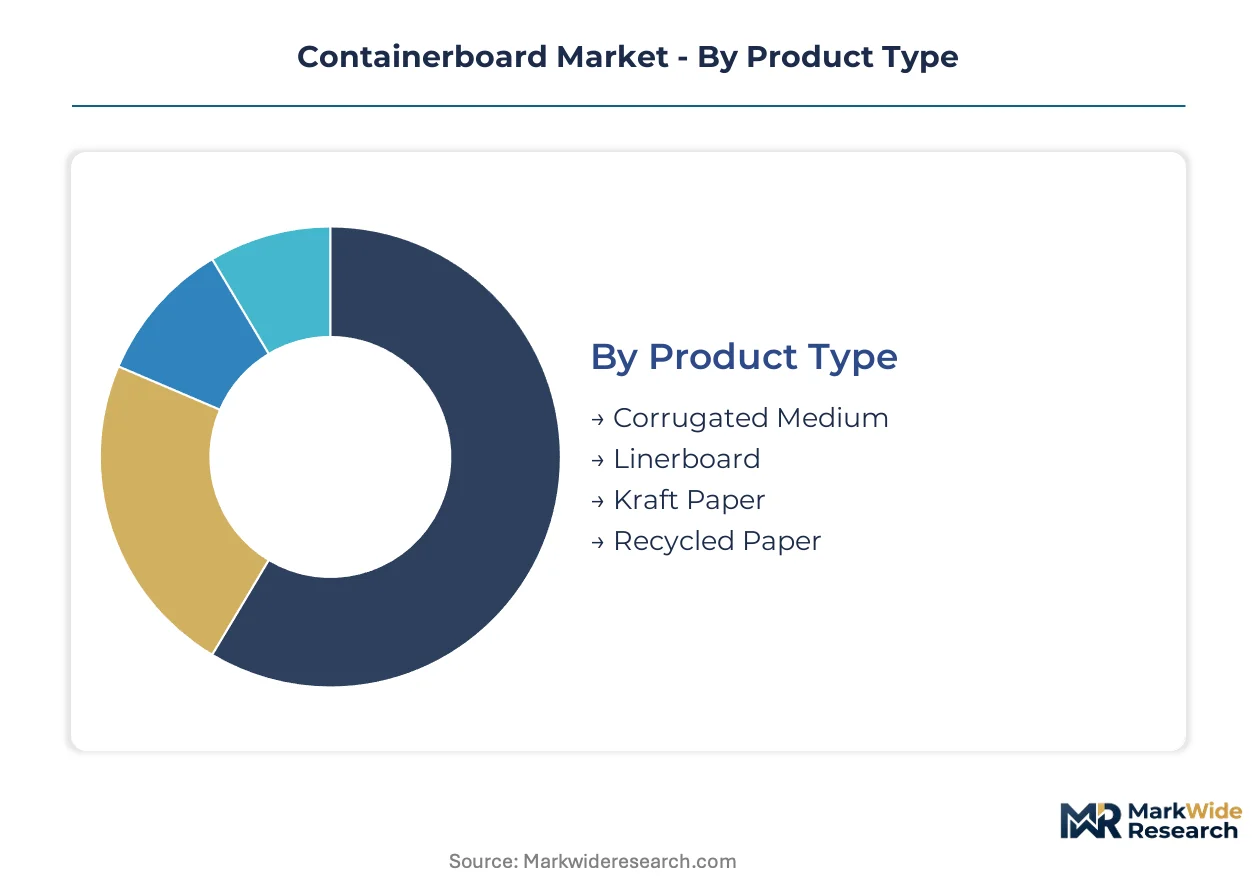
Containerboard segmentation reveals divergent margin profiles and capital intensity across grades. Product type determines fiber sourcing strategy and equipment requirements. End-use concentration shapes regional mill placement and box plant network density.
Product Type:
Cycle times vary dramatically: linerboard mills run continuous schedules with 30-45 day order backlogs, while specialty kraft grades turn in 10-14 day windows driven by spot purchasing.
- Linerboard:Unbleached kraft pulp construction delivers burst strength exceeding 350 kPa for stacked load-bearing performance. Demand concentrates in China's Yangtze River Delta manufacturing corridor where export packaging specifications mandate high ring crush resistance. MEE wastewater enforcement compresses domestic supply toward integrated producers with captive pulp lines.
- Corrugated Medium:Fluted inner layer engineered from semi-chemical pulp with C-flute and B-flute profiles dominating. E-commerce fulfillment networks in Germany and France specify 32 ECT grade minimums for automated sortation hub compatibility. REACH coating protocols favor water-based barrier integration with recycled fiber streams.
- Kraft Paper:Bleached and unbleached grades serve industrial wrapping and protective interleaving applications.
- Recycled Paper:Post-consumer OCC-based construction for non-contact packaging tiers in cost-sensitive consumer goods.
Linerboard dominates installed base. Recycled paper is where expansion concentrates.
End User:
Margin tiers separate contractually anchored food and beverage accounts from volatile spot-market e-commerce demand.
- Food & Beverage:Dairy and ready-meal exporters in the Netherlands and Belgium drive barrier-coated linerboard specifications. EU Green Deal circularity incentives reward closed-loop fiber recovery systems with captive box plant networks. FSC chain-of-custody audits extend qualification timelines for multi-source recycled supply.
- E-Commerce:Third-party logistics providers specify 500-unit minimum runs with variable graphics for brand campaigns. Single-pass inkjet web printing enables lot-size-one production that mechanical folder-gluers cannot match. Mass customization capability separates integrated producers from commodity converters.
- Electronics:Anti-static and moisture-barrier specifications for semiconductor and component shipping.
- Consumer Goods:Retail-ready packaging with shelf-display graphics for mass merchandisers.
Food and beverage anchors volume commitments. E-commerce is climbing the fastest.
Form:
Inventory carrying costs and working capital requirements scale with processing stage.
- Roll:Mill-direct supply to integrated corrugators with 72-hour slitter-scheduling flexibility.
- Sheet:Pre-cut dimensions for independent box plants lacking sheeter capacity.
- Box:Finished corrugated containers with print and die-cut specifications.
- Pad:Flat protective layers for palletized load stabilization.
Roll form dominates tonnage throughput. Box form is where value-add expansion concentrates.
Production Type:
Capital deployment and regulatory exposure diverge sharply between virgin and recycled fiber systems.
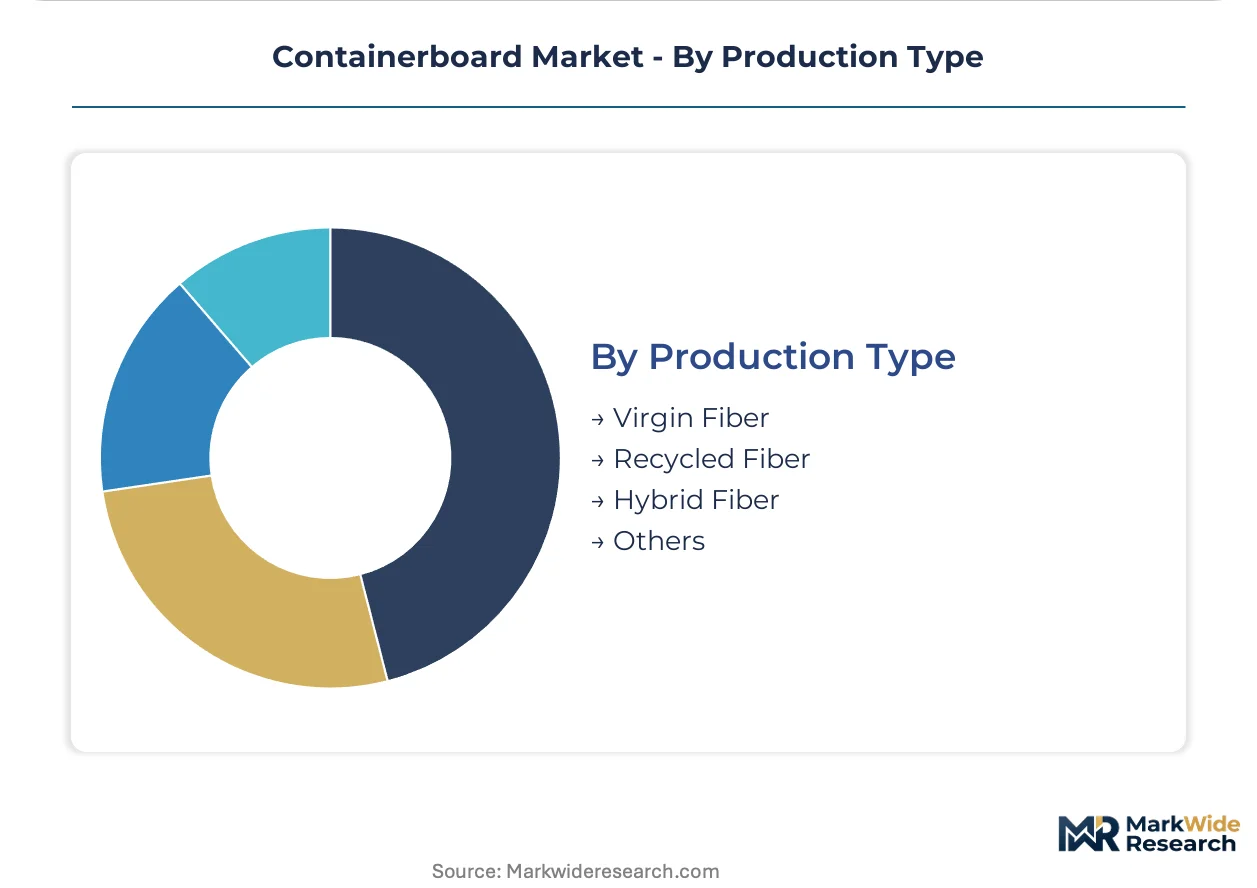
- Recycled Fiber:Post-consumer OCC streams with contamination rates degrading sheet strength. China's MEE enforcement eliminates small-scale mill capacity, tightening furnish availability toward larger integrated producers. EU Green Deal mandates redirect capital toward circular production retrofits.
- Virgin Fiber:Softwood kraft pulping with price volatility tied to lumber and energy markets.
- Hybrid Fiber:Blended furnish optimizing cost and performance for specific end-use tiers.
- Others:Agricultural residue and alternative fiber experiments in pilot-scale deployment.
Virgin fiber retains premium positioning. Recycled fiber is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish linerboard exports reach automated fulfillment hubs in Germany and the Netherlands. Containerboard trade corridors track manufacturing density and regulatory stringency across continents.
United States
Third-party logistics providers expand automated sortation hubs across Georgia and Texas. EPA emissions standards and OSHA workplace safety frameworks govern mill operations in the Southeast. The Pacific Northwest pulp corridor supplies kraft fiber to California packaging converters serving e-commerce fulfillment networks.
Germany
Dairy and ready-meal exporters in Bavaria drive barrier-coated linerboard specifications. EU Green Deal circularity incentives and REACH chemical protocols redirect capital toward closed-loop fiber recovery. The Ruhr industrial cluster concentrates corrugated box production for automated retail distribution across Central Europe.
China
Manufacturing corridor expansion in the Yangtze River Delta concentrates demand for high-performance linerboard grades. MEE wastewater discharge limits eliminate small-scale recycled fiber operations, compressing supply toward integrated producers. Guangdong Province packaging output scales to serve Asia-Pacific export manufacturing.
India
Organized retail and quick-commerce growth in Mumbai and Bangalore outpaces domestic containerboard supply. BIS standards and DGFT import frameworks shape fiber sourcing strategies for corrugated converters. Maharashtra's industrial belt attracts foreign mill investment to bridge the packaging supply gap.
Netherlands
Rotterdam port logistics and Antwerp chemical corridors anchor European linerboard distribution. REACH Annex XVII restrictions on fluorochemical coatings accelerate water-based barrier qualification. The Randstad packaging cluster serves refrigerated food exporters across the North Sea trade lane.
Containerboard Market Vendor Landscape
On the supply side, the industry is consolidating around integrated producers with captive pulp lines and box plant networks. Tiered competition separates scale-driven multinationals from regional specialists focused on recycled fiber optimization. Strategic archetypes include North American integrated giants, European circular-economy leaders, and Asian recycled-fiber dominant players. Capacity expansion and M&A activity concentrate market share among producers with multi-regional mill footprints.
Among North American integrated producers, International Paper and Packaging Corporation of America exemplify the scale-driven archetype with extensive mill networks. Smurfit WestRock occupies a position within the European circular-economy tier, leveraging recycling infrastructure density. Nine Dragons Paper (Holdings) Limited anchors the Asian recycled-fiber dominant archetype, controlling cost positions through regional furnish sourcing.
| Leading Market Players |
|---|
| Mondi Group |
| Packaging Corporation of America |
| International Paper |
| Georgia-Pacific LLC |
| DS Smith |
| Smurfit WestRock |
| Oji Holdings Corporation |
| Stora Enso Oyj |
| Nine Dragons Paper (Holdings) Limited |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge corridors move linerboard from Finnish mills to German corrugated converters at freight rates that swing mill netbacks by mid-single-digit percentages, concentrating pricing power among integrated producers with captive box plant networks while forcing independent converters into spot-market vulnerability.
Pricing Analysis
Analog flexographic workflows versus single-pass inkjet systems versus next-generation AI-driven nesting platforms define a three-tier pricing structure across premium, standard, and economy levels. Linerboard mills command contract premiums through FSC chain-of-custody certification and captive pulp integration, while recycled medium producers face cost compression from OCC contamination rates degrading sheet strength. E-commerce fulfillment networks exhibit highest price sensitivity due to 500-unit minimum run requirements, whereas dairy exporters in the Netherlands absorb premium barrier-coated grades for REACH compliance.
Supply Chain Analysis
Integrated corrugators in Germany, the United States, and China hold captive capacity that insulates against furnish volatility. Containerboard production draws from softwood kraft pulp, post-consumer OCC streams, and semi-chemical hardwood grades as primary inputs. Single-source vulnerability concentrates in Yangtze River Delta linerboard supply where MEE enforcement eliminated small-scale recycled fiber capacity. Distribution runs through mill-direct roll shipments to integrated corrugators with 72-hour slitter-scheduling flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing convergence and EU Green Deal circularity mandates are compressing legacy equipment replacement cycles, creating acquisition windows for producers with mass customization capabilities.
For Market Incumbents: Pre-empt digital-native competitors by retrofitting box plants with single-pass inkjet web presses and AI-driven nesting software. Secure captive recycled fiber supply through M&A of regional OCC collection networks before EU Green Deal subsidies attract financial buyers. Vertical integration into barrier coating R&D insulates against REACH Annex XVII fluorochemical phaseouts. For New Entrants and Emerging Players: Mumbai and Bangalore packaging underpenetration offers white-space expansion as organized retail and quick-commerce growth outpaces domestic containerboard supply. Target independent corrugated converters lacking sheeter capacity with sheet-form pre-cut dimensions delivered on 48-hour lead times. Qualify BIS standards compliance to access Maharashtra's industrial belt procurement channels. For Investors and Strategic Acquirers: Regional specialists with captive OCC sourcing and digital print conversion capabilities represent the most defensible acquisition archetype. Long-term viability hinges on circular-economy certification density and e-commerce fulfillment network integration. Monitor EU Green Deal capital subsidy disbursement velocity as inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Retrofit | Single-pass inkjet web presses enable lot-size-one production for e-commerce brand campaigns. |
| Backward Integration into OCC Collection | Captive fiber recovery systems secure furnish supply against MEE enforcement tightening availability. |
| Barrier Coating R&D Expansion | Bio-based wax and clay mineral composites replace fluorochemical coatings for REACH Annex XVII compliance. |
| Captive Box Plant Network Expansion | EU Green Deal circularity incentives reward closed-loop fiber recovery with captive converting capacity. |
| India Market Entry | Maharashtra and Karnataka industrial belts attract foreign mill investment to bridge packaging supply gaps. |
Methodological Framework
Desk research of trade association capacity databases, customs export records, and mill equipment disclosure filings preceded structured interviews with corrugated plant managers, linerboard procurement directors, digital print technology vendors, and EU regulatory affairs specialists. Primary fieldwork validated secondary estimates through bottom-up capacity tallying and top-down demand reconciliation across e-commerce fulfillment, food and beverage export, and consumer goods packaging segments.
Assumptions held fixed include regulatory enforcement timelines for EU Green Deal mandates and MEE wastewater standards, while natural gas price trajectories and OCC contamination rates were varied across sensitivity scenarios. Segmentation modeling spanned product type, end-use concentration, production fiber source, and geographic manufacturing corridor. CAGRs were derived from installed capacity expansion announcements, demand elasticity estimates, and substitution dynamics between analog and digital converting workflows.
Practitioners should monitor EU Green Deal subsidy allocation velocity, MEE enforcement action against small-scale Chinese mills, and inkjet web press adoption rates among Tier 2 converters for early signals of competitive inflection. Quarterly review of linerboard spot price spreads, digital print equipment order backlogs, and FSC chain-of-custody audit completion timelines is advised to detect structural shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Sanitary Cans Market
Containers
Oblong Container Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Metal Cans and Glass Jars Market
Containers
Clear Hinged Container Market
Containers
HDPE Crates Market
Containers
Child-Resistant Containers Market
Containers
Global Food Storage Container Market
Containers
Soup Containers Market
Containers
Insert Trays Market
Containers
Pocket Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
Trigger Sprayer Market
Containers
Thin Wall Containers Market
Containers
Roll Containers Market
Containers
Container Stacking Machine Market