
 Algeria Container Glass Market | 2026-2036
Algeria Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Container Glass Market Insights
Pharmaceutical packaging is expanding as Algeria's domestic drug manufacturing base matures and local fill-finish operations multiply. ALVER leverages vertical integration from silica sand mining through finished container output to control cost structures across its Oran facility. Nouvelle Verrerie de Chlef anchors supply to the wine and spirits sector through dedicated amber glass production lines. INTER GLASS competes on custom mold flexibility for mid-tier cosmetics brands seeking shorter production runs.
Container glass denotes hollow-ware formed from molten silica-soda-lime batches, typically containing 70-74% silicon dioxide, shaped by blow-and-blow or press-and-blow forming at 1,050-1,200°C for hermetic liquid and solid storage. The material dimension shows soda-lime glass dominating volume due to its cost efficiency in beverage bottles, while borosilicate vials command premium positioning in pharmaceutical injectables where thermal shock resistance matters. Among end users, food and beverage occupies the mature volume base, yet pharmaceutical packaging carries the fastest structural expansion as import substitution policies deepen local production.
Algeria's Ministry of Environment enforces packaging waste recovery obligations that push manufacturers toward recyclable-format investment, while the national standards body applies quality benchmarks for food-contact glass that shape product access rules. The country's pharmaceutical regulator demands type-II and type-III borosilicate compliance for parenteral drug containers, filtering which suppliers qualify for health-sector procurement. Stakeholders must monitor how enforcement capacity at port customs evolves, since import glassware competition remains the critical variable for domestic margin sustainability.
Market Dynamics
Algeria's container glass sector confronts a tightening regulatory environment from the Ministry of Environment, where extended producer responsibility mandates are forcing capital reallocation toward waste recovery infrastructure ahead of the 2026 compliance deadline.
Growth Catalysts
- Domestic pharmaceutical fill-finish expansion:Algeria's import substitution policies for active pharmaceutical ingredients are multiplying local drug packaging demand, pulling borosilicate vial requirements upward.
- Waste recovery obligations:The Ministry of Environment's packaging waste directives are compelling manufacturers to invest in closed-loop recycling systems that lower virgin silica dependence.
- Coastal logistics concentration:Demand clustering along the Algiers-Oran-Annaba corridor reduces distribution costs for beverage and food container suppliers serving Mediterranean ports.
Market Restraints
- Natural gas price volatility:Furnace operations depend on subsidized Algerian hydrocarbon feedstock, and any subsidy reduction would compress margin structures immediately.
- Import glassware competition:Egyptian and Turkish container suppliers with depreciated currency advantages threaten domestic pricing power at Algerian ports.
- Borosilicate technical limitation:Local furnace configurations remain optimized for soda-lime batches, constraining rapid pivot toward pharmaceutical-grade thermal shock resistance.
Strategic Opportunities
- Underpenetrated Saharan distribution:Algeria's southern interior cities lack reliable container glass supply chains, creating white space for regional depot investments.
- Cosmetics custom mold services:Mid-tier beauty brands in Oran and Algiers seek shorter production runs with flexible mold capabilities that incumbent mass producers ignore.
- Extended producer responsibility incentives:The Ministry of Environment's waste recovery credits reward early compliance investments with procurement preference in state-tendered beverage contracts.
Industry Challenges
- Specialized furnace engineering talent:Algeria's technical institutes produce insufficient glass technology graduates, forcing reliance on expatriate Egyptian and Italian specialists.
- Pharmaceutical certification timelines:The national pharmaceutical regulator's type-II and type-III borosilicate approval cycles extend 18-24 months, freezing supplier qualification pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Container Glass Market |
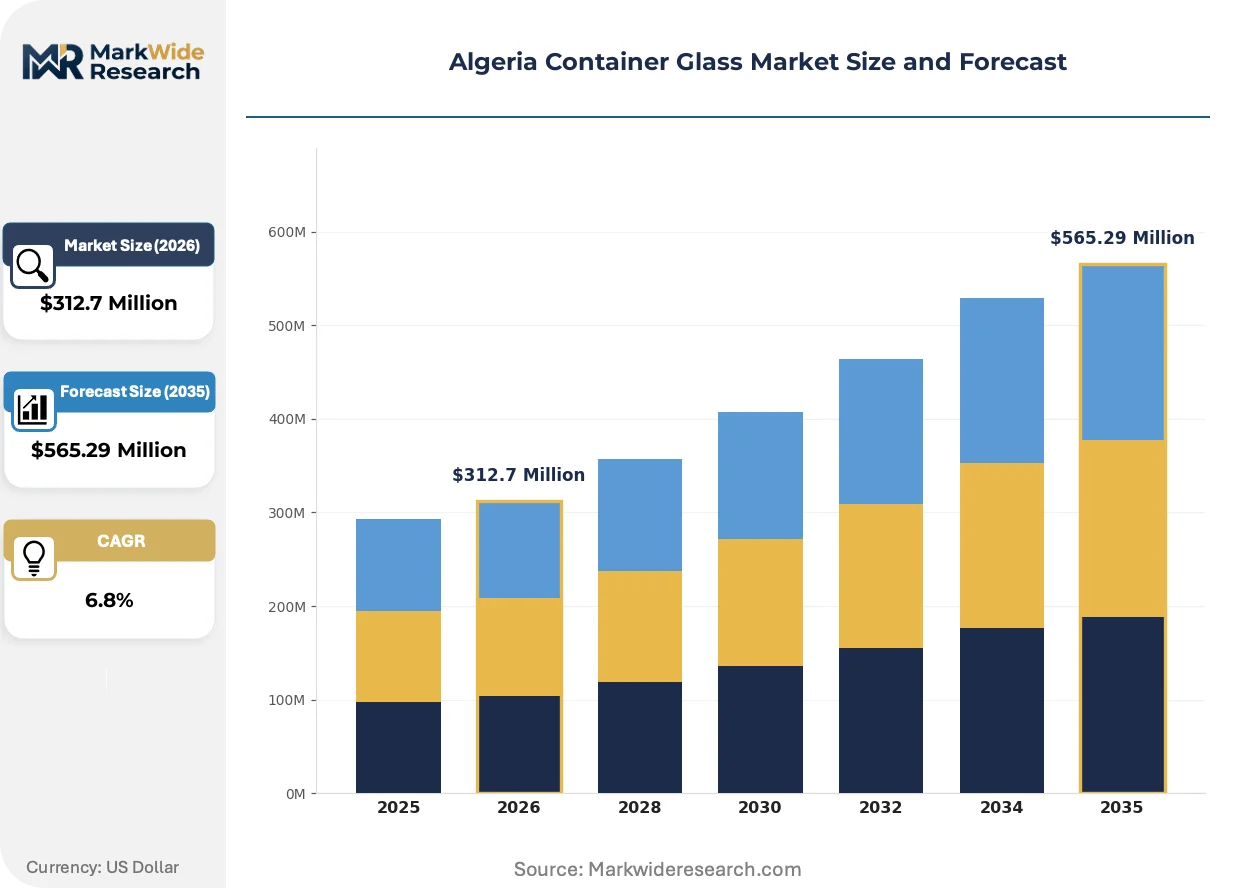
| Market Size in 2026 | $312.7 Million |
| Market Size in 2035 | $565.29 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Vials Material: Soda-Lime Glass, Borosilicate Glass, Lead Glass, Colored Glass End User: Food & Beverage, Pharmaceuticals, Cosmetics, Home Care Packaging Type: Recyclable, Single-Use, Bulk, Custom Design |
| Companies Covered | Société Algérienne des Verres, SpA (ALVER), Nouvelle Verrerie de Chlef, SpA, INTER GLASS, Sarl., Mediterranean Float Glass, NOVER, AFRICAVER, Feemio Group Co., Ltd., Changsha Kotto Glass Industrial Co Ltd, Castel Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Container Glass Market Trends and Innovations
Electrification of melting technology and regulatory tightening around circularity are compressing legacy furnace economics while opening premium positioning for compliant suppliers.
Plasma-assisted melting is electrifying container glass production by replacing natural gas combustion with electrode-based thermal energy. Pharmaceutical packaging specialists in Annaba are piloting these systems to isolate batch chemistry from hydrocarbon contamination. The technology is electrifying cost structures for premium vial segments where purity commands price separation from commodity beverage bottles.
The Ministry of Environment's extended producer responsibility framework now mandates minimum post-consumer cullet ratios in new container production. Glass manufacturers must fund reverse logistics networks or face procurement exclusion from state beverage tenders. Food-contact container segments are responding fastest, integrating on-site crushing and beneficiation to secure compliance documentation.
Buyer consolidation among Algeria's state-owned beverage distributors is compressing supplier negotiation cycles from annual to quarterly terms. Smaller wine and spirits bottlers in the Chelif Valley are losing leverage as central procurement desks in Algiers aggregate volume. This concentration is most visible in amber glass contracts, where Nouvelle Verrerie de Chlef now faces direct negotiations with consolidated buyers rather than fragmented regional clients.
Algeria Container Glass Market Segmentation
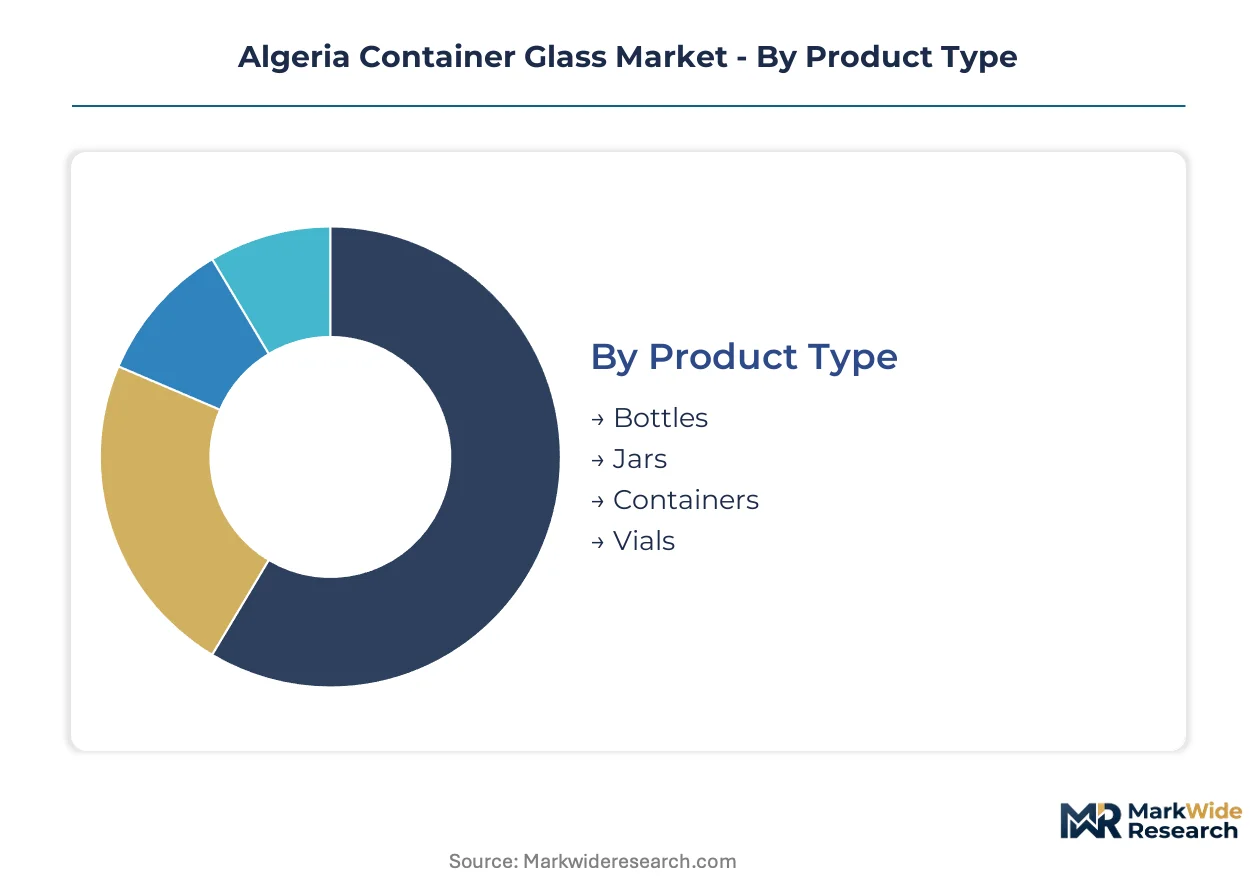
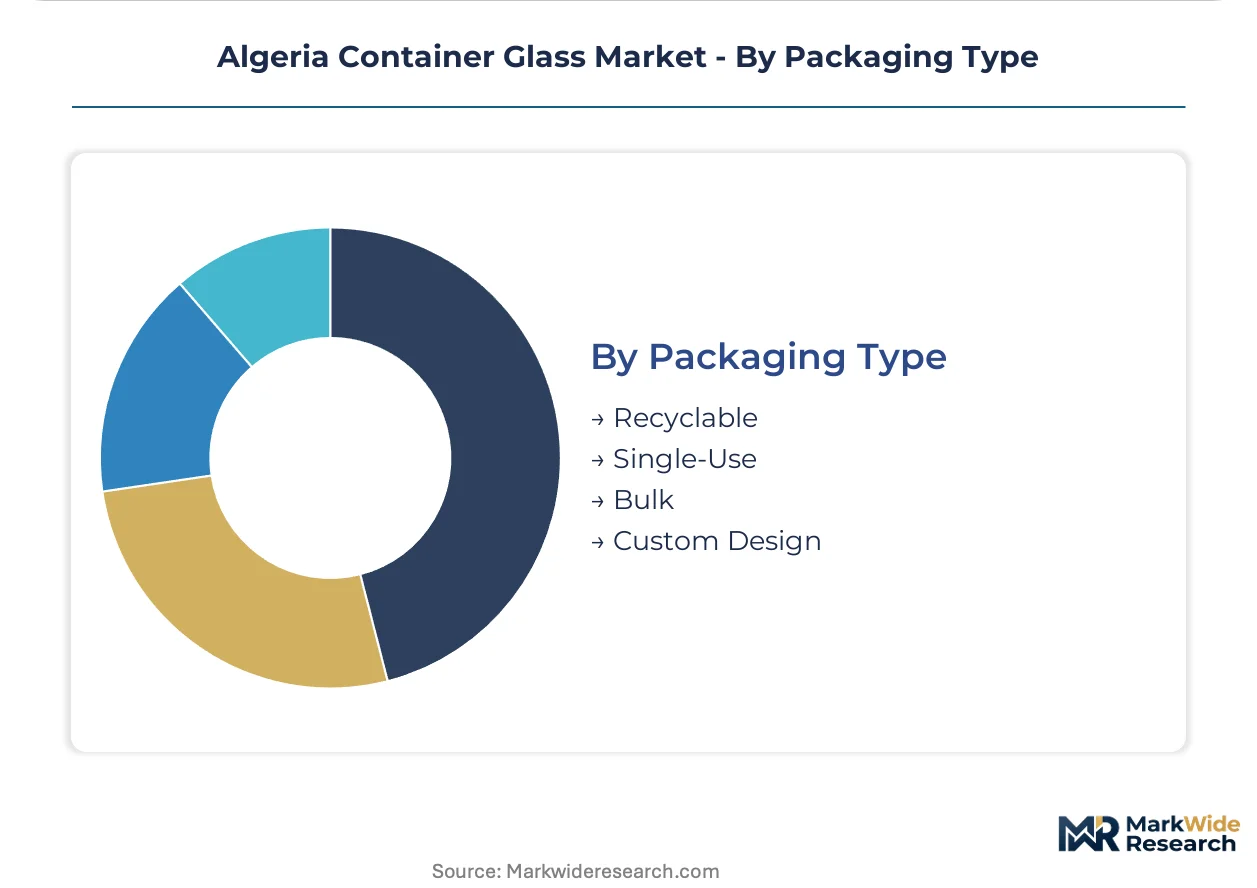
Algeria's container glass market fragments across four dimensions that shape procurement priorities and furnace investment decisions. Material chemistry and end-use certification requirements determine supplier qualification barriers, while packaging format choices reflect the Ministry of Environment's tightening circularity mandates.
Product Type:
Buyers select container formats based on closure compatibility, filling line speed, and shelf presence requirements in Algeria's coastal retail corridors.
- Bottles:Narrow-necked hollow-ware dominates beverage and condiment applications, with Algiers-Oran distributors specifying 250ml to 1.5L capacity ranges for carbonated soft drinks and cooking oils. The format commands volume concentration in state beverage tenders where standardization reduces procurement complexity.
- Jars:Wide-mouth containers with lug or continuous thread finishes serve preserved foods and spreads. Annaba food processors are expanding jar demand for olive paste and harissa exports to European halal markets, pulling capacity from Oran manufacturers.
- Containers:Rectangular and square-section storage ware addresses bulk food service and institutional procurement in Algeria's hotel and catering sector.
- Vials:Small-volume tubular and molded formats carry pharmaceutical compliance requirements from the national drug regulator.
Volume sits with bottles; growth tilts toward vials as domestic fill-finish capacity expands.
Material:
Furnace batch chemistry determines thermal properties, chemical durability, and regulatory compliance pathways for Algerian manufacturers.
- Soda-Lime Glass:Silica-soda-lime batches containing 70-74% silicon dioxide dominate Algerian furnace output due to lower melting temperatures and raw material availability from local silica sand deposits. The material anchors beverage and food container production at ALVER's Oran complex, where cost efficiency matters for state tender participation.
- Borosilicate Glass:Thermal shock-resistant formulations with 80% silica and 13% boron oxide command premium positioning in pharmaceutical injectables. Annaba specialists are piloting plasma-assisted melting to isolate batch chemistry from hydrocarbon contamination, though local furnace configurations constrain rapid capacity scaling.
- Lead Glass:High-refractive-index formulations serve decorative and specialty optical applications with limited Algerian demand.
- Colored Glass:Iron and chromium-doped batches produce amber and green tints for UV-sensitive contents, with Nouvelle Verrerie de Chlef anchoring wine and spirits supply through dedicated production lines.
Cost structures favor soda-lime; certification requirements are accelerating borosilicate furnace retrofits.
End User:
Downstream industry regulations and import substitution policies determine container specification complexity and contract tenure.
- Food & Beverage:Mature volume base concentrated in state-owned distributors and private label bottlers along the Mediterranean coast. Buyer consolidation is compressing supplier negotiation cycles from annual to quarterly terms.
- Pharmaceuticals:Domestic drug manufacturing expansion under import substitution policies is multiplying borosilicate vial demand. Type-II and type-III compliance requirements from the national pharmaceutical regulator filter supplier qualification.
- Cosmetics:Mid-tier beauty brands in Oran and Algiers seek shorter production runs with flexible mold capabilities.
- Home Care:Detergent and cleaning product packaging follows less stringent food-contact standards.
Procurement stability characterizes food and beverage; pharmaceutical packaging is climbing the fastest.
Packaging Type:
Environmental compliance positioning and supply chain configuration shape format selection among Algerian buyers.
- Recyclable:Post-consumer cullet integration is becoming mandatory under Ministry of Environment extended producer responsibility frameworks. Manufacturers must fund reverse logistics or face exclusion from state beverage tenders.
- Single-Use:Linear consumption models face procurement preference erosion as waste recovery obligations tighten.
- Bulk:Large-format containers for institutional and industrial buyers reduce per-unit logistics costs.
- Custom Design:Proprietary mold investments differentiate cosmetics and premium spirits positioning.
Regulatory pressure is concentrating volume in recyclable formats; custom design commands margin premiums in fragmented buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hassi Messaoud Industrial Zone and Oran Special Economic Zone concentrate investment incentives for glass manufacturers, drawing capital toward Algeria's northwestern industrial corridor. Northern coastal infrastructure dominates logistics efficiency. Southern distribution networks remain underdeveloped.
Algiers Province
State beverage procurement desks and pharmaceutical distributors cluster in Algiers, generating concentrated demand for standardized bottle formats and borosilicate vials. The Ministry of Environment enforces extended producer responsibility deadlines that push manufacturers toward recyclable-format compliance. The port of Algiers anchors import competition from Egyptian and Turkish container suppliers.
Oran Metropolitan Area
ALVER's integrated silica-sand-to-finished-container complex supplies cost-competitive soda-lime output for domestic beverage tenders. The national pharmaceutical regulator's type-II and type-III certification requirements filter which furnace operators qualify for health-sector contracts. The Oran Special Economic Zone offers tax holidays that offset natural gas price volatility risks for furnace operators.
Annaba Governorate
Plasma-assisted melting pilots aim to isolate pharmaceutical batch chemistry from hydrocarbon contamination. The Ministry of Environment's waste recovery credits reward early compliance investments with procurement preference in state contracts. Annaba's port infrastructure supports export-oriented jar production for European halal food markets.
Chlef Province
Nouvelle Verrerie de Chlef anchors amber glass supply to wine and spirits bottlers in the Chelif Valley. Consolidated buyer negotiations now run quarterly rather than annual, compressing supplier margin structures. The region's silica sand deposits support colored glass specialization with lower raw material transport costs.
Saharan Interior
Southern cities from Tamanrasset to Ouargla lack reliable container glass supply chains, creating white space for regional depot investments. Road logistics costs from northern production centers exceed container value for low-margin beverage formats. Local distributors currently rely on imported plastic alternatives or irregular truck shipments.
Algeria Container Glass Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration determining cost position in state beverage tenders while custom mold flexibility wins cosmetics contracts. The vendor base clusters around three furnace-scale tiers: integrated silica-sand operators, mid-size regional suppliers, and import-dependent traders. Strategic archetypes include backward-integrated mass producers, amber-glass specialists, and flexible custom-mold service providers. Capacity expansion and compliance-focused furnace retrofits represent the dominant competitive moves as regulatory deadlines approach.
Among Algeria-based integrated producers, Société Algérienne des Verres, SpA (ALVER) and Nouvelle Verrerie de Chlef, SpA occupy positions exemplifying the mass-production and specialty-glass archetypes respectively. INTER GLASS, Sarl. sits within the flexible-service tier serving fragmented cosmetics demand. Feemio Group Co., Ltd. and Changsha Kotto Glass Industrial Co Ltd represent Chinese-origin suppliers competing on depreciated-currency cost structures at Algerian ports. Mediterranean Float Glass anchors the import-dependent trading segment.
| Leading Market Players |
|---|
| Société Algérienne des Verres, SpA (ALVER) |
| Nouvelle Verrerie de Chlef, SpA |
| INTER GLASS, Sarl. |
| Mediterranean Float Glass |
| NOVER |
| AFRICAVER |
| Feemio Group Co., Ltd. |
| Changsha Kotto Glass Industrial Co Ltd |
| Castel Group |
| Others |
Pricing and Supply Chain Analysis
Specialized furnace engineering talent scarcity in Algeria's northwestern industrial corridor widens labor-cost differentials between expatriate-dependent operators and local-technical-institute feeders, translating into premium-mid-economy pricing differentiation across borosilicate and soda-lime tiers.
Pricing Analysis
Short lead-time premiums for pharmaceutical-grade borosilicate vials run 15-25% above contract-scheduled soda-lime beverage bottles, while spot inventory clearance discounts emerge for amber glass surplus from Nouvelle Verrerie de Chlef's wine-sector contracts. Three-tier pricing structure across premium pharmaceutical certification, standard food-contact compliance, and economy bulk-beverage tenders anchors the market. Cost compression in the economy tier intensifies because Egyptian and Turkish import competition erodes domestic pricing power at Algerian ports. State beverage distributors show highest price sensitivity due to consolidated procurement desks, while cosmetics brands seeking custom mold flexibility tolerate premium positioning.
Supply Chain Analysis
Domestic-content mandates from Algeria's Ministry of Environment reshape sourcing toward local silica sand deposits and captive cullet recovery networks, reducing import dependence for raw material feedstock. Supply concentrates in Algeria's northern coastal corridor from Algiers through Oran to Annaba, with secondary inputs drawn from Egyptian boron oxide traders and Italian furnace engineering specialists. Single-source vulnerability sits with expatriate technical talent for plasma-assisted melting retrofits. Distribution runs through Mediterranean port infrastructure with state-owned beverage distributors anchoring downstream volume aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algeria's container glass sector reads as a consolidation play where extended producer responsibility compliance deadlines force capital-constrained operators toward exit or acquisition by integrated majors.
For Market Incumbents: Cement market position through backward integration into silica sand mining and captive cullet beneficiation, locking in cost structures against Egyptian import competition. Prioritize plasma-assisted melting certification for pharmaceutical-grade borosilicate qualification before regulatory approval timelines freeze competitor pipelines. Channel control through direct state beverage tender relationships defends margin compression from buyer consolidation. For New Entrants and Emerging Players: E-commerce-enabled custom mold services for mid-tier cosmetics brands in Oran and Algiers bypass incumbent mass-production scale advantages. Saharan interior depot networks for Tamanrasset and Ouargla address white-space distribution gaps where plastic alternatives currently dominate. Flexible production runs with digital design-to-mold workflows capture premium positioning ignored by volume-focused operators. For Investors and Strategic Acquirers: Re-rating potential sits with amber-glass specialists possessing dedicated wine-sector production lines given European halal export demand acceleration. Five-to-ten-year viability hinges on furnace electrification capex execution and regulatory compliance certification velocity. Watch Ministry of Environment enforcement capacity at port customs as the critical inflection signal for domestic margin sustainability against import competition.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Assisted Melting Retrofit | Isolates pharmaceutical batch chemistry from hydrocarbon contamination at Annaba pilots. |
| Captive Silica Sand Integration | ALVER's Oran complex controls raw material cost structures against import volatility. |
| Reverse Logistics Network Buildout | Post-consumer cullet recovery secures Ministry of Environment tender compliance documentation. |
| Custom Mold Digital Platform | INTER GLASS serves fragmented cosmetics demand with shorter production run flexibility. |
| Saharan Distribution Depot Investment | Tamanrasset and Ouargla white space reduces plastic alternative dependence in southern cities. |
Research Methodology
Independent corroboration across furnace operations executives, pharmaceutical packaging procurement managers, Ministry of Environment compliance officers, and customs port officials underwrites the qualitative findings in this study. Primary interviews with plant engineers at integrated silica-sand-to-container complexes, regulatory affairs leads navigating type-II and type-III borosilicate certification, and state beverage distributor procurement desks combined with secondary validation from Algerian customs trade records, national standards body filings, and pharmaceutical regulator documentation. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across material chemistry and end-use segmentation dimensions.
Rate-of-change decomposition separates volume growth into pharmaceutical fill-finish expansion, beverage tender standardization, and waste recovery obligation compliance across the analysis window. Segmentation modeling incorporates material chemistry tier, end-use regulatory complexity, packaging format circularity credentials, and regional logistics accessibility. CAGRs derive from production capacity buildout schedules, furnace retrofit investment pipelines, and import substitution policy implementation trajectories. Forecast inputs include natural gas subsidy policy stability and Egyptian-Turkish currency-adjusted export pricing dynamics.
Inputs from Algerian industrial zone investment authorities and pharmaceutical regulator certification databases were available through the study window; gaps in real-time furnace utilization rates and proprietary buyer contract terms introduce uncertainty bands around margin structure projections. Forecasts reflect documented assumptions regarding Ministry of Environment enforcement capacity evolution and hydrocarbon feedstock pricing policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Corrugated Open-Head Drums Market
Containers
EMEA Container Technology Market
Containers
Steel Containers Market
Containers
Belgium Container Glass Market
Containers
Sample Containers Market
Containers
Composite Ibcs System Market
Containers
Canning Jars Market
Containers
Wooden Crates Market
Containers
HDPE Bottles Market
Containers
Pails Market
Containers
Oblong Jar Market
Containers
Edible Oil Cans Market
Containers
Water Resistant Packing Cubes Market
Containers
Containerboard Market
Containers
Die Cut Display Container Market
Containers
Hinged Lid Compostable Container Market