
 Lift-Off Lid Box Market | 2026-2036
Lift-Off Lid Box Market Size, Share, and Industry Trends Forecast 2026-2036
Lift-Off Lid Box Market Foresight
A capital-intensity divergence between integrated paperboard producers and boutique rigid-box specialists is reorganizing competitive tiers in the lift-off lid box sector. International Paper Company leverages its captive pulp supply and North American mill network to control raw material costs for high-volume folding box grades. Smurfit Kappa Group anchors European demand through its corrugated and solid board integration, while Burt Rigid Box Inc. specializes in handcrafted rigid lift-off lid constructions for luxury end users where automation remains limited.
A lift-off lid box consists of a separate base and removable lid, typically constructed from rigid paperboard over wrapped chipboard or greyboard, with corner stays or wrapped edges providing structural integrity for repeated opening cycles. The design permits premium unboxing experiences, archival storage, and reusable packaging applications across retail and gift categories. Rigid boxes command the highest margin pools in cosmetics and jewelry end uses where structural permanence justifies material cost premiums. Folding boxes compete on volume throughput in e-commerce subscription services where flat-ship efficiency dominates logistics economics. Eco-friendly boxes are gaining specification share as EU Ecodesign requirements and US state-level extended producer responsibility laws tighten virgin fiber allowances.
The US EPA oversees recycling stream contamination standards that affect mixed-fiber lift-off lid box recoverability, while the EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds for paperboard packaging placed on European markets. China's GB standards for packaging materials, administered by SAMR, restrict heavy metal content in printed paperboard surfaces destined for food-contact applications. Stakeholders must monitor divergence between regional recyclability certification schemes and material passport requirements as these frameworks mature.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing virgin fiber allowances while China's GB standards tighten heavy metal limits on printed surfaces, forcing manufacturers to requalify material formulations across multiple certification schemes simultaneously.
Growth Catalysts
- EU Ecodesign requirements:Minimum recycled content thresholds for paperboard packaging placed on European markets are pulling demand toward certified fiber streams and closed-loop supply arrangements.
- Luxury cosmetics end-use:Premium fragrance and skincare brands in France and South Korea are specifying rigid lift-off lid constructions for unboxing-driven brand equity.
- Guangdong province cluster:Specialized rigid box manufacturers concentrate around Shenzhen and Dongguan, creating density advantages for tooling, lamination, and hand-assembly labor pools.
Market Restraints
- Pulp cost volatility:Integrated paperboard producers with captive pulp supply control input economics, leaving non-integrated converters exposed to spot market fluctuations in northern bleached softwood kraft.
- Composite recyclability:Mixed-fiber structures with laminated films or foil stamping face stream contamination barriers under US EPA recycling standards, limiting post-consumer recovery rates.
- Automation ceiling:Handcrafted rigid box construction for luxury segments resists line-speed scaling, constraining volume elasticity during demand surges.
Strategic Opportunities
- Extended producer responsibility tailwinds:US state-level EPR laws are mandating producer-funded collection infrastructure, creating first-mover advantages for brands with pre-qualified recyclable formats.
- Reusable packaging applications:Archival storage and gift-box reuse cycles are extending effective brand impressions beyond point-of-sale in jewelry and spirits categories.
- Digital print convergence:Hybrid production lines combining offset base lamination with inkjet personalization are enabling short-run customization for subscription box services.
Industry Challenges
- Material passport compliance:Divergence between regional recyclability certification schemes requires parallel documentation systems for EU, US, and Chinese market access.
- Skilled hand-assembly labor:Premium rigid box finishing depends on trained craftspeople for corner stays and wrapped edge execution, with limited apprenticeship pipeline replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lift-Off Lid Box Market |
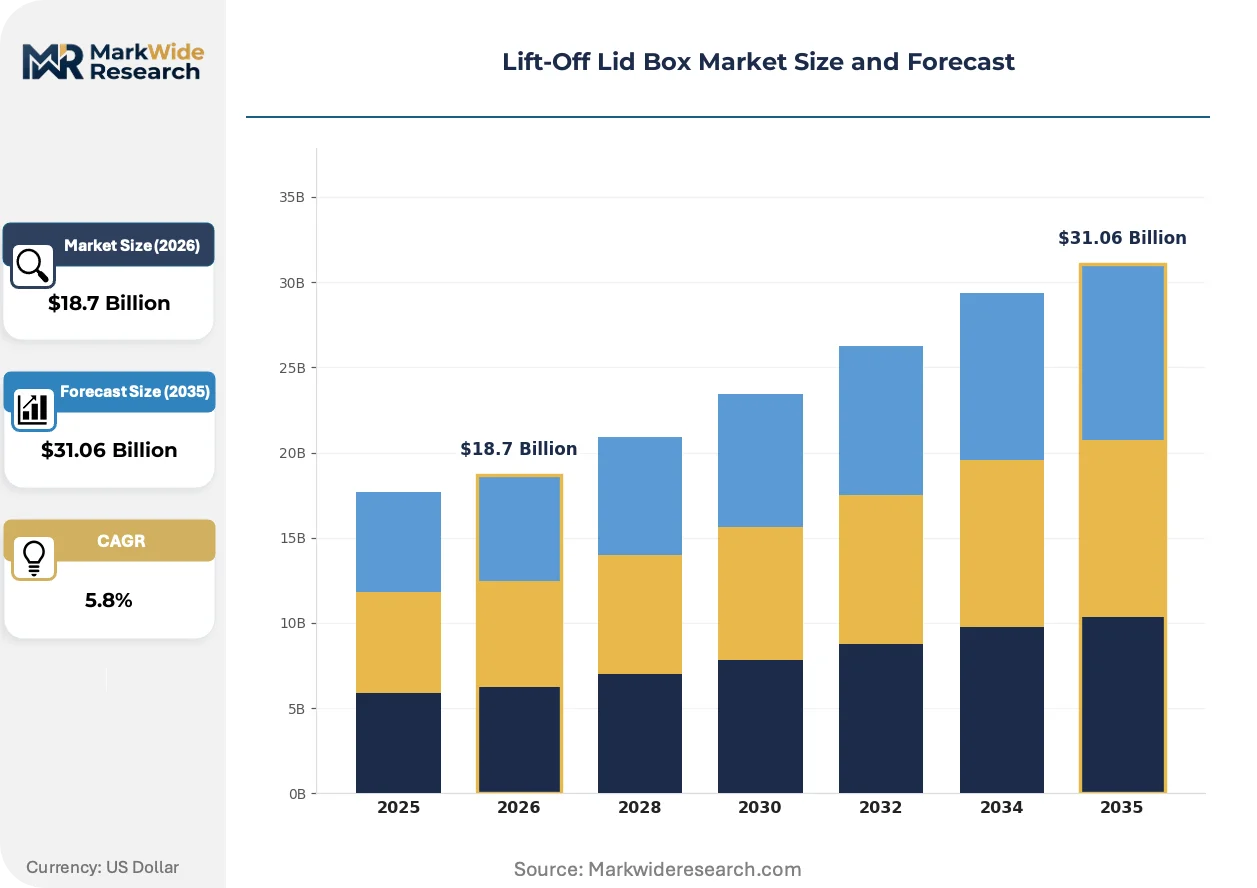
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Box Type: Rigid Boxes, Folding Boxes, Eco-Friendly Boxes, Custom Boxes Material: Cardboard, Paperboard, Plastic, Wood End User: Retail, E-commerce, Food & Beverage, Cosmetics Size: Small, Medium, Large, Extra Large |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa Group, DS Smith Plc, Burt Rigid Box Inc., Taylor Box Company, PakFactory, Sunrise Packaging Inc., Elegant Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lift-Off Lid Box Market Shifts & Advancements
Material science advances and regulatory stringency are reconfiguring specification priorities across the value chain, with sustainability credentials now filtering supplier selection before cost negotiations.
Water-based barrier coatings are fragmenting the traditional polyethylene-laminated paperboard segment by eliminating plastic film layers while maintaining grease resistance. Food-contact and cosmetics brands in Germany and the Netherlands are piloting these substrates for premium positioning. The technology is fragmenting incumbent supply relationships as converters must qualify new coating chemistries and heat-seal parameters.
China's GB standards for packaging materials, administered by SAMR, now restrict heavy metal migration from printed surfaces into food-contact applications. Manufacturers serving dual-use cosmetic and food gift markets must segregate production lines or reformulate ink systems. The regulation most affects exporters using legacy solvent-based gravure presses in Shandong and Zhejiang provinces.
Direct-to-brand procurement patterns are compressing traditional distributor intermediation in North American and European markets. Subscription box services and boutique cosmetics labels now specify directly with rigid box converters, bypassing packaging wholesalers. This disintermediation is most pronounced in California and New York metro areas where brand creative teams co-locate with fulfillment infrastructure.
Lift-Off Lid Box Market Segmentation
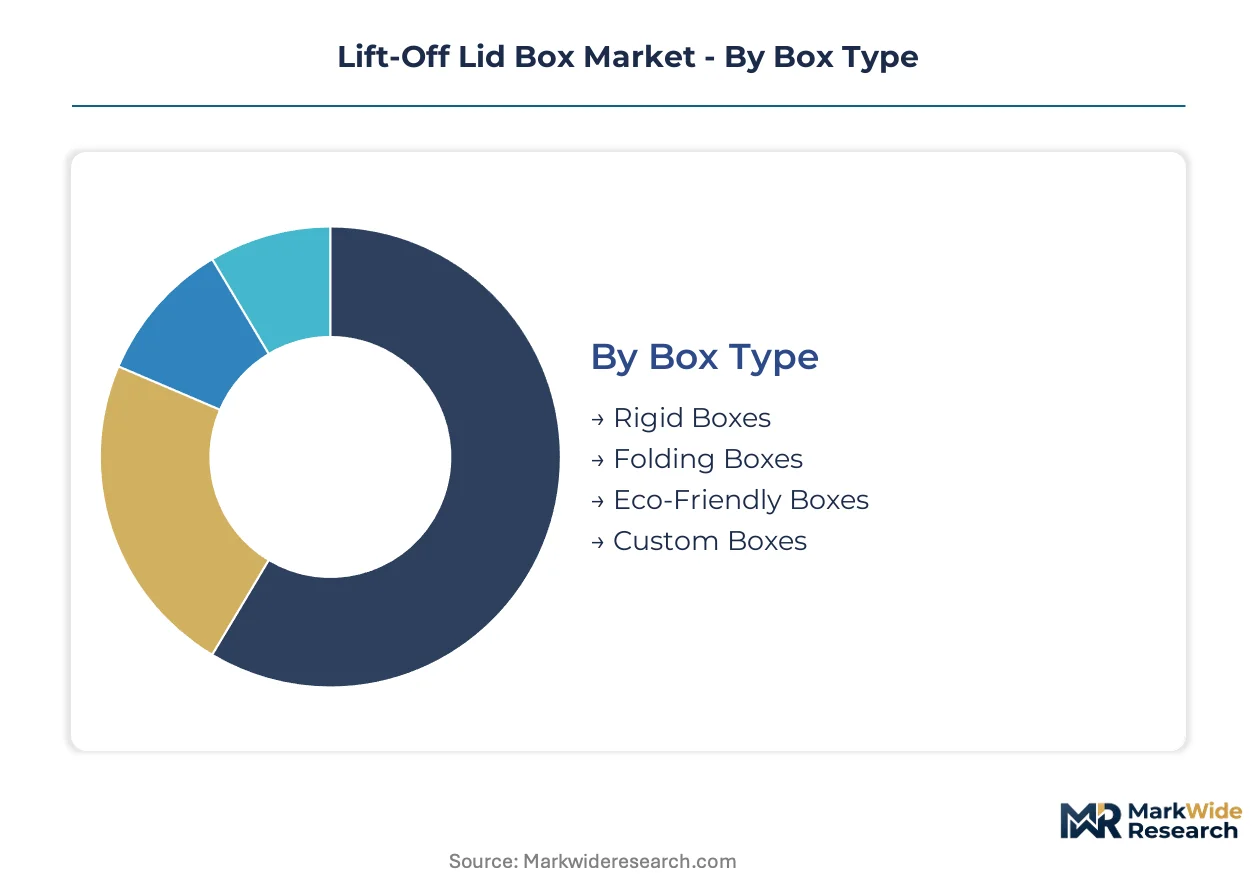
Segmentation in the lift-off lid box market reveals where substitution pressures and margin pools concentrate. Rigid constructions command premium positioning in luxury unboxing experiences, while folding formats compete on logistics efficiency in high-velocity channels.
Box Type:
Substitution pressure runs strongest against laminated folding boxes as water-based barrier coatings displace polyethylene films in food-contact applications.
- Rigid Boxes:Constructed from wrapped chipboard or greyboard with corner stays for structural permanence through repeated opening cycles. Demand concentrates in French and South Korean luxury cosmetics for unboxing-driven brand equity, though hand-assembly constraints limit volume elasticity.
- Folding Boxes:Flat-ship designs with creased paperboard that erects at point of use, optimized for e-commerce subscription throughput. China's Guangdong province cluster around Shenzhen and Dongguan supplies tooling and lamination infrastructure at scale.
- Eco-Friendly Boxes:Certified fiber streams and closed-loop supply arrangements meeting EU Ecodesign recycled content thresholds.
- Custom Boxes:Hybrid production lines combining offset base lamination with inkjet personalization for short-run brand specifications.
Folding boxes retain volume leadership; rigid boxes hold the steepest expansion curve.
Material:
Cost tier stratification separates virgin fiber grades from recycled-content specifications as regulatory thresholds tighten across EU and Chinese markets.
- Cardboard:Lower basis-weight constructions for single-use gift and retail applications with limited reuse cycles.
- Paperboard:Higher caliper grades including solid bleached sulfate and coated unbleached kraft, specified for premium surface print quality and structural rigidity in cosmetics presentations.
- Plastic:PET and PP substrates for moisture-critical applications, facing displacement pressure from fiber-based barrier coatings in EU pilot programs.
- Wood:Veneer-wrapped or solid constructions for ultra-premium spirits and jewelry archival storage, commanding material cost premiums that justify limited automation.
Paperboard dominates value capture; wood maintains the narrowest but highest-margin niche.
End User:
Application-driven specification divergence separates unboxing-experience investments from logistics-cost minimization priorities.
- Retail:Point-of-sale presentations requiring shelf-ready structural integrity and high-impact graphics for impulse conversion.
- E-commerce:Flat-ship efficiency dominates, with direct-to-brand procurement bypassing traditional distributor intermediation in California and New York metro areas.
- Food & Beverage:China's SAMR-administered GB standards restrict heavy metal migration from printed surfaces, forcing ink system reformulation for dual-use cosmetic and food gift production lines.
- Cosmetics:Premium fragrance and skincare brands specify rigid lift-off lid constructions where structural permanence justifies material cost premiums and extends brand impression through reuse cycles.
E-commerce drives shipment volume; cosmetics commands margin concentration.
Size:
Volume scale economics concentrate in mid-range formats while oversized segments face freight cost penalties and dimensional weight pricing.
- Small:Jewelry and sample-size cosmetics where material cost is subordinate to unboxing experience investment per unit.
- Medium:Standard gift and subscription box formats optimizing palletization density and automated fulfillment line compatibility.
- Large:Multi-item sets and spirits presentations requiring reinforced base constructions for weight-bearing performance.
- Extra Large:Limited production runs for specialty retail and archival storage applications with handcrafted finishing dependencies.
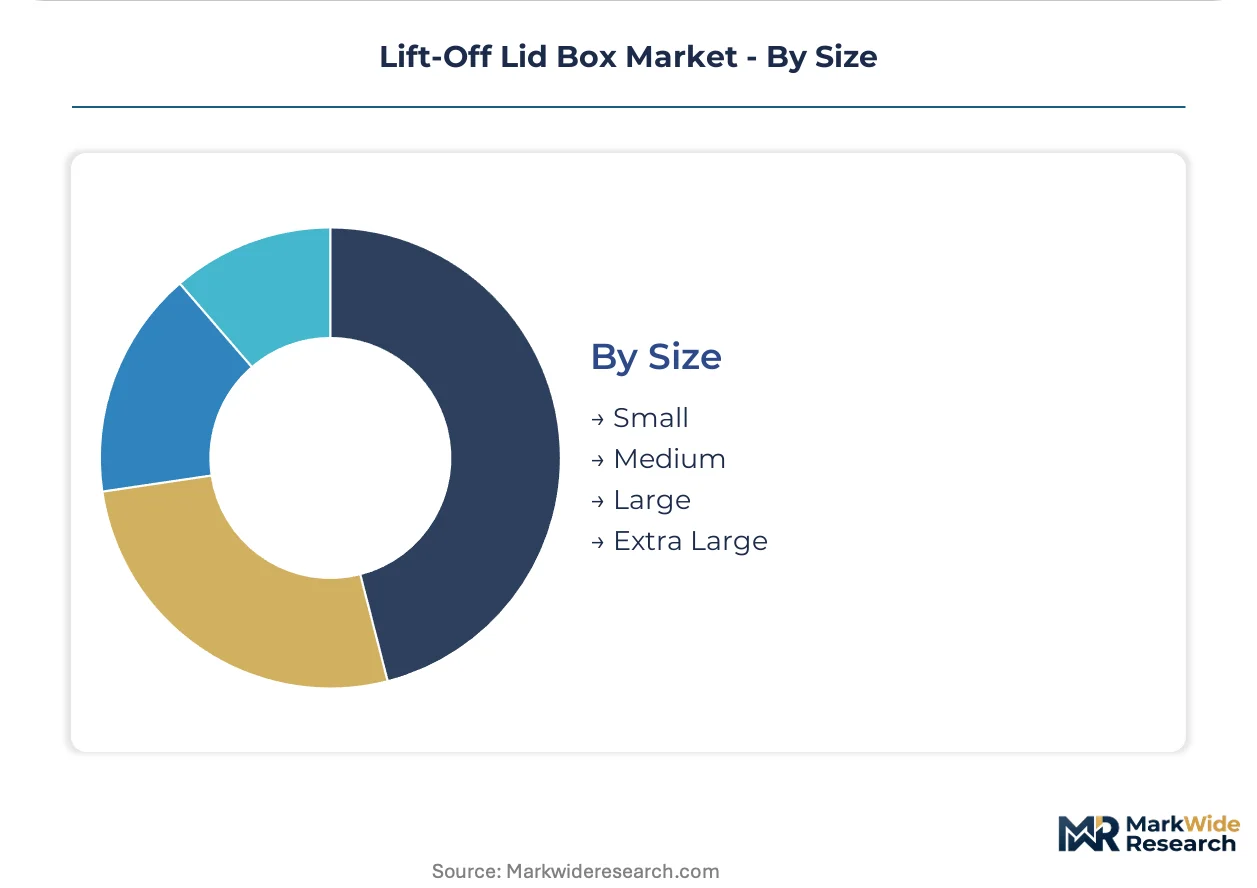
Medium sizes retain shipment leadership; small formats are gaining share fastest in subscription services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in lift-off lid boxes track paperboard cost differentials and luxury goods manufacturing location shifts. China maintains surplus capacity for rigid box fabrication while France and South Korea import specialized constructions for cosmetics presentation. Regulatory divergence between EU Ecodesign thresholds and US EPA recycling standards fragments certification requirements across destination markets.
China
Guangdong province manufacturers cluster around Shenzhen and Dongguan for tooling density and hand-assembly labor pools. SAMR-administered GB standards restrict heavy metal migration from printed surfaces, forcing ink reformulation for exporters serving dual-use cosmetic and food gift segments. The Pearl River Delta supplies rigid box infrastructure at scale for global brand procurement.
United States
Direct-to-brand procurement compresses distributor intermediation in California and New York metro areas where creative teams co-locate with fulfillment infrastructure. EPA recycling stream contamination standards affect mixed-fiber recoverability, limiting post-consumer recovery for laminated constructions. Integrated paperboard producers leverage captive pulp supply to control input economics for high-volume folding grades.
France
Premium fragrance houses specify rigid lift-off lid constructions for unboxing-driven brand equity in Paris and Grasse manufacturing corridors. EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds, pulling demand toward certified fiber streams. The Île-de-France region concentrates luxury packaging specification authority for global cosmetics distribution.
South Korea
Skincare brands in Seoul and Gyeonggi-do specify rigid constructions where structural permanence extends brand impression through reuse cycles. MFDS alignment with international food-contact standards affects dual-use gift box production lines. The Seoul Capital Area anchors premium cosmetics packaging demand for Asian export markets.
Germany
Water-based barrier coating pilots in North Rhine-Westphalia and Bavaria fragment traditional polyethylene-laminated segments for food-contact applications. REACH compliance and EU Ecodesign requirements compress virgin fiber allowances, accelerating closed-loop supply arrangements. The Rhine-Ruhr corridor concentrates converter qualification activity for next-generation substrate chemistries.
Lift-Off Lid Box Market Competitive Landscape
Concentration sits with integrated paperboard producers controlling captive pulp supply and mill networks for cost-positioned folding grades. Boutique rigid-box specialists occupy premium tiers where handcrafted finishing resists automation scaling. Three archetypes structure competition: capital-intensive integrated producers with backward fiber control, regional corrugated converters diversifying into solid board, and craft-oriented rigid box ateliers serving luxury end uses. Dominant competitive moves include geographic expansion into Guangdong manufacturing clusters and portfolio diversification toward water-based barrier substrates.
Among North American integrated producers, International Paper Company and WestRock Company exemplify capital-intensive archetypes with mill network control. Smurfit Kappa Group anchors European demand through corrugated and solid board integration. Burt Rigid Box Inc. occupies the craft-specialist tier where hand-assembly execution commands premium positioning in cosmetics and jewelry segments.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| DS Smith Plc |
| Burt Rigid Box Inc. |
| Taylor Box Company |
| PakFactory |
| Sunrise Packaging Inc. |
| Elegant Packaging |
| Others |
Supply & Pricing Matrix
EU Ecodesign requirements and recycled content thresholds gate both supplier qualification and price differentiation simultaneously, forcing converters to absorb certification costs or forfeit premium tier access while integrated producers leverage captive fiber streams to defend margin positions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, though luxury cosmetics brands command project-based premiums for handcrafted rigid constructions. Price differentiation rests on certification grade and volume scale, with FSC-certified fiber streams commanding tier premiums over standard grades. Cost compression in folding box tiers is intensifying because Guangdong cluster competition erodes converter margins. E-commerce subscription services exhibit highest price sensitivity, while French fragrance houses remain least sensitive due to unboxing-experience ROI.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as pulp cost volatility drives integrated producers to maintain captive inventory buffers. Geographic supply concentrates in China, the United States, and Sweden for paperboard substrate production. Raw material dependencies draw from northern bleached softwood kraft, recycled fiber streams, and water-based barrier coating chemistries. Single-source vulnerability sits with Guangdong hand-assembly labor pools for premium rigid box finishing. Distribution runs through direct-to-brand channels in California and New York metro areas, bypassing traditional packaging wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based barrier coating commercialization constitutes a high-growth disruption, with EU regulatory deadlines forcing substrate transitions that fragment incumbent polyethylene-laminated supply relationships.
For Market Incumbents: Compound defensive positioning through backward integration into captive pulp supply and water-based coating qualification programs. Integrated producers should expand Guangdong tooling partnerships to secure hand-assembly capacity for luxury tier defense. Certification investment in closed-loop fiber streams represents the critical lever against non-integrated converter erosion. For New Entrants and Emerging Players: FSC chain-of-custody fast-track programs unlock white-space access in EU cosmetics procurement where incumbent qualification lags. Target mid-tier subscription box services in North American markets where direct-to-brand procurement patterns bypass established distributor relationships. Digital print convergence offers the most penetrable go-to-market angle for short-run customization capabilities. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation implementation reshapes the acquisition landscape toward converters with pre-qualified recyclable formats and regional certification documentation systems. Long-term viability favors craft-oriented rigid box ateliers with trained hand-assembly workforces and established luxury brand relationships. Monitor water-based barrier coating adoption rates as the signal for substrate transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pulp Supply | International Paper and WestRock leverage North American mill networks to control input economics against spot market volatility. |
| Water-Based Barrier Coating Qualification | German and Dutch pilot programs fragment polyethylene-laminated segments for food-contact and cosmetics applications. |
| Guangdong Manufacturing Cluster Expansion | Shenzhen and Dongguan concentration provides tooling density and hand-assembly labor pools for premium rigid box output. |
| Direct-to-Brand Channel Development | California and New York metro creative teams co-locating with fulfillment infrastructure bypass traditional packaging distributors. |
| Closed-Loop Fiber Stream Certification | EU Ecodesign recycled content thresholds pull demand toward FSC-certified supply arrangements with documented chain-of-custody. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings. Conversations with rigid box converters, luxury cosmetics packaging directors, Guangdong manufacturing cluster managers, and pulp procurement leads at integrated producers inform supply-side dynamics. Secondary validation draws from EPA recycling stream standards, EU Packaging and Packaging Waste Regulation documentation, SAMR GB standards filings, and trade flow data from customs records. Bottom-up capacity assessments and top-down demand modeling triangulate market sizing across the analysis window.
Sensitivity analysis frameworks test forecast robustness against pulp cost volatility scenarios and regulatory implementation timelines. Segmentation dimensions include box type, material grade, end-use application, and geographic production cluster. CAGRs derive from trend-line extrapolation of historical shipment data adjusted for substitution effects and regulatory displacement. Industry-specific forecast inputs incorporate EU recycled content threshold compliance curves and water-based barrier coating adoption rates.
Decision-makers should treat outputs as directional under base assumptions of stable pulp supply and phased regulatory implementation; material deviation would warrant model refresh. Revision becomes warranted when water-based barrier coating cost parity crosses threshold viability against polyethylene lamination.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Essential Oil Containers Market
Containers
North America Insulated Shipping Containers Market
Containers
Wire Containers Market
Containers
Foldable Container Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Conipack Pails Market
Containers
Slip Lid Can Market
Containers
Spout Containers Market
Containers
Stack and Nest Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
Dispensing Jug Market
Containers
Trays Market
Containers
Asia and Africa Food Cans Market
Containers
Thin Wall Plastic Containers Market
Containers
Stackable Plastic Trays Market
Containers
Dual-Ovenable Trays and Containers Market