
 Nucleating and Clarifying Agents Market | 2026-2036
Nucleating and Clarifying Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleating and Clarifying Agents Market Intelligence
A capital-intensity divergence between integrated multinational suppliers and regional compounders is bifurcating competitive dynamics. Milliken & Company leverages its Spartanburg research campus to sustain proprietary hypernucleating technology for thin-wall packaging. ADEKA Corporation anchors Asian supply through captive production of sorbitol-based clarifiers in Japan and Thailand. Zibo Rainwell Co. Ltd. competes on cost-positioned powder grades serving Shandong province's extrusion base.
Nucleating and clarifying agents are specialty additives that induce controlled crystallization in semi-crystalline thermoplastics, typically dosed at 0.1–0.3 wt% to reduce haze and raise heat-deflection temperature. These agents function by providing heterogeneous nucleation sites that accelerate crystal growth rates without degrading optical clarity in applications such as thermoformed food containers and automotive interior panels. Polypropylene-grade clarifiers command premium positioning due to stringent optical specifications in healthcare and food-contact segments, while polyolefin nucleating agents for automotive structural parts concentrate volume. Powder and granular forms dominate industrial handling, though liquid concentrates are gaining traction in continuous compounding lines where dosing precision reduces waste.
REACH registration requirements under ECHA govern aromatic-based clarifier chemistries in Europe, while FDA food-contact notifications constrain substance migration limits for U.S. packaging applications. China's GB standards for plastic food-contact materials, administered by SAMR, are tightening testing protocols for nucleating agent purity and heavy-metal content. Formulators must monitor evolving regulatory thresholds across these jurisdictions to preserve market access and avoid reformulation costs.
Market Dynamics
Integrated polypropylene producers in China's Yangtze River Delta are internalizing additive compounding operations, compressing margins for independent masterbatch suppliers and forcing specialization around regulatory compliance and custom formulation services.
Growth Catalysts
- Recycled content mandates:Brand owners in Southeast Asia are mandating higher post-consumer thresholds in packaging, requiring clarifying masterbatches that restore optical properties to mechanically recycled polypropylene.
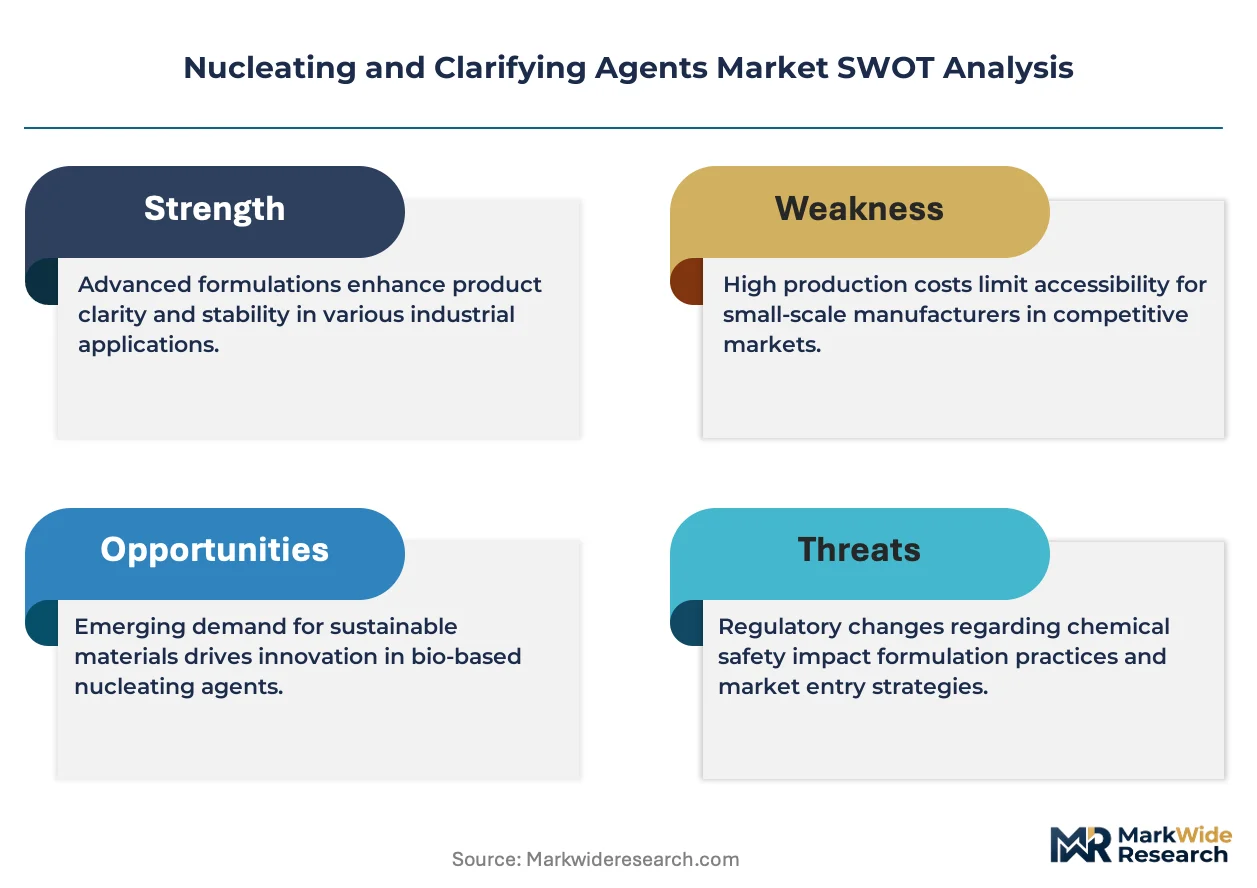
- REACH compliance redirection:ECHA registration requirements for aromatic-based chemistries are accelerating formulation shifts toward sorbitol-derived alternatives in European food-contact applications.
- Thin-wall packaging specifications:Healthcare and dairy processors demand hypernucleating grades that maintain stiffness-to-weight ratios in reduced-gauge thermoformed containers.
Market Restraints
- Feedstock volatility:Sorbitol prices fluctuate with corn and tapioca starch markets, squeezing margin predictability for clarifier compounders dependent on bio-based feedstocks.
- Supply concentration:Captive production of advanced nucleating agents concentrates among Japanese and Thai facilities, creating geographic single-source risk for European and North American converters.
- Migration limit stringency:FDA food-contact notifications constrain substance thresholds below detection limits achievable with legacy aromatic chemistries, forcing premature formulation obsolescence.
Strategic Opportunities
- Automotive interior panels:Polyolefin nucleating agents for structural parts face underpenetration in electric vehicle platforms seeking weight reduction without sacrificing heat-deflection temperature.
- Liquid concentrate formats:Continuous compounding lines favor precision-dosed liquid systems over powder handling, opening channel innovation for dosing equipment-integrated suppliers.
- EU Green Deal alignment:Biodegradable nucleating chemistries qualifying for EU taxonomy sustainable finance criteria access preferential procurement from packaging majors with Science Based Targets.
Industry Challenges
- Crystallization kinetics expertise:Formulators lack sufficient polymer physics specialists to optimize nucleating agent selection across variable cooling-rate processing conditions.
- Dual certification timelines:Simultaneous pursuit of FDA food-contact approval and EFSA safety assessments extends time-to-market by 18-24 months for novel chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleating and Clarifying Agents Market |
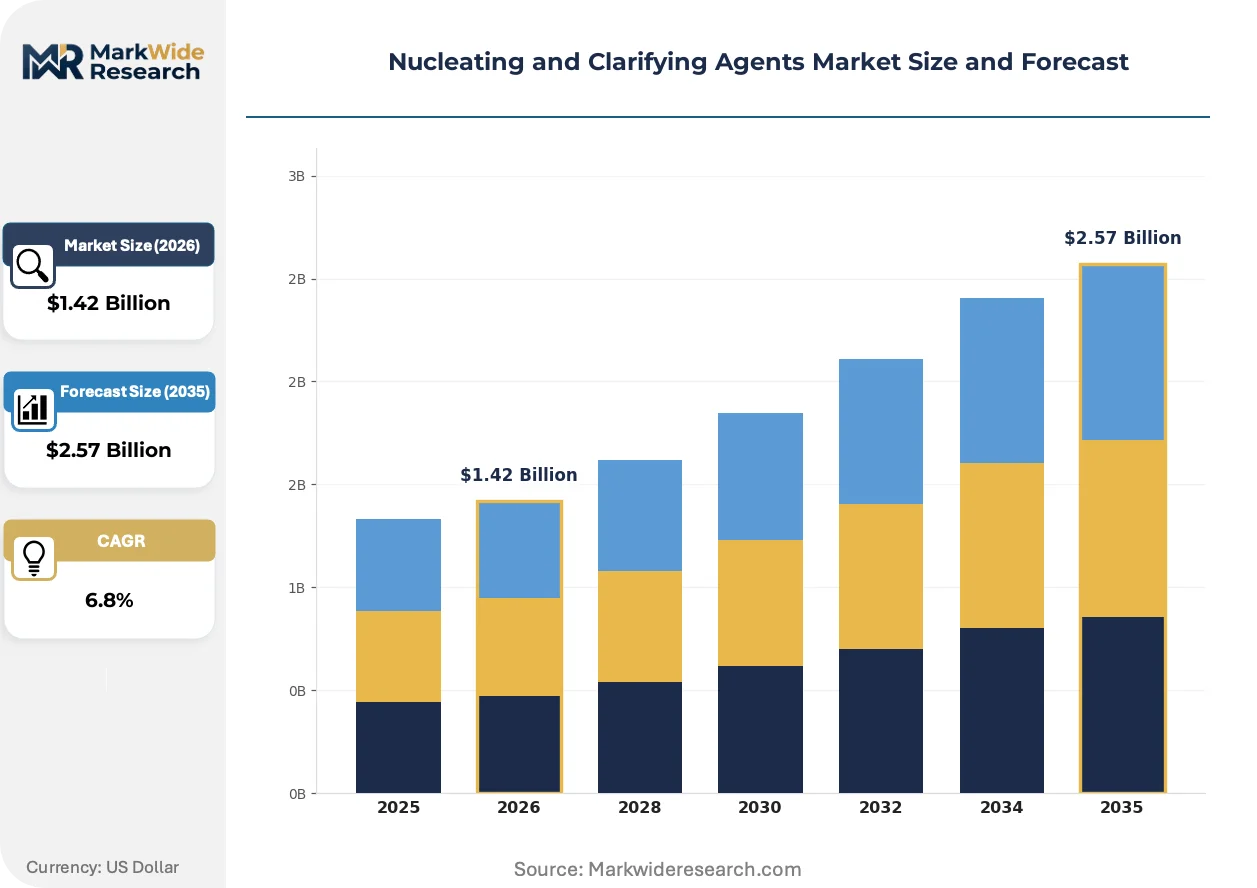
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, Polypropylene, Polystyrene, Polyester Application: Packaging, Automotive Parts, Consumer Goods, Textiles End User: Manufacturers, Retailers, Wholesalers, Distributors Form: Granular, Powder, Liquid, Concentrate |
| Companies Covered | Milliken & Company, ADEKA Corporation, BASF SE, Clariant AG, Amfine Chemical Corporation, Imerys, Zibo Rainwell Co. Ltd., Polyvel Inc., Everspring Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleating and Clarifying Agents Market Strategic Shifts & Innovations
Hypernucleating and clarifying technologies are bifurcating between premium optical grades for healthcare and cost-optimized powder formulations for commodity packaging, with regulatory chemistry constraints accelerating this divergence.
Non-aromatic sorbitol-derived clarifiers are displacing traditional dibenzylidene sorbitol chemistries in European and North American food-contact applications. Major dairy and ready-meal packaging converters in Germany and the Netherlands have completed formulation transitions since REACH restrictions tightened. This displacement is compressing demand for legacy aromatic grades while expanding addressable market for bio-based alternatives with equivalent haze performance.
REACH registration requirements under ECHA now govern aromatic-based clarifier substances at tonnage thresholds triggering full safety dossier submission. Industrial consequence includes withdrawal of several legacy clarifiers from European distribution by multinational suppliers unwilling to bear registration costs. Food-contact packaging segments in France and Italy are most affected, responding through accelerated qualification of sorbitol-based replacements and direct supplier engagement with Japanese clarifier manufacturers.
Brand-owner procurement teams are consolidating additive purchasing through integrated masterbatch suppliers rather than direct nucleating agent sourcing. This channel consolidation disrupts historical relationships between compounders and independent additive distributors. The shift is most visible in Southeast Asian packaging clusters, where converters seek single-source accountability for optical performance and regulatory documentation across recycled-content supply chains.
Nucleating and Clarifying Agents Market Segmentation
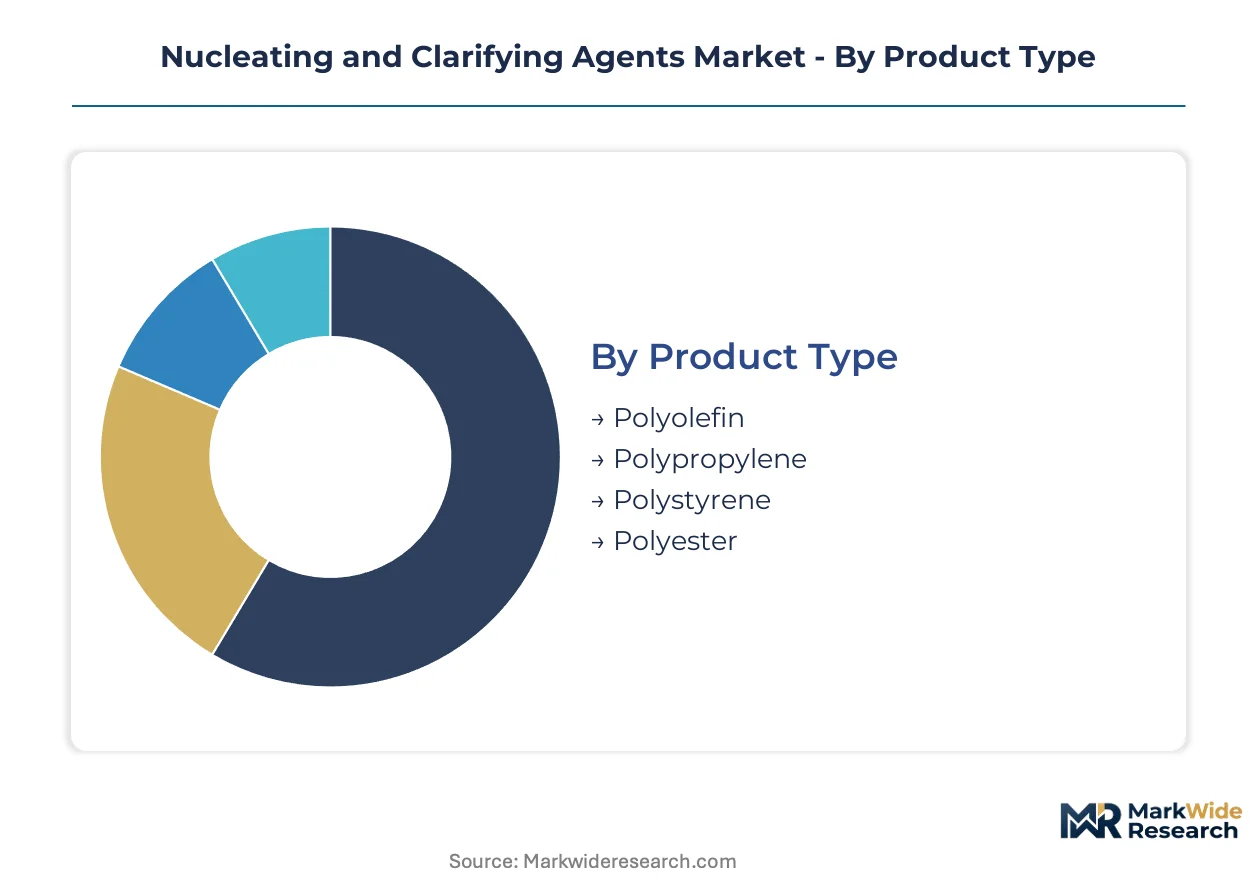
Segmentation in nucleating and clarifying agents reveals how formulation chemistry, physical form, and customer channel create distinct margin structures. Each dimension carries implications for regulatory compliance, processing equipment compatibility, and geographic sourcing strategy.
Product Type:
Polypropylene-grade agents dominate export flows to Southeast Asian packaging converters, while polyolefin nucleating agents serve largely domestic automotive supply chains in Germany, Japan, and the United States.
- Polyolefin:These agents accelerate crystallization in polyethylene and copolymer resins used for automotive structural components. Demand concentrates with tier-one suppliers in Stuttgart and Detroit serving electric vehicle platforms seeking heat-deflection temperature improvements without metal substitution.
- Polypropylene:Sorbitol-derived clarifiers for this resin achieve optical clarity below 2% haze in thin-wall food containers. Southeast Asian packaging converters in Thailand and Vietnam procure masterbatches to meet recycled-content mandates from multinational brand owners.
- Polystyrene:Nucleating agents for crystal and impact grades reduce cycle times in injection-molded consumer electronics housings. Japanese compounders in Osaka prefecture represent the primary demand concentration.
- Polyester:Agents for PET and PBT engineering resins enhance mold release in connector applications. German automotive wiring harness manufacturers drive specification requirements.
Polypropylene holds the largest share; momentum sits with polyolefin grades as electric vehicle production expands.
Application:
Cost tier differentiation separates premium healthcare packaging from commodity food containers, with automotive parts commanding intermediate pricing based on heat-performance certification.
- Packaging:Thermoformed dairy containers and ready-meal trays require FDA-compliant clarifiers with migration limits below detection thresholds. German and Dutch converters have completed formulation transitions to sorbitol-based alternatives under REACH pressure.
- Automotive Parts:Structural interior panels utilize hypernucleating agents to maintain stiffness-to-weight ratios in reduced-gauge designs. Underpenetration persists in electric vehicle platforms where battery enclosure thermal management competes for material selection attention.
- Consumer Goods:Transparent storage containers and housewares demand cost-optimized powder grades. Shandong province extrusion bases in China source from domestic compounders competing on price position.
- Textiles:Fiber-grade nucleating agents improve dye uptake and tensile consistency in polypropylene nonwovens. Turkish textile manufacturers near Istanbul represent growing demand for spunbond applications.
Packaging generates the highest volume; automotive parts are climbing the fastest as lightweighting specifications tighten.
End User:
Volume concentration varies sharply by channel, with manufacturers internalizing compounding operations while distributors retain relevance in regulatory documentation and custom formulation services.
- Manufacturers:Integrated polypropylene producers in China's Yangtze River Delta have brought additive compounding in-house, compressing margins for independent suppliers. This captive production trend concentrates among state-owned petrochemical groups.
- Retailers:Large-format packaging converters in France and Italy source clarifying masterbatches through consolidated procurement teams seeking single-source accountability for optical performance and compliance documentation.
- Wholesalers:Regional distributors in India's Gujarat and Maharashtra states stock powder grades for small and medium extrusion operations serving local flexible packaging markets.
- Distributors:Independent additive distributors in North America retain niche positions in technical service and rapid sample qualification for custom color-matched clarifying systems.
Manufacturers hold the largest share; distributors are gaining share fastest through specialization in dual-certification support for novel chemistries.
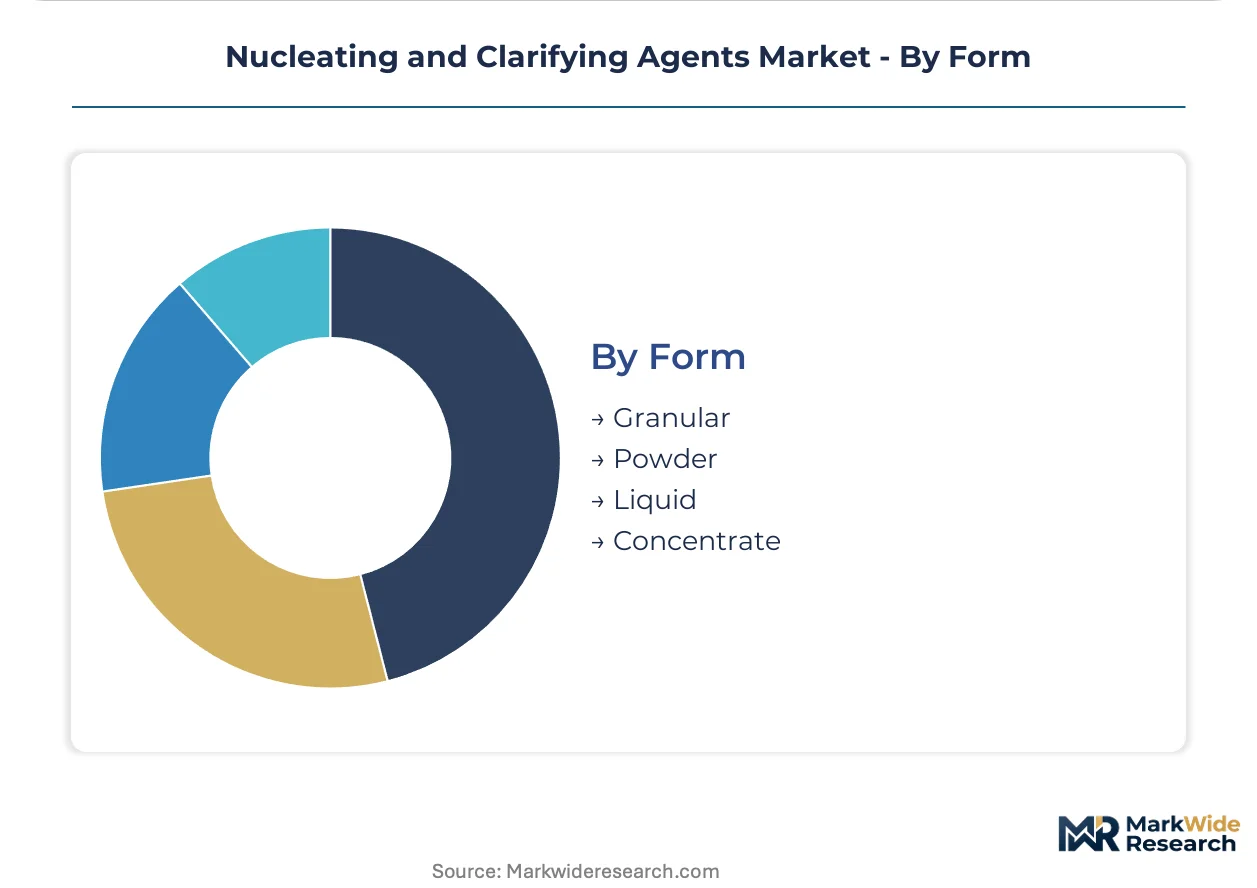
Form:
Supply concentration in liquid concentrate production centers on Japanese and Thai facilities, while powder handling dominates Chinese domestic consumption patterns.
- Granular:Free-flowing pellets suit high-throughput compounding lines with automated dosing systems. Major European masterbatch producers in Belgium and Switzerland prefer this format for batch consistency.
- Powder:Fine-milled sorbitol derivatives remain the default for cost-sensitive commodity packaging. Dust control requirements limit adoption in continuous processing environments.
- Liquid:Precision-dosed systems integrate with continuous compounding lines to reduce waste and improve dispersion uniformity. Japanese suppliers ADEKA and Milliken have developed proprietary carrier fluid technologies.
- Concentrate:High-let-down ratio formulations enable just-in-time dilution at converter sites. Southeast Asian packaging clusters favor this format for inventory flexibility across multiple resin grades.
Powder holds the largest share; liquid formats are expanding most quickly as continuous compounding investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters in Vietnam and Thailand exhibit acute price sensitivity to sorbitol-based clarifier costs, whereas German automotive compounders absorb premium pricing for hypernucleating grades that certify heat-deflection performance in electric vehicle interior panels.
United States
FDA food-contact notifications constrain migration limits for nucleating agents in dairy packaging below detection thresholds achievable with legacy aromatic chemistries. Brand owners in the Upper Midwest dairy belt mandate sorbitol-derived clarifiers for thermoformed containers. Spartanburg, South Carolina anchors proprietary hypernucleating research serving thin-wall healthcare packaging specifications.
Germany
REACH registration requirements under ECHA govern aromatic-based clarifier substances at tonnage thresholds triggering full safety dossier submission. Stuttgart-area tier-one automotive suppliers procure polyolefin nucleating agents for structural interior panels in electric vehicle platforms. The Rhine-Ruhr industrial corridor hosts masterbatch producers consolidating additive procurement for French and Dutch packaging converters.
China
GB standards administered by SAMR tighten testing protocols for nucleating agent purity and heavy-metal content in food-contact materials. State-owned petrochemical groups in the Yangtze River Delta have internalized additive compounding operations, compressing margins for independent suppliers. Shandong province extrusion bases source cost-positioned powder grades from domestic compounders competing on price position.
Japan
METI industrial policy supports advanced materials development for export-oriented specialty chemical production. Osaka prefecture compounders represent primary demand concentration for polystyrene nucleating agents in injection-molded consumer electronics housings. Chubu region facilities anchor Asian supply of sorbitol-based clarifiers through captive production serving Thai packaging converters.
Thailand
Southeast Asian packaging converters expand procurement of clarifying masterbatches as multinational brand owners mandate higher post-consumer recycled content thresholds. Japanese clarifier manufacturers direct-engage Thai compounders to bypass distribution layers. Bangkok-area masterbatch facilities qualify sorbitol-derived formulations for export to Vietnamese and Indonesian flexible packaging markets.
Nucleating and Clarifying Agents Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in nucleating and clarifying agents. Multinational chemical conglomerates with captive polymer operations leverage backward integration into additive synthesis, while independent compounders defend position through regulatory documentation services and custom formulation capabilities. Three archetypes dominate: integrated petrochemical groups internalizing compounding, Japanese specialty chemical producers with captive Asian manufacturing, and regional Chinese powder-grade suppliers competing on cost position. Capacity expansion in liquid concentrate formats and geographic licensing of hypernucleating technology constitute the dominant competitive moves.
Among Japanese specialty chemical producers, ADEKA Corporation exemplifies the captive-production archetype with integrated manufacturing in domestic and Thai facilities. Milliken & Company occupies a position in the premium technology tier, represented in the raw data as a research-intensive operator with proprietary hypernucleating capabilities. Zibo Rainwell Co. Ltd. anchors the cost-competitive Chinese specialist tier, supplying powder grades to Shandong province extrusion bases without international brand positioning.
| Leading Market Players |
|---|
| Milliken & Company |
| ADEKA Corporation |
| BASF SE |
| Clariant AG |
| Amfine Chemical Corporation |
| Imerys |
| Zibo Rainwell Co. Ltd. |
| Polyvel Inc. |
| Everspring Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
FDA food-contact notification thresholds simultaneously gate supplier qualification and stratify price tiers, forcing compounders to absorb dual-certification costs that separate premium sorbitol-derived clarifiers from legacy aromatic grades facing formulation obsolescence. REACH registration requirements under ECHA impose parallel entry barriers in Europe, concentrating pricing power among Japanese and Thai producers with captive production and existing dossier compliance.
Pricing Analysis
After-sales technical service contracts and regulatory documentation packages drive lifetime value for clarifying masterbatch suppliers serving multinational brand owners. Three-tier pricing structure across premium optical grades, standard food-contact formulations, and economy powder positions reflects certification tier and volume scale differentiation. Pricing pressure stems from Yangtze River Delta integrated producers internalizing compounding operations and compressing margins for independent suppliers. Southeast Asian packaging converters exhibit acute price sensitivity to sorbitol feedstock volatility, while German automotive compounders absorb premium positioning for hypernucleating grades certifying heat-deflection performance.
Supply Chain Analysis
Malacca Strait transit and Bangkok port congestion chokepoints expose just-in-time clarifier concentrate flows to Southeast Asian packaging clusters. Geographic supply concentrates in Japan, Thailand, and China, with Chubu region facilities anchoring Asian sorbitol-based clarifier production. Raw material dependencies rest on corn and tapioca starch markets for sorbitol feedstock, alongside specialized carrier fluid chemistries for liquid concentrate formats. Single-source vulnerability concentrates among Japanese captive production facilities serving European and North American converters. Distribution runs through integrated masterbatch suppliers consolidating additive procurement rather than direct nucleating agent sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where brand-owner procurement consolidation and regulatory chemistry constraints are creating interoperability standards around dual-certified clarifier formulations that favor integrated suppliers with existing FDA-EFSA dossier libraries.
For Market Incumbents: Compound defensive positioning through backward integration into sorbitol feedstock processing and captive liquid concentrate capacity additions in Thailand or Vietnam. Consolidate channel control by acquiring regional distributors with established regulatory documentation services, as independent masterbatch suppliers face margin compression from Yangtze River Delta petrochemical groups internalizing compounding operations. For New Entrants and Emerging Players: Differentiate on biodegradable nucleating chemistries qualifying for EU taxonomy sustainable finance criteria, targeting packaging majors with Science Based Targets procurement mandates. White-space penetration concentrates in electric vehicle interior panel applications where polyolefin nucleating agents remain underpenetrated relative to battery thermal management materials. Go-to-market execution favors direct engagement with Thai compounders serving Vietnamese and Indonesian flexible packaging markets. For Investors and Strategic Acquirers: REACH registration deadlines for aromatic-based clarifier substances reshape the acquisition landscape toward targets with existing ECHA dossier compliance and Japanese-Thai manufacturing footprints. Long-term viability favors vertically integrated specialists with captive sorbitol processing and dual-certification capabilities across FDA and EFSA jurisdictions. Watch for inflection signals in brand-owner recycled-content mandate thresholds accelerating clarifying masterbatch demand restoration for mechanically recycled polypropylene.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sorbitol Processing | Captive feedstock supply from corn and tapioca starch markets insulates margin predictability against commodity volatility. |
| Liquid Concentrate Capacity Expansion | Precision-dosed systems align with continuous compounding investments at Southeast Asian packaging converters. |
| Dual-Certification Dossier Investment | Simultaneous FDA and EFSA approval pathways accelerate time-to-market for novel sorbitol-derived chemistries. |
| Regional Distribution Acquisition | Regulatory documentation capabilities defend position against integrated masterbatch supplier consolidation. |
| Biodegradable Chemistry Development | EU taxonomy alignment opens preferential procurement channels from packaging majors with Science Based Targets. |
Research Approach
A standing panel of technical R&D directors at polypropylene producers, procurement leads at Southeast Asian packaging converters, masterbatch compounders in Germany and Thailand, and regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical conglomerates, ECHA registration databases, and FDA food-contact notification records. Bottom-up volume builds across resin-grade segments triangulated against top-down petrochemical capacity forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including polymer type, application end-use, physical form, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating recycled-content mandate trajectories and electric vehicle platform lightweighting specifications. Industry-specific inputs included sorbitol feedstock price indices and clarifier migration limit regulatory thresholds.
Material uncertainties — feedstock commodity volatility, REACH registration timeline delays, and brand-owner recycled-content threshold acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory chemistry displacement rates and captive production internalization trends. Practitioners should keep alternative scenarios live as ECHA aromatic substance restrictions and FDA detection limit stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Silage Additives Market
Additives
Global Scale Inhibitors Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Potassium Nitrate Market
Additives
Clouding Agents Market
Additives
Global Feed Acidifiers Market
Additives
Metal Modifiers Market
Additives
Chitosan Powder Market
Additives
Alginic Acid Market
Additives
Sodium Citrate Anhydrous Market
Additives
Supplemental Coolant Additives Market
Additives
Gluconic Acid and Derivatives Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Monocalcium Phosphate Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Global Flame Retardant Masterbatches Market