
 2-Ethylhexyl Nitrate (2EHN) Market | 2026-2036
2-Ethylhexyl Nitrate (2EHN) Market Size, Share, and Industry Trends Forecast 2026-2036
2-Ethylhexyl Nitrate (2EHN) Market Insights
Modular additive bundling with cetane improvers, lubricity agents, and cold-flow modifiers is hardening procurement preferences among fleet operators and fuel blenders. Innospec Inc. leverages its integrated fuel additive technology platform to sustain long-term supply agreements with European refiners. Afton Chemical anchors its position through specialized combustion chemistry R&D centers in North America and Asia. Deepak Nitrite Limited competes on manufacturing scale from its Indian production base, supplying regional diesel additive formulators.
2-Ethylhexyl nitrate is an organic nitrate ester synthesized through nitration of 2-ethylhexanol, typically yielding a colorless to pale yellow liquid with flash points near 76 degrees Celsius and primary function as a cetane number improver in diesel fuels. The additive segment commands the deepest margin pools where fuel performance specifications drive premium pricing for high-purity grades. Automotive application demand leads absolute volume consumption, while chemical intermediates for pharmaceutical nitrate synthesis represent the fastest-expanding niche within the application portfolio. Bulk delivery modes dominate refinery procurement, though IBC configurations are gaining traction among mid-size blenders seeking inventory flexibility.
EPA fuel additive registration requirements under 40 CFR Part 79 govern market access for 2EHN sold into US transportation fuel pools, while REACH compliance in Europe mandates full toxicological dossiers for nitrate ester imports. China's MEE enforces dual carbon goals that pressure refiners toward lower-emission cetane improver formulations, indirectly filtering supplier qualification standards. India's BIS certification for petroleum additives adds another compliance layer for imported additive packages. Stakeholders must monitor how evolving NOx emission caps in major automotive markets recalibrate the technical specifications that define premium versus commodity-grade 2EHN acceptance criteria.
Market Dynamics
Refinery procurement consolidation around bundled additive packages is compressing standalone 2EHN spot markets while elevating long-term formulation partnerships. China's MEE dual carbon mandates and India's BIS certification layers are filtering supplier pools faster than incumbents can expand qualified capacity.
Growth Catalysts
- China MEE dual carbon protocols:Refiners in Shandong and Jiangsu provinces face binding NOx reduction targets that require premium cetane improvers. This regulatory pressure is pulling high-purity 2EHN into domestic fuel pools at accelerating rates.
- Marine diesel specifications:IMO 2020 residual fuel blending operations in Singapore and Rotterdam are absorbing nitrated ester packages to meet engine manufacturer warranty requirements for medium-speed marine engines.
- Modular additive blending:Integrated packages combining cetane improvers with lubricity agents and cold-flow modifiers are hardening procurement preferences among European fleet operators seeking single-source formulation accountability.
Market Restraints
- 2-ethylhexanol feedstock volatility:Oxo-alcohol pricing swings tied to propylene and syngas cost curves are compressing margin predictability for 2EHN manufacturers without backward integration into alcohol production.
- Supplier concentration in India:Deepak Nitrite's dominant position from its Dahej and Nandesari facilities creates single-source risk for regional formulators dependent on spot cargo availability during turnaround seasons.
- Di-tert-butyl peroxide substitution:Organic peroxide cetane improvers are displacing 2EHN in certain non-road diesel applications where storage stability requirements are less stringent and cost sensitivity is acute.
Strategic Opportunities
- Vietnam refining expansion:Nghi Son and Dung Quat refinery upgrades are creating first-mover positioning for additive suppliers able to establish local technical service infrastructure ahead of 2026 capacity ramp.
- Pharmaceutical nitrate intermediates:Isosorbide mononitrate and similar cardiovascular drug precursors represent an emerging application vertical with pricing multiples above fuel additive grades.
- EU Green Deal carbon border adjustments:CBAM implementation is disadvantaging high-carbon-intensity cetane improver imports, creating preference windows for producers with verified low-emission manufacturing footprints.
Industry Challenges
- Nitrate ester handling certification:Specialized HAZMAT training requirements for 2EHN storage and transport are constraining logistics provider availability and extending onboarding timelines for new market entrants.
- REACH dossier maintenance:ECHA toxicological data requirements for nitrate ester imports demand continuous investment in substance evaluation studies, particularly for reproductive toxicity endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Ethylhexyl Nitrate (2EHN) Market |
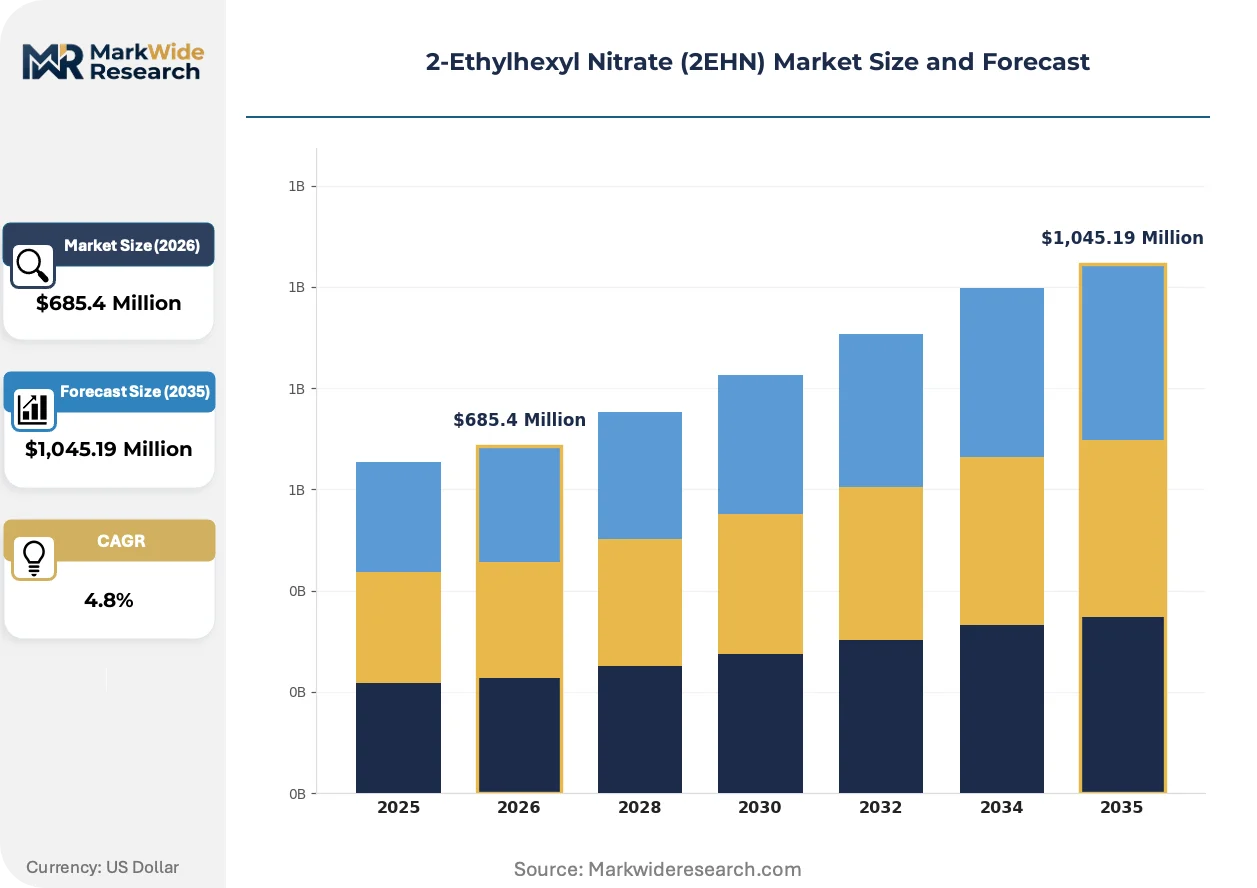
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Additive, Fuel, Intermediate Application: Automotive, Chemicals, Coatings, Pharmaceuticals End User: Manufacturers, Distributors, OEMs, Retailers Delivery Mode: Bulk, Drums, Containers, IBCs |
| Companies Covered | EURENCO, Innospec Inc., Afton Chemical, VeryOne, Deepak Nitrite Limited, Lubrizol, BASF SE, JX Nippon Oil & Energy Corporation, Octel America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Ethylhexyl Nitrate (2EHN) Market Trends and Innovations
Digital formulation platforms and predictive blending analytics are compressing development cycles for next-generation additive packages. These tools are enabling refiners to optimize cetane response curves in real-time rather than relying on static specification sheets.
Continuous-flow nitration reactor technology is rewriting process economics for 2EHN manufacturers. This equipment eliminates batch-to-batch variability, reduces solvent waste volumes, and enables smaller-scale producers to achieve pharmaceutical-grade purity thresholds. European specialty chemical houses are retrofitting existing facilities with skid-mounted continuous units to defend position against Asian volume suppliers.
REACH authorization requirements for Substances of Very High Concern are tightening import documentation burdens for nitrate ester suppliers. ECHA's 2023 updated guidance on PBT assessment criteria is forcing additional ecotoxicology testing for long-chain alkyl nitrates. German and Dutch fuel additive distributors are consolidating supplier panels to reduce compliance administration overhead.
Fleet operator concentration is altering channel economics for 2EHN distribution. Large trucking cooperatives in Poland and Spain are negotiating direct additive supply agreements with manufacturers, bypassing traditional refinery blender intermediaries. This disintermediation is most visible in markets where fuel card networks have achieved sufficient scale to aggregate purchasing power across thousands of independent operators.
2-Ethylhexyl Nitrate (2EHN) Market Segmentation
2-Ethylhexyl nitrate's functional versatility creates distinct margin profiles across product grades, while regulatory stringency in fuel applications fragments specification requirements. Understanding how demand concentrates across these dimensions clarifies where formulation partnerships generate durable revenue streams versus transactional spot sales.
Product Type:
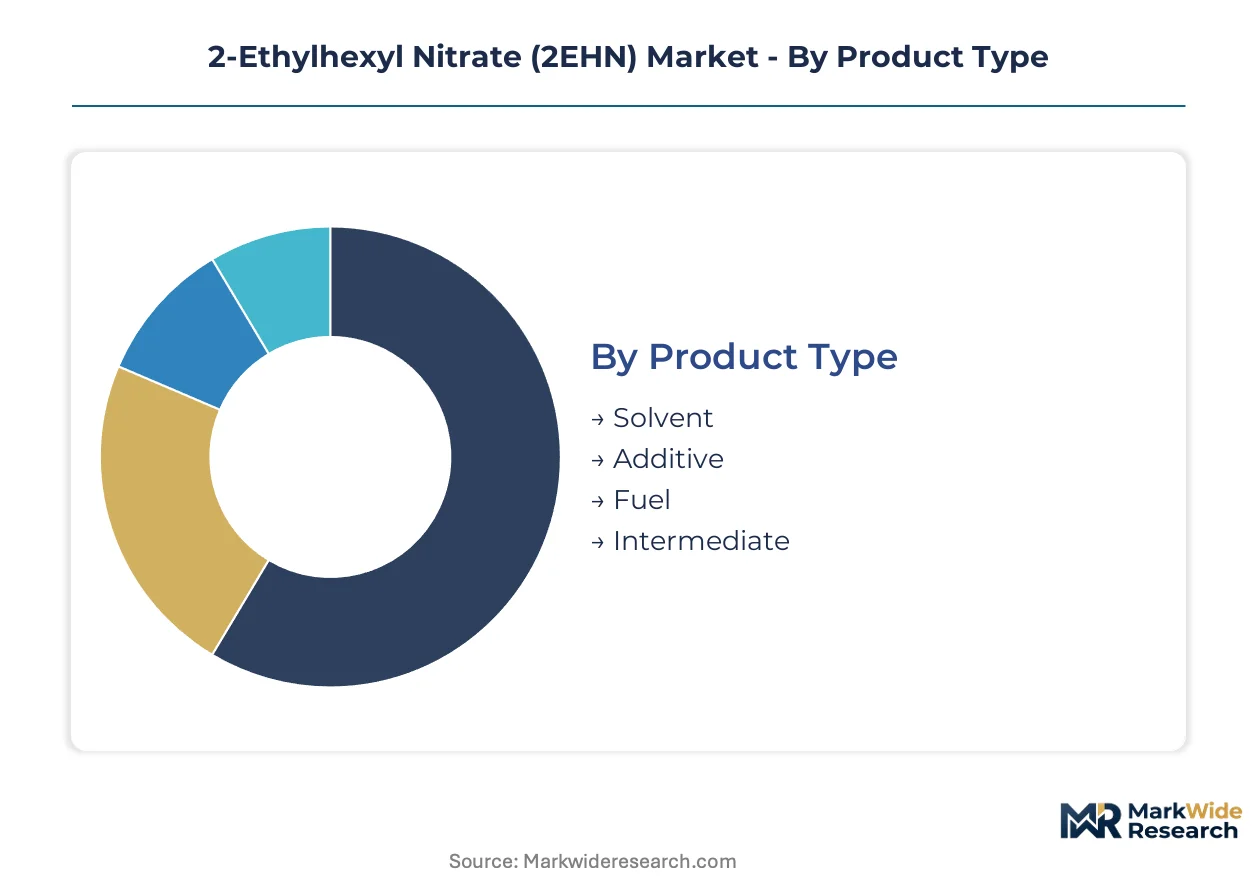
Additive and fuel grades embed directly into refinery formulation systems, whereas solvent and intermediate forms circulate through standalone chemical distribution channels with different integration economics.
- Additive:High-purity cetane improver formulations meeting NMPA, EPA 40 CFR Part 79, and REACH registration requirements command premium positioning. Refiners in Shandong province and European marine fuel blenders in Rotterdam anchor demand for certified additive grades as dual carbon protocols tighten.
- Fuel:Finished diesel fuel incorporating 2EHN as a performance component flows through integrated refinery-distribution networks. Marine diesel specifications under IMO 2020 warranty requirements concentrate uptake in Singapore and Rotterdam bunkering corridors.
- Solvent:Industrial solvent applications leverage 2EHN's nitrate ester properties for specialized extraction processes.
- Intermediate:Pharmaceutical nitrate synthesis for cardiovascular drug precursors represents an emerging vertical with distinct purity thresholds.
Volume placements concentrate in Additive; the faster expansion belongs to Intermediate.
Application:
Cost tier differentiation separates specification-heavy automotive fuel uses from process chemical applications where purity requirements moderate.
- Automotive:Diesel engine manufacturers specify cetane improver loading rates to meet emissions certification. India's BIS additive standards and China's MEE NOx reduction mandates are pulling premium-grade cargoes into domestic fuel pools.
- Pharmaceuticals:Isosorbide mononitrate and related cardiovascular drug precursors require pharmaceutical-grade 2EHN with batch documentation. European specialty chemical houses with continuous-flow nitration capabilities dominate supply for this specification tier.
- Chemicals:Process chemical applications utilize 2EHN in organic synthesis and specialty manufacturing.
- Coatings:Nitrocellulose and industrial coating formulations incorporate 2EHN for solvency and drying properties.
Automotive captures the deepest volume base; Pharmaceuticals is climbing the fastest on pricing multiples.
End User:
Customer type determines contract structure, with manufacturers locking in multi-year supply agreements while distributors manage spot inventory volatility.
- Manufacturers:Fuel additive formulators and pharmaceutical producers with captive blending operations source 2EHN through direct procurement channels. Deepak Nitrite's Dahej facility supplies regional manufacturers under long-term offtake arrangements.
- OEMs:Engine manufacturers specify additive packages for warranty compliance, creating pull-through demand for certified 2EHN grades in medium-speed marine and heavy-duty diesel applications.
- Distributors:Chemical distribution networks manage inventory for mid-size blenders without direct refinery relationships.
- Retailers:Specialty chemical retailers serve small-volume pharmaceutical and coatings customers.
Manufacturers hold the largest committed volumes; OEMs are gaining share fastest through specification lock-in.
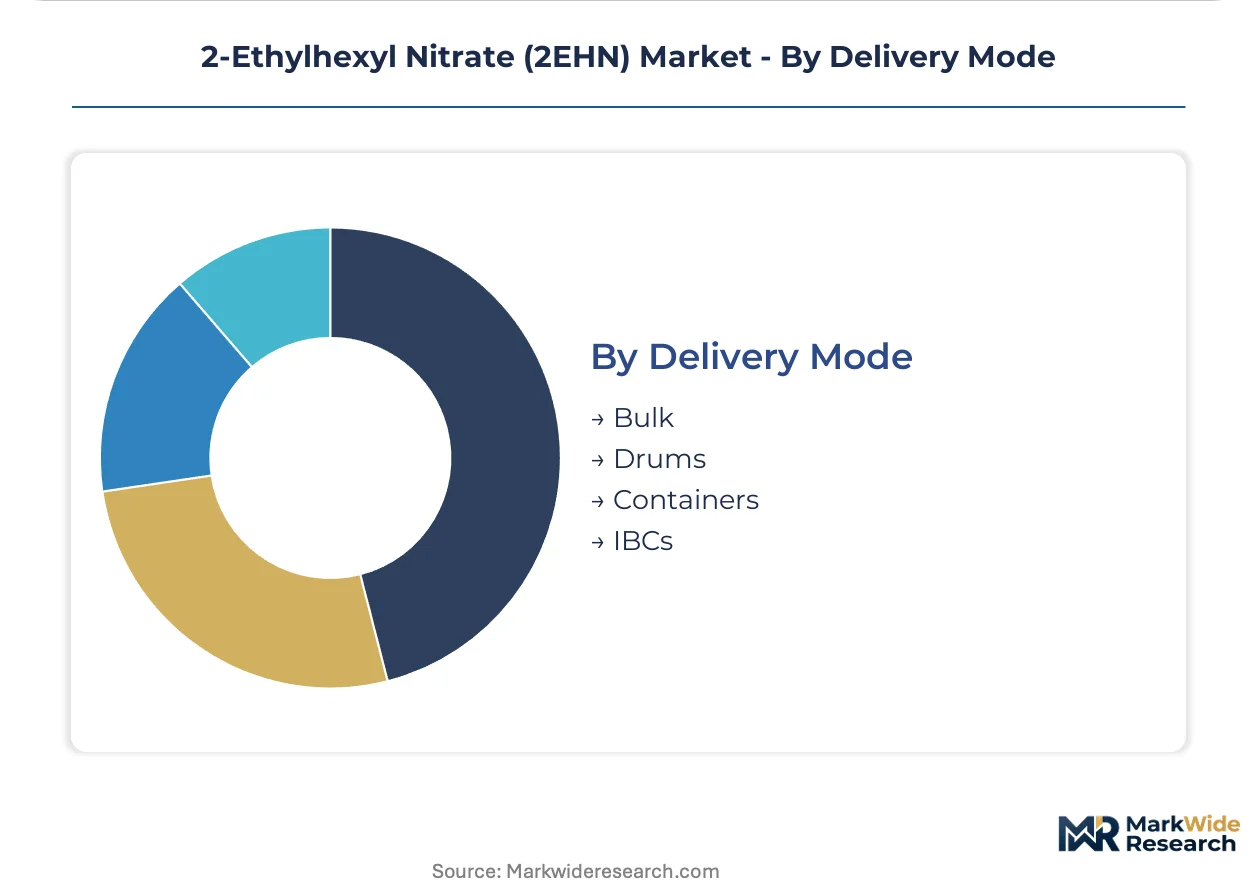
Delivery Mode:
Supply concentration in bulk infrastructure shapes regional access, while IBC flexibility enables inventory strategies for smaller blenders.
- Bulk:Tanker and railcar deliveries dominate refinery procurement with economies of scale. Singapore and Rotterdam marine fuel terminals absorb bulk cetane improver cargoes for IMO 2020 blending operations.
- IBCs:Intermediate bulk containers are gaining traction among European mid-size blenders seeking formulation flexibility without committed tankage. Polish and Spanish fleet cooperatives negotiating direct supply agreements favor IBC configurations for distributed storage.
- Drums:Standard drum packaging serves pharmaceutical and specialty chemical customers with lower volume requirements.
- Containers:ISO tank containers facilitate intermodal shipment for regional chemical distributors.
Bulk infrastructure commands the volume base; IBCs are expanding most quickly among disintermediated fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in India and China while consumption gravitates toward European marine fuel corridors and North American refining clusters. This geographic asymmetry creates arbitrage windows for bulk cargo movements and shapes regional pricing differentials.
China
Shandong and Jiangsu refiners face binding NOx reduction targets under MEE dual carbon protocols that pull high-purity additive grades into domestic fuel pools. NMPA environmental compliance protocols are tightening formulation standards for cetane improvers entering transportation fuel channels. The Yangtze River Delta hosts the densest concentration of qualified additive formulators serving both automotive OEMs and marine diesel blenders.
India
Dahej and Nandesari production facilities anchor regional supply for diesel additive formulators across South Asia. BIS certification requirements for petroleum additives are filtering import channels and elevating domestic manufacturing preference. Gujarat's chemical manufacturing corridor is absorbing capacity expansion investments to serve accelerating demand from fleet operators and refinery upgrade projects.
Germany
REACH compliance mandates for nitrate ester imports are concentrating supplier relationships around established toxicological dossiers. ECHA's updated PBT assessment criteria are forcing additional ecotoxicology testing for long-chain alkyl nitrates. The North Rhine-Westphalia refining cluster is retrofitting continuous-flow nitration capabilities to defend position against Asian volume suppliers.
United States
EPA fuel additive registration under 40 CFR Part 79 governs market access for cetane improvers entering transportation fuel pools. Gulf Coast refiners are consolidating procurement around bundled additive packages that compress standalone spot markets. The Houston Ship Channel marine terminal complex is absorbing nitrated ester cargoes for IMO 2020 residual fuel blending operations.
Singapore
IMO 2020 marine diesel specifications are driving warranty-compliant cetane improver demand from medium-speed engine manufacturers. The bunkering corridor connecting Singapore and Rotterdam is absorbing premium-grade additive packages for residual fuel blending. Jurong Island's integrated petrochemical complex is expanding storage infrastructure to handle increasing cetane improver throughput.
2-Ethylhexyl Nitrate (2EHN) Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with backward integration into alcohol feedstocks and nitrate ester synthesis capabilities. Three archetypes dominate: multinational fuel additive specialists with global registration portfolios, regional volume producers serving domestic refining corridors, and pharmaceutical-grade specialists leveraging continuous-flow reactor technology. Capacity expansion and formulation partnership lock-ins represent the dominant competitive moves as procurement consolidation elevates long-term supply agreements over spot transactions.
Among multinational specialists, Innospec Inc., Afton Chemical, and BASF SE occupy positions defined by integrated fuel additive technology platforms and specialized combustion chemistry R&D infrastructure. Deepak Nitrite Limited exemplifies the regional volume producer archetype with manufacturing scale from its Indian production base. EURENCO and VeryOne represent European specialists with capabilities spanning both fuel additive and energetic materials applications. Lubrizol and Octel America sit within the North American additive formulator tier, while JX Nippon Oil & Energy Corporation anchors Asia-Pacific refinery supply relationships.
| Leading Market Players |
|---|
| EURENCO |
| Innospec Inc. |
| Afton Chemical |
| VeryOne |
| Deepak Nitrite Limited |
| Lubrizol |
| BASF SE |
| JX Nippon Oil & Energy Corporation |
| Octel America |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap chemical producers in India's Gujarat corridor anchor supply discipline through captive nitration capacity, translating feedstock control into pricing power that resists oxo-alcohol volatility. Sovereign-backed Chinese refiners in Shandong province leverage state financing to absorb premium-grade 2EHN cargoes, compressing margin recovery for independent traders lacking long-term offtake structures.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade tiers accelerates because European specialty houses with continuous-flow nitration capabilities command batch-documentation premiums. Three-tier pricing structure across pharmaceutical-grade, refinery-certified additive, and industrial-solvent levels separates specification tiers by purity thresholds and regulatory dossier completeness. Price differentiation hinges on REACH registration status and EPA 40 CFR Part 79 compliance depth. Mid-size blenders without committed tankage exhibit acute price sensitivity, while marine fuel formulators in Singapore accept premium positioning for warranty-compliant packages.
Supply Chain Analysis
Empty IBC returns and drum refurbishment flows from European fleet cooperatives in Poland and Spain create reverse-logistics complexity for direct-supply manufacturers bypassing traditional refinery blenders. Manufacturing concentrates in India, China, and Germany, with Dahej and Nandesari facilities anchoring Asian volume and North Rhine-Westphalia housing REACH-compliant specialty production. Feedstock draws from propylene and syngas oxo-alcohol streams, with nitration reagents sourced from regional chemical distributors. Single-source vulnerability around Deepak Nitrite's turnaround seasons elevates spot cargo risk for regional formulators. Distribution runs through bulk tanker and railcar infrastructure for refineries, with IBC flexibility gaining share among disintermediated fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH dossier maintenance and EPA 40 CFR Part 79 registration erect barrier-to-entry moats favoring incumbents with sustained toxicological investment capacity.
For Market Incumbents: Deploy continuous-flow nitration retrofit programs to defend pharmaceutical-grade positioning against Asian volume suppliers. Deepen backward integration into 2-ethylhexanol production to neutralize oxo-alcohol feedstock volatility threatening margin predictability. Lock in multi-year formulation partnerships with European marine fuel blenders before di-tert-butyl peroxide substitution accelerates in non-road segments. For New Entrants and Emerging Players: Capture Vietnamese refinery upgrade demand at Nghi Son and Dung Quat by establishing local technical service infrastructure ahead of capacity ramp. Pharmaceutical nitrate intermediates for cardiovascular drug precursors offer the most penetrable vertical, with pricing multiples above fuel additive grades justifying purity investment. Lead with IBC-configured flexibility targeting Polish and Spanish fleet cooperatives negotiating direct supply agreements. For Investors and Strategic Acquirers: Distressed-cycle entries favor continuous-flow nitration specialists in Germany with verified low-carbon manufacturing footprints ahead of EU Green Deal carbon border adjustment implementation. Long-term viability over the mid-decade window rests on REACH authorization resilience and pharmaceutical-grade certification depth. Monitor ECHA reproductive toxicity endpoint updates as inflection signals for dossier maintenance burden escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Nitration Retrofit | Eliminates batch variability and enables pharmaceutical-grade purity thresholds for European specialty houses. |
| Backward Integration into 2-Ethylhexanol | Neutralizes propylene and syngas cost curve volatility compressing margin predictability for standalone producers. |
| Long-Term Supply Agreement with Marine Fuel Blenders | Secures IMO 2020 warranty-compliant positioning in Singapore and Rotterdam bunkering corridors. |
| Pharmaceutical-Grade Certification Investment | Unlocks isosorbide mononitrate precursor demand with pricing multiples above refinery additive tiers. |
| Local Technical Service Infrastructure in Vietnam | Captures first-mover positioning at Nghi Son and Dung Quat refinery upgrades ahead of regional competition. |
Research Methodology
Multi-period observation of refinery procurement consolidation patterns and bundled additive package adoption anchored the trend analysis, supplemented by interviews with plant managers at Indian nitration facilities, procurement leads at European marine fuel blenders, distribution channel partners managing IBC logistics, and technical R&D directors developing continuous-flow reactor systems. Secondary validation drew from customs and trade data tracking 2EHN cargo movements, ACC and Cefic chemical industry reports, SEC 10-K filings of listed additive specialists, and EPA fuel additive registration databases. Bottom-up volume estimates from individual production facilities triangulated against top-down demand projections from diesel engine manufacturer specifications.
Segment-weighting across the analysis window applied differential growth assumptions to pharmaceutical-grade, refinery-certified additive, and industrial-solvent tiers, with purity thresholds and regulatory dossier completeness serving as industry-specific modeling dimensions. Automotive application demand, marine diesel specification evolution under IMO 2020, and pharmaceutical nitrate intermediate expansion informed CAGRs derived from historical volume trajectories and forward-looking formulation partnership announcements. Regional production hub capacity utilization and qualified supplier pool concentration shaped geographic allocation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA PBT assessment criteria updates, MEE dual carbon protocol stringency revisions, and di-tert-butyl peroxide substitution rates in non-road diesel applications. Practitioners should monitor REACH authorization timelines and carbon border adjustment implementation signals for early indicators of compliant supplier pool contraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Global Butyric Acid Derivatives Market
Additives
Phenolic Antioxidant Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Competitive Inhibitors Market
Additives
Sodium Metabisulfite Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
North America Potassium Nitrate Market
Additives
Tartaric Acid Market
Additives
Calcium Tartrate Market
Additives
Asia-Pacific Water Enhancer Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Global Asphalt Additives Market
Additives
Chitosan Powder Market
Additives
Global Sizing Agents Market
Additives
Triazine UV Absorber Market