
 Alginic Acid Market | 2026-2036
Alginic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Alginic Acid Market Outlook
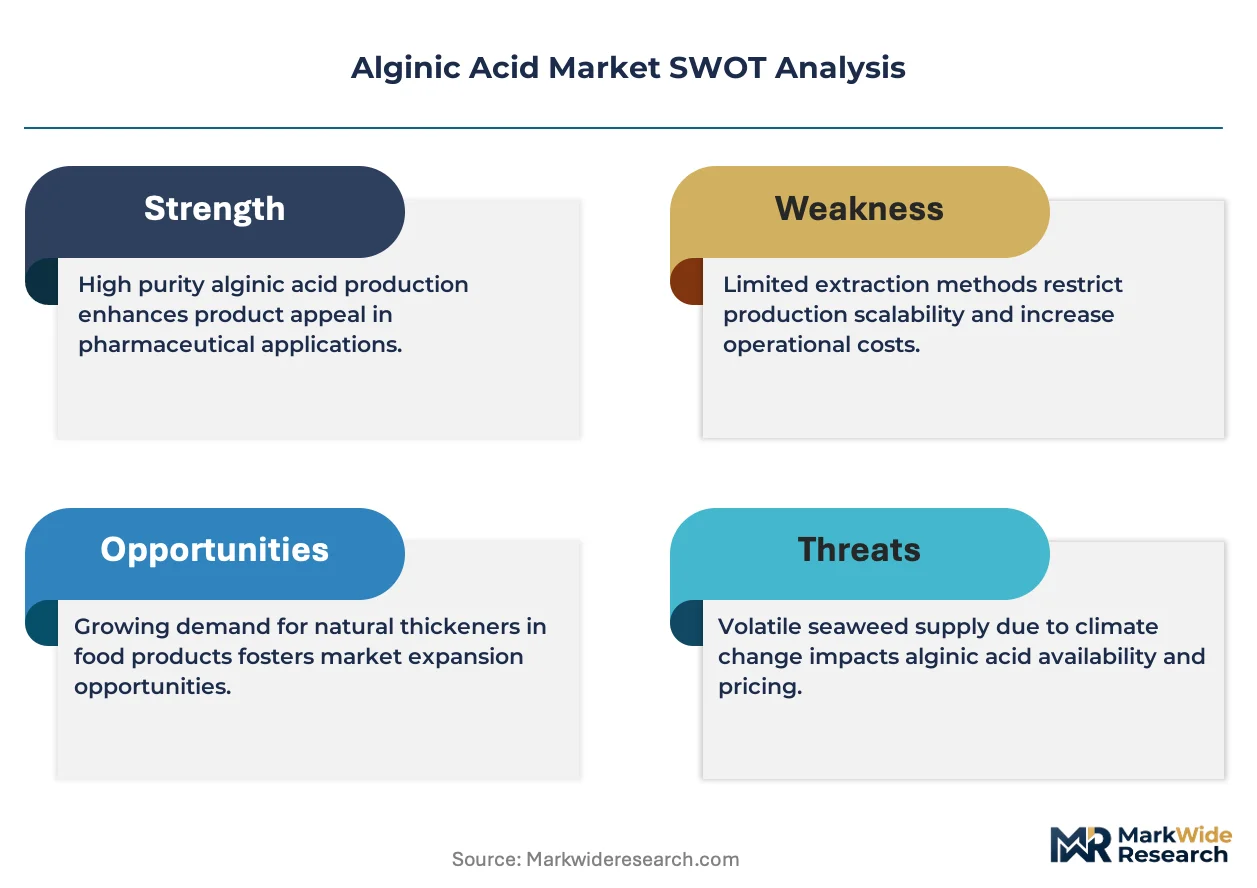
EU REACH regulation is hardening purity benchmarks for alginic acid derivatives entering food and pharmaceutical channels, compelling processors to upgrade extraction and refining protocols. Cargill Incorporated leverages its global sourcing infrastructure to secure consistent brown seaweed feedstock across multiple harvesting regions. KIMICA Corporation sustains Japanese market leadership through proprietary extraction technologies that yield high-viscosity sodium alginate grades. Shandong Jiejing Group dominates Chinese domestic supply with integrated seaweed farming and processing operations spanning Shandong Province.
Alginic acid is a linear polysaccharide composed of beta-D-mannuronic acid and alpha-L-guluronic acid residues extracted primarily from brown seaweed cell walls, with molecular weight and M/G ratio determining functional properties such as gel strength, viscosity, and ion-binding capacity. Its primary industrial purpose centers on thickening, gelling, stabilizing, and film-forming applications across food, pharmaceutical, and biomedical sectors. Sodium alginate commands the largest product type position due to its solubility and versatility in food spherification and wound dressing formulations, while calcium alginate represents the fastest-expanding category driven by hemostatic and dental impression material demand. Pharmaceutical sector applications concentrate the highest margin pools as pharmacopeial-grade material commands stringent certification and limited qualified supplier bases.
FDA food additive regulations and USP-NF monographs govern alginic acid quality for ingestible and implantable applications in the United States, while EMA and European Pharmacopoeia standards enforce comparable purity thresholds across EU member states. China's NMPA and GB standards for food-grade hydrocolloids impose additional testing protocols that filter smaller processors from pharmaceutical supply chains. Stakeholders must monitor evolving pharmacopeial harmonization initiatives and seaweed sustainability certification schemes to secure long-term supply positions.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing the qualified supplier base for alginic acid derivatives, as REACH compliance in Europe and USP-NF standards in the United States harden purity benchmarks beyond the reach of smaller seaweed processors.
Growth Catalysts
- Controlled-release drug formulations:Pharmaceutical manufacturers are substituting synthetic polymers with bio-based alginates in tablet coatings and sustained-release matrices. This substitution is widening demand for pharmacopeial-grade sodium alginate across oral dosage development pipelines.
- REACH compliance protocols:ECHA enforcement of stricter impurity limits for food-grade and pharmaceutical-grade alginates is filtering out unqualified processors. Qualified suppliers are capturing margin expansion as certification becomes a bottleneck.
- China's integrated seaweed farming:Shandong Province processors anchor regional supply chains through captive brown seaweed cultivation. This concentration secures feedstock availability for both domestic consumption and export market positioning.
Market Restraints
- Brown seaweed harvest volatility:Climate-driven fluctuations in Laminaria and Macrocystis yields create input cost instability. Processors lack effective hedging instruments against marine biomass supply shocks.
- Chinese supply concentration:Overreliance on Shandong and Fujian Province processors for refined alginate creates geographic risk exposure. Single-region dependency amplifies disruption vulnerability from environmental or policy shocks.
- Protein contamination limits:Residual seaweed protein in food-grade alginates triggers EFSA allergen labeling requirements. Purification to sub-threshold levels demands capital-intensive refining infrastructure.
Strategic Opportunities
- Biomedical scaffold applications:Tissue engineering programs are adopting calcium alginate hydrogels for cell encapsulation. This emerging application commands premium pricing outside traditional food and pharma channels.
- Indian pharmaceutical manufacturing:CDSCO alignment with ICH quality guidelines is opening pharmacopeial-grade alginate demand from Indian generic drug exporters. Local supply gaps create import substitution potential.
- Wound care channel expansion:Hospital procurement consolidation favors suppliers offering integrated hemostatic dressing portfolios. Alginate fiber producers can bypass distributor tiers through direct clinical contract structures.
Industry Challenges
- Pharmacopeial certification timelines:USP-NF and European Pharmacopoeia monograph compliance requires 18-24 month validation cycles. Start-up processors face working capital strain during qualification periods.
- Extraction technician scarcity:Proprietary alginate recovery protocols depend on experienced seaweed chemists. Workforce aging in Japanese and Norwegian processing facilities threatens knowledge transfer continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alginic Acid Market |
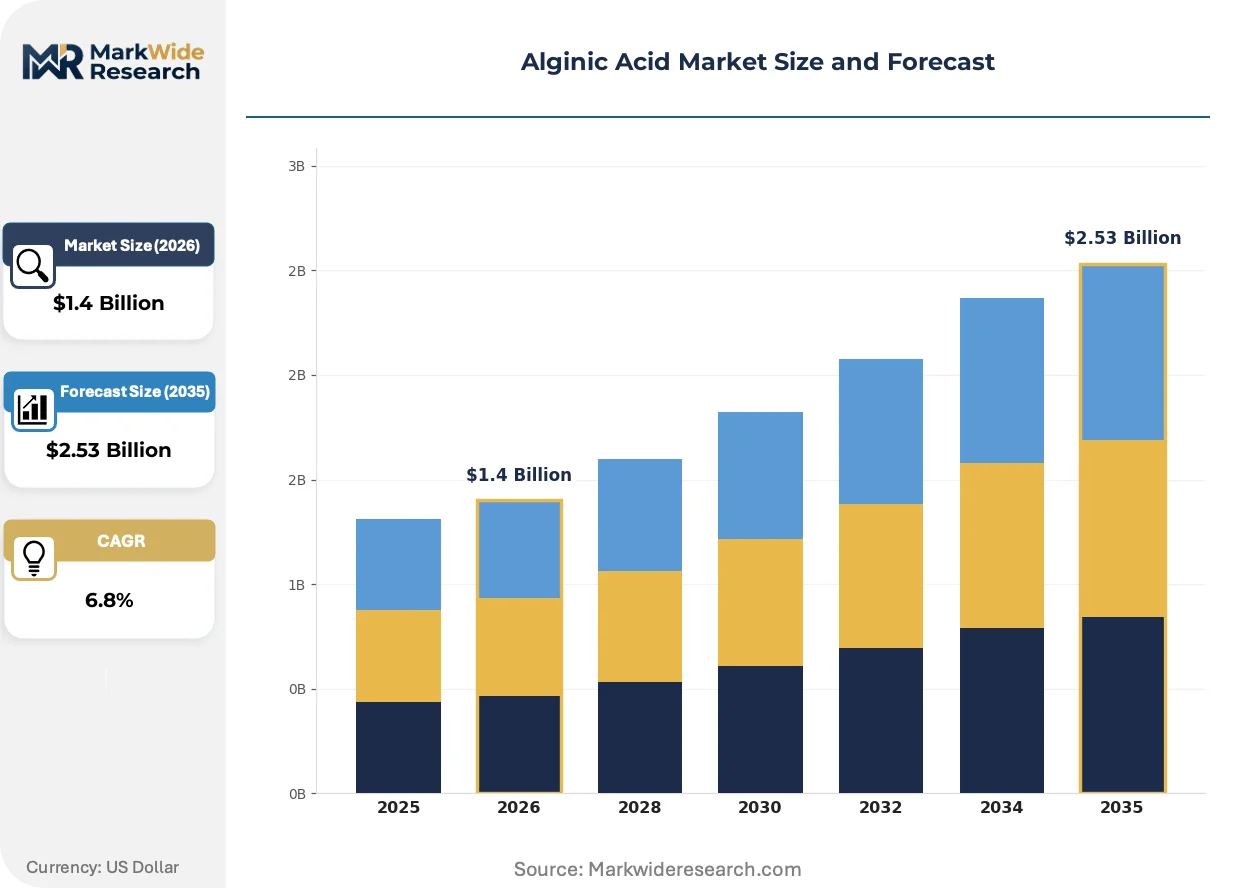
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Alginate, Calcium Alginate, Potassium Alginate, Ammonium Alginate Application: Food Industry, Pharmaceutical Sector, Cosmetics, Textile Industry Form: Powder, Granules, Liquid, Gel End User: Food Manufacturers, Healthcare Providers, Personal Care Companies, Textile Manufacturers |
| Companies Covered | BASF, DuPont, Cargill Incorporated, FMC Corporation, KIMICA Corporation, Algaia, Protan AS, Shandong Jiejing Group, CP Kelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alginic Acid Market Strategic Shifts
Enzymatic extraction methods are reshaping competitive economics in alginic acid production, while regulatory harmonization initiatives and buyer consolidation in pharmaceutical procurement are restructuring channel relationships across the value chain.
Enzymatic alginate lyase treatments are overtaking traditional alkaline extraction in high-viscosity grade production. Biopharmaceutical contract manufacturers are adopting these processes to secure tighter molecular weight distribution in excipient batches. This technology is overtaking conventional chemical extraction as the default for pharmacopeial certification pathways.
EMA and European Pharmacopoeia alignment on residual heavy metal limits is forcing processor upgrades to ion-exchange purification systems. Manufacturers serving EU markets must demonstrate batch-level compliance with stricter arsenic and lead thresholds. Sodium alginate for implantable applications faces the steepest compliance gradient, with suppliers investing in dedicated pharmaceutical-grade production lines.
Hospital group purchasing organizations are consolidating wound dressing procurement across integrated delivery networks. Alginate fiber suppliers are responding with direct contractual relationships that bundle hemostatic products with inventory management services. This consolidation is most visible in United States acute care settings, where three national GPOs control majority purchasing volume.
Alginic Acid Market Segmentation
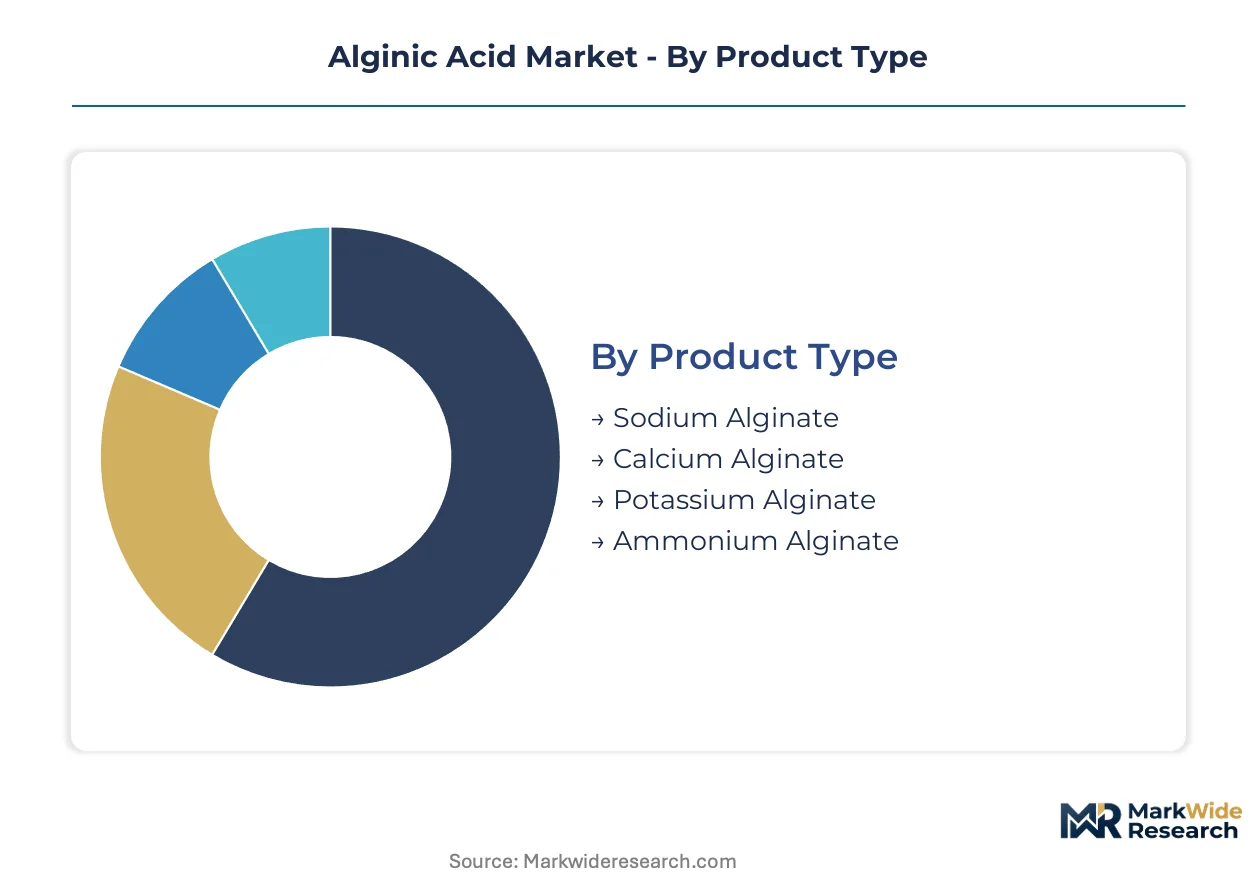
Alginic acid derivatives command divergent certification pathways across product grades, with pharmacopeial standards filtering supplier participation in high-margin pharmaceutical channels while food-grade specifications dominate volume throughput.
Product Type:
Pharmacopeial-grade sodium alginate demands USP-NF monograph compliance in the United States and European Pharmacopoeia certification for EU markets, whereas food-grade categories face EFSA purity thresholds and FDA food additive regulations with lower barrier-to-entry thresholds.
- Sodium Alginate:Water-soluble salt of alginic acid with M/G ratio determining viscosity grades from 50 to 1000 mPa·s. Pharmaceutical tablet coating applications in the United States and spherification techniques in European gastronomy concentrate demand for high-viscosity, low-protein grades.
- Calcium Alginate:Insoluble calcium salt forming ionotropic hydrogels through cross-linking with divalent cations. Hemostatic wound dressings in Japanese hospital procurement and dental impression materials in German clinical settings drive steepest expansion trajectory among all product types.
- Potassium Alginate:Potassium salt variant with enhanced solubility in cold water systems. Low-sodium food formulations in South Korean processed foods sector absorb regional production from domestic seaweed processors.
- Ammonium Alginate:Ammonium counterion variant with specialized rheological properties for textile printing pastes. Reactive dye thickening applications in Indian textile clusters around Surat and Tiruppur sustain niche demand.
Leading the category by volume: Sodium Alginate. Growing fastest: Calcium Alginate.
Application:
Margin structures diverge sharply across application channels, with pharmaceutical excipient contracts commanding three-to-five-year qualification timelines and food industry procurement operating on annual price negotiations with minimal technical barriers.
- Food Industry:Thickening, stabilizing, and gelling functions across dairy alternatives, sauces, and confectionery. European clean-label formulation trends favor E-number-free positioning for sodium alginate in plant-based meat analogues.
- Pharmaceutical Sector:Controlled-release matrix systems, tablet binders, and wound care formulations. FDA IND-enabling studies and EMA quality documentation create multi-year supplier lock-in for qualified processors.
- Cosmetics:Emulsion stabilization and film-forming properties in skincare and haircare products. Korean beauty export manufacturers specify low-odor, low-color grades for premium positioning.
- Textile Industry:Printing paste rheology modification and sizing applications. Indian and Bangladeshi textile hubs source ammonium alginate for reactive dye systems on cotton substrates.
Widest margin pool: Pharmaceutical Sector. Largest volume absorption: Food Industry.
Form:
Physical form selection determines logistics economics and handling infrastructure requirements, with powder grades enabling bulk ocean freight and gel forms demanding temperature-controlled distribution networks.
- Powder:Spray-dried particulate with standardized mesh sizes for industrial handling. Pharmaceutical excipient specifications require sub-150 micron particle distribution for uniform tablet compression.
- Granules:Agglomerated particles with reduced dusting characteristics. Food manufacturing facilities in Brazil and Mexico specify granules for automated dosing equipment compatibility.
- Liquid:Pre-hydrated solutions with preserved viscosity stability. Ready-to-use textile printing pastes in Italian and Spanish dye houses eliminate on-site dissolution steps.
- Gel:High-viscosity hydrated matrices for biomedical and wound care applications. Sterile calcium alginate gels for hospital burn units require aseptic filling capabilities and ethylene oxide sterilization validation.
Dominant logistics format: Powder. Steepest demand climb: Gel.
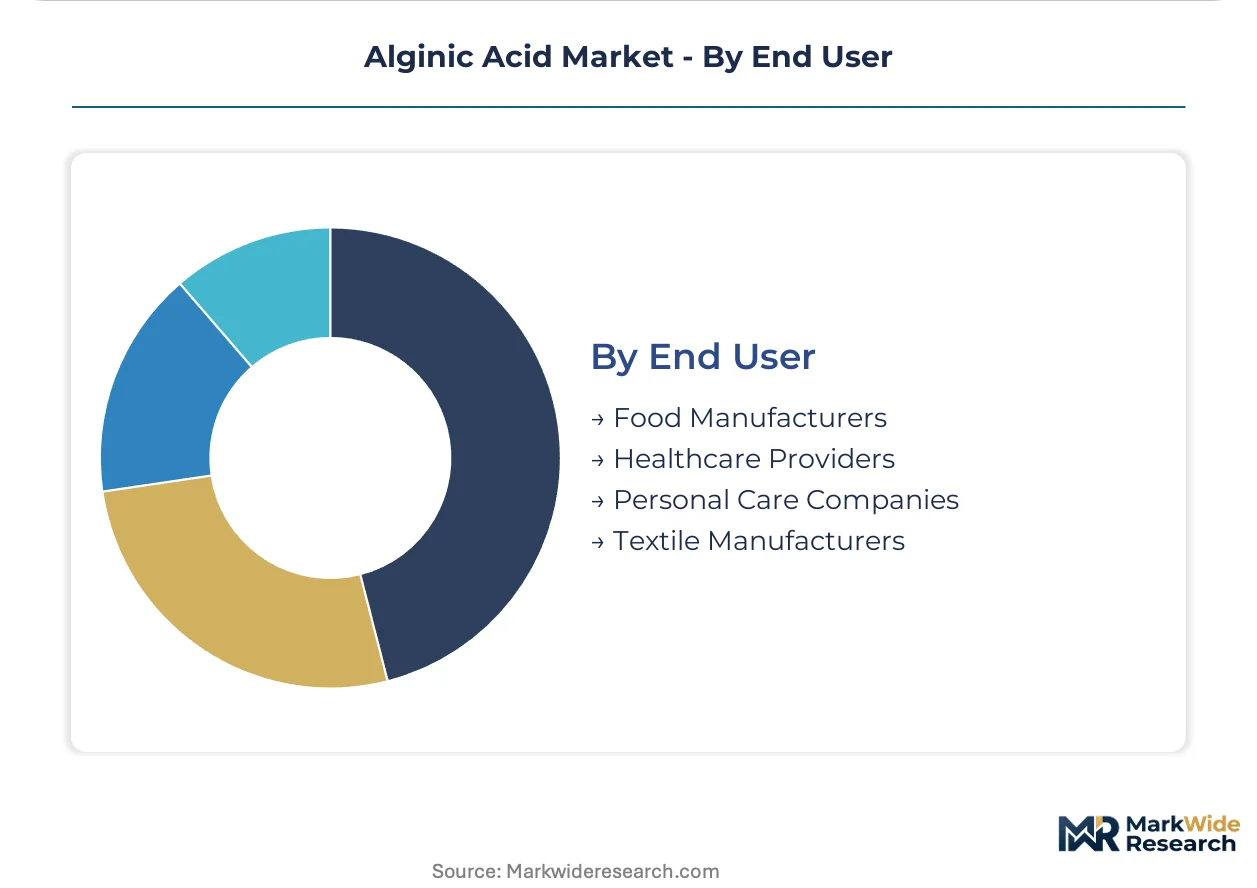
End User:
Procurement sophistication varies dramatically across end-user categories, with healthcare providers demanding batch-level Certificates of Analysis and textile manufacturers operating on commodity-grade specifications with minimal documentation.
- Food Manufacturers:Industrial-scale hydrocolloid procurement for processed foods and beverages. Japanese and Thai seafood processors utilize sodium alginate for artificial caviar and structured seafood products.
- Healthcare Providers:Hospital systems and specialty clinics sourcing hemostatic and advanced wound care materials. United States integrated delivery networks consolidate alginate dressing procurement through national GPO contracts.
- Personal Care Companies:Cosmetic formulators and contract manufacturers. French and Italian luxury skincare houses specify ultra-low ash content grades for premium serum formulations.
- Textile Manufacturers:Dye houses and printing operations across woven and knit fabric production. Turkish textile exporters around Bursa and Denizli source alginate thickeners for EU-bound finished goods.
Most stringent qualification requirements: Healthcare Providers. Highest volume throughput: Food Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qingdao anchors the global alginic acid trade through its concentration of brown seaweed processing facilities and deep-water port infrastructure serving export markets.
China
Shandong Province processors dominate global alginate supply through integrated Laminaria farming and extraction operations. NMPA pharmaceutical-grade certification requirements filter smaller competitors from high-margin medical channels. Qingdao and Weihai industrial clusters export refined sodium alginate to European and North American pharmaceutical formulators.
United States
FDA food additive regulations and USP-NF monographs govern quality standards for ingestible and implantable alginate applications. Hospital group purchasing organizations consolidate wound dressing procurement across integrated delivery networks. Boston and San Diego biomedical corridors drive demand for pharmacopeial-grade calcium alginate in tissue engineering applications.
Japan
PMDA enforcement of pharmaceutical excipient standards sustains premium pricing for high-viscosity sodium alginate grades. METI industrial policy supports domestic seaweed processing automation to offset labor cost pressures. Tokyo-Osaka pharmaceutical manufacturing belt sources certified alginates for controlled-release tablet formulations.
Germany
EMA and European Pharmacopoeia alignment on residual heavy metal limits compel processor upgrades to ion-exchange purification systems. REACH compliance protocols harden purity benchmarks beyond the reach of unqualified suppliers. Hamburg and Bremen port facilities handle bulk alginate imports for redistribution to EU pharmaceutical manufacturers.
India
CDSCO alignment with ICH quality guidelines opens pharmacopeial-grade alginate demand from generic drug exporters. FSSAI food safety standards govern hydrocolloid imports for processed food manufacturing. Mumbai and Hyderabad pharmaceutical clusters create import substitution opportunities for certified sodium alginate suppliers.
Alginic Acid Market Competitive Environment
The competitive structure tilts toward integrated seaweed processors with captive feedstock supply. Market participation concentrates among three tiers: multinational ingredient conglomerates with diversified hydrocolloid portfolios, regional specialists with proprietary extraction technologies, and vertically integrated Asian processors controlling farming-to-refining value chains. Capacity expansion and pharmacopeial certification acquisition represent the dominant competitive moves as qualification becomes the primary bottleneck.
Among multinational ingredient suppliers, Cargill Incorporated and BASF occupy positions spanning multiple hydrocolloid categories and geographic markets. Within the Asia-Pacific specialist tier, KIMICA Corporation and Shandong Jiejing Group exemplify contrasting models—Japanese proprietary extraction expertise versus Chinese integrated farming scale. These named entities anchor the competitive map without exhausting the qualified supplier base, which remains compressed by certification timelines and capital requirements.
| Leading Market Players |
|---|
| BASF |
| DuPont |
| Cargill Incorporated |
| FMC Corporation |
| KIMICA Corporation |
| Algaia |
| Protan AS |
| Shandong Jiejing Group |
| CP Kelco |
| Others |
Value Chain & Pricing Dynamics
Brown seaweed feedstock costs cascade through three distinct pricing tiers as Laminaria and Macrocystis harvest volatility in Chinese and Chilean waters compresses margins at the refining stage. Processors with captive cultivation operations in Shandong Province command premium realization for pharmacopeial-grade sodium alginate, while spot-market dependent competitors face cost compression in food-grade categories.
Pricing Analysis
Yield-linked pricing for high-viscosity sodium alginate grades anchors value capture in pharmaceutical excipient contracts, with USP-NF and European Pharmacopoeia certification thresholds creating 40-60% spreads over food-grade equivalents. Price differentiation rests on protein contamination limits and heavy metal thresholds rather than volume scale. Pricing pressure stems from REACH compliance upgrade costs filtering smaller processors from qualified supplier pools. Food manufacturers exhibit highest price sensitivity, while biomedical scaffold developers accept premium positioning for batch-level Certificates of Analysis.
Supply Chain Analysis
Seaweed biomass returns from pharmaceutical-grade refining lines feed lower-tier food and textile channels, maximizing extraction yield economics across the value chain. Supply concentrates in China, Norway, and Japan, with Shandong Province processors controlling 60-70% of refined alginate output. Raw material dependencies center on Laminaria japonica cultivation, Macrocystis pyrifera wild harvests, and enzymatic extraction reagents. Single-source vulnerability concentrates in Qingdao port logistics for EU-bound pharmaceutical shipments. Distribution runs through integrated processor-direct contracts for pharmacopeial grades and regional distributor networks for commodity food-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a certification-driven consolidation play. EMA and FDA pharmacopeial hardening is systematically eliminating sub-scale processors lacking ion-exchange purification infrastructure.
For Market Incumbents: Deploy pharmacopeial-grade capacity expansion in India to intercept CDSCO-aligned demand from generic drug exporters. KIMICA Corporation's proprietary extraction expertise and Cargill's multi-region feedstock sourcing demonstrate how backward integration into captive seaweed farming neutralizes harvest volatility threats. Lock in five-year qualification timelines with Boston and San Diego biomedical corridors before Indian domestic supply matures.
For New Entrants and Emerging Players: Launch via enzymatic extraction technology licensing to bypass 18-24 month USP-NF validation cycles. White-space targets concentrate in Indian pharmaceutical manufacturing and tissue engineering scaffold applications, where qualified supplier scarcity overrides price sensitivity. The most penetrable entry vector is calcium alginate hydrogel supply for cell encapsulation protocols outside traditional food and pharma procurement channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Chinese processors with NMPA certification but lacking REACH upgrade capital in Shandong and Fujian Provinces. Long-term viability hinges on pharmacopeial-grade conversion capability across the 5-10 year regulatory harmonization window. Monitor EMA-European Pharmacopoeia alignment on residual heavy metal limits as the inflection signal for mandatory ion-exchange infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Certification Acquisition | USP-NF and European Pharmacopoeia compliance locks in multi-year supplier relationships with pharmaceutical formulators. |
| Backward Integration into Seaweed Farming | Shandong Province captive cultivation secures feedstock availability against climate-driven Laminaria yield fluctuations. |
| Enzymatic Extraction Technology Deployment | Alginate lyase treatments tighten molecular weight distribution for biopharmaceutical excipient specifications. |
| Indian Market Entry via CDSCO Alignment | Mumbai and Hyderabad pharmaceutical clusters create import substitution demand as ICH quality guidelines converge. |
| Direct Hospital GPO Contracting | United States integrated delivery networks consolidate alginate dressing procurement through three national purchasing organizations. |
Study Parameters
Trade databases, pharmacopeial monograph repositories, and brown seaweed harvest statistics formed the secondary backbone for this analysis. Primary interviews with pharmaceutical excipient procurement managers, seaweed processing plant engineers, and hospital GPO contracts administrators validated extraction cost structures and qualification timeline assumptions. Bottom-up triangulation across sodium alginate viscosity grades, calcium alginate wound care applications, and regional regulatory clusters reconciled with top-down macroeconomic indicators.
Bottom-up modeling of molecular weight distribution requirements, M/G ratio specifications, and end-use industry absorption rates anchored the analytical framework across the projection horizon. Segmentation dimensions included product type, application channel, physical form, and end-user procurement sophistication. CAGRs were derived from pharmaceutical pipeline analysis, food formulation substitution trends, and biomedical scaffold adoption curves rather than extrapolated historical growth.
The model assumes a particular technology adoption path; alternative pathways for enzymatic extraction versus alkaline processing would alter the outlook for high-viscosity grade supply economics. Forecasts reflect assumptions on EMA-FDA regulatory convergence timelines and Chinese environmental enforcement intensity. Practitioners should monitor CDSCO inspection readiness among Indian pharmaceutical manufacturers and ECHA REACH enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tocopheryl Acetate Market
Additives
Chelating Agents Market
Additives
Polyols and Sorbitols Products Market
Additives
Organic Dispersants Market
Additives
Europe Anti-Caking Market
Additives
Global Sodium Acetate Market
Additives
Plastics Modifiers Market
Additives
Chelated Selenium Market
Additives
Feed Additives Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Sodium Stearyl Fumarate Market
Additives
Canada Water Enhancer Market
Additives
Metallic Stearate Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Sorbitan Tristearate Market
Additives
Gelatin Peptones Market