
 Metal Modifiers Market | 2026-2036
Metal Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Modifiers Market Outlook
Specialized metallurgical engineering talent is bifurcating the competitive landscape, with Western universities producing fewer pyrometallurgy graduates while Asian technical institutes expand alloy-focused curricula. BASF SE leverages captive research infrastructure across Ludwigshafen to sustain formulation leadership in high-temperature coatings. Evonik Industries AG anchors its position through backward integration into rare earth precursor supply. Lubrizol Corporation differentiates via friction-modifier expertise ported from lubricants into metal surface treatments.
Metal modifiers encompass chemical agents and physical treatments that alter grain structure, surface hardness, corrosion resistance, or thermal properties of base metals, typically applied through vapor deposition, thermal spraying, or melt incorporation at 0.01–5.0 weight percent loadings to achieve specified ASTM or DIN mechanical performance thresholds. The primary commercial purpose centers on extending component service life in stress-intensive environments while reducing material intensity. Alloying agents command the deepest margin pools due to aerospace-grade certification barriers and long qualification cycles. Additives represent the fastest-expanding category as automotive lightweighting programs substitute modified aluminum for conventional steel stampings. Coatings remain mature across marine and infrastructure applications, with titanium substrates attracting disproportionate R&D allocation for medical implant compatibility.
EPA toxicity thresholds under the Toxic Substances Control Act and REACH authorization requirements through ECHA constrain cadmium and hexavalent chromium formulations, redirecting formulation investment toward boron nitride and rare earth alternatives. China's MIIT enforces GB standards on tungsten and molybdenum discharge rates from modifier production facilities, elevating compliance costs for export-oriented suppliers. Stakeholders must monitor regulatory divergence between EU hazard-classification expansions and US OSHA permissible exposure limit revisions when siting new production capacity or qualifying reformulated product lines.
Market Dynamics
REACH authorization requirements through ECHA and EPA toxicity thresholds under the Toxic Substances Control Act are forcing wholesale reformulation of cadmium and hexavalent chromium chemistries, redirecting R&D investment toward boron nitride and rare earth alternatives while extending qualification timelines for aerospace-grade modifiers.
Growth Catalysts
- Aerospace OEM procurement:Next-generation airframe programs in the US and Germany are expanding titanium-modified alloy specifications, locking in multi-year supply agreements with qualified modifier suppliers.
- REACH compliance deadlines:ECHA authorization timelines for legacy chemistries are accelerating substitution demand for compliant rare earth and boron-based formulations across European coating applications.
- Automotive lightweighting mandates:Modified aluminum stampings are displacing conventional steel in passenger vehicle platforms, driven by NHTSA fuel economy standards and OEM mass-reduction targets.
Market Restraints
- Rare earth supply concentration:Chinese dominance in neodymium and dysprosium refining creates input cost volatility and geopolitical exposure for Western formulators dependent on Jiangsu province supply chains.
- Pyrometallurgy talent scarcity:Western universities are producing fewer specialized alloy engineers, constraining R&D throughput and extending development cycles for high-temperature coating innovations.
- Long qualification protocols:ASTM and DIN certification requirements for aerospace-grade modifiers impose 18-36 month validation periods, freezing out new entrants and limiting competitive dynamism.
Strategic Opportunities
- Medical implant surface engineering:Titanium substrate compatibility requirements for orthopedic and dental implants are opening premium coating segments with margin structures exceeding industrial applications.
- MIIT environmental enforcement:China's GB standards on tungsten and molybdenum discharge rates are elevating compliance costs for domestic suppliers, creating acquisition opportunities for Western producers with cleaner process technologies.
- Additive manufacturing integration:Powder bed fusion and directed energy deposition processes are converging with in-situ modifier delivery systems, enabling grain structure control unattainable through conventional melt incorporation.
Industry Challenges
- Cross-regulatory divergence:EU hazard-classification expansions and OSHA permissible exposure limit revisions are moving on asynchronous timelines, complicating unified product portfolio strategies for multinational suppliers.
- Backward integration execution:Captive rare earth precursor production requires metallurgical expertise distinct from formulation chemistry, straining organizational capabilities at mid-cap specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Modifiers Market |
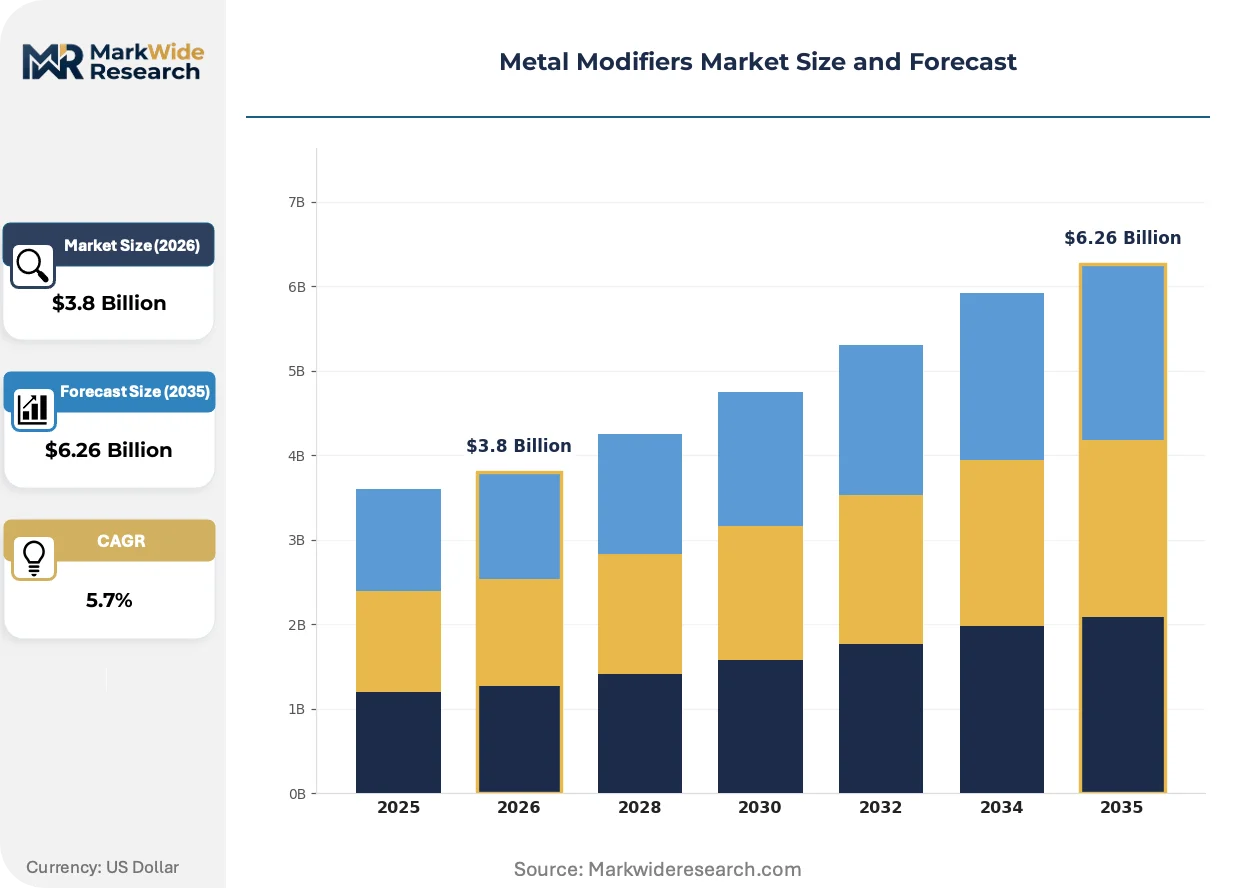
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloying Agents, Coatings, Additives, Catalysts Application: Aerospace, Automotive, Construction, Electronics Material: Aluminum, Copper, Steel, Titanium End User: Manufacturers, Suppliers, Contractors, Research Institutions |
| Companies Covered | BASF SE, Evonik Industries AG, Lubrizol Corporation, Solvay SA, The Dow Chemical Company, Clariant AG, AkzoNobel N.V., Arkema SA, Infineum International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Modifiers Market Strategic Shifts
Boron nitride-based thermal barrier formulations are supplanting legacy chemistries across multiple end-use verticals, while regulatory frameworks on both sides of the Atlantic harden permissible additive boundaries. Procurement patterns are compressing as OEMs consolidate qualified supplier lists.
Advanced boron nitride ceramic coatings are supplanting yttria-stabilized zirconia in gas turbine hot-section applications. Siemens Energy and GE Aerospace are accelerating adoption for next-generation blade platforms. This material transition is supplanting established supply relationships and forcing coating houses to rebuild thermal spray qualification portfolios from substrate preparation through post-coat inspection protocols.
REACH authorization requirements for chromium trioxide and cadmium compounds are tightening formulation freedom for European coating producers. The industrial consequence is a bifurcation between grandfathered legacy chemistries and newly qualified rare earth alternatives. Marine and infrastructure segments are most affected, with Dutch and German applicators accelerating workforce retraining for boron nitride spray application techniques ahead of 2027 sunset dates.
Consolidated procurement is compressing qualified supplier lists at tier-one aerospace and automotive OEMs. Long-tail coating houses and regional distributors are losing shelf position to formulators with captive analytical laboratories and in-house ASTM testing capabilities. This concentration is most visible in Germany's Ruhr industrial cluster, where BASF and Evonik are absorbing specification-setting roles previously held by fragmented specialty chemical distributors.
Metal Modifiers Market Segmentation
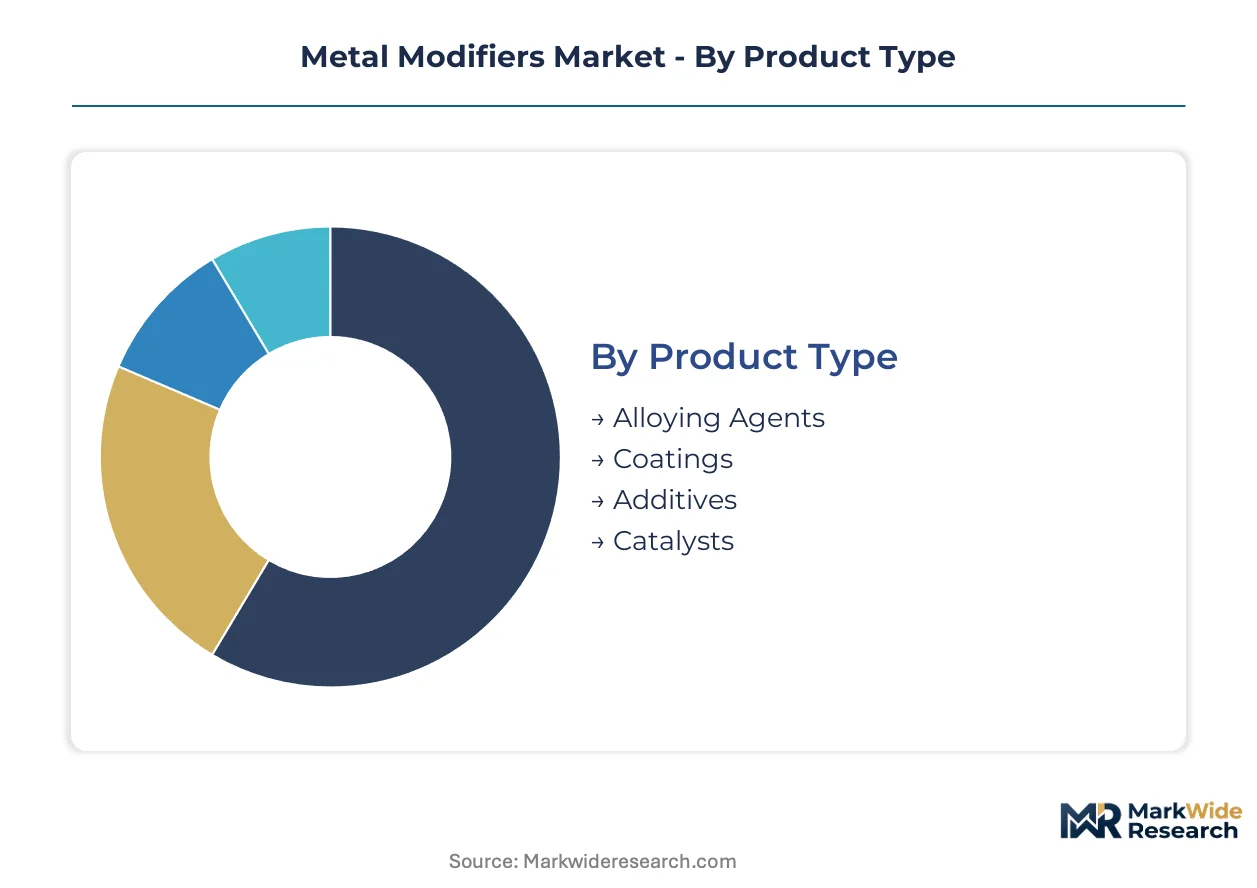
Metal modifier procurement patterns diverge sharply across product chemistry and end-use certification requirements. ASTM and DIN qualification protocols create tiered market access that fragments supplier competitive positioning.
Product Type:
REACH authorization timelines and EPA Toxic Substances Control Act thresholds are bifurcating formulation strategies between legacy chemistries and compliant alternatives.
- Alloying Agents:Melt-incorporated elements at 0.01–5.0 weight percent loadings that alter grain structure and mechanical thresholds. Aerospace OEMs in Germany and the US are locking in multi-year supply agreements for titanium-modified specifications, with certification barriers freezing out unqualified competitors.
- Additives:Chemical agents introduced during casting or forming operations to enhance corrosion resistance or thermal properties. Automotive lightweighting programs across Michigan and Stuttgart are substituting modified aluminum for conventional steel stampings, climbing the fastest as fuel economy mandates harden.
- Coatings:Surface-applied layers via vapor deposition or thermal spraying for hardness and oxidation protection. Marine infrastructure in Rotterdam and Hamburg drives mature demand.
- Catalysts:Reaction-accelerating compounds for metallurgical processing efficiency. Process optimization in Jiangsu province facilities concentrates procurement.
Established volume favors alloying agents; emerging adoption favors additives.
Application:
End-use qualification intensity separates premium-grade from industrial-grade modifier demand.
- Aerospace:Airframe and engine component specifications requiring 18-36 month ASTM validation cycles. Boeing and Airbus supply chains in Seattle and Toulouse anchor procurement concentration.
- Automotive:Passenger vehicle platforms demanding mass-reduction compliance with NHTSA standards. OEM stamping operations in Wolfsburg and Detroit are expanding modified aluminum specifications.
- Construction:Infrastructure reinforcement and corrosion protection for steel frameworks. Dutch marine applicators are retraining workforces for boron nitride spray techniques ahead of regulatory sunset dates.
- Electronics:Thermal management and conductivity modification for semiconductor packaging. Precision requirements in Hsinchu and Dresden fabs drive specification tightness.
Certification burden favors aerospace; volume scale favors automotive.
Material:
Substrate compatibility requirements dictate modifier formulation chemistry and application methodology.
- Titanium:Biocompatible substrates for orthopedic and dental implants with premium margin structures. Medical device manufacturers in Warsaw and Minneapolis are qualifying surface engineering specifications.
- Aluminum:Lightweight stampings displacing steel across passenger vehicle platforms. German Ruhr cluster formulators are absorbing specification-setting roles from fragmented distributors.
- Steel:Mature infrastructure and marine applications with established coating protocols. Rotterdam port maintenance contracts sustain baseline demand.
- Copper:Electrical conductivity and thermal management applications in power transmission and electronics. Grid infrastructure investments in Texas and Bavaria drive procurement.
Medical premium favors titanium; industrial volume favors aluminum.
End User:
Technical capability and in-house testing infrastructure separate qualified buyers from price-sensitive procurement.
- Manufacturers:Tier-one OEMs with captive analytical laboratories consolidating qualified supplier lists. BASF and Evonik are displacing regional distributors in specification-setting roles.
- Suppliers:Mid-stream formulators requiring backward integration into rare earth precursor supply. Jiangsu province refining concentration creates input cost exposure.
- Contractors:Field application services for marine and infrastructure coatings. Dutch and German applicators face workforce retraining imperatives.
- Research Institutions:Alloy development and qualification testing for next-generation formulations. Western university pyrometallurgy programs are constraining R&D throughput.
Procurement concentration favors manufacturers; capability scarcity favors research institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT enforcement of GB discharge standards in Jiangsu province anchors the dominant geography, while ECHA authorization timelines and EPA Toxic Substances Control Act thresholds reshape formulation strategies across Western supply chains.
China
Jiangsu province concentrates rare earth refining capacity for neodymium and dysprosium precursors. MIIT enforces GB standards on tungsten and molybdenum discharge rates from modifier production facilities. Suzhou and Nanjing industrial parks host formulators facing elevated compliance costs that favor acquisition by Western producers with cleaner process technologies.
Germany
The Ruhr industrial cluster absorbs specification-setting roles from fragmented specialty chemical distributors. ECHA authorization requirements for chromium trioxide and cadmium compounds accelerate substitution demand for boron nitride formulations. Ludwigshafen and Essen anchor BASF and Evonik captive research infrastructure for high-temperature coating innovations.
United States
Seattle and Detroit aerospace OEMs lock in multi-year supply agreements for titanium-modified alloy specifications. EPA toxicity thresholds under the Toxic Substances Control Act constrain cadmium and hexavalent chromium chemistries. Michigan stamping operations expand modified aluminum procurement for NHTSA fuel economy compliance.
Netherlands
Rotterdam port maintenance contracts sustain mature marine coating demand. ECHA REACH authorization timelines force workforce retraining for boron nitride spray application techniques. Dutch applicators face 2027 sunset dates for legacy chromium formulations across infrastructure reinforcement segments.
Japan
Tokyo and Osaka medical device manufacturers qualify titanium substrate surface engineering for orthopedic and dental implants. METI standards govern rare earth import dependency for modifier precursor supply. Precision coating houses in the Chubu region rebuild thermal spray qualification portfolios for next-generation blade platforms.
Metal Modifiers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with formulation specialists commanding premium margins through aerospace-grade certification barriers while commodity-scale producers compete on volume throughput. The vendor base consolidates around three strategic archetypes: integrated chemical conglomerates with captive research infrastructure, mid-cap specialists executing backward integration into rare earth supply, and regional coating houses with fragmented specification-setting influence. Dominant competitive moves include M&A absorption of qualified suppliers by tier-one OEMs and capacity expansion into medical implant surface engineering segments.
Among German-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype with captive infrastructure across Ludwigshafen. Lubrizol Corporation represents the specialist tier, occupying a position derived from friction-modifier expertise ported from adjacent lubricant applications. These three anchors illustrate how formulation leadership, upstream precursor control, and cross-domain technology transfer define competitive positioning in this market.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Lubrizol Corporation |
| Solvay SA |
| The Dow Chemical Company |
| Clariant AG |
| AkzoNobel N.V. |
| Arkema SA |
| Infineum International Limited |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-thirty-six-month ASTM qualification cycles concentrate pricing power with incumbent formulators possessing captive testing infrastructure, while Jiangsu province rare earth refining dominance anchors input cost volatility that propagates through alloy modifier quotations.
Pricing Analysis
Price spreads between German Ruhr cluster formulators and Chinese Jiangsu province suppliers reflect certification-grade differentiation rather than commodity arbitrage. Three-tier pricing structure across aerospace-grade, automotive-grade, and industrial-grade certification levels segments buyer access, with NHTSA-compliant automotive stampings commanding mid-tier positioning. Cost compression in industrial-grade coatings is intensifying because REACH sunset dates for hexavalent chromium formulations force rapid process retooling. Tier-one aerospace OEMs with locked multi-year offtake agreements exhibit lowest price sensitivity; fragmented marine applicators in Rotterdam and Hamburg face acute margin pressure.
Supply Chain Analysis
China and Germany anchor rare earth precursor and high-temperature coating formulation respectively, with the United States concentrating titanium-modified alloy specification-setting. Neodymium and dysprosium oxides, boron nitride ceramic precursors, and tungsten-molybdenum discharge treatment chemicals constitute critical input dependencies. Single-source vulnerability concentrates in Jiangsu province neodymium refining, exposing Western formulators to MIIT environmental enforcement disruptions. Distribution runs through qualified supplier lists at tier-one OEMs, with BASF and Evonik absorbing specification-setting roles from fragmented regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical implant surface engineering represents early-cycle expansion potential as orthopedic and dental manufacturers in Warsaw and Minneapolis accelerate titanium substrate qualification programs.
For Market Incumbents: Consolidate specification-setting authority by absorbing qualified regional distributors in Germany's Ruhr cluster, where REACH compliance deadlines are eliminating fragmented coating houses lacking captive ASTM testing capabilities. Backward integration into rare earth precursor supply—exemplified by Evonik's Jiangsu province positioning—defends margin structures against Chinese refining concentration. Priority lever rests on medical implant coating certification investment ahead of competitor qualification cycles. For New Entrants and Emerging Players: Fast-tracked aerospace-grade ASTM certification for boron nitride thermal barrier formulations unlocks white-space opportunity as Siemens Energy and GE Aerospace rebuild supplier portfolios for next-generation blade platforms. Target Dutch and German marine applicators facing 2027 REACH sunset workforce retraining imperatives for spray application technique transitions. Go-to-market angle emphasizes cleaner process technologies that satisfy MIIT GB discharge standards for acquisition by Western producers seeking Jiangsu province footholds. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because regulatory qualification barriers and pyrometallurgy talent scarcity constrain competitive entry across the projection horizon. Acquisition target archetype: mid-cap formulators with captive rare earth precursor relationships and in-process aerospace certification pipelines. Signal to watch is ECHA authorization timeline acceleration for remaining chromium trioxide applications, which would compress substitution demand into narrower supplier windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Precursors | Evonik's Jiangsu positioning demonstrates upstream control defending against Chinese refining volatility. |
| Medical Implant Surface Engineering Certification | Warsaw and Minneapolis orthopedic manufacturers are qualifying titanium substrate specifications with premium margin structures. |
| Boron Nitride Thermal Spray Qualification | Siemens Energy and GE Aerospace adoption for blade platforms forces coating houses to rebuild portfolios. |
| Acquisition of REACH-Compliant Regional Formulators | BASF and Evonik absorption of Ruhr cluster distributors eliminates fragmented specification-setting competition. |
| Clean Process Technology Deployment | Western producers with MIIT GB-compliant operations gain acquisition leverage over Jiangsu province suppliers facing elevated compliance costs. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with pyrometallurgy R&D directors, aerospace OEM procurement leads, marine coating applicators, and rare earth supply chain managers; and secondary validation through ECHA authorization databases, EPA TSCA filing records, MIIT GB standard disclosures, and ACC trade flow data. Bottom-up alloy modifier volume estimates triangulated against top-down aerospace and automotive production forecasts across the analysis window.
Across the modeling period, projections segmented by product chemistry, end-use certification intensity, substrate material compatibility, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating NHTSA fuel economy mandate compliance schedules and REACH authorization sunset timelines. Industry-specific inputs included titanium-modified alloy specification adoption rates at Boeing and Airbus supply chains, and modified aluminum stamping penetration across Wolfsburg and Detroit OEM platforms.
Decision-makers should treat outputs as directional under sustained aerospace OEM procurement expansion and REACH substitution demand assumptions; material deviation in rare earth supply concentration or pyrometallurgy graduate pipeline constraints would warrant model refresh. Recalibration cycles align with material shifts in ECHA authorization timelines and MIIT environmental enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Silica-Based Matting Agents Market
Additives
Choline Chloride Market
Additives
Apocarotenal Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Agrochemicals Additives Market
Additives
Competitive Inhibitors Market
Additives
Global Rheology Modifiers Market
Additives
Sodium Diacetate Market
Additives
North America Citric Acid Market
Additives
Texture Modifier Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Asia Pacific Plastic Additives Market
Additives
Anti-Settling Agents Market
Additives
High Performing Matting Agents Market
Additives
Hexyl Acetate Market
Additives
Lubricant Additives Market