
 Chitosan Powder Market | 2026-2036
Chitosan Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Chitosan Powder Market Analysis
Multi-source chitin procurement from crustacean waste streams is pivoting toward vertically integrated coastal operations. Primex EHF leverages its Icelandic cold-water shrimp processing partnerships to secure consistent raw material access. Heppe Medical Chitosan GmbH sustains pharmaceutical-grade certification dominance through ISO 13485-aligned production in Germany. Kitozyme S.A. anchors European food-grade supply with enzymatic deacetylation technology that reduces alkali waste.
Chitosan powder comprises partially deacetylated chitin polysaccharide, typically achieving 70-95% deacetylation degree and molecular weights spanning 50 to 2,000 kDa depending on hydrolysis conditions. Manufacturers extract the biopolymer through alkaline deproteination and demineralization of crustacean shells, yielding a cationic polymer functional for flocculation, film formation, and controlled release matrices. Deacetylated chitosan generates the largest revenue pool due to established water treatment and biomedical demand, while chitosan oligosaccharides command premium positioning in functional food and cosmeceutical formulations where lower molecular weight enables enhanced bioavailability. Chitosan nanoparticles represent the fastest-expanding product category as nanoscale drug delivery systems gain traction in oncology and vaccine adjuvant applications.
EMA medical device regulations and EU REACH chemical registration requirements shape pharmaceutical-grade chitosan certification pathways and import compliance costs. FDA GRAS notifications and EPA National Primary Drinking Water Regulations influence food additive approvals and municipal flocculation procurement standards in the United States. Japan's PMDA pharmaceutical standards and METI biomanufacturing initiatives create a dual framework that rewards high-purity chitosan for regenerative medicine while supporting domestic supply chain resilience. Stakeholders must monitor evolving biodegradability certification schemes and marine resource traceability requirements as sustainability claims become enforceable market access conditions.
Market Dynamics
Pharmaceutical-grade chitosan certification requirements are concentrating procurement power among vertically integrated coastal processors with captive crustacean waste supply chains. Cold-water shrimp processors in Iceland and North Atlantic crab fisheries are securing decade-long raw material contracts with biomedical manufacturers seeking EMA-aligned traceability documentation.
Growth Catalysts
- EU Green Deal substitution mandates:REACH chemical registration requirements and biodegradability certifications are forcing synthetic polymer replacement in packaging and water treatment applications across European manufacturing.
- Enzymatic deacetylation advances:Biocatalytic processing technologies are reducing caustic soda consumption by 60% in chitosan production, cutting alkali waste discharge costs for coastal processors.
- Japan METI biomedical clusters:Government-funded regenerative medicine research hubs in Osaka and Kobe are creating concentrated demand pull for high-purity chitosan in tissue engineering scaffolds.
Market Restraints
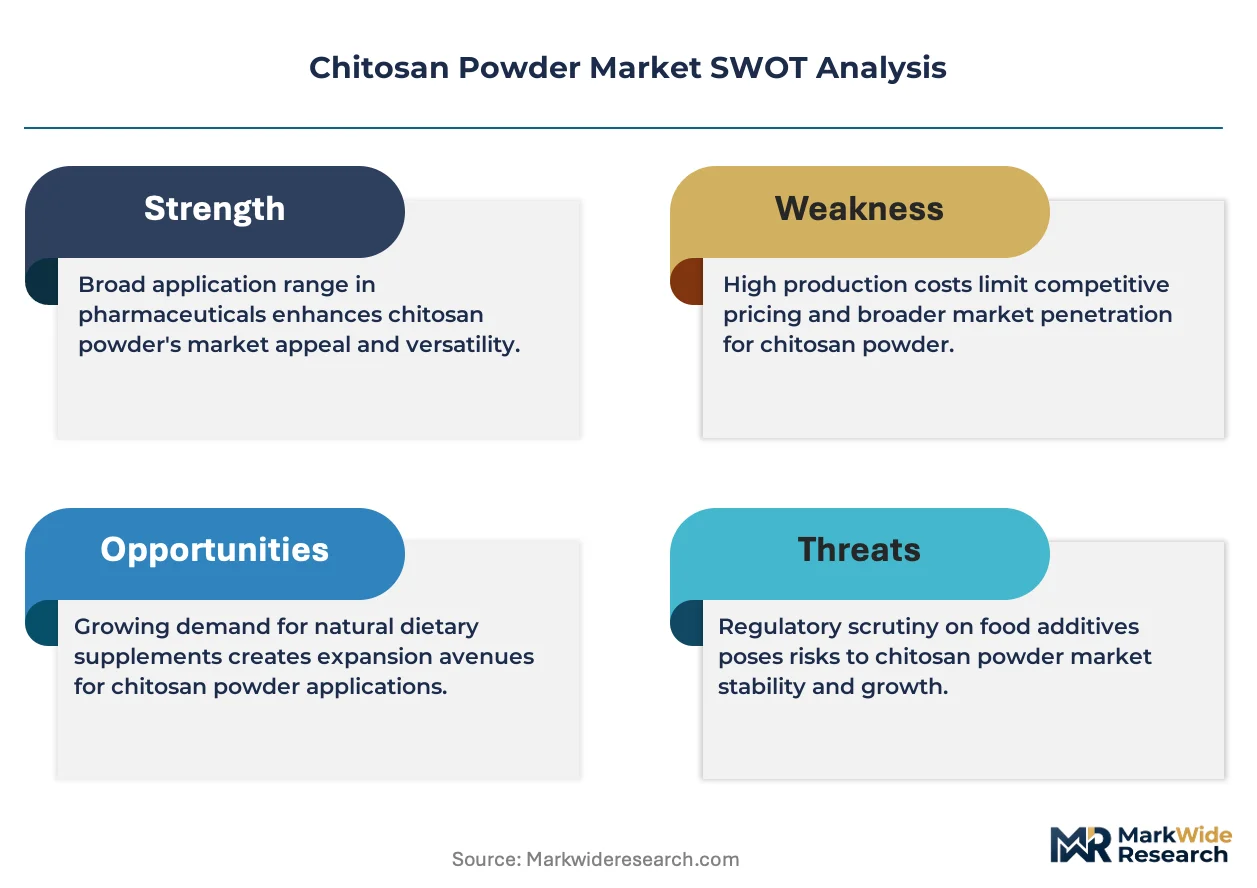
- Crustacean shell supply seasonality:North Atlantic and North Pacific fishing quotas create 40% raw material volume swings between peak harvest and off-season months.
- Pharmaceutical-grade certification costs:EMA medical device regulation compliance and ISO 13485 quality management system audits add 18-24 month qualification timelines for new suppliers.
- Chitosan oligosaccharide substitution:Lower molecular weight derivatives are capturing functional food and cosmeceutical demand that previously flowed to standard chitosan powder grades.
Strategic Opportunities
- India CDSCO pharmaceutical pathway:The country's national pharmaceutical regulator is streamlining active pharmaceutical ingredient approvals for marine-derived excipients, opening formulation partnerships with domestic generic drug manufacturers.
- Chitosan nanoparticle oncology delivery:Nanoscale drug carrier systems are penetrating Phase II clinical trials for targeted chemotherapy release, creating premium pricing tiers above conventional excipient markets.
- US EPA municipal flocculation procurement:National Primary Drinking Water Regulations are tightening turbidity standards, accelerating chitosan adoption in water treatment plants seeking biodegradable coagulant alternatives.
Industry Challenges
- Deacetylation degree standardization:Inconsistent 70-95% deacetylation measurement protocols across ISO, JIS, and USP methodologies are creating batch rejection disputes between suppliers and pharmaceutical formulators.
- Biomedical processing skill scarcity:Qualified technicians capable of maintaining pyrogen-free environments during chitosan nanoparticle synthesis command 3x standard chemical operator wages in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chitosan Powder Market |
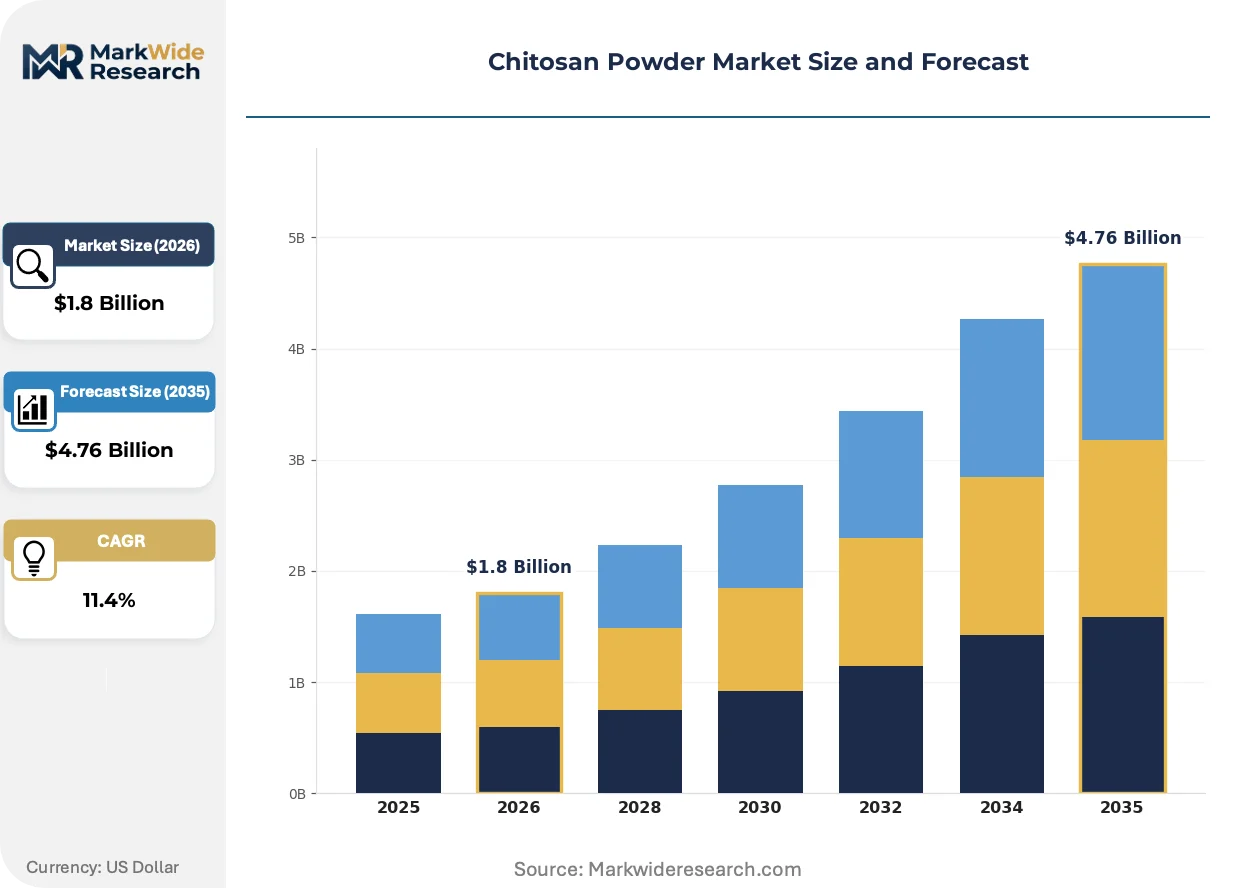
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deacetylated Chitosan, Chitosan Oligosaccharides, Chitosan Nanoparticles, Chitosan Microspheres End Use Industry: Pharmaceuticals, Agriculture, Food & Beverage, Cosmetics Form: Powder, Granules, Tablets, Capsules Application: Food Preservation, Water Treatment, Drug Delivery, Biodegradable Films |
| Companies Covered | Primex EHF, Heppe Medical Chitosan GmbH, Kitozyme S.A., Advanced Biopolymers AS, Golden-Shell Pharmaceutical, Qingdao Yunzhou Biochemistry Co., Ltd., Panvo Organics Pvt Ltd., Novamatrix, Biopharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chitosan Powder Market Emerging Trajectories
Electrochemical and enzymatic production methods are displacing conventional alkali-intensive processing, while regulatory traceability requirements are reshaping how coastal processors document marine resource origins for biomedical customers.
Continuous-flow enzymatic deacetylation is electrifying chitosan manufacturing economics by eliminating batch reactor downtime and caustic soda neutralization steps. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting these systems to secure EMA environmental compliance documentation. The technology is compressing capital recovery timelines for mid-scale processors from seven years to under four.
EMA medical device regulation updates are mandating marine resource traceability from catch documentation through final polymer certification. European chitosan importers must now submit species identification and fishing zone coordinates for every crustacean shell batch. High-purity biomedical grades face the steepest documentation burdens, with German and French notified bodies rejecting 30% of first-submission technical files for incomplete chain-of-custody records.
Formulators are consolidating supplier relationships around vertically integrated processors offering integrated quality testing and regulatory filing support. Small and mid-sized biomedical companies in Japan and the United States are abandoning multi-source procurement in favor of single-supplier partnerships with ISO 13485-certified coastal operations. This concentration is most visible in regenerative medicine clusters around Kobe and Boston, where scaffold manufacturers prioritize audit-ready documentation over unit cost minimization.
Chitosan Powder Market Segmentation
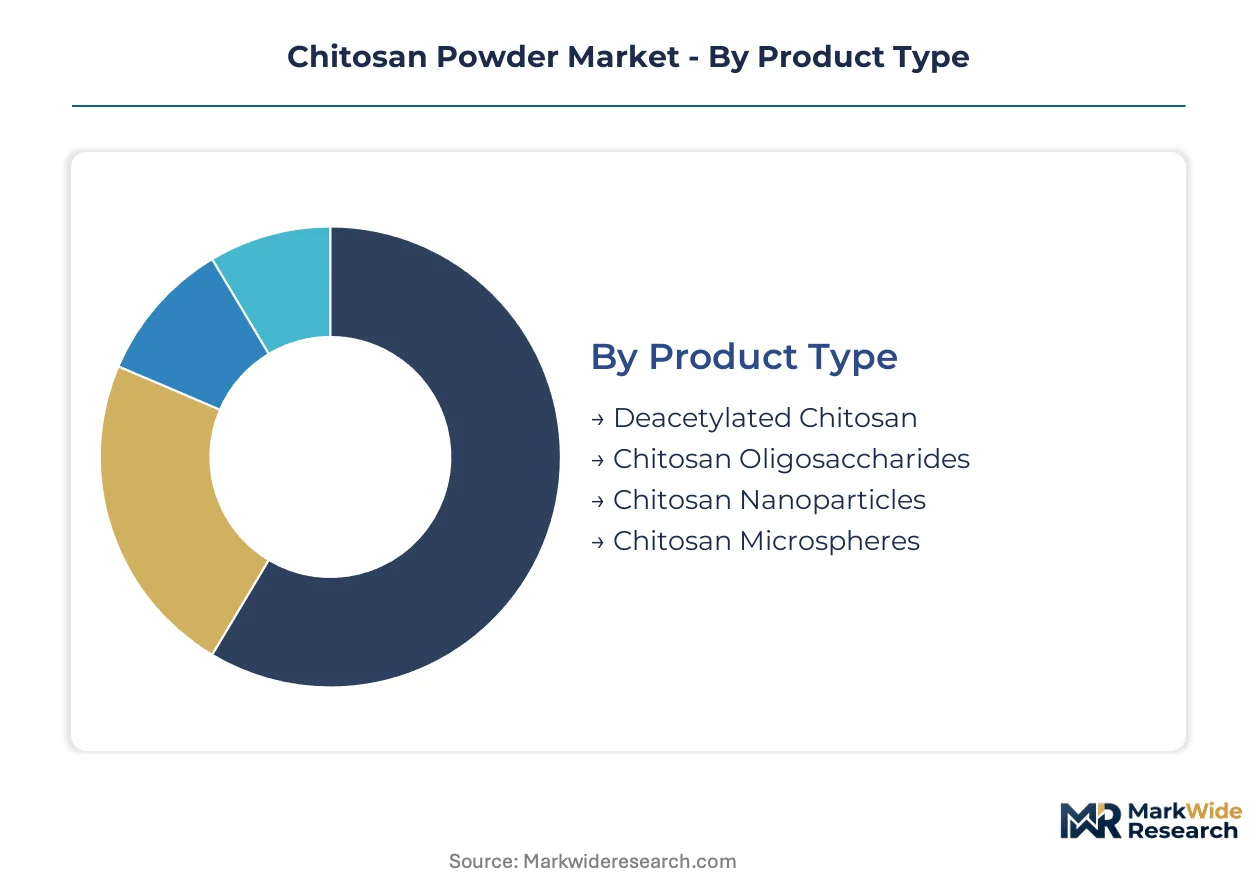
Chitosan powder procurement decisions hinge on molecular weight specifications, regulatory certification tiers, and end-use performance requirements. Manufacturers segment supply chains to match deacetylation precision with application-specific bioactivity demands.
Product Type:
Cost tier determines supplier qualification pathways, with pharmaceutical-grade certification adding 40-60% processing overhead versus industrial grades.
- Deacetylated Chitosan:This standard-grade biopolymer achieves 70-95% deacetylation through alkaline processing of crustacean shells. Water treatment municipalities in Germany and biomedical scaffold manufacturers in Japan drive volume procurement for flocculation and tissue engineering matrices.
- Chitosan Oligosaccharides:Lower molecular weight derivatives (typically under 10 kDa) enable enhanced cellular uptake. Functional food formulators in South Korea and cosmeceutical developers in France concentrate demand for bioavailable antioxidant and antimicrobial applications.
- Chitosan Nanoparticles:Nanoscale carriers penetrate Phase II oncology trials for targeted chemotherapy release, commanding premium excipient pricing from Swiss and Boston contract manufacturers.
- Chitosan Microspheres:Spherical particulate forms enable controlled-release depot formulations for long-acting injectables.
Deacetylated chitosan leads on scale; chitosan nanoparticles lead on momentum.
End Use Industry:
Application maturity separates established volume buyers from emerging specification-driven adopters.
- Pharmaceuticals:Drug delivery systems and regenerative medicine scaffolds require EMA-aligned traceability and ISO 13485 quality management. METI-funded clusters in Osaka and Kobe generate concentrated demand pull for high-purity grades.
- Agriculture:Biopesticide formulations and seed coating applications exploit chitosan's elicitor properties for plant defense activation.
- Food & Beverage:Preservative and edible film applications leverage FDA GRAS status and EFSA novel food approvals.
- Cosmetics:Moisture-retention and antimicrobial claims in Korean and French skincare drive oligosaccharide-grade consumption.
Pharmaceuticals anchor revenue concentration; agriculture shows steepest expansion trajectory.
Form:
Processing stage determines logistics economics and end-user handling requirements.
- Powder:The dominant commercial format enables flexible dissolution and compounding across all application categories. Bulk pharmaceutical and water treatment procurement favors 25-kg drum packaging for handling efficiency.
- Granules:Reduced dust generation improves occupational safety in high-volume agricultural blending operations.
- Tablets:Pre-compressed units simplify dosing for small-scale water treatment and aquaculture applications.
- Capsules:Unit-dose delivery suits nutraceutical and dietary supplement distribution channels.
Powder dominates volume throughput; granules gain share in safety-regulated environments.
Application:
Performance certification requirements fragment supply sources between industrial and biomedical qualified producers.
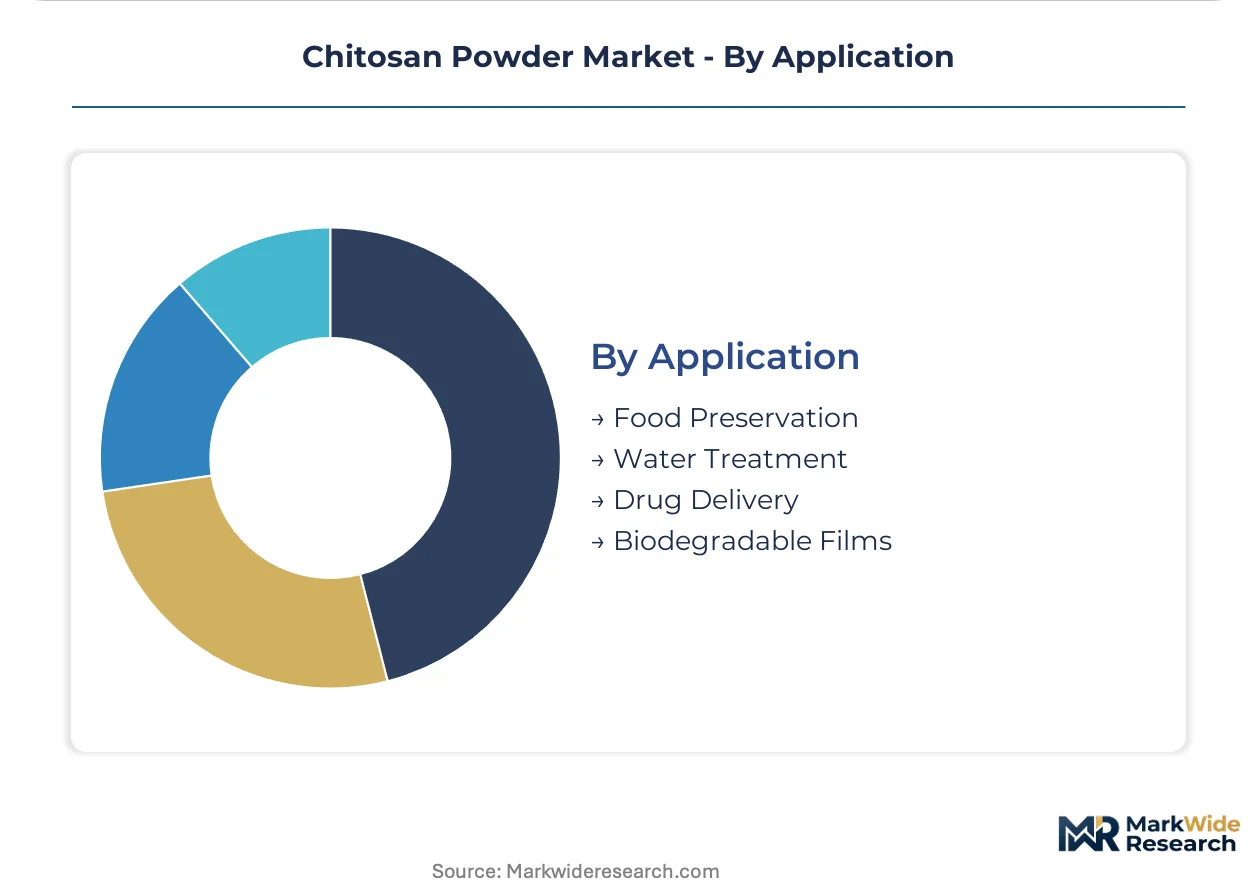
- Food Preservation:Antimicrobial coatings and shelf-life extension applications exploit chitosan's film-forming barrier properties against oxygen and moisture.
- Water Treatment:Municipal flocculation procurement under EPA National Primary Drinking Water Regulations drives biodegradable coagulant substitution in US treatment plants.
- Drug Delivery:Nanoparticle and microsphere excipients for oncology and vaccine adjuvant applications command the highest purity premiums from EMA-notified body-certified suppliers.
- Biodegradable Films:EU Green Deal packaging mandates accelerate synthetic polymer replacement in French and German flexible packaging.
Water treatment sustains volume leadership; drug delivery climbs fastest on value per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka-Kobe biomedical corridor generates concentrated procurement pull for pharmaceutical-grade chitosan, with METI-funded regenerative medicine clusters creating anchor demand for high-purity grades. Coastal processing operations in Iceland and Vietnam secure raw material access through cold-water shrimp and tropical crab waste stream partnerships.
Japan
Osaka and Kobe tissue engineering scaffold manufacturers drive premium-grade consumption through METI biomanufacturing initiative funding. PMDA pharmaceutical standards enforce pyrogen-free certification requirements that concentrate supplier relationships around ISO 13485-qualified coastal processors. Domestic crab and shrimp processing waste streams from Hokkaido fisheries provide captive raw material security for vertically integrated operations.
Germany
EMA medical device regulation compliance costs filter supplier entry, with notified bodies in Berlin and Munich rejecting technical files for incomplete marine resource traceability. REACH chemical registration mandates accelerate synthetic polymer substitution in municipal water treatment procurement. Bavarian pharmaceutical contract manufacturers consolidate single-source partnerships with enzymatic deacetylation technology adopters.
United States
EPA National Primary Drinking Water Regulations tighten turbidity standards for municipal flocculation procurement, expanding biodegradable coagulant adoption in Great Lakes and Northeast treatment plants. FDA GRAS notifications govern food additive approvals for preservative and edible film applications. Greater Boston regenerative medicine clusters mirror Japanese demand patterns for audit-ready documentation over unit cost minimization.
Iceland
North Atlantic cold-water shrimp processing partnerships yield consistent crustacean shell supply for biomedical-grade production. EMA-aligned traceability documentation from catch through final polymer certification supports European pharmaceutical market access. Coastal processors leverage geographic isolation to secure decade-long raw material contracts with German and Swiss contract manufacturers.
India
CDSCO pharmaceutical regulator streamlining of marine-derived excipient approvals opens formulation partnerships with domestic generic drug manufacturers in Maharashtra and Gujarat. FSSAI food safety standards govern preservative applications in processed food manufacturing. Tamil Nadu and Andhra Pradesh coastal aquaculture operations expand crustacean waste aggregation for industrial-grade chitosan production.
Chitosan Powder Market Vendor Landscape
Global majors compete with regional champions across certification tier and raw material access dimensions. The vendor base stratifies between pharmaceutical-grade specialists with ISO 13485 alignment and industrial-grade processors serving water treatment and agriculture applications. Three archetypes dominate: vertically integrated coastal processors with captive crustacean supply, enzymatic technology specialists reducing alkali waste discharge, and pharmaceutical contract manufacturers with regulatory filing support capabilities. Competitive moves concentrate on backward integration into fishing quota partnerships and capacity expansion for nanoparticle-grade production.
Within the vertically integrated processor tier, Primex EHF exemplifies geographic specialization through Icelandic cold-water shrimp sourcing partnerships. Heppe Medical Chitosan GmbH occupies a position among EMA-notified body-certified specialists serving German and Swiss pharmaceutical contract manufacturing demand. Kitozyme S.A. represents the enzymatic technology archetype with European food-grade supply positioning. These three anchors illustrate how raw material security, regulatory certification depth, and processing technology differentiation create distinct competitive positions.
| Leading Market Players |
|---|
| Primex EHF |
| Heppe Medical Chitosan GmbH |
| Kitozyme S.A. |
| Advanced Biopolymers AS |
| Golden-Shell Pharmaceutical |
| Qingdao Yunzhou Biochemistry Co., Ltd. |
| Panvo Organics Pvt Ltd. |
| Novamatrix |
| Biopharm |
| Others |
Supply Flow & Price Mechanics
North Atlantic cold-water shrimp shell spot indices cascade through three distinct pricing tiers, with pharmaceutical-grade certification premiums widening against industrial-grade benchmarks as EMA traceability mandates harden procurement specifications for biomedical buyers.
Pricing Analysis
Input-cost pass-through from crustacean waste aggregation dominates contract negotiations, with enzymatic deacetylation adopters capturing margin relief against alkali-intensive processors. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels reflects certification depth and deacetylation precision. Pricing pressure stems from chitosan oligosaccharide substitution in functional food applications, compressing standard-grade realizations. Municipal water treatment buyers exhibit highest price sensitivity, while Swiss and Boston oncology contract manufacturers accept premium excipient multiples for nanoparticle-grade supply.
Supply Chain Analysis
Certification gating through ISO 13485 and EMA medical device regulations concentrates qualified supply among German, Icelandic, and Japanese coastal processors with captive raw material access. Production draws from North Atlantic shrimp fisheries, Hokkaido crab processing waste, and Vietnam tropical aquaculture operations. Single-source vulnerability pervades pharmaceutical-grade procurement, where decade-long raw material contracts lock in buyer-supplier dependencies. Distribution runs through direct partnerships with biomedical contract manufacturers, bypassing commodity chemical distributors for high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chitosan powder market has entered a late-cycle quality phase, with regenerative medicine scaffold specifications hardening deacetylation degree tolerances beyond legacy industrial-grade norms.
For Market Incumbents: Extend certification depth into EMA-notified body dual registrations to preempt emerging enzymatic technology specialists from capturing pharmaceutical market share. Deepen upstream control over Hokkaido and North Atlantic fishing quota partnerships before raw material access consolidates further. Capacity expansion in enzymatic deacetylation technology represents the critical defensive lever against alkali-waste regulatory restrictions tightening across European coastal zones. For New Entrants and Emerging Players: The premium-economy tier price gap in Indian pharmaceutical excipient supply creates immediate white-space opportunity for CDSCO-aligned production investments. Agricultural biopesticide formulations in Maharashtra and Gujarat offer the most penetrable volume segment, with FSSAI compliance requirements less burdensome than biomedical certification pathways. A co-manufacturing partnership with established Tamil Nadu crustacean processors accelerates market entry without captive fishing infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with enzymatic technology specialists possessing both coastal raw material contracts and ISO 13485 quality management alignment. The five-to-ten year viability window favors acquisition targets with demonstrated EMA technical file submission success rather than pure production scale. The signal to watch is Phase II oncology trial progression for chitosan nanoparticle drug delivery systems, which would validate premium excipient pricing sustainability and trigger valuation repricing across the qualified supplier tier.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Deacetylation Capacity Buildout | EMA environmental compliance documentation secures pharmaceutical contract manufacturing partnerships in Germany and Switzerland. |
| Backward Integration into Fishing Quota Partnerships | Decade-long raw material contracts with Icelandic and Hokkaido processors eliminate crustacean shell supply seasonality exposure. |
| ISO 13485 Certification Investment | Medical device quality management alignment opens regenerative medicine scaffold procurement channels in Osaka-Kobe clusters. |
| Chitosan Nanoparticle Production Scale-Up | Oncology drug delivery excipient qualification commands premium pricing tiers from Boston and Swiss contract manufacturers. |
| CDSCO Pharmaceutical Pathway Navigation | Streamlined marine-derived excipient approvals enable formulation partnerships with Maharashtra and Gujarat generic drug producers. |
Methodological Framework
Coverage spans Japan, Germany, the United States, Iceland, and India, with primary inputs from each market gathered through structured interviews with pharmaceutical contract manufacturing executives, biomedical scaffold R&D directors, municipal water treatment procurement officers, crustacean processing plant managers, and regulatory affairs specialists at EMA-notified bodies. Secondary validation incorporated FDA GRAS notification databases, EMA medical device regulation technical file submissions, EPA National Primary Drinking Water Regulations compliance records, METI biomanufacturing initiative funding disclosures, and customs trade data for chitin derivative flows. Bottom-up volume estimates from end-use application demand were triangulated against top-down supply-side capacity assessments across enzymatic and alkaline processing routes.
Rate-of-change decomposition across the projection horizon separated volume growth drivers from value-per-kilogram expansion, with segmentation modeling across deacetylation grade tiers, molecular weight specifications, end-use industry categories, and regional regulatory clusters. CAGRs were derived from fitted growth curves anchored to documented procurement contract volumes and announced capacity expansions. Forecast inputs included enzymatic technology adoption rates, EMA traceability documentation burden evolution, and METI-funded regenerative medicine cluster funding trajectories.
The model assumes a particular technology adoption path; alternative pathways for electrochemical deacetylation commercialization would alter the outlook for alkali waste discharge cost structures and coastal processor competitive positioning. Forecasts reflect assumptions regarding regulatory enforcement consistency, fishing quota stability, and pharmaceutical-grade certification timeline norms. A model refresh is warranted upon material change in Phase II clinical trial progression for chitosan nanoparticle oncology applications or substantial revision to EU Green Deal biodegradability certification schemes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
High Performing Matting Agents Market
Additives
Lecithin and Phospholipids Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Low Melt Inclusions Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
China Citric Acid Market
Additives
Global Flame Retardant Masterbatches Market
Additives
Ethoxyquin Market
Additives
Apocarotenal Market
Additives
Global Metal Scavenging Agents Market
Additives
Anti-Block Additives Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Global Cement Additives Market
Additives
Inorganic Filler Market
Additives
Alginic Acid Market
Additives
North America Pectin Market