
 Silage Additives Market | 2026-2036
Silage Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Silage Additives Market Intelligence
The price-performance gap between premium inoculant formulations and commodity chemical preservatives is hardening as dairy processors impose stricter milk quality contracts. BASF SE leverages its industrial chemical heritage to sustain cost-competitive organic acid lines across European feed channels. Lallemand anchors its position through specialized bacterial culture portfolios that dominate high-value dairy cooperative supply agreements. DSM-Firmenich differentiates via integrated nutritional science platforms that extend beyond silage into full ruminant health systems.
Silage additives comprise chemical and biological formulations applied to forage crops to accelerate beneficial fermentation, suppress spoilage organisms, and preserve nutritional value during anaerobic storage; typical inoculants contain defined strains of Lactobacillus buchneri or Pediococcus pentosaceus at concentrations exceeding 100,000 colony-forming units per gram of fresh forage, with organic acid salts such as sodium benzoate or potassium sorbate serving as chemical alternatives that directly lower pH. Biological additives represent the fastest-expanding technology category as bacterial cultures displace synthetic preservatives under tightening residue regulations, while fermentation inhibitors retain margin concentration in price-sensitive beef cattle segments where storage losses impose heavier economic penalties than milk quality premiums.
EMA guidelines on veterinary medicinal product residues, REACH substance restrictions on synthetic acids, and EU Green Deal farm-to-fork targets collectively redirect formulation R&D toward microbial solutions with documented safety dossiers. The European Commission's Farm Sustainability Data Network creates compliance transparency that favors suppliers with third-party validated bacterial strain libraries. Stakeholders must monitor how feed-to-food traceability mandates reshape procurement criteria for silage additive selection across integrated dairy supply chains.
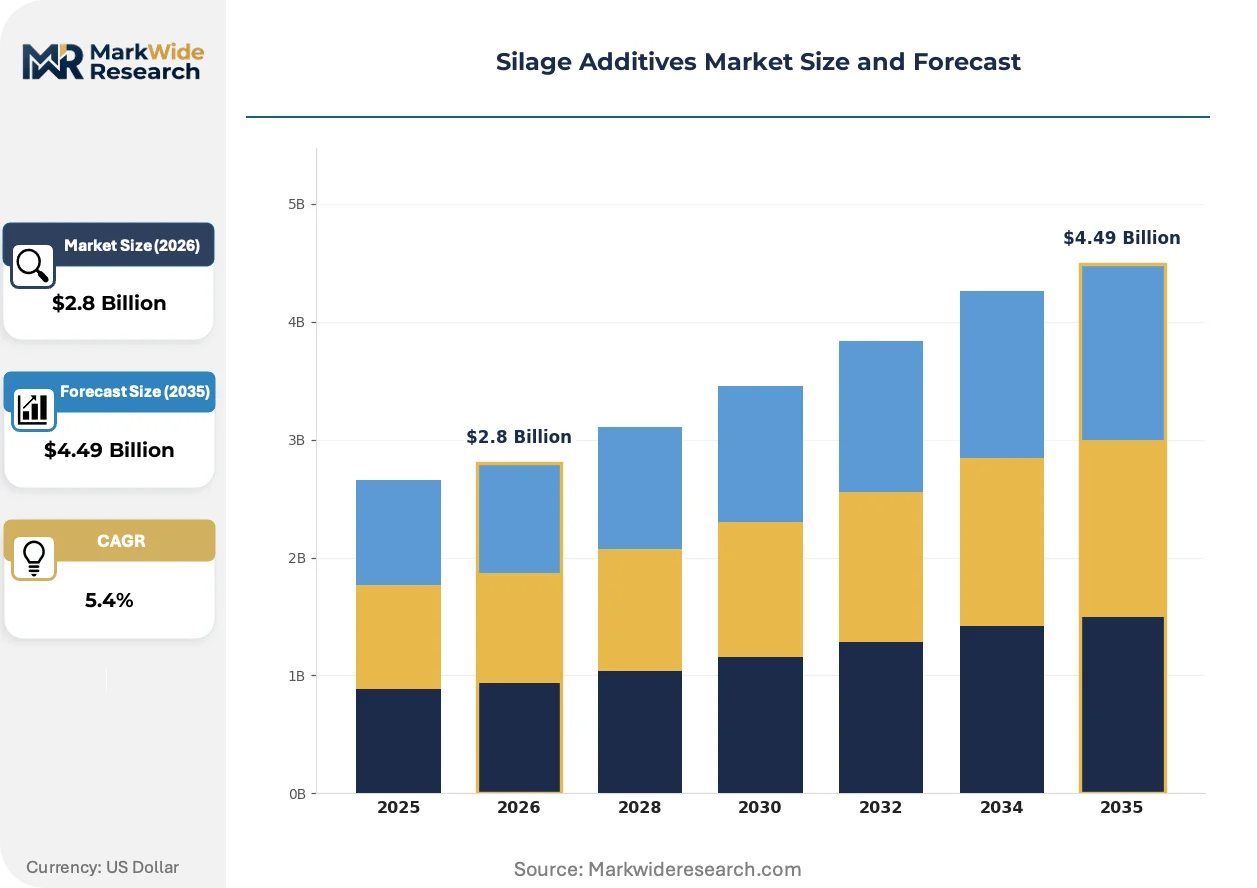
Market Dynamics
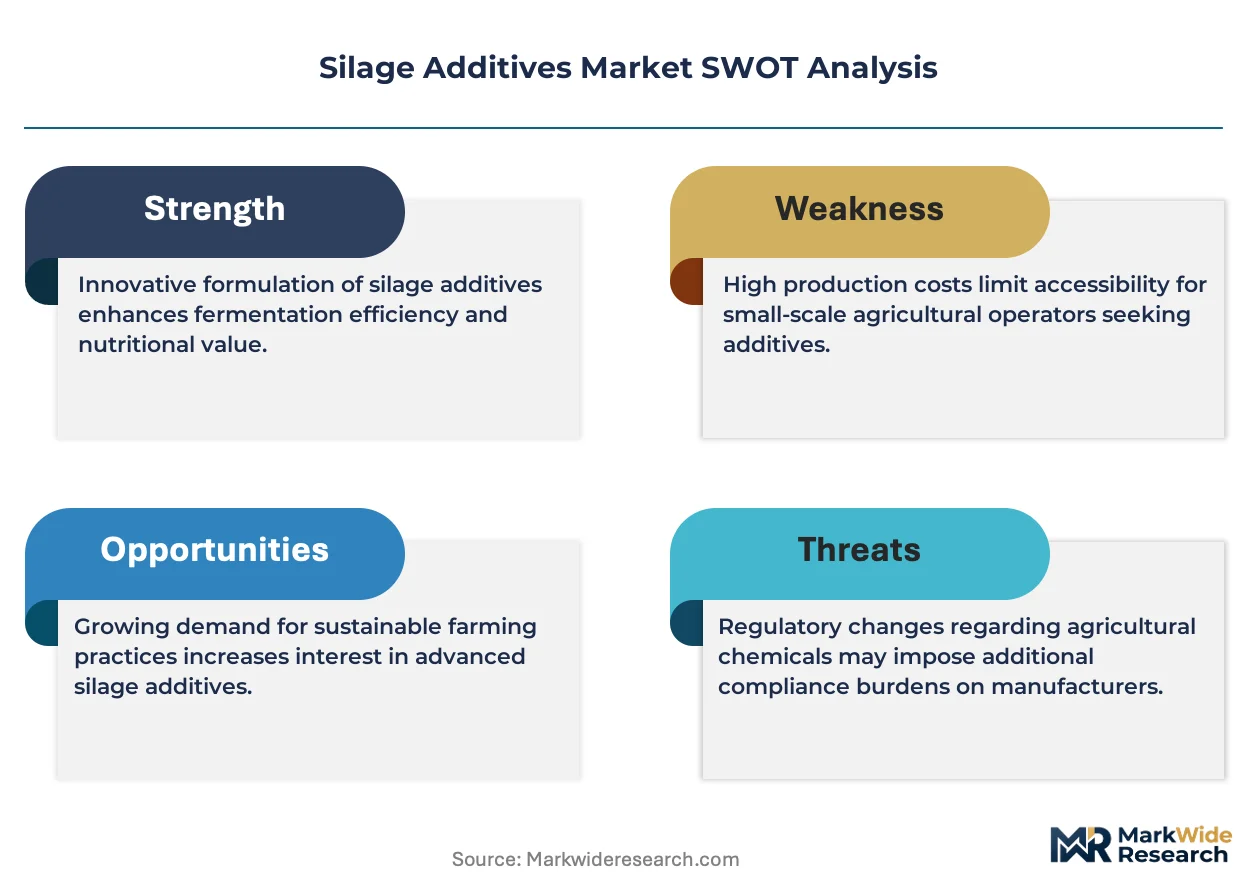
The European Union's F-Gas Regulation and REACH frameworks are systematically disqualifying synthetic acid preservatives while elevating microbial inoculants to default status in commercial dairy procurement.
Growth Catalysts
- Biological fermentation science:Defined bacterial strain libraries from Lactobacillus buchneri and Pediococcus pentosaceus now deliver pH stability rivaling chemical alternatives without residue risk.
- EU Green Deal farm-to-fork targets:Mandatory sustainability disclosures through the Farm Sustainability Data Network create procurement preference for third-party validated biological additives.
- German dairy cooperative consolidation:Large-scale feed procurement by integrated processors in Bavaria and Lower Saxony standardizes inoculant specifications across thousands of member farms.
Market Restraints
- Live culture supply concentration:Specialized bacterial culture production clusters in Denmark and the Netherlands create geographic chokepoints for inoculant manufacturers.
- Organic acid feedstock volatility:Propionic acid and benzoate salt prices track petrochemical derivatives, compressing margins for chemical preservative lines.
- EMA residue documentation requirements:Veterinary medicinal product dossiers for novel strains extend approval timelines beyond typical product development cycles.
Strategic Opportunities
- Polish and Romanian dairy expansion:Underpenetrated markets in Eastern European member states lack established inoculant supply relationships, opening cooperative contract opportunities.
- Silage-to-ruminant health integration:Convergence of fermentation science with microbiome analytics enables full-feed-system positioning beyond standalone preservation.
- CSRD-aligned carbon accounting:Corporate sustainability reporting mandates create demand for additives with verified methane reduction credentials in enteric fermentation modeling.
Industry Challenges
- Strain-specific technical expertise:Formulation chemists with combined anaerobic microbiology and ruminant nutrition credentials remain scarce across European R&D centers.
- Legacy chemical inventory integration:Beef cattle operations with sunk costs in organic acid storage infrastructure resist biological conversion despite tightening regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silage Additives Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermentation Inhibitors, Organic Acids, Enzymes, Biological Additives Application: Dairy Cattle, Beef Cattle, Sheep, Goats Form: Liquid, Powder, Granules, Tablets Technology: Chemical Preservatives, Natural Fermentations, Bacterial Cultures, Enzymatic Processes |
| Companies Covered | DuPont Pioneer, DSM-Firmenich, Lallemand, Volac, Nutreco, BASF SE, Schaumann BioEnergy, ADDCON, Chr. Hansen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silage Additives Market Strategic Shifts & Innovations
Biological preservation systems are displacing synthetic chemistry through regulatory compulsion rather than price competition, fundamentally restructuring how feed additives are formulated, validated, and procured across European dairy supply chains.
Multi-strain inoculant cocktails with Lactobacillus buchneri as the anchor organism are electrifying anaerobic stability performance in corn and grass silages. Dutch dairy cooperatives in Friesland and North Holland have adopted these formulations as baseline specifications. The technology is electrifying competitive positioning by collapsing the historical performance gap between premium biologicals and commodity chemical preservatives.
REACH substance restrictions on synthetic organic acids are accelerating formulation exits among incumbent chemical suppliers. Industrial consequences include stranded production capacity for benzoate and sorbate lines originally scaled for feed applications. German feed compounders are responding fastest, converting blending facilities to inoculant handling infrastructure ahead of anticipated substance authorization withdrawals.
Consolidated procurement by integrated dairy processors is compressing supplier rosters to single-source or dual-source arrangements. Traditional distribution through independent agricultural merchants is losing share to direct manufacturer-cooperative contracting. This concentration is most visible in the Netherlands, where three dairy cooperatives control additive selection for over eighty percent of national milk production.
Silage Additives Market Segmentation
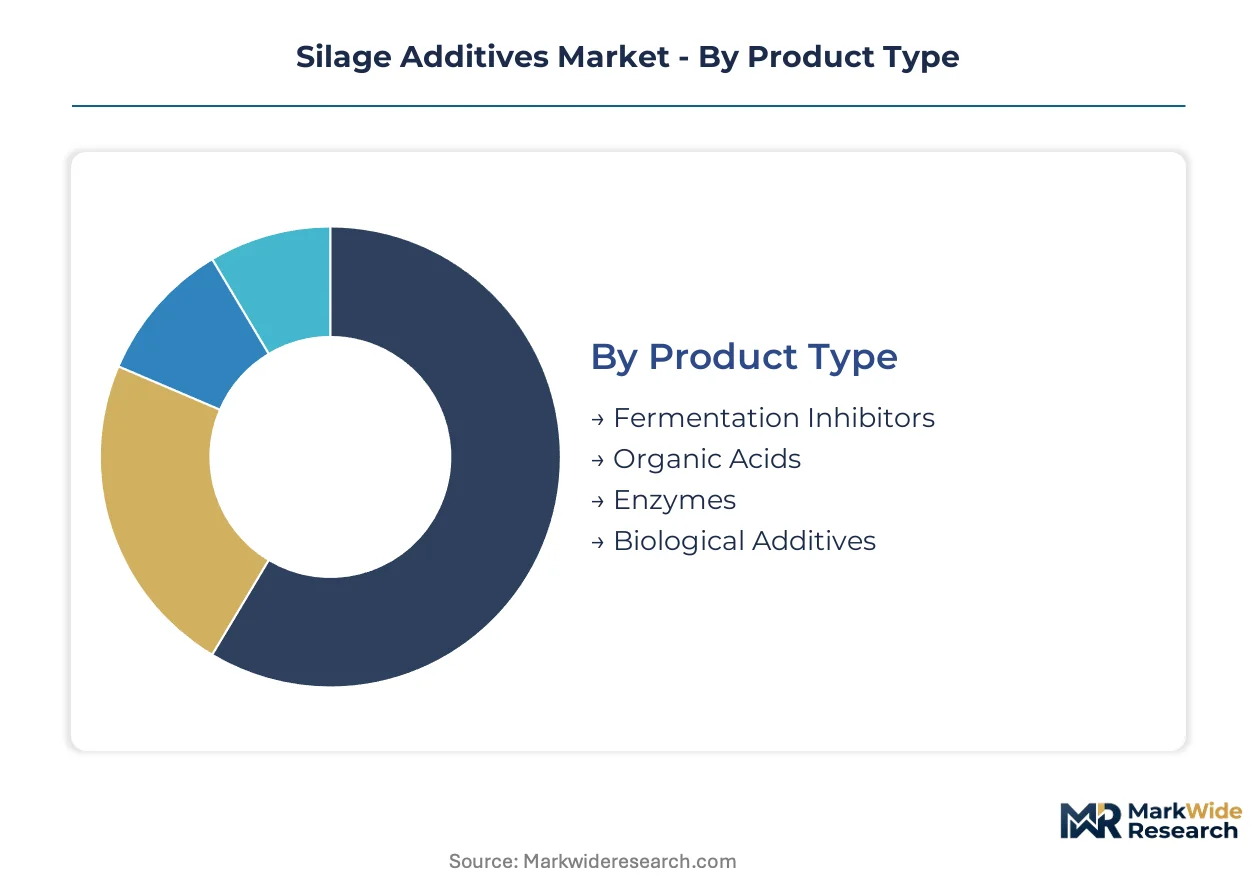
Silage additive procurement patterns diverge sharply across livestock categories and farm scales, with dairy cooperatives prioritizing residue-free biologicals while beef operations optimize for storage loss economics. Formulation selection further fragments by application method infrastructure and regional regulatory compliance requirements.
Product Type:
Cost tier differentiation separates commodity chemical preservatives from premium biological formulations with documented strain efficacy.
- Biological Additives:Defined bacterial cultures of Lactobacillus buchneri and Pediococcus pentosaceus deliver anaerobic stability without synthetic residue risk. Demand concentrates in German and Dutch dairy cooperatives where milk quality contracts impose strict additive documentation requirements under EMA veterinary medicinal product guidelines.
- Organic Acids:Propionic acid, benzoate salts, and sorbate formulations provide direct pH suppression through chemical action. Beef cattle operations in price-sensitive Eastern European markets retain this category where storage infrastructure investments already favor liquid acid handling systems.
- Fermentation Inhibitors:Nitrite and hexamine-based compounds arrest spoilage organism metabolism through metabolic disruption.
- Enzymes:Cellulase and hemicellulase preparations accelerate fiber breakdown to improve digestibility in lower-quality forages.
Organic acids lead volumes today; biological additives are gaining share fastest.
Application:
End-use livestock category determines performance premium tolerance and regulatory scrutiny intensity.
- Dairy Cattle:High-value milk production justifies premium inoculant expenditure where quality premiums outweigh additive costs. Integrated processors in Bavaria and Lower Saxony standardize bacterial culture specifications across member farms through cooperative procurement.
- Beef Cattle:Feedlot operations prioritize storage loss minimization over residue concerns, sustaining organic acid demand despite REACH substance restrictions on synthetic preservatives.
- Sheep:Smaller flock sizes and seasonal production patterns favor low-cost powder formulations with minimal application equipment requirements.
- Goats:Niche dairy segments in France and Greece drive specialized inoculant demand for high-fat milk preservation.
Dairy cattle dominates revenue concentration; beef cattle maintains the largest treated tonnage base.
Form:
Application infrastructure maturity and labor availability shape physical formulation preferences across farm scales.
- Liquid:Tank-mix systems enable precise dosing through existing spray equipment on large-scale operations. Dutch dairy cooperatives in Friesland specify liquid inoculants for automated forage harvester integration.
- Powder:Dry formulations offer extended shelf stability and simplified logistics for distributed farm networks without refrigerated storage capacity.
- Granules:Dust-free handling characteristics appeal to operations with manual application protocols and respiratory safety concerns.
- Tablets:Pre-measured unit dosing eliminates mixing calculations for smaller farms with variable forage volumes.
Liquid formulations capture the steepest expansion trajectory; powder maintains broadest geographic penetration.
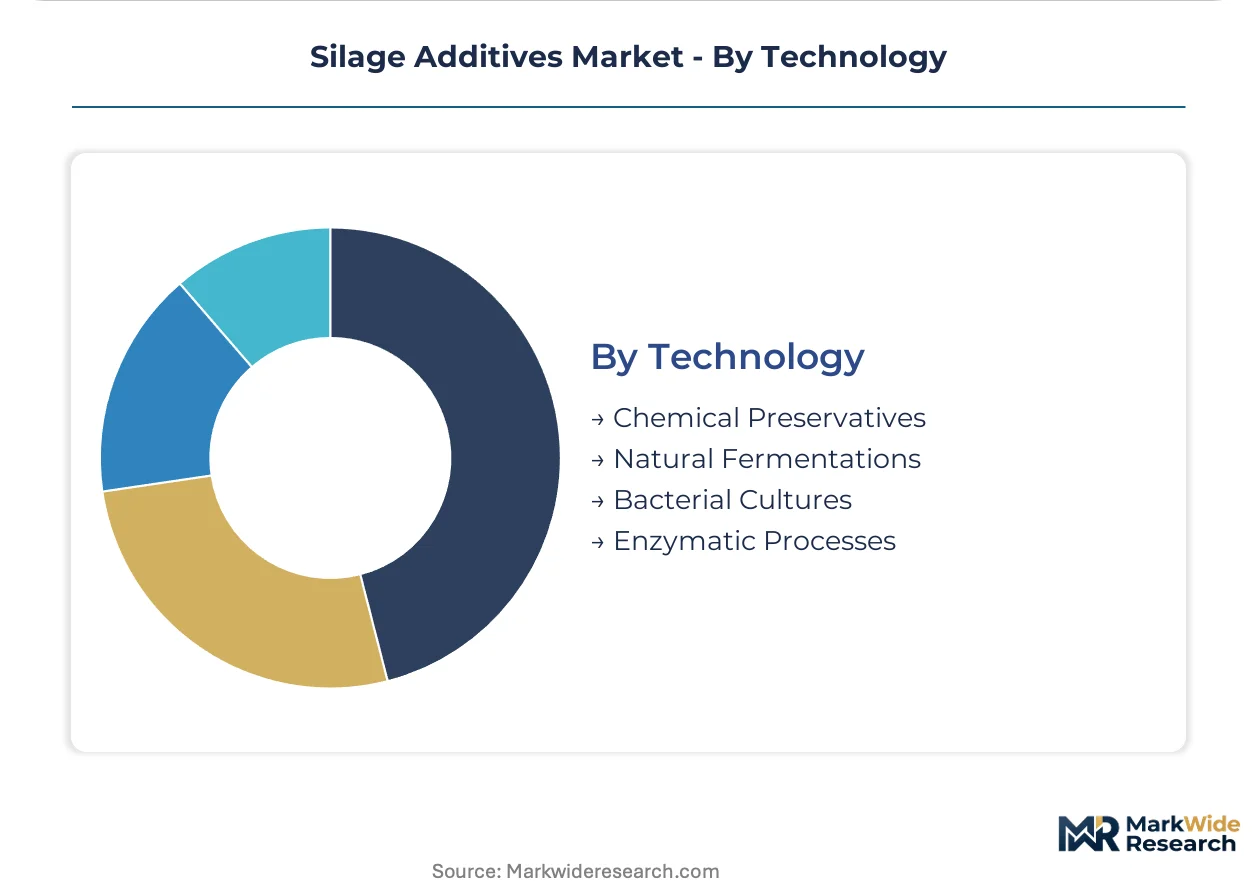
Technology:
Regulatory authorization pathways and residue documentation requirements increasingly determine technology selection feasibility.
- Bacterial Cultures:Multi-strain cocktails with validated safety dossiers satisfy EU Green Deal farm-to-fork traceability mandates. EMA veterinary medicinal product approvals for novel strains extend development timelines but secure exclusive market positions.
- Chemical Preservatives:REACH substance restrictions on benzoates and sorbates accelerate formulation exits among incumbent suppliers with stranded production capacity.
- Natural Fermentations:Undefined wild culture systems retain cost advantage in informal supply chains lacking third-party validation infrastructure.
- Enzymatic Processes:Fiber-degrading catalysts complement bacterial inoculants in premium tier formulations targeting high-digestibility dairy rations.
Chemical preservatives retain installed base dominance; bacterial cultures climb the fastest amid regulatory displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized microbiologists and fermentation scientists cluster in Denmark and the Netherlands, anchoring bacterial culture supply for inoculant manufacturers. These talent concentrations shape procurement networks across European dairy regions. Geography determines additive selection through regulatory pressure and cooperative consolidation intensity.
Germany
Dairy cooperative procurement in Bavaria and Lower Saxony standardizes Lactobacillus buchneri specifications across thousands of member farms. The F-Gas Regulation and REACH frameworks systematically disqualify synthetic acid preservatives from commercial feed channels. Industrial conversion is accelerating in northern feed compounding clusters as blending facilities shift from chemical handling to live culture infrastructure.
Netherlands
Three dairy cooperatives control additive selection for over eighty percent of national milk production, compressing supplier rosters to direct manufacturer contracts. The Farm Sustainability Data Network mandates traceability disclosures that favor third-party validated biological formulations. Friesland and North Holland processing centers specify liquid inoculants with automated forage harvester integration.
France
Large-scale dairy operations in Brittany and Normandy expand inoculant use under processor-imposed milk quality contracts. EMA veterinary medicinal product guidelines require residue documentation that elevates microbial solutions over chemical alternatives. Auvergne-Rhône-Alpes hosts specialized bacterial strain validation facilities serving cooperative supply agreements.
Poland
Eastern European dairy expansion lacks established inoculant supply relationships, opening cooperative contract opportunities for bacterial culture suppliers. EU Green Deal farm-to-fork targets apply fully despite later market development, accelerating biological adoption from a lower base. Masovian and Greater Poland dairy clusters represent primary penetration targets for multi-strain formulation suppliers.
Romania
Underpenetrated beef and dairy segments retain organic acid infrastructure due to price-sensitive procurement and sunk storage costs. REACH substance restrictions nonetheless apply, creating regulatory pressure for biological conversion without established distribution networks. Transylvania and Wallachia farming cooperatives present contract manufacturing opportunities for Danish and Dutch culture suppliers.
Silage Additives Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the silage additive sector. The market structure consolidates around integrated fermentation science platforms and commodity chemical heritage operations. Three strategic archetypes dominate: multinational nutrition conglomerates with ruminant health portfolios, specialized bacterial culture houses with validated strain libraries, and industrial chemical suppliers with feed channel scale. Competitive dynamics center on direct cooperative contracting and conversion of chemical blending capacity to biological handling infrastructure.
Among European-based specialists, Lallemand and Chr. Hansen exemplify the bacterial culture archetype with documented strain efficacy dossiers. DSM-Firmenich occupies a position bridging nutritional science integration with full-feed-system positioning. BASF SE represents the industrial chemical heritage segment sustaining organic acid lines through cost-competitive manufacturing scale. These three anchors illustrate the competitive tension between microbial innovation platforms and legacy preservative operations under tightening residue regulations.
| Leading Market Players |
|---|
| DuPont Pioneer |
| DSM-Firmenich |
| Lallemand |
| Volac |
| Nutreco |
| BASF SE |
| Schaumann BioEnergy |
| ADDCON |
| Chr. Hansen |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EMA-validated bacterial cultures and commodity organic acid preservatives splits procurement budgets across European dairy cooperatives. This bifurcation concentrates supply chain leverage with Danish and Dutch culture houses while compressing margins for German chemical compounders facing REACH substance authorization withdrawals.
Pricing Analysis
Service bundling separates premium inoculant suppliers offering technical advisory and residue documentation from unbundled commodity acid vendors. Three-tier pricing structure across premium, standard, and economy levels reflects EMA dossier completeness, strain specificity, and cooperative volume commitments. Cost compression in chemical preservative tiers is intensifying because petrochemical feedstock volatility erodes margin buffers. Beef cattle operations in Eastern Europe exhibit highest price sensitivity; integrated Dutch dairy processors show lowest.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-compromised live cultures remains underdeveloped, forcing write-offs when cold chains fail between Danish production facilities and Southern European farms. Supply concentrates in Denmark, the Netherlands, and Germany for bacterial strain propagation and formulation. Raw material dependencies include fermentation media, cryoprotectant agents, and sterile packaging films. Single-source vulnerability clusters around specialized culture collection repositories. Distribution runs through cooperative procurement officers rather than independent agricultural merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eastern European dairy expansion offers geographic arbitrage against saturated Western markets, exploiting lower biological additive penetration despite equivalent EU Green Deal compliance obligations.
For Market Incumbents: Deepen backward integration into captive bacterial strain libraries to defend against emerging culture-house competitors from Denmark. Secure exclusive cooperative supply agreements in Bavaria and Lower Saxony before REACH withdrawals accelerate chemical preservative exits. Prioritize EMA veterinary medicinal product dossier investments for novel Lactobacillus buchneri variants. For New Entrants and Emerging Players: Enter via underpenetrated Polish and Romanian dairy cooperatives lacking established inoculant supply relationships. Target Masovian and Greater Poland clusters where biological adoption lags regulatory mandates. Pursue contract manufacturing partnerships with Dutch culture suppliers to bypass stranded capital requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized microbiology talent clusters exceed formulation capacity expansion rates. Five-to-ten year viability favors bacterial culture houses with validated strain libraries over chemical preservative operations facing stranded production assets. Target acquisition archetype: mid-scale culture suppliers with EMA dossier progress but limited cooperative distribution. Monitor EMA authorization timelines for novel strains as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Dossier Investment | Accelerates market access for novel Lactobacillus buchneri strains ahead of regulatory deadlines. |
| Cooperative Supply Agreement | Locks in multi-year procurement commitments with Friesland and North Holland dairy processors. |
| Cold Chain Infrastructure | Reduces live culture spoilage losses between Danish production hubs and Eastern European farms. |
| Backward Integration | Captures margin from fermentation media and cryoprotectant supply currently sourced externally. |
| Multi-Strain Cocktail Development | Addresses anaerobic stability performance gaps that commodity chemical preservatives still exploit. |
Research Approach
Bottom-up dairy cooperative procurement modeling reconciled against top-down bacterial culture production tracking forms the analytical core. Primary interviews with feed procurement managers, fermentation scientists, cooperative technical directors, and EMA regulatory affairs specialists combined with secondary validation from EU Farm Sustainability Data Network disclosures, EMA veterinary medicinal product registers, REACH substance authorization databases, and national dairy cooperative annual reports. Triangulation across stakeholder inputs and documentary sources ensures coverage of both demand-side procurement patterns and supply-side capacity constraints.
Historical trendline analysis of inoculant adoption rates against organic acid displacement patterns established baseline growth trajectories. Segmentation modeling spans product type, livestock category, application form, and technology pathway with regional regulatory cluster overlays. CAGRs derive from volume-weighted averaging across cooperative contract terms and spot market chemical preservative transactions. Industry-specific forecast inputs include EMA authorization pipeline status and REACH substance review schedules.
The model holds under stable EU Green Deal implementation timelines; deviation in F-Gas Regulation enforcement intensity or EMA dossier approval acceleration would shift biological adoption curves. Practitioners should monitor EMA novel strain authorization bulletins and REACH benzoate withdrawal announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
LAMEA Driveline Additives Market
Additives
Oxygen Scavengers Market
Additives
Green Polymer Additive Market
Additives
Sodium Citrate Anhydrous Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Shortstop Inhibitor Market
Additives
Inorganic Filler Market
Additives
Middle East Feed Additives Market
Additives
Global Rheology Modifiers Market
Additives
Chelating Agents Market
Additives
South America Concrete Admixtures Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Pectin Market
Additives
FD and C Lakes Market
Additives
Encapsulated Citric Acid Market
Additives
Engine Oil Additive Market