
 Nucleating Agents Market | 2026-2036
Nucleating Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleating Agents Market Outlook
REACH compliance in Europe is consolidating the cost-of-entry calculus for nucleating agent suppliers seeking registration dossiers for novel organic chemistries. Milliken & Company leverages its Spartanburg research campus to sustain proprietary sorbitol-based clarifier portfolios across multiple polymer systems. ADEKA Corporation anchors Asian supply through captive production of phosphate ester nucleating agents in Japan and China. Clariant AG competes via specialized color-nucleant masterbatch combinations that integrate optical brightening with crystallization control.
Nucleating agents are crystallization promoters, typically organophosphate salts or sorbitol derivatives, that reduce polymer spherulite size from 50-100 micrometers down to 1-5 micrometers to improve optical clarity and mechanical stiffness in semi-crystalline thermoplastics. Their primary commercial purpose centers on accelerating cycle times in injection molding while boosting heat deflection temperature and flexural modulus for thin-wall packaging and automotive underhood components. Organic nucleating agents command premium positioning due to superior clarity performance in polypropylene random copolymers, while talc retains volume leadership in commodity applications where cost minimization dominates specification sheets. The packaging application segment absorbs the largest share of nucleating agent volume, driven by converter demands for downgauged containers that maintain top-load strength.
The US FDA maintains food-contact notification requirements for nucleating agents under 21 CFR, while China's SAMR enforces GB 4806 standards for plastics in food packaging, creating divergent compliance pathways for multinational suppliers. Japan's METI chemical substance reporting framework and the EU's REACH authorization process jointly elevate testing burdens for new molecular entities entering these jurisdictions. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulatory scrutiny of persistent chemistries threatens certain legacy nucleating agent categories and accelerates substitution timelines for next-generation formulations.
Market Dynamics
Polypropylene packaging converters in East China are accelerating purchases of clarifying nucleating agents as GB 4806 food-contact standards tighten, forcing reformulation cycles across Zhejiang and Jiangsu compounding clusters.
Growth Catalysts
- GB 4806 Compliance Deadlines:China's SAMR enforcement timeline for plastics in food packaging is compelling domestic converters to upgrade additive packages ahead of certification renewals.
- Downgauging Imperative:Thin-wall container specifications in appliance and automotive Tier-1 supply chains are mandating nucleating agents to maintain top-load strength at reduced wall thickness.
- Phosphate Ester Performance:Next-generation organophosphate salts are achieving sub-5-micron spherulite sizes in random copolymers, unlocking optical clarity previously reserved for amorphous polymers.
Market Restraints
- REACH Registration Burden:ECHA dossier requirements for novel organic chemistries are consolidating supplier bases and elevating cost-of-entry for European market participation.
- Sorbitol Derivative Input Volatility:Feedstock fluctuations for clarifier precursors are compressing margin structures for premium organic nucleating agent portfolios.
- Talc Substitution Pressure:Commodity mineral fillers retain volume leadership in cost-minimized applications where optical performance is secondary to flexural modulus targets.
Strategic Opportunities
- Automotive Underhood Expansion:Heat deflection temperature requirements for engine-bay components are extending nucleating agent specification into glass-reinforced polyamide systems.
- India BIS Standardization:Pending harmonization of food-contact additive regulations is creating first-mover positioning for suppliers establishing local technical service infrastructure.
- Masterbatch Integration:Color-nucleant combinations that merge optical brightening with crystallization control are capturing specification share among brand-owner packaging designers.
Industry Challenges
- PFAS Substitution Complexity:Regulatory scrutiny of persistent chemistries under EPA and EU frameworks is accelerating reformulation timelines for legacy nucleating agent categories without drop-in replacements.
- Application-Specific Certification:Divergent FDA food-contact notification pathways and Japan METI substance reporting requirements are fragmenting product registration strategies for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleating Agents Market |
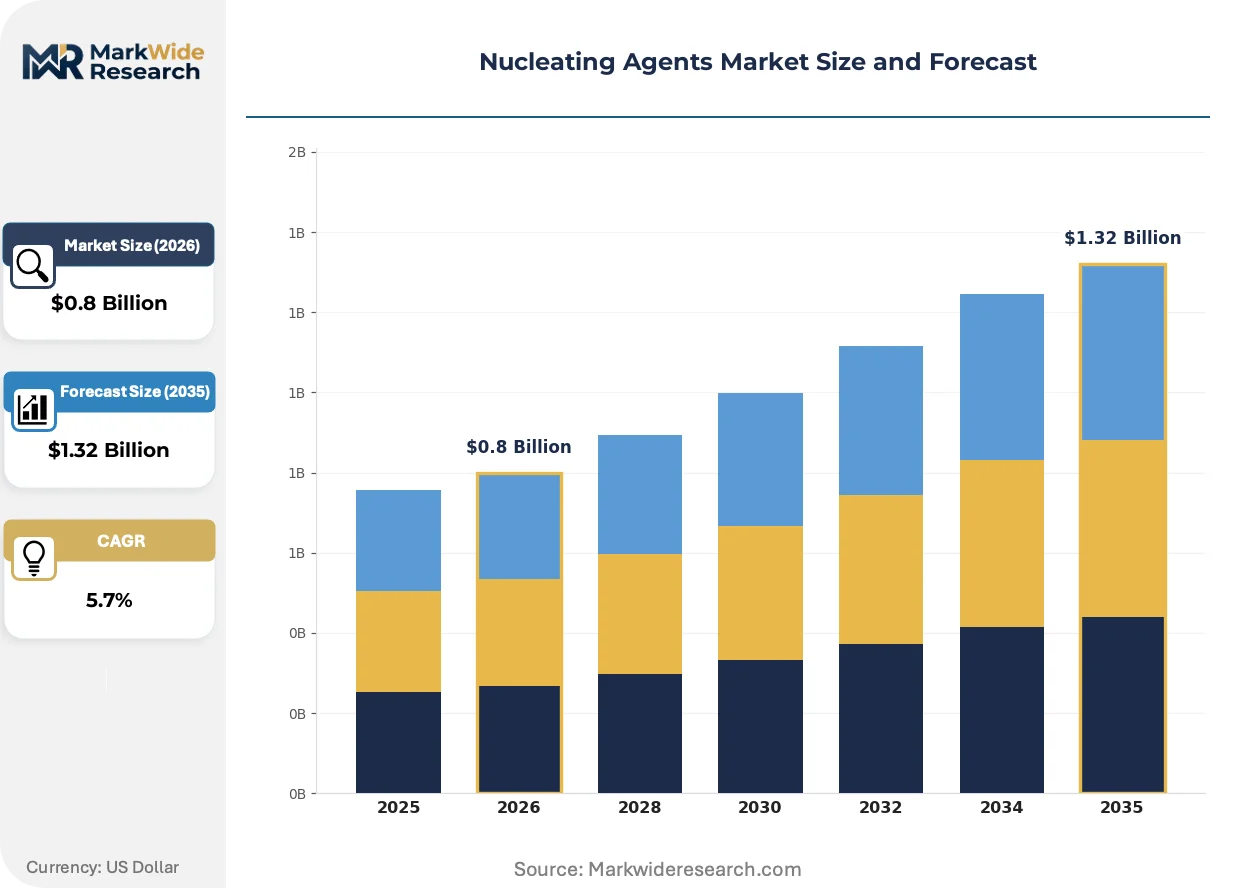
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.32 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Talc, Sodium Benzoate, Organic Nucleating Agents Application: Packaging, Textiles, Automotive Components, Consumer Goods End User: Food & Beverage, Pharmaceutical, Electronics, Construction Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Milliken & Company, ADEKA Corporation, BASF SE, Clariant AG, Imerys S.A., New Japan Chemical Co., Ltd., Avient Corporation, GCH Technology Co., Ltd., Shandong Rainwell New Materials Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleating Agents Market Strategic Shifts
Reformulation pressures around persistent chemistry restrictions are accelerating molecular innovation cycles, while compounding technology advances are redistributing value capture across the additive supply chain.
Non-sorbitol clarifying technologies are decentralizing optical performance improvement across polymer systems. Phosphate ester and carboxylate salt nucleating platforms are achieving clarity parity with legacy sorbitol derivatives in polypropylene random copolymers. Automotive lighting lens manufacturers and medical device molders are adopting these alternatives at compressed qualification cycles to preempt regulatory risk. This chemistry diversification is decentralizing supplier power away from incumbent clarifier portfolios and fragmenting specification standards across end-use verticals.
REACH authorization processes for novel molecular entities are compressing commercialization timelines for European market entry. ECHA's evolving data requirements for organophosphate chemistries are forcing parallel registration strategies across multiple jurisdictions. Food packaging converters in Germany and France are prioritizing pre-registered additive platforms to avoid supply discontinuity. The regulatory friction is advantaging suppliers with established dossier portfolios while constraining market access for emerging chemistry platforms.
Specification authority is migrating from compounders to brand-owner packaging designers who control optical performance targets. Direct engagement between nucleating agent suppliers and consumer goods companies is displacing traditional distributor-mediated technical sales in high-clarity applications. Converter procurement teams are unbundling additive specification from base resin purchasing to lock in multi-year clarifier supply agreements. This buyer-side consolidation is most visible in East China, where appliance OEMs are centralizing nucleating agent qualification across their molding supplier networks.
Nucleating Agents Market Segmentation
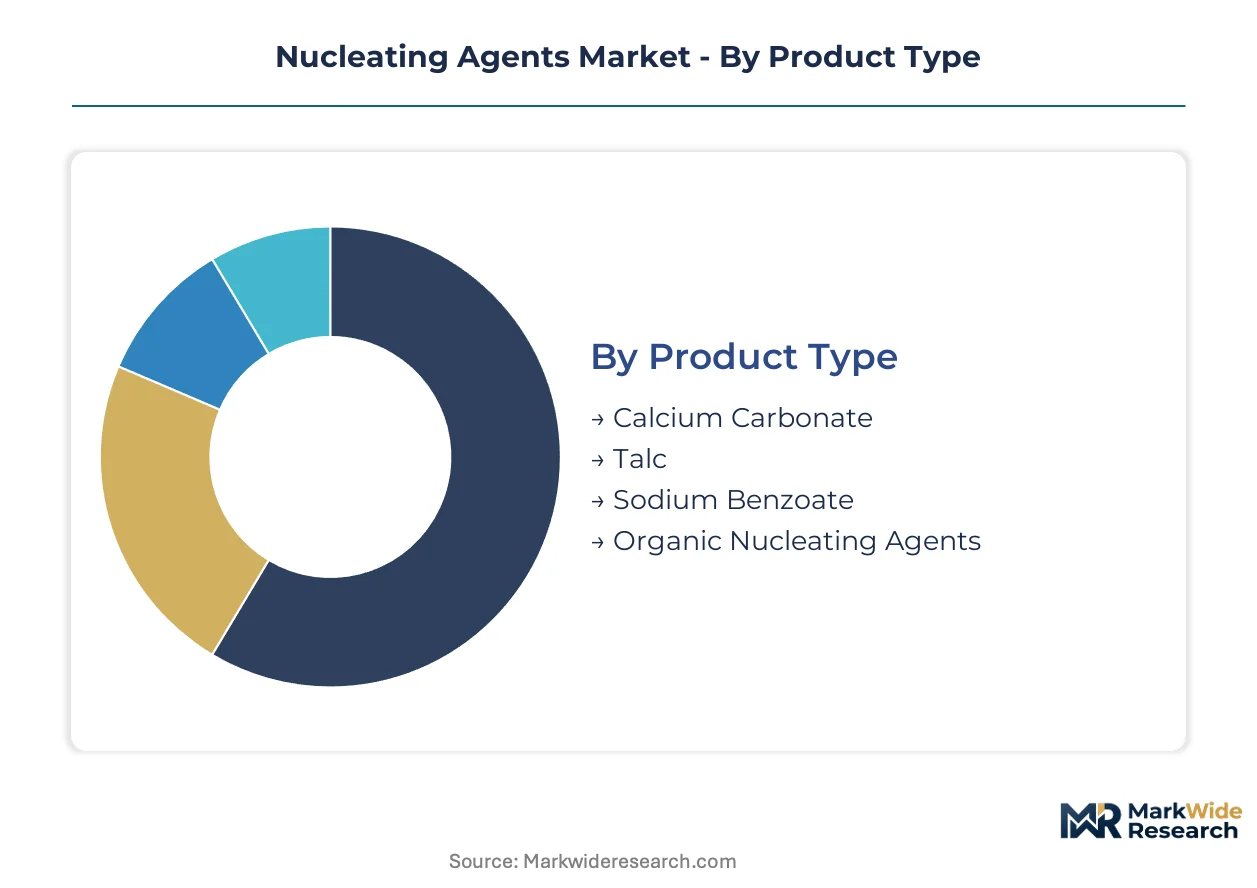
Nucleating agent selection hinges on crystallization kinetics, optical targets, and regulatory compliance rather than commodity substitution. Specification authority has migrated from resin suppliers to compounders and brand owners who unbundle additive procurement from base polymer purchasing. Each segmentation dimension carries distinct margin structures and technical service intensity.
Product Type:
Customization intensity spans from off-the-shelf mineral fillers to proprietary organic molecules requiring formulation support.
- Organic Nucleating Agents:Sorbitol derivatives and organophosphate salts achieve sub-5-micron spherulite sizes in polypropylene random copolymers. Demand concentrates in East China's Zhejiang province packaging clusters as GB 4806 food-contact standards tighten and converters seek clarity parity with amorphous polymers.
- Talc:Lamellar magnesium silicate dominates commodity volume where flexural modulus targets outweigh optical requirements. Specifications from appliance OEMs in Jiangsu province favor cost-minimized 5-10 micron grades for non-food-contact structural components.
- Calcium Carbonate:Precipitated and ground variants serve cost-sensitive applications with moderate nucleation efficiency and minimal clarity contribution.
- Sodium Benzoate:Carboxylate salt chemistry provides intermediate performance between mineral fillers and premium organics for polypropylene homopolymer systems.
Most installed capacity flows through Talc. Expansion is steepest in Organic Nucleating Agents.
Application:
Cycle time reduction and mechanical property targets vary sharply across molding processes and wall thickness requirements.
- Packaging:Thin-wall injection molded containers drive clarifying agent consumption as downgauging mandates maintain top-load strength at reduced material usage. Converter specifications in China's Yangtze River Delta prioritize heat deflection temperature alongside optical clarity for hot-fill dairy applications.
- Automotive Components:Underhood applications in glass-reinforced polyamide systems demand thermal stability beyond standard polypropylene nucleation. Engine-bay component suppliers specify phosphate ester chemistries to achieve crystallization acceleration without volatile emissions.
- Textiles:Fiber spinning applications utilize nucleating agents to control dye uptake and tensile property consistency in polypropylene multifilament.
- Consumer Goods:Appliance housings and furniture components balance aesthetic surface quality with stiffness requirements through talc-organic hybrid formulations.
Volume concentration sits with Packaging. Steepest specification upgrades are occurring in Automotive Components.
End User:
Regulatory exposure and certification burden fragment demand patterns across downstream verticals.
- Food & Beverage:Direct food-contact applications trigger FDA notification pathways and China's SAMR GB 4806 compliance requirements. Brand-owner packaging designers in East China centralize nucleating agent qualification across molding supplier networks to lock in multi-year clarifier supply agreements.
- Pharmaceutical:Medical device molders adopt non-sorbitol clarifying platforms at compressed qualification cycles to preempt regulatory risk from persistent chemistry scrutiny.
- Electronics:Connector and housing applications prioritize dimensional stability and warpage control in miniaturized components.
- Construction:Geotextiles and building materials emphasize UV stability and long-term mechanical retention over optical performance.
Certification complexity peaks in Food & Beverage. Procurement autonomy is expanding fastest in Pharmaceutical.
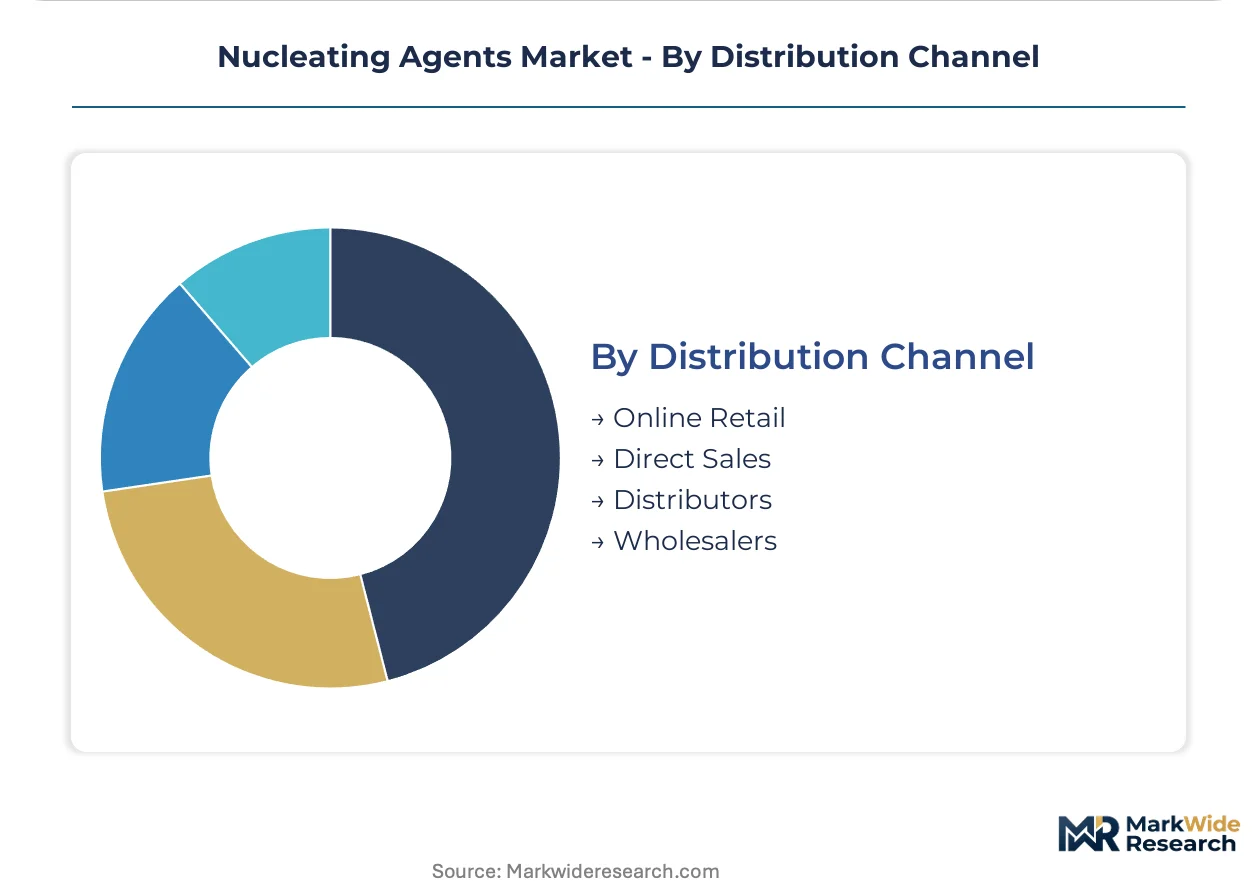
Distribution Channel:
Technical service requirements and batch size economics reshape channel selection across customer tiers.
- Distributors:Regional compounders and mid-tier converters rely on stocked inventory and localized technical support for standard nucleating agent grades. Zhejiang and Jiangsu polymer clusters maintain distributor relationships for just-in-time additive delivery.
- Direct Sales:Major packaging converters and automotive Tier-1 suppliers engage nucleating agent manufacturers directly for custom masterbatch formulations and joint development programs.
- Online Retail:Small-volume purchasers and research facilities source standard grades through digital platforms with limited technical consultation.
- Wholesalers:Bulk mineral fillers flow through traditional wholesale networks serving construction and commodity plastics processors.
Transaction volume concentrates through Distributors. Relationship intensity is deepening fastest in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nucleating agents industry traces its commercial origins to post-war polymerization advances in the United States and Germany, where early sorbitol derivatives first enabled polypropylene clarity improvements. Asian manufacturing expansion subsequently concentrated production capacity and converter demand in East Asian chemical clusters.
China
Packaging converters in Zhejiang and Jiangsu provinces are accelerating clarifying agent procurement as SAMR tightens GB 4806 food-contact enforcement timelines. The Yangtze River Delta polymer compounding belt now hosts the densest concentration of nucleating agent specification activity worldwide.
United States
Automotive underhood component suppliers specify phosphate ester chemistries for glass-reinforced polyamide systems requiring elevated heat deflection temperatures. FDA maintains 21 CFR notification requirements for food-contact nucleating agents, creating distinct compliance pathways from Asian regulatory frameworks.
Germany
ECHA's REACH authorization dossier requirements are consolidating supplier bases for novel organic chemistries entering European markets. The Rhineland chemical corridor houses compounders prioritizing pre-registered additive platforms to avoid supply discontinuity risks.
Japan
METI's chemical substance reporting framework elevates testing burdens for new molecular entities in automotive and medical device applications. Chubu region polymer processors are adopting non-sorbitol clarifying platforms at compressed qualification cycles to preempt regulatory risk.
India
Pending BIS harmonization of food-contact additive regulations is creating first-mover positioning opportunities for suppliers establishing local technical service infrastructure. Maharashtra and Gujarat polymer clusters are centralizing nucleating agent qualification across molding supplier networks.
Nucleating Agents Market Competitive Environment
The competitive structure tilts toward technology-integrated specialists with proprietary chemistry portfolios. Supplier concentration remains moderate, with distinct capability tiers separating mineral filler commodity providers from organic nucleating agent innovators. Two strategic archetypes dominate: vertically integrated chemical conglomerates with captive additive production, and focused specialty additive houses with dedicated polymer application laboratories. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure converter relationships ahead of regulatory compliance deadlines.
Among the specialty additive houses, Milliken & Company and ADEKA Corporation exemplify the technology-anchored archetype with established research campuses and regional production footprints. Clariant AG occupies a position within the diversified chemical group tier, leveraging masterbatch integration capabilities. BASF SE represents the scale-driven conglomerate model with broad polymer additive portfolios spanning multiple nucleating agent chemistries. These three players anchor distinct competitive vectors without exhaustive market coverage.
| Leading Market Players |
|---|
| Milliken & Company |
| ADEKA Corporation |
| BASF SE |
| Clariant AG |
| Imerys S.A. |
| New Japan Chemical Co., Ltd. |
| Avient Corporation |
| GCH Technology Co., Ltd. |
| Shandong Rainwell New Materials Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Japan and Germany anchor premium organic nucleating agent supply, their conservative balance-sheet discipline translating into pricing stability even as commodity mineral fillers erode margins elsewhere. This ownership pattern insulates clarifier portfolios from short-term cost pressures while concentrating supply leverage in legacy chemical clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments nucleating agent procurement by certification grade and volume commitment. Premium organophosphate salts command substantial markups over talc where FDA food-contact notification or GB 4806 compliance is mandatory. Cost compression in commodity mineral fillers is intensifying because polypropylene converters in Jiangsu province are unbundling additive specification from base resin purchasing. Small-volume research facilities exhibit highest price sensitivity, while appliance OEMs centralizing multi-year clarifier supply agreements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with organophosphate salt precursors concentrated in Japanese and Chinese chemical parks. Manufacturing draws from sorbitol derivatives, phosphate ester intermediates, and lamellar magnesium silicate feedstocks. Tariff exposure on US-China chemical trade routes threatens just-in-time delivery schedules for Zhejiang compounding clusters. Distribution runs through regional masterbatch compounders who blend nucleating agents with colorants for converter direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nucleating agents market compounds steadily as regulatory compliance deadlines force reformulation cycles across food-contact packaging. Polypropylene clarity mandates in automotive and appliance supply chains reinforce baseline demand.
For Market Incumbents: Deepen captive production of phosphate ester chemistries in East China to preempt supply discontinuity risks from REACH dossier delays. Anchor technical service teams directly inside Zhejiang appliance OEM procurement networks to lock specification authority before GB 4806 renewal peaks. Mineral filler substitution and emerging non-sorbitol clarifying platforms threaten legacy sorbitol derivative margins.
For New Entrants and Emerging Players: India's pending BIS harmonization of food-contact additive regulations opens a window for establishing local technical service infrastructure ahead of standardization enforcement. Target Maharashtra and Gujarat polymer clusters where centralizing nucleating agent qualification across molding supplier networks remains incomplete. Lead with masterbatch-integrated color-nucleant combinations that merge optical brightening with crystallization control.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional masterbatch compounders with captive nucleating agent blending capacity and established converter relationships. The five-to-ten-year viability window favors suppliers with pre-registered REACH dossiers and SAMR GB 4806 compliance documentation already filed. Watch for ECHA authorization timeline acceleration as the inflection signal for supplier base consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Ester Precursors | Secures supply continuity for clarifying agents ahead of REACH registration deadlines in Germany. |
| Masterbatch Integration with Optical Brightening | Captures specification share among East China brand-owner packaging designers unbundling additive procurement. |
| Joint Venture in India BIS Pre-Certification | Positions first-mover advantage before Maharashtra polymer clusters centralize nucleating agent qualification. |
| Long-Term Supply Agreement with Automotive Tier-1 | Locks volume commitments for glass-reinforced polyamide nucleating agents in underhood applications. |
| Green Manufacturing Transition for PFAS-Free Formulations | Preempts EPA and EU regulatory scrutiny accelerating substitution timelines for legacy nucleating agent categories. |
Study Parameters
Coverage spans China, the United States, Germany, Japan, and India, with primary inputs from each market's polymer compounding and converter base. The approach combines primary interviews with plant managers at Zhejiang and Jiangsu packaging converters, procurement leads at automotive Tier-1 suppliers, technical R&D directors at masterbatch compounders, and regulatory affairs specialists navigating FDA and SAMR pathways. Secondary validation draws from customs and trade data, SEC 10-K additive segment disclosures, ECHA registration dossier databases, and BIS draft standard notifications. Bottom-up volume modeling triangulates against top-down polymer consumption forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including organic versus mineral nucleating agent chemistry, packaging versus automotive versus textile application, food-contact versus industrial end-use, and direct sales versus distributor channel. CAGRs derive from fitted trend extrapolation adjusted for regulatory compliance deadline clustering. Industry-specific forecast inputs include polymer compounding capacity expansion schedules in the Yangtze River Delta and automotive lightweighting content-per-vehicle trajectories for glass-reinforced polyamide systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt PFAS restriction enforcement or sudden talc substitution acceleration. Forecasts reflect assumptions about regulatory timeline adherence and polymer converter inventory cycle behavior. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Refining Additives Market
Additives
Europe Feed Additives Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Tire Additives Market
Additives
Refinery Fuel Additives Market
Additives
Canada Water Enhancer Market
Additives
Viscosity Reducing Agents Market
Additives
Anti-Wear Additives Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Isobutyl Acetate Market
Additives
Fuel Additives Market
Additives
Bromine Derivatives Market
Additives
Tamarind Gum Derivatives Market
Additives
Stabilizers Market
Additives
Rheological Additives Market
Additives
Global Low-Profile Additive Market