
 Gluconic Acid and Derivatives Market | 2026-2036
Gluconic Acid and Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Gluconic Acid and Derivatives Market Foresight
Pharmaceutical manufacturing is expanding as the dominant demand vertical for gluconate derivatives, displacing traditional construction-grade sodium gluconate in margin contribution. Jungbunzlauer Suisse AG leverages its fermentation expertise to dominate European pharmaceutical-grade supply. Roquette Frères anchors its position through plant-based raw material sourcing and food-grade certification depth. Evonik Industries specializes in high-purity derivatives for injectable applications, competing on regulatory dossier completeness rather than volume.
Gluconic acid and its derivatives comprise organic compounds produced primarily via microbial fermentation of glucose, with sodium gluconate functioning as a biodegradable chelating agent effective at alkaline pH ranges. These substances serve industrial and commercial purposes spanning concrete retardation, pharmaceutical mineral supplementation, and food acidulation. Powder formulations command premium positioning in pharmaceutical and nutraceutical channels where dosing precision and shelf stability determine contract awards. Liquid solutions dominate concrete additive and industrial cleaning applications where bulk handling efficiency outweighs unit margin. The food and beverage segment remains mature with stable offtake, while personal care formulators are shifting toward zinc and potassium gluconates for antimicrobial and skin-conditioning claims.
EPA guidelines on green chemistry alternatives and REACH registration requirements in Europe are elevating compliance costs for non-fermentation synthetic routes, effectively advantaging biobased producers. FDA pharmaceutical-grade monographs for calcium and zinc gluconates enforce batch-level purity thresholds that filter out commodity chemical suppliers. China's NMPA and GB standards for food and pharmaceutical additives impose parallel testing protocols, creating a fragmented but tightening global regulatory mesh. Stakeholders must monitor fermentation feedstock cost volatility and evolving chelating agent restrictions in industrial wastewater discharge rules across multiple jurisdictions.
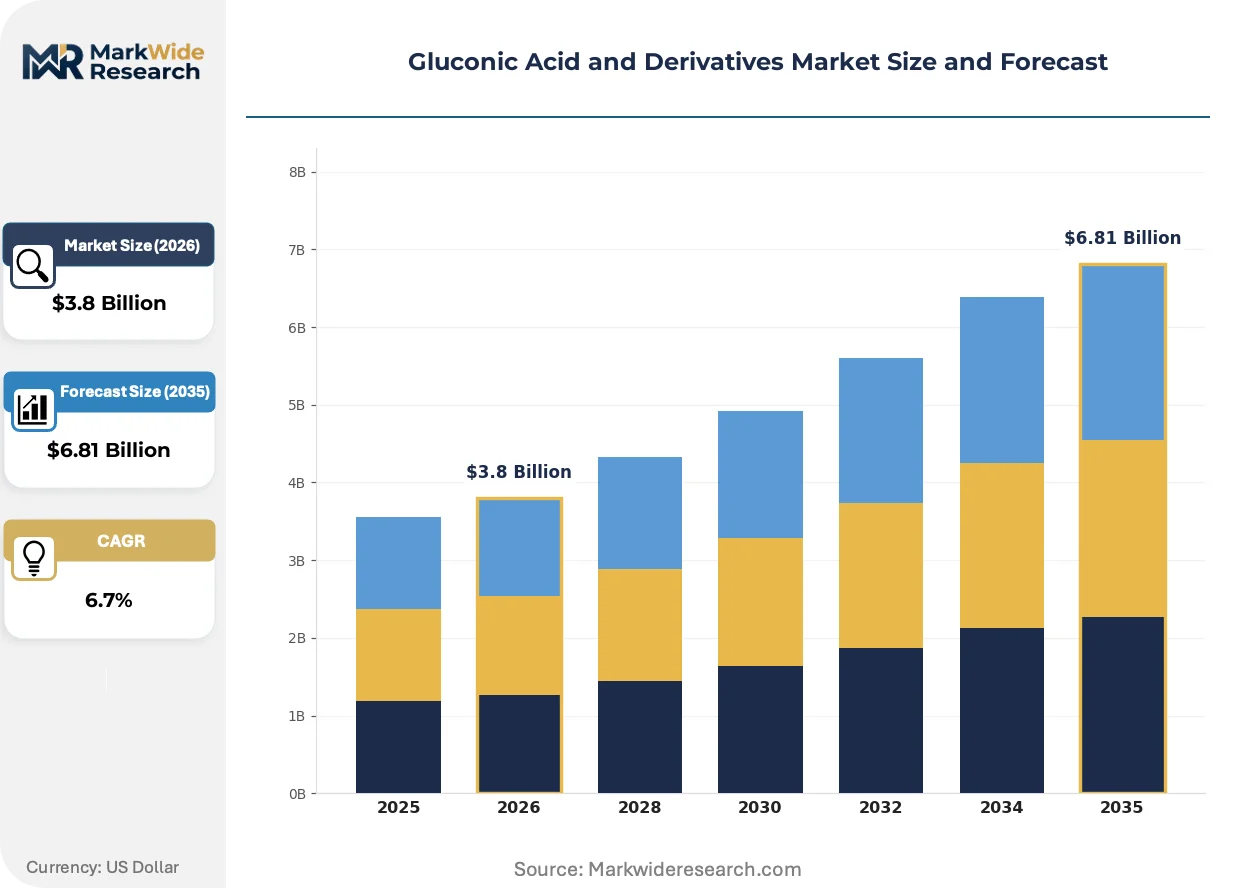
Market Dynamics
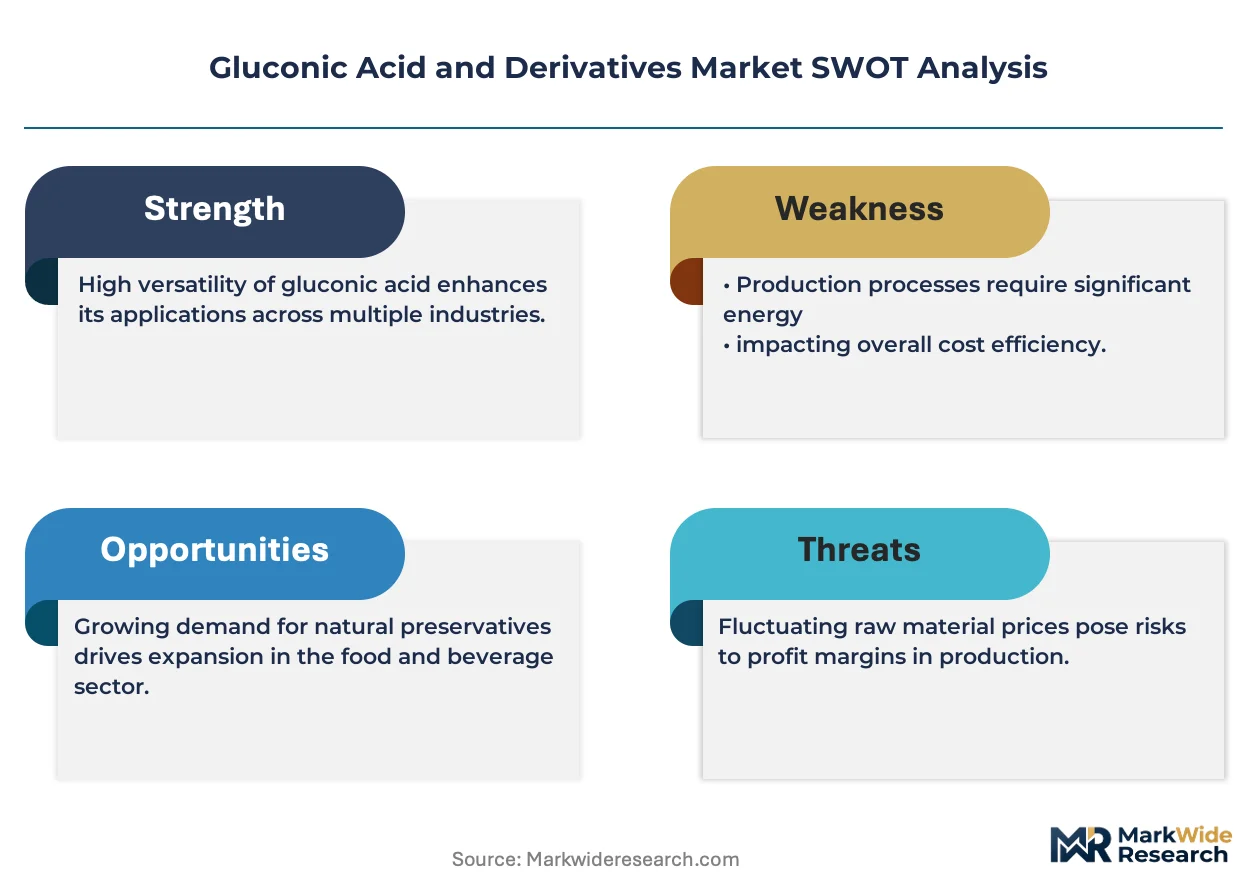
Pharmaceutical-grade fermentation capacity is tightening across Shandong, Basel, and Gujarat clusters as FDA, EMA, and NMPA purity standards converge, forcing commodity producers to either upgrade bioreactor infrastructure or exit injectable-grade supply chains entirely.
Growth Catalysts
- REACH green chelating mandates:EPA and ECHA rules on biodegradable alternatives are accelerating sodium gluconate substitution for EDTA in industrial cleaning and concrete retardation.
- Injectable mineral therapy expansion:Hospital formularies are expanding calcium gluconate and zinc gluconate use in critical care and parenteral nutrition protocols.
- China's dual carbon targets:Fermentation-based production in Shandong province receives preferential grid access and carbon credit treatment versus petrochemical routes.
Market Restraints
- Glucose feedstock volatility:Corn and wheat starch prices swing with drought cycles in US Midwest and Black Sea regions, compressing fermentation margins without pass-through clauses.
- Pharmaceutical-grade supply concentration:Three Swiss and German fermentation houses control over 70 percent of injectable-grade calcium gluconate API, creating single-source vulnerability for generic injectable manufacturers.
- Technical purity ceiling:Batch-to-batch endotoxin control below 0.5 EU per gram requires dedicated bioreactor lines that cannot pivot to food-grade output.
Strategic Opportunities
- Underpenetrated Brazilian agrochemical chelation:ANVISA is accelerating registration timelines for biodegradable complexing agents in micronutrient fertilizers.
- Personal care antimicrobial convergence:Zinc gluconate is displacing triclosan and parabens in European cosmetic formulations under ECHA biocide restrictions.
- US IRA green chemistry procurement:Federal purchasing mandates for biobased feedstocks are opening institutional channels previously locked by petrochemical incumbents.
Industry Challenges
- Pharmaceutical GMP compliance timeline:FDA and EMA batch release testing for calcium gluconate injectable now averages 14-18 weeks, straining working capital for mid-scale fermentation operators.
- Fermentation scale-up complexity:Moving from 50,000L to 200,000L bioreactor capacity requires strain optimization and contamination control expertise concentrated in Basel and Copenhagen technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluconic Acid and Derivatives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluconic Acid, Sodium Gluconate, Calcium Gluconate, Zinc Gluconate, Potassium Gluconate Application: Food & Beverage, Pharmaceuticals, Concrete Additives, Cleaning Agents, Personal Care End User Industry: Pharmaceutical Manufacturers, Construction Firms, Household Care Producers, Nutraceutical Companies, Cosmetic Formulators Form: Powder, Liquid, Granules, Crystals, Solution |
| Companies Covered | Merck KGaA, Roquette Frères, Jungbunzlauer Suisse AG, Evonik Industries, Tokyo Chemical Industry Co., Ltd, Archer Daniels Midland Company, Cargill Incorporated, FUSO Chemicals Co., Ltd, Shandong Xinhong Pharmaceutical Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluconic Acid and Derivatives Market Shifts & Advancements
Continuous fermentation monitoring via Raman spectroscopy and AI-driven metabolic flux analysis is compressing batch variability and enabling real-time purity prediction, fundamentally altering how pharmaceutical-grade gluconates achieve regulatory release.
Metabolic engineering of Aspergillus niger strains is rewriting yield economics for gluconic acid fermentation. CRISPR-edited strains with enhanced glucose oxidase expression are achieving titers above 180 grams per liter in pilot installations. Pharmaceutical contract manufacturers in Switzerland and Denmark are adopting these platforms to reduce downstream purification load and endotoxin risk.
EMA's updated excipient guidelines and FDA's process analytical technology (PAT) initiative are tightening documentation requirements for fermentation-derived mineral salts. Batch records must now include real-time viable cell counts and metabolite profiling. European API manufacturers are responding by integrating PAT sensors directly into production lines, while Asian suppliers face extended qualification timelines for export markets.
Hospital procurement consortia are consolidating mineral supplement purchasing through centralized pharmacy and therapeutics committees, displacing fragmented distributor relationships. Large US health systems and NHS Trusts in England are negotiating multi-year calcium gluconate supply agreements with fermentation houses holding complete regulatory dossiers. This concentration is visible most acutely in parenteral nutrition compounding, where formulary standardization reduces supplier counts to two or three qualified sources per network.
Gluconic Acid and Derivatives Market Segmentation
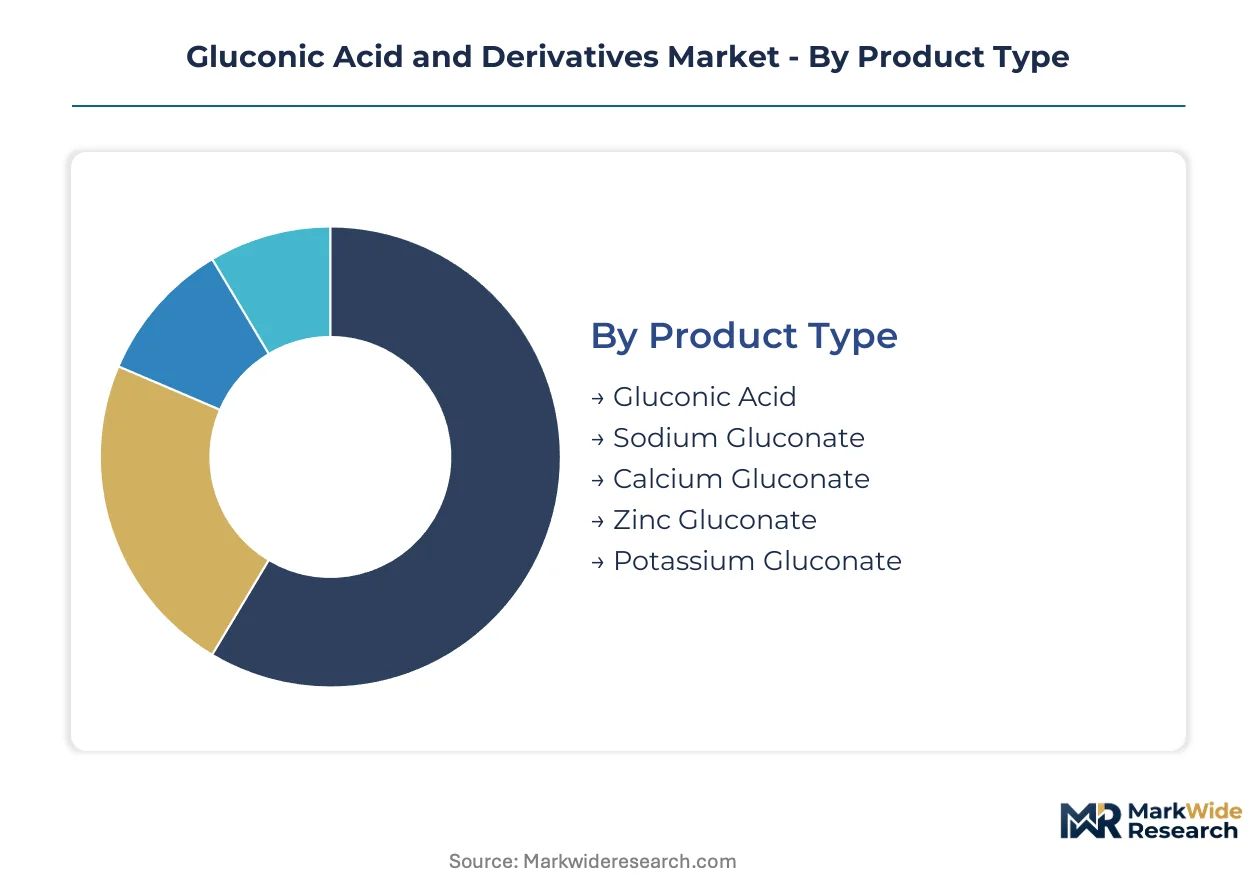
Gluconic acid derivatives span divergent purity grades and regulatory tiers, from commodity concrete retarders to endotoxin-controlled injectables. Segmentation reveals where capital requirements create defensive moats and where feedstock flexibility permits margin recovery.
Product Type:
Capital intensity peaks with pharmaceutical-grade mineral salts requiring dedicated bioreactor lines and endotoxin-controlled downstream processing. Sodium gluconate demands the lowest upfront investment, running on shared fermentation infrastructure with food-grade output.
- Gluconic Acid:The foundational fermentation output serves as chemical intermediate for downstream salt production and direct acidulant use in food processing. Demand concentrates in European and Chinese manufacturing clusters where REACH and GB standards enforce purity documentation for food contact applications.
- Sodium Gluconate:Concrete retardation and industrial chelation absorb the majority of volume, with construction-grade specifications tolerating higher impurity loads than pharmaceutical channels. Shandong fermentation houses dominate supply, leveraging preferential grid access under China's dual carbon targets to undercut petrochemical EDTA alternatives.
- Calcium Gluconate:Injectable-grade batches require 0.5 EU per gram endotoxin thresholds and 14-18 week FDA release timelines, filtering out commodity producers. Swiss and German fermentation specialists control the majority of qualified API supply for hospital formularies.
- Zinc Gluconate:Oral supplements and topical antimicrobial formulations drive offtake, with ECHA biocide restrictions accelerating displacement of triclosan in European personal care. Nutraceutical contract manufacturers in Denmark and Switzerland source from CRISPR-enhanced strain platforms.
- Potassium Gluconate:Parenteral nutrition compounding and electrolyte replacement therapies absorb pharmaceutical-grade volumes, while food-grade material fortifies sports beverages and clinical nutrition products.
Most installed capacity flows through sodium gluconate. Expansion is steepest in calcium gluconate.
Application:
Margin structure varies sharply across applications, with pharmaceutical and personal care commanding three-to-five-fold premiums over construction and industrial cleaning on a per-kilogram basis.
- Food & Beverage:Acidulant and preservative functions in processed foods, beverages, and dairy products. Mature demand profile with stable offtake from large-scale food manufacturers seeking clean-label alternatives to synthetic preservatives.
- Pharmaceuticals:Parenteral mineral supplementation, critical care electrolyte management, and generic injectable manufacturing. Hospital procurement consortia in the US and NHS Trusts in England are consolidating supplier relationships around fermentation houses with complete FDA and EMA dossiers.
- Concrete Additives:Retardation of cement hydration enables extended workability in high-temperature pours and complex formwork. Chinese construction activity absorbs the majority of regional sodium gluconate output, with BASF and Sika specifying biodegradable alternatives under green building certification schemes.
- Cleaning Agents:Industrial and institutional formulations leverage biodegradable chelation at alkaline pH ranges, with EPA green chemistry procurement mandates opening federal institutional channels previously locked by petrochemical incumbents.
- Personal Care:Zinc and potassium gluconates serve antimicrobial and skin-conditioning claims, with European cosmetic formulators pivoting rapidly under ECHA restrictions on traditional biocides.
Pharmaceutical applications capture the highest unit margins. Cleaning agents are gaining share fastest on regulatory substitution mandates.
End User Industry:
Customer concentration and qualification timelines create divergent sales cycle economics, with pharmaceutical manufacturers demanding 18-24 month vendor validation against spot-market purchasing by construction distributors.
- Pharmaceutical Manufacturers:Injectable-grade mineral salt procurement governed by FDA, EMA, and NMPA monographs with batch-level purity thresholds. Multi-year supply agreements with fermentation houses holding complete regulatory documentation are displacing fragmented distributor relationships.
- Construction Firms:Ready-mix concrete producers and specialty admixture blenders specify sodium gluconate for retardation in mega-project pours. Chinese state-owned construction enterprises anchor regional demand through centralized procurement of Shandong-sourced material.
- Household Care Producers:Industrial and consumer cleaning formulations specify biodegradable chelating agents under EPA Safer Choice and EU Ecolabel criteria. Large multinational formulators are consolidating supplier bases to reduce qualification overhead.
- Nutraceutical Companies:Oral mineral supplements and clinical nutrition products drive food-grade and pharmaceutical-grade offtake. Direct-to-consumer brands and contract manufacturers compete for qualified fermentation capacity.
- Cosmetic Formulators:European personal care manufacturers are accelerating zinc gluconate adoption as antimicrobial claims face ECHA biocide regulation tightening.
Pharmaceutical manufacturers absorb the majority of high-purity fermentation output. Cosmetic formulators are expanding most quickly on regulatory substitution.
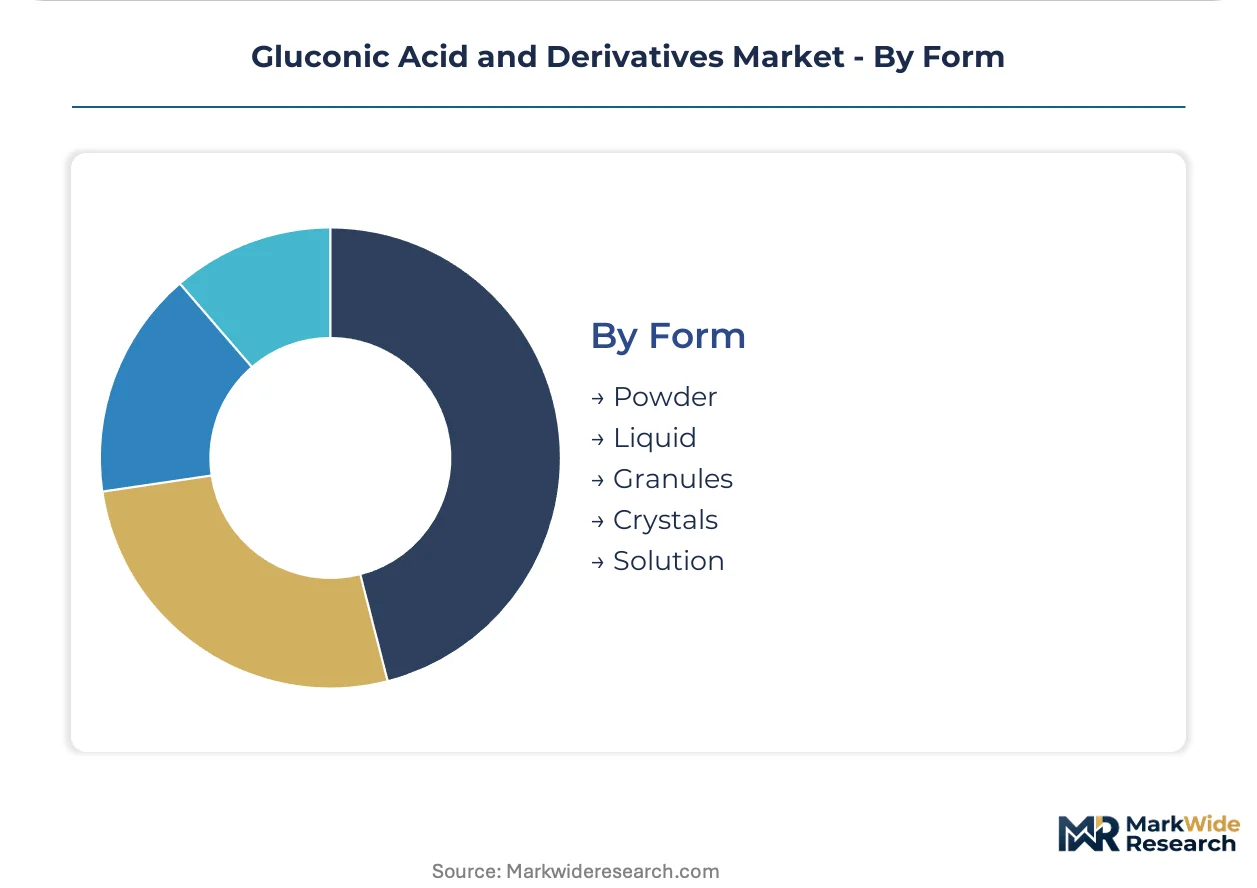
Form:
Physical form selection traces directly to handling economics and dosing precision requirements, with powders commanding packaging and stability premiums over bulk liquid solutions.
- Powder:Dosing precision and shelf stability determine contract awards in pharmaceutical and nutraceutical channels, with micronized grades specified for direct-compression tablet manufacturing.
- Liquid:Bulk handling efficiency dominates concrete additive and industrial cleaning applications where tanker delivery and automated dosing systems outweigh unit margin considerations.
- Granules:Intermediate flow properties serve food processing and agricultural chelation applications requiring dust-free handling and controlled dissolution rates.
- Crystals:High-purity crystalline grades meet pharmaceutical monograph specifications for visual clarity and dissolution profile consistency in parenteral formulations.
- Solution:Ready-to-use aqueous preparations reduce compounding complexity in hospital pharmacy and clinical nutrition settings, with endotoxin-controlled solutions specified for direct intravenous administration.
Most fermentation output ships as liquid or powder. Solution formats are climbing the fastest on hospital formulary standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as fermentation-based manufacturers migrate toward jurisdictions offering carbon credit treatment and streamlined pharmaceutical-grade certification. Cost-of-compliance gaps between REACH-governed Europe and China's dual carbon incentive zones now exceed 15 percent for bioreactor capex recovery timelines.
China
Shandong province hosts the densest concentration of sodium gluconate fermentation capacity globally, supplying construction-grade material to domestic mega-projects and export markets. NMPA pharmaceutical-grade standards and GB food additive protocols run parallel, creating dual-certification overhead for producers targeting hospital formularies. Qingdao and Jinan industrial clusters are expanding CRISPR-enhanced strain platforms to capture calcium gluconate API demand from Southeast Asian generic injectable manufacturers.
Germany
Specialized fermentation houses in the Rhine-Ruhr and Bavaria regions dominate injectable-grade calcium gluconate supply for EMA-regulated hospital networks. ECHA biocide restrictions on traditional antimicrobials are accelerating zinc gluconate offtake from cosmetic formulators in Hamburg and Düsseldorf. BASF's Ludwigshafen complex anchors industrial chelation demand, specifying biodegradable alternatives under EU Green Deal procurement mandates.
United States
EPA Safer Choice and IRA biobased procurement mandates are unlocking federal institutional channels previously controlled by petrochemical EDTA suppliers. Midwest corn-belt glucose feedstock proximity supports fermentation economics for cleaning agent manufacturers in Illinois and Ohio. FDA's 14-18 week batch release timelines for injectable-grade mineral salts favor established fermentation specialists with complete regulatory dossiers over commodity importers.
Switzerland
Basel's pharmaceutical fermentation cluster concentrates the highest-purity calcium gluconate API capacity for parenteral nutrition compounding across European hospital networks. Swissmedic's alignment with EMA excipient guidelines reduces qualification friction for export markets. Jungbunzlauer Suisse AG's fermentation expertise anchors regional supply, though capacity constraints are forcing generic injectable manufacturers toward multi-year contracting.
India
Gujarat and Maharashtra fermentation facilities are upgrading from food-grade to pharmaceutical-grade infrastructure to capture CDSCO-regulated hospital procurement. PLI scheme incentives for active pharmaceutical ingredients are offsetting bioreactor capex burdens for domestic producers. Mumbai and Ahmedabad clusters face extended FDA qualification timelines for export-grade calcium gluconate, constraining working capital for mid-scale operators.
Gluconic Acid and Derivatives Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation specialists race to install dedicated pharmaceutical-grade bioreactor lines before FDA and EMA purity standards fully converge. The vendor base separates into three functional tiers: Swiss-German specialists commanding injectable-grade premiums, Chinese scale producers absorbing construction-grade volume, and diversified chemical houses pivoting from petrochemical routes. Strategic archetypes include fermentation-purity specialists, agricultural-commodity integrators, and pharmaceutical-grade contract manufacturers. M&A activity concentrates on acquiring CRISPR strain platforms and endotoxin-controlled downstream assets, while geographic expansion targets Brazilian agrochemical and US federal procurement channels.
Among European fermentation specialists, Jungbunzlauer Suisse AG and Roquette Frères occupy positions defined by regulatory dossier depth rather than volume scale. Evonik Industries represents the pharmaceutical-grade contract manufacturing archetype, anchoring high-purity derivative supply for injectable applications. Shandong Xinhong Pharmaceutical Co., Ltd exemplifies the Chinese scale-producer model, leveraging provincial carbon credit treatment to undercut petrochemical alternatives in construction and industrial cleaning channels. Merck KGaA's diversified life sciences structure permits cross-divisional fermentation expertise transfer, while Archer Daniels Midland Company and Cargill Incorporated embody agricultural-commodity backward integration into glucose feedstock security.
| Leading Market Players |
|---|
| Merck KGaA |
| Roquette Frères |
| Jungbunzlauer Suisse AG |
| Evonik Industries |
| Tokyo Chemical Industry Co., Ltd |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| FUSO Chemicals Co., Ltd |
| Shandong Xinhong Pharmaceutical Co., Ltd |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in Shandong province and private-equity-rolled-up Swiss fermentation specialists anchor divergent pricing behaviors, with state-supported grid access and carbon credit treatment enabling aggressive spot-market positioning in construction-grade sodium gluconate while Basel-based houses maintain injectable-grade premiums through regulatory dossier scarcity.
Pricing Analysis
Distributor margins in pharmaceutical channels absorb the steepest compression as hospital procurement consortia consolidate supplier relationships around fermentation houses with complete FDA and EMA documentation. Three-tier pricing structure across injectable-grade, food-grade, and construction-grade levels stratifies by endotoxin thresholds and batch release timelines. Cost compression in construction-grade material is intensifying because Shandong fermentation clusters leverage preferential carbon credit treatment to undercut petrochemical EDTA alternatives. Ready-mix concrete producers exhibit the highest price sensitivity, while parenteral nutrition compounding pharmacies accept premium positioning for endotoxin-controlled supply security.
Supply Chain Analysis
Glucose feedstock supply rests on corn and wheat starch processors in the US Midwest, Black Sea regions, and Shandong agricultural belts, with fermentation economics tethered to drought-cycle volatility. Calcium carbonate for mineral salt conversion, pharmaceutical-grade filtration membranes, and CRISPR-edited Aspergillus niger strain licenses constitute critical input dependencies. Single-source vulnerability concentrates in Swiss-German injectable-grade API supply, where three fermentation houses control qualified output for generic injectable manufacturers. Distribution runs through regional chemical distributors for construction-grade material and direct long-term contracting for pharmaceutical-grade supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with hospital procurement consortia and EMA excipient guidelines forcing demand toward premium specifications that only dedicated pharmaceutical-grade fermentation infrastructure can satisfy.
For Market Incumbents: Acquire CRISPR-enhanced strain platforms and endotoxin-controlled downstream assets to defend against emerging Chinese producers upgrading from food-grade to pharmaceutical-grade infrastructure. Deepen backward integration into glucose feedstock security through agricultural-belt offtake agreements or captive corn-processing capacity, insulating margins from Midwest drought-cycle volatility that compresses fermentation economics without pass-through clauses. For New Entrants and Emerging Players: Continuous fermentation monitoring via Raman spectroscopy and AI-driven metabolic flux analysis offers a technology-first wedge into pharmaceutical contract manufacturing services, where mid-scale operators lack capital for PAT sensor integration. Brazilian agrochemical chelation under ANVISA's accelerating registration timelines for biodegradable complexing agents represents the most penetrable white-space geography, with micronutrient fertilizer formulators seeking alternatives to EDTA. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fermentation operators in Gujarat and Maharashtra facing extended FDA qualification timelines for export-grade calcium gluconate, creating distressed capability acquisition opportunities. The long-term viability framing centers on regulatory dossier completeness as the scarcest asset across the projection horizon. Watch for EMA-FDA purity standard convergence as the inflection trigger that forces commodity producers to exit injectable-grade supply chains entirely.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Installation of dedicated pharmaceutical-grade bioreactor lines before EMA-FDA standards fully converge secures qualified supply position for hospital procurement consortia. |
| Backward Integration | Upstream control over glucose feedstock through agricultural-belt offtake agreements insulates fermentation margins from corn and wheat starch price volatility. |
| Green Manufacturing Transition | CRISPR-edited Aspergillus niger strain platforms reduce downstream purification load and endotoxin risk, compressing batch variability through real-time purity prediction. |
| Long-term Supply Agreement | Multi-year calcium gluconate contracts with NHS Trusts and US health systems displace fragmented distributor relationships, locking in qualified API volume. |
| Joint Venture | Partnerships with Brazilian agrochemical formulators accelerate ANVISA registration for biodegradable chelating agents in micronutrient fertilizers. |
Research Methodology
Multiple input streams — fermentation plant managers, pharmaceutical procurement leads at hospital systems, regulatory affairs directors, and downstream construction admixture blenders — were reconciled against customs and trade data, SEC filings from diversified chemical houses, and NMPA pharmaceutical-grade registration databases. Primary interviews with Swiss and German fermentation specialists, Shandong provincial industrial cluster officials, and Gujarat facility operators were cross-validated through bottom-up capacity modeling and top-down demand segmentation across purity grades and end-use applications.
Historical shipment volumes from fermentation houses were cross-referenced against panel input from formulary directors and GPO contracts managers to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type tier, application margin structure, end-user industry concentration, and physical form handling economics, with CAGRs derived from strain yield improvement trajectories and regulatory substitution elasticity for green chelating agents.
The model holds under stable glucose feedstock pricing and converging FDA-EMA purity standards; deviation in corn-belt drought severity or NMPA export certification timelines would shift capacity expansion schedules and working capital requirements for mid-scale operators. A small set of named triggers — ECHA biocide restriction enforcement, US IRA biobased procurement mandate expansion, and CRISPR strain platform licensing accessibility — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Material Shrinkage-reducing Agents Market
Additives
Pearlizers Market
Additives
Antimicrobial Additives Market
Additives
China Feed Additives Market
Additives
Global Sodium Acetate Market
Additives
Europe Citric Acid Market
Additives
Defoaming Coating Additives Market
Additives
Ammonium Acetate Market
Additives
Gasoline Additives Market
Additives
Global Pearlizing Agent Market
Additives
Octane Improver Fuel Additives Market
Additives
Global Butyric Acid Derivatives Market
Additives
Silage Additives Market
Additives
1,4 Butanediol Derivatives Market
Additives
Dipotassium Guanylate Market
Additives
Low Volatile Organic Compounds Coating Additives Market