
 Defense Optronics Market | 2026-2036
Defense Optronics Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Optronics Market Insights
ISO 9001 and AS9100D certification cycles for defense suppliers is collapsing the vendor landscape, favoring primes with established audit trails. Lockheed Martin leverages captive semiconductor fabrication for focal plane arrays, insulating its thermal imaging supply chain from export control volatility. BAE Systems anchors European optronics production through its Glasgow and Rochester facilities, sustaining sovereign capacity independent of transatlantic component flows. Elbit Systems specializes in helmet-mounted display integration, competing directly with Thales Group for NATO pilot vision system contracts.
Defense optronics encompasses electro-optical and infrared systems engineered for detection, identification, and targeting in contested electromagnetic environments, typically operating across 0.4 to 14 micrometer spectral bands with cooled indium antimonide or mercury cadmium telluride detector materials. These systems serve military end users by converting photonic energy into actionable intelligence under degraded visibility conditions including night, smoke, and electronic warfare interference. Thermal imaging now leads product type revenue generation due to uncooled microbolometer cost reductions, while multispectral sensors represent the fastest-expanding technology segment as forces demand fused visible-SWIR-MWIR data streams for positive identification at extended ranges. Heads-up displays command premium margins within military aviation applications, though night vision persists as the highest-volume product category across ground forces procurement programs.
FDA export documentation requirements intersect with ITAR-controlled thermal imager shipments, creating dual-compliance friction for US-origin focal plane arrays destined for allied militaries. The EU AI Act's risk classification framework is forcing recalibration of autonomous targeting algorithms embedded in Thales and Leonardo sensor packages sold to European defense ministries. Stakeholders must monitor divergence between US ITAR reform timelines and EU strategic autonomy initiatives, as misalignment threatens to fragment supplier certification regimes and strand development investments on either side of the Atlantic.
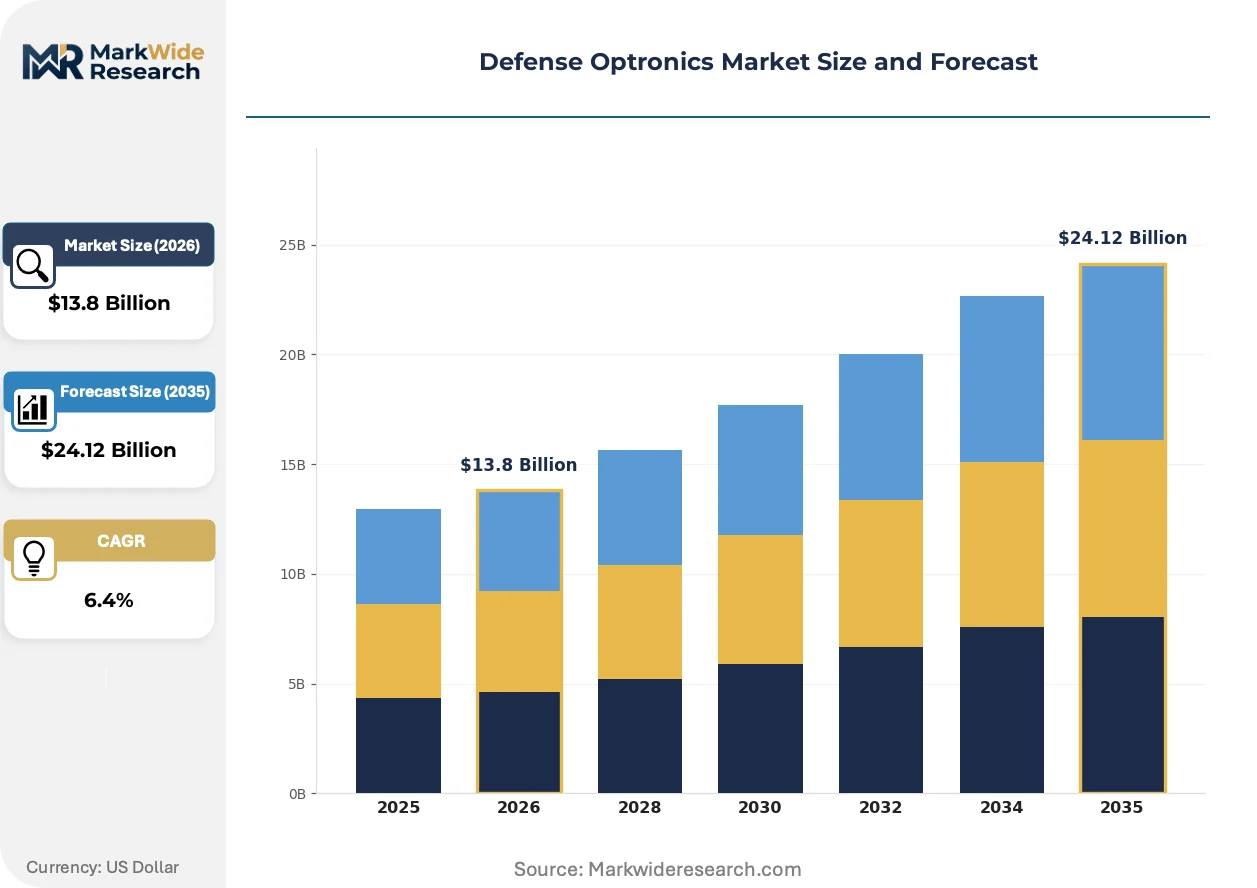
Market Dynamics
Defense optronics procurement is tightening around cybersecurity-certified supply chains, with ITAR reform timelines and EU strategic autonomy initiatives creating divergent qualification regimes that compress vendor eligibility and reshape competitive positioning.
Growth Catalysts
- Multispectral sensor demand:NATO forces are accelerating procurement of fused visible-SWIR-MWIR data streams for positive identification at extended ranges.
- Indo-Pacific theater preparedness:Sustained defense modernization budgets in the United States are concentrating investment in thermal imaging and helmet-mounted display systems.
- EU AI Act risk classification:European defense ministries are recalibrating autonomous targeting algorithms, generating replacement demand for compliant sensor packages.
Market Restraints
- Indium antimonide supply concentration:Cooled detector materials depend on limited semiconductor fabrication capacity subject to export control volatility.
- Dual-compliance friction:FDA export documentation intersects with ITAR-controlled thermal imager shipments, stranding focal plane arrays in customs.
- Uncooled microbolometer substitution:Cost reductions in uncooled alternatives are compressing margins for legacy cooled detector architectures.
Strategic Opportunities
- Helmet-mounted display integration:Aviation applications command premium margins as pilots demand fused sensor-to-display data pipelines.
- AS9100D certification concentration:Collapsing vendor qualification cycles favor primes with established audit trails, consolidating market share among prepared suppliers.
- Mercury cadmium telluride convergence:Advanced detector materials paired with AI-driven image processing are opening extended spectral band applications.
Industry Challenges
- ISO 9001 audit timeline compression:Defense contractors face truncated certification cycles that strain quality management system documentation.
- Legacy system integration complexity:New multispectral suites must interface with existing battlefield networks, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Optronics Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Night Vision, Thermal Imaging, Image Intensifiers, Heads-Up Displays Application: Surveillance, Target Acquisition, Reconnaissance, Battlefield Situational Awareness Technology: Focal Plane Arrays, Multispectral Sensors, RFID Systems, Laser Range Finders End User: Military Forces, Law Enforcement Agencies, Defense Contractors, Security Services |
| Companies Covered | Lockheed Martin Corporation, BAE Systems, Thales Group, Northrop Grumman Corporation, Raytheon Technologies Corporation, L3Harris Technologies, Inc., Elbit Systems Ltd., Leonardo S.p.A., FLIR Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Optronics Market Trends and Innovations
Defense optronics is pivoting toward uncooled architectures and AI-embedded processing, with regulatory divergence between Washington and Brussels fragmenting supplier certification regimes and forcing parallel development tracks.
Uncooled microbolometer arrays are supplanting cooled indium antimonide detectors in ground-force thermal imaging applications. Army procurement programs are adopting these sensors for squad-level targeting systems. The shift is compressing unit costs while extending operational readiness in contested electromagnetic environments.
EU AI Act risk classification frameworks are forcing recalibration of autonomous targeting algorithms embedded in sensor packages. European defense ministries now mandate human-in-the-loop verification for lethal decision chains. Thales and Leonardo are redesigning software architectures to satisfy these constraints ahead of contract renewals.
Outcome-based maintenance contracts are displacing traditional spares-and-repair arrangements in NATO aviation programs. Prime contractors retain sensor fleet performance liability, shifting operational risk upstream. This model is concentrating in the United States and United Kingdom fighter modernization budgets.
Defense Optronics Market Segmentation
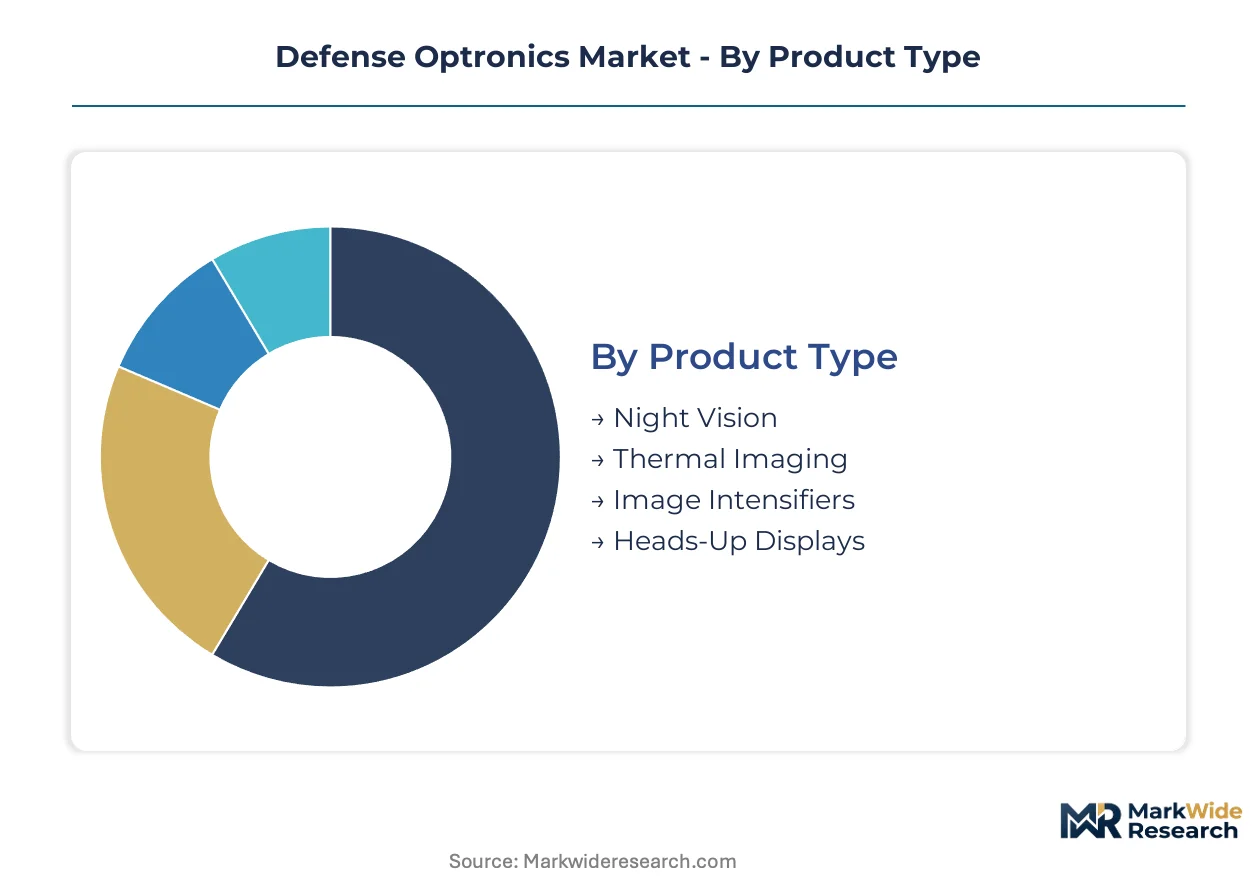
Defense optronics segmentation reveals how substitution pressures and certification barriers reshape procurement patterns across sensor architectures. Understanding these divides exposes where vendor consolidation concentrates and where new entrants find technical footholds.
Product Type:
Uncooled microbolometer advances are compressing demand for legacy cooled architectures, with substitution pressure falling hardest on high-maintenance detector categories.
- Thermal Imaging:Uncooled microbolometer arrays now dominate ground-force procurement, cutting unit costs while extending operational readiness in electronic warfare environments. US Army squad-level targeting systems are standardizing on these sensors for contested electromagnetic theaters.
- Heads-Up Displays:Helmet-mounted systems command premium margins in fighter modernization programs, with NATO pilot vision contracts driving fused sensor-to-display data pipeline development. Aviation applications sustain the highest per-unit pricing across military end uses.
- Night Vision:Image intensifier tubes persist as the highest-volume category in ground forces procurement despite thermal substitution pressures.
- Image Intensifiers:Legacy photocathode technologies face declining procurement share as thermal fusion becomes standard in new soldier systems.
Thermal imaging anchors the volume base while heads-up displays gain share at the steepest rate.
Application:
Cost tier stratification separates high-investment airborne programs from mass-fielded ground systems, with middleware complexity driving margin differentiation.
- Battlefield Situational Awareness:Multispectral sensor suites fusing visible-SWIR-MWIR data streams now represent the primary procurement priority for NATO force modernization. Extended-range positive identification requirements are accelerating fused architecture adoption across mechanized units.
- Target Acquisition:Laser range finder integration with thermal cores is concentrating investment in precision fires support, with fire control system upgrades driving replacement cycles in US and European artillery programs.
- Surveillance:Persistent stare requirements in Indo-Pacific theater preparedness are sustaining demand for cooled long-wave infrared systems on aerial platforms.
- Reconnaissance:Unmanned platform payload miniaturization is compressing sensor size-weight-power constraints for special operations forces.
Battlefield situational awareness anchors the volume base while target acquisition climbs the fastest.
Technology:
Supply concentration in semiconductor fabrication creates chokepoints for focal plane array availability, with detector material sourcing determining competitive access.
- Focal Plane Arrays:Indium antimonide and mercury cadmium telluride detector materials operate across 0.4 to 14 micrometer spectral bands, with cooled architectures dependent on limited foundry capacity subject to ITAR export controls. Captive fabrication at primes is insulating supply chains from volatility.
- Multispectral Sensors:Fused visible-SWIR-MWIR architectures are expanding fastest as forces demand positive identification at extended ranges, with AI-driven image processing opening new spectral band applications.
- Laser Range Finders:Eye-safe wavelength standards are recalibrating procurement specifications across NATO target designation programs.
- RFID Systems:Asset tracking integration with maintenance databases is supporting outcome-based fleet management contracts.
Focal plane arrays anchor the volume base while multispectral sensors expand most quickly.
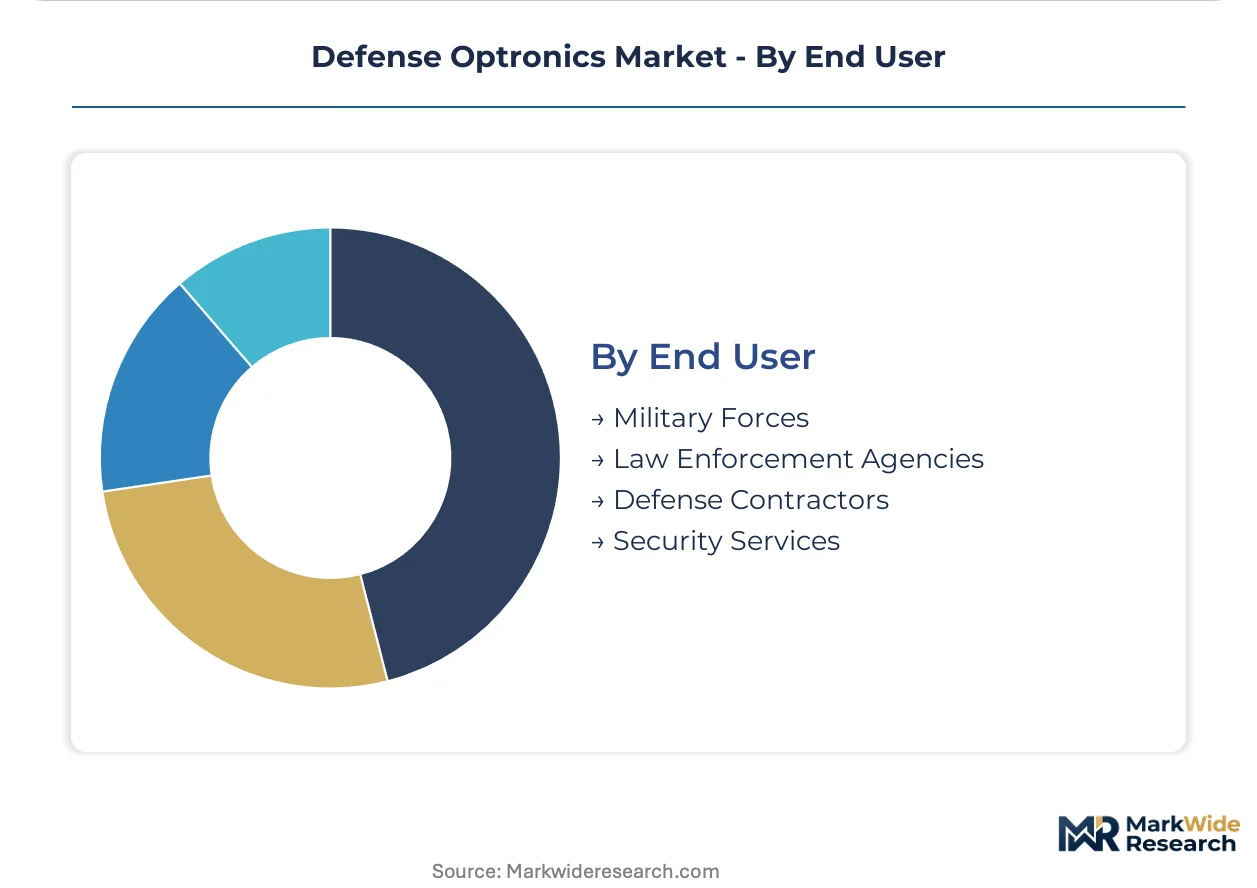
End User:
Customer type determines certification burden intensity, with defense contractor qualification cycles collapsing faster than military direct procurement timelines.
- Military Forces:Direct procurement by armed services sustains the highest absolute spending, with US Department of Defense cybersecurity certification requirements reshaping supplier qualification protocols and compressing vendor eligibility.
- Defense Contractors:Primes with established AS9100D audit trails are consolidating subcontractor tiers, with ISO 9001 timeline compression favoring incumbents over new market entrants.
- Law Enforcement Agencies:Thermal imager procurement faces dual-compliance friction between FDA export documentation and ITAR controls.
- Security Services:Critical infrastructure protection applications are adopting surplus military specifications with reduced performance thresholds.
Military forces anchor the volume base while defense contractors gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense modernization budgets and sovereign capacity initiatives are reshaping procurement patterns across NATO member states and Indo-Pacific allies. National security strategies now prioritize resilient supply chains for focal plane arrays and thermal imaging components. Certification divergence between Washington and Brussels is fragmenting vendor qualification regimes.
United States
Indo-Pacific theater preparedness drives sustained investment in multispectral sensor suites and helmet-mounted displays for fighter modernization. The Department of Defense's tightening cybersecurity certification requirements compress vendor eligibility timelines. Arizona and Florida host concentrated primes with established AS9100D audit trails insulating thermal imaging supply chains from export control volatility.
United Kingdom
Royal Air Force and Royal Navy programs sustain demand for cooled long-wave infrared systems on aerial platforms. UK strategic defense reviews emphasize sovereign optronics production independent of transatlantic component flows. Glasgow and Rochester anchor BAE Systems' European manufacturing footprint for focal plane array integration.
Germany
Bundeswehr mechanized unit modernization accelerates procurement of fused visible-SWIR-MWIR architectures for extended-range positive identification. EU AI Act risk classification frameworks mandate human-in-the-loop verification for autonomous targeting algorithms. Bavaria and Baden-Württemberg concentrate subsystem integrators serving NATO pilot vision system contracts.
France
DGA procurement priorities emphasize outcome-based maintenance contracts displacing traditional spares-and-repair arrangements in fighter programs. Thales Group anchors national capacity for helmet-mounted display integration competing for NATO aviation contracts. Île-de-France and Provence-Alpes-Côte d'Azur host prime contractors recalibrating sensor software architectures ahead of contract renewals.
Israel
Defense export licensing frameworks support specialized helmet-mounted display integration for allied pilot vision systems. IDF operational requirements drive miniaturized unmanned platform payload development for special operations forces. Central Israel concentrates Elbit Systems' production capacity for night vision and thermal fusion soldier systems.
Defense Optronics Market Competitive Landscape
Player mix skews toward vertically integrated defense primes with captive semiconductor fabrication and established certification audit trails. Market structure concentrates around aerospace conglomerates with sovereign production mandates and mid-tier specialists in helmet-mounted display integration. Two archetypes dominate: scale-driven primes with backward integration into focal plane arrays, and niche integrators competing on rapid customization cycles. Competitive moves center on AS9100D certification pre-emption and outcome-based fleet performance contracting.
Among US-based primes, Lockheed Martin and Northrop Grumman exemplify the scale-driven archetype with in-house detector material production. Thales Group represents the European sovereign capacity model with Glasgow and Rochester anchoring transatlantic supply chain resilience. Elbit Systems occupies a specialist position in helmet-mounted display integration competing directly for NATO aviation contracts. These three named entities illustrate how geographic certification divergence and production sovereignty reshape competitive positioning across the Atlantic.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems |
| Thales Group |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| L3Harris Technologies, Inc. |
| Elbit Systems Ltd. |
| Leonardo S.p.A. |
| FLIR Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
AS9100D certification cycles gate both supplier qualification and price differentiation simultaneously, compressing vendor eligibility timelines while concentrating pricing power among primes with established audit trails. This regulatory barrier creates tiered cost structures where certified incumbents command substantial premiums over uncertified challengers struggling to penetrate defense procurement channels.
Pricing Analysis
Certification level (ISO/AS9100D-grade) creates the primary spread across defense optronics procurement, with three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to human-in-the-loop verified sensor packages for NATO aviation contracts, while standard tiers serve ground-force thermal imaging programs. Cost compression in uncooled microbolometer arrays is intensifying because of manufacturing scale efficiencies in commercial infrared markets. Law enforcement agencies exhibit highest price sensitivity due to budget constraints, whereas fighter modernization programs demonstrate least sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Inventory lead times for cooled indium antimonide focal plane arrays have extended substantially, with foundry capacity constraints creating procurement bottlenecks for prime contractors. Supply concentrates in the United States, Israel, and France for detector material fabrication, with each nation maintaining sovereign production mandates. Raw material dependencies center on mercury cadmium telluride substrates, germanium optics, and specialized semiconductor packaging. Single-source vulnerability pervades cooled detector architectures where limited foundry capacity faces ITAR export restrictions. Distribution runs through prime contractor integration facilities with direct military procurement representing the dominant downstream channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense optronics fragmentation creates entry opportunities as divergent NATO and EU regulatory frameworks splinter vendor qualification regimes, generating specialized niches for compliance-focused specialists.
For Market Incumbents: Compound certification advantages by accelerating AS9100D pre-emption across subcontractor tiers before EU strategic autonomy initiatives harden alternative qualification pathways. Lockheed Martin's captive semiconductor fabrication model demonstrates how backward integration into focal plane arrays insulates against export control volatility threatening uncooled microbolometer substitution pressures. Primes should extend outcome-based maintenance contracting to shift operational risk downstream while capturing recurring revenue streams. For New Entrants and Emerging Players: Differentiate on rapid AI-embedded image processing customization for European defense ministries recalibrating autonomous targeting algorithms under EU AI Act constraints. White-space targets include middleware development for legacy system integration complexity and helmet-mounted display subcomponent supply to primes lacking rapid customization cycles. Law enforcement thermal imager procurement represents the most penetrable segment given dual-compliance friction stranding established suppliers. A direct contracting angle with national procurement offices bypasses prime-tier consolidation. For Investors and Strategic Acquirers: ITAR reform timelines reshaping Washington's export control posture alter the acquisition landscape, with timing-sensitive deployment of capital ahead of regime clarity offering asymmetric returns. Long-term viability centers on platforms with demonstrated sovereign production capacity across multiple NATO member states rather than single-jurisdiction dependencies. Acquisition target archetype: mid-tier specialists with established EU AI Act compliance pathways and existing helmet-mounted display integration contracts. The signal to watch is divergence between US and EU cybersecurity certification reciprocity negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Focal Plane Array Fabrication | Lockheed Martin's in-house detector production insulates thermal imaging supply chains from ITAR volatility. |
| EU AI Act Compliance Recalibration | Thales and Leonardo sensor software redesigns ahead of contract renewals capture replacement demand from European ministries. |
| Outcome-Based Maintenance Contracting | Prime retention of sensor fleet performance liability concentrates risk upstream in US and UK fighter programs. |
| Helmet-Mounted Display Integration | Elbit Systems' specialization in pilot vision systems competes directly with Thales for NATO aviation contracts. |
| Multispectral Sensor Architecture Development | Fused visible-SWIR-MWIR data streams address extended-range positive identification requirements in Indo-Pacific theater preparedness. |
Research Methodology
The analysis maps thermal imaging, helmet-mounted displays, night vision systems, and multispectral sensors, each validated through defense procurement officers, prime contractor program managers, focal plane array foundry engineers, and military end-user feedback. Primary interviews with subsystem integrators and semiconductor fabrication specialists combined with secondary validation from Department of Defense budget justifications, NATO procurement databases, EU defense equipment directives, and customs export records. Bottom-up unit economics triangulated against top-down defense modernization budget allocations across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including defense procurement disclosure filings and national strategic defense review commitments. The analytical framework modeled product type, application, technology, and end-user segments across the projection horizon, with CAGRs derived from deployment schedule phasing and replacement cycle assumptions. Industry-specific forecast inputs included squad-level targeting system fielding timelines and fighter modernization program sensor upgrade schedules.
The analysis sits within stated boundaries; outcomes outside sustained Indo-Pacific theater preparedness budgets or ITAR-EU regulatory reciprocity agreements would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and uncooled microbolometer cost trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Automotive LED Lighting Market
Others
Smart Home Service Market
Others
Smart Home Gateways Market
Others
Middle East and Africa Surface Analysis Market
Others
Smart Home Market
Others
Europe Battery Packaging Market
Others
North America Micro Market
Others
United States Cigarette Market
Others
Inorganic Tin Chemicals Market
Others
Palatants Market
Others
Asia-Pacific Air Separation Unit Market
Others
US Mobile MRI Services Market
Others
Asia-Pacific B2B Legal Services Market
Others
Global Duty-Free Retailing Market
Others
Qatar Smartphone Market
Others
Football Sportswear Market