
 Smart Badge Market | 2026-2036
Smart Badge Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Badge Market Outlook
The gap between premium biometric badges and commodity RFID cards is restructuring procurement patterns across enterprise security budgets. IDEMIA leverages its government ID heritage to anchor high-assurance credential programs. Thales Group competes through chip-level encryption specialization. Zebra Technologies Corp. dominates mobile-computing-integrated badge workflows in logistics environments.
A smart badge is a portable credential device embedding wireless transponders, secure elements, or biometric sensors to authenticate identity and authorize physical or digital access. Units typically operate at 13.56 MHz for NFC protocols or 860-960 MHz for UHF RFID, with read ranges from contact to twelve meters depending on antenna configuration. Bluetooth badges and biometric badges command the strongest margin pools as enterprises trade up from basic proximity cards. Healthcare facilities and event organizers represent the fastest-growing end-user verticals, driven by infection-control protocols and dynamic attendee tracking requirements.
FCC Part 15 governs unlicensed radio emissions for badges sold in the United States, while GDPR and the EU AI Act impose strict biometric data retention limits across European deployments. The FDA regulates badges with integrated health sensors in clinical settings, requiring IEC 60601-1-2 electromagnetic compatibility certification. Buyers must weigh interoperability standards against vendor lock-in as cloud-connected badge architectures proliferate.
Market Dynamics
The EU AI Act's biometric data retention limits are forcing badge manufacturers to rearchitect credential verification systems around on-device processing rather than cloud storage.
Growth Catalysts
- NFC protocol expansion:Healthcare facilities in Germany deploy contactless badges for infection-control compliance, replacing magnetic stripe credentials in clinical workflows.
- FCC Part 15 compliance:US corporate campuses accelerate unlicensed spectrum deployments for building access, driving 13.56 MHz badge upgrades across Fortune 500 security budgets.
- Bluetooth Low Energy convergence:Logistics operators integrate mobile-computing badges with warehouse management systems for real-time location tracking of personnel.
Market Restraints
- Secure element supply concentration:Chip-level encryption components concentrate among three Asian foundries, exposing procurement to geopolitical disruption.
- Biometric sensor cost structure:Fingerprint and iris modules carry 4-6x premium over basic RFID transponders, compressing margins in price-sensitive education and retail deployments.
- GDPR data localization:European biometric data storage mandates require regional server infrastructure, raising operational complexity for multinational credential programs.
Strategic Opportunities
- India's manufacturing corridor:PLI scheme incentives for electronics production attract badge assembly to Gujarat and Tamil Nadu industrial zones.
- Dynamic attendee tracking:Event organizers in Brazil adopt real-time location badges for crowd flow optimization and emergency evacuation protocols.
- Health sensor integration:FDA-regulated clinical badges with IEC 60601-1-2 certification open reimbursement pathways in US hospital systems.
Industry Challenges
- RF engineering talent scarcity:Antenna design for optimized read ranges requires specialized electromagnetic simulation expertise concentrated among legacy defense contractors.
- Legacy access control integration:Proprietary Wiegand protocol infrastructure in installed building systems forces expensive middleware development for cloud-connected badge architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Badge Market |
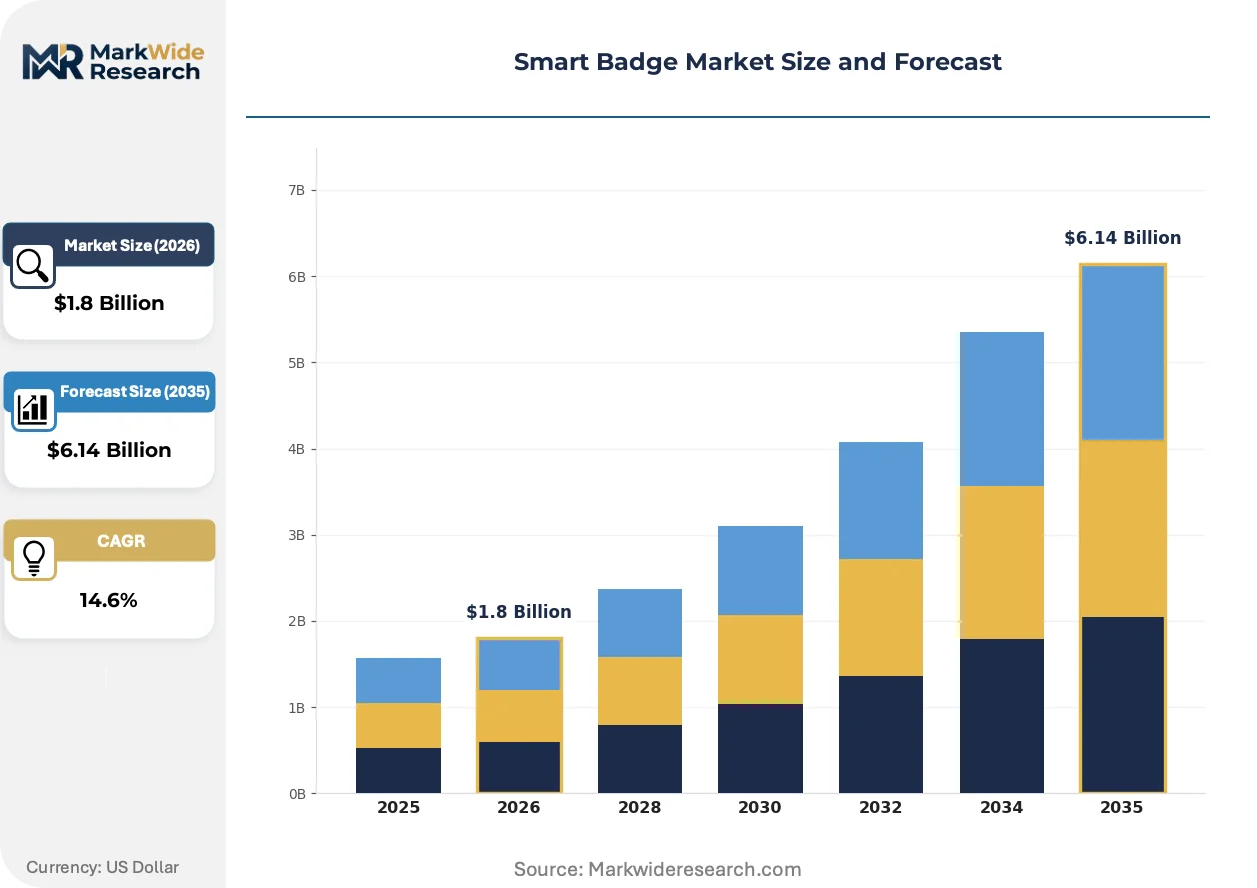
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Badges, NFC Badges, RFID Badges, Biometric Badges End User: Corporate Offices, Educational Institutions, Event Organizers, Healthcare Facilities Technology: Near Field Communication, Radio Frequency Identification, Biometric Authentication, Cloud Connectivity Application: Security Access Control, Attendance Management, Visitor Management, Credential Verification |
| Companies Covered | IDEMIA, Thales Group, Giesecke+Devrient GmbH, ASSA ABLOY, Zebra Technologies Corp., Identiv, Inc., CardLogix Corporation, Unitech Electronics Co., Ltd., Watchdata Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Badge Market Strategic Shifts
Edge computing architectures are redistributing credential verification away from centralized servers, compressing authentication latency while complicating firmware update logistics across dispersed device fleets.
Multi-modal biometric fusion is decentralizing identity assurance across corporate and government deployments. Fingerprint-plus-facial recognition badges eliminate single-point biometric failure modes. Financial services and critical infrastructure operators in Singapore and Switzerland adopt these credentials for high-assurance access. The technology is decentralizing risk management from IT security teams to individual credential holders through localized template matching.
GDPR Article 17 right-to-erasure mandates are reshaping biometric data lifecycle management across European deployments. Badge vendors must engineer cryptographic deletion mechanisms that purge templates from secure elements without physical device recovery. Healthcare and public sector procurement specifications in France and Germany now require demonstrable data portability compliance, favoring vendors with modular firmware architectures.
Subscription-based credential lifecycle management is displacing perpetual license models in enterprise security procurement. Buyers in US commercial real estate and German industrial manufacturing prefer per-badge monthly fees covering hardware, cloud platform access, and certificate rotation. This shift concentrates vendor-customer relationships around ongoing service performance rather than upfront equipment margins, with strongest traction among mid-market enterprises lacking dedicated credential administration staff.
Smart Badge Market Segmentation
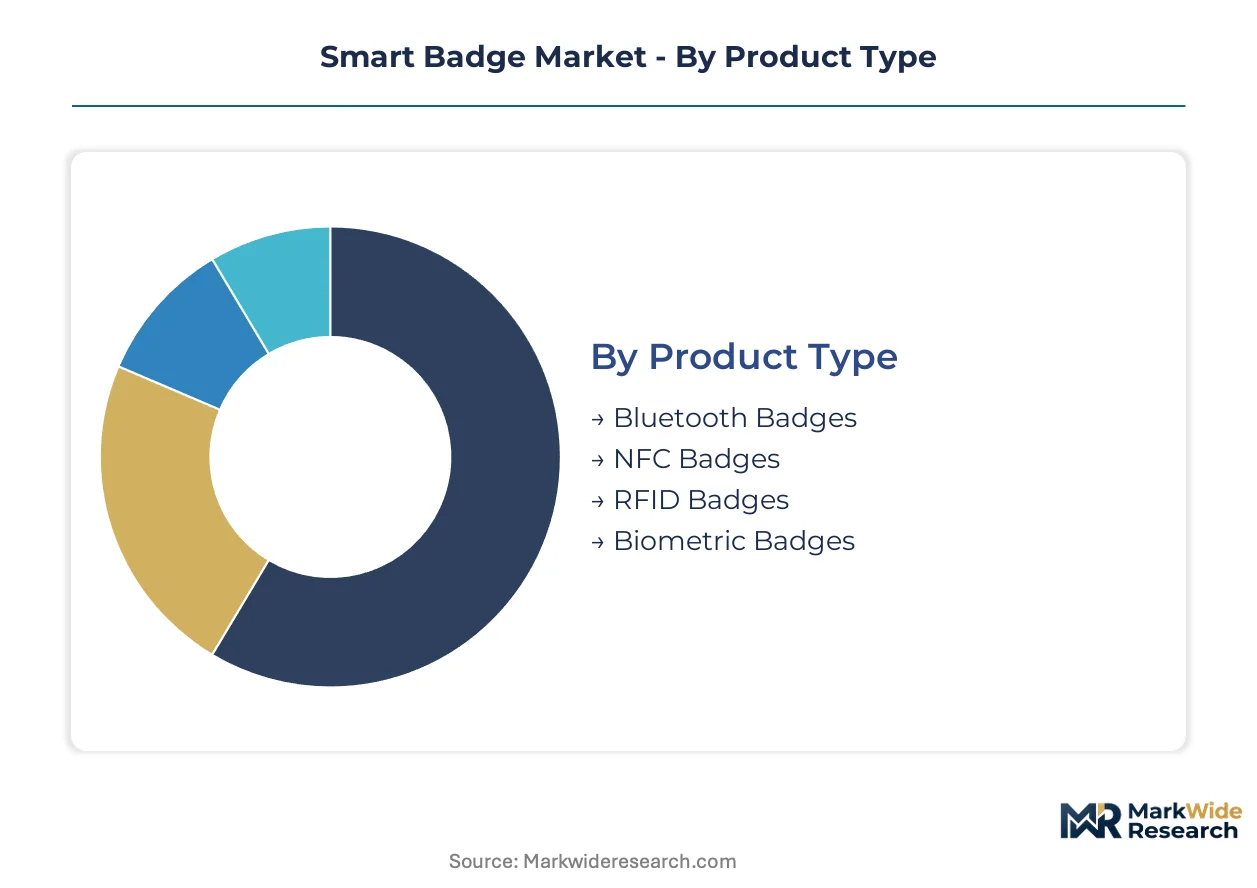
Smart badge procurement decisions hinge on integration depth, with standalone devices serving legacy access systems while embedded credentials feed building management platforms. Understanding where each segment sits on this spectrum clarifies vendor selection and total cost of ownership calculations for security administrators.
Product Type:
RFID badges dominate standalone deployments with minimal IT infrastructure, while Bluetooth and biometric variants embed into unified building automation stacks.
- Bluetooth Badges:These credentials leverage 2.4 GHz protocols for real-time location tracking across extended ranges up to 100 meters. Logistics operators in Germany's industrial corridor integrate these with warehouse management systems for personnel flow optimization. Battery life constraints and firmware update logistics complicate fleet management at scale.
- Biometric Badges:Fingerprint or iris sensors embedded in the credential body perform on-device template matching, eliminating cloud biometric storage under GDPR Article 17 mandates. Healthcare facilities in France specify these for clinical access where infection control prohibits shared surface contact. Unit costs run 4-6x above basic transponder cards, limiting penetration in price-sensitive education sectors.
- NFC Badges:Operating at 13.56 MHz with contact-to-10cm read ranges, these ISO 14443-compliant credentials serve event organizers requiring rapid tap-and-go authentication.
- RFID Badges:UHF variants at 860-960 MHz deliver 12-meter read ranges for perimeter access without user action, dominating manufacturing campus deployments.
RFID badges lead volumes today; biometric badges are gaining share fastest.
End User:
Cost tier stratification separates premium biometric deployments from commodity card rollouts across buyer categories.
- Healthcare Facilities:Infection-control protocols and FDA IEC 60601-1-2 requirements drive contactless biometric adoption in US hospital systems. Reimbursement pathways for integrated health sensor badges accelerate procurement cycles beyond standard security budgets.
- Corporate Offices:Fortune 500 campuses in North America prioritize 13.56 MHz NFC upgrades to replace magnetic stripe infrastructure, with cloud-connected architectures enabling centralized credential lifecycle management.
- Event Organizers:Brazilian stadium operators deploy real-time location badges for crowd flow optimization and emergency evacuation compliance.
- Educational Institutions:K-12 districts and universities favor basic RFID proximity cards given constrained security budgets and high card replacement volumes from student turnover.
Corporate offices anchor revenue concentration; healthcare facilities show steepest expansion trajectory.
Technology:
Application maturity varies sharply, with three-decade-old RFID protocols competing against emerging cloud-native architectures.
- Near Field Communication:Standardized at 13.56 MHz with ISO/IEC 18092 compliance, NFC enables smartphone-credential interoperability for hybrid physical-digital access. Germany's healthcare sector mandates these for clinical workstation authentication.
- Radio Frequency Identification:Passive UHF and HF transponders operate without onboard power, delivering lowest per-unit cost for high-volume deployments.
- Biometric Authentication:On-device template matching addresses GDPR and EU AI Act retention limits by eliminating centralized biometric databases.
- Cloud Connectivity:Over-the-air certificate rotation and firmware updates enable subscription-based credential management, displacing perpetual license models in US commercial real estate.
Radio Frequency Identification maintains installed base dominance; Cloud Connectivity is climbing the fastest.
Application:
Functional integration depth separates point solutions from platform-embedded credential workflows.
- Security Access Control:Building entry systems represent the foundational use case, with Wiegand protocol legacy infrastructure forcing expensive middleware development for cloud-connected badge architectures.
- Attendance Management:Workforce time-tracking integrations with HRIS platforms drive demand in manufacturing and logistics environments where labor compliance auditing is critical.
- Visitor Management:Temporary credential issuance for contractors and guests requires flexible entitlement provisioning, favoring mobile-credential solutions over physical card stock.
- Credential Verification:High-assurance identity binding for government and financial services applications demands multi-modal biometric fusion and secure element certification.
Security Access Control commands current spend; Credential Verification shows strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor drives premium biometric deployments, while India's electronics manufacturing incentives attract badge assembly migration from traditional Asian supply bases.
United States
FCC Part 15 unlicensed spectrum rules accelerate 13.56 MHz NFC badge upgrades across Fortune 500 corporate campuses. FDA IEC 60601-1-2 certification requirements govern clinical badge deployments in hospital systems. Greater Boston's healthcare technology cluster integrates contactless credentials with workstation authentication protocols.
Germany
Manufacturing campuses in the industrial corridor merge credential verification with building management systems for integrated facility control. GDPR Article 17 right-to-erasure mandates force cryptographic deletion mechanisms in biometric template management. Bavaria's automotive and industrial automation hubs specify multi-modal fusion badges for high-assurance access.
France
Healthcare procurement specifications require demonstrable data portability compliance under GDPR, favoring modular firmware architectures. ANSM and CNIL guidance shapes clinical badge data lifecycle protocols in public hospital networks. The Île-de-France region concentrates demand for cloud-connected credential platforms in commercial real estate.
India
PLI scheme incentives for electronics production draw badge assembly operations to Gujarat and Tamil Nadu industrial zones. BIS certification requirements structure quality benchmarks for domestic market entry. Karnataka's technology corridor hosts integration partnerships between credential vendors and building automation providers.
Brazil
Event organizers deploy real-time location badges for crowd flow optimization and emergency evacuation compliance in stadium infrastructure. ANVISA regulatory frameworks influence health sensor badge specifications for clinical applications. São Paulo's exhibition and convention centers anchor demand for dynamic attendee tracking systems.
Smart Badge Market Competitive Environment
Top-tier vendors anchor government ID and high-assurance credential programs, while mid-tier specialists compete on sector-specific integration depth. The market structures around three strategic archetypes: secure element chip specialists, mobile-computing workflow integrators, and government identity heritage players. Consolidation pressures intensify as cloud-connected architectures demand ongoing service capabilities beyond hardware margins. M&A activity targets middleware competencies for legacy Wiegand protocol integration.
Within the government identity tier, IDEMIA and Thales Group exemplify high-assurance credential program anchoring. Zebra Technologies Corp. occupies a position among mobile-computing-integrated workflow specialists. These three entities represent distinct competitive vectors: secure element encryption heritage, defense-aerospace credential lineage, and logistics environment real-time tracking specialization respectively.
| Leading Market Players |
|---|
| IDEMIA |
| Thales Group |
| Giesecke+Devrient GmbH |
| ASSA ABLOY |
| Zebra Technologies Corp. |
| Identiv, Inc. |
| CardLogix Corporation |
| Unitech Electronics Co., Ltd. |
| Watchdata Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Biometric-commodity badge divergence splits procurement into high-margin on-device processing tiers and price-pressed RFID transponder volumes, with EU AI Act compliance costs concentrating premium supply in Germany's industrial corridor while Asian foundries anchor commodity chip production.
Pricing Analysis
Capacity additions in India's PLI-subsidized electronics zones are reshaping price floors for basic transponder badges while biometric variants sustain 4-6x premiums through secure element certification. Three-tier pricing structure across premium biometric, standard NFC, and economy RFID levels reflects GDPR Article 17 compliance costs and FDA IEC 60601-1-2 certification tiers. Price erosion runs through education sector proximity cards as Indian assembly scales. Healthcare facilities show least price sensitivity given reimbursement pathways for clinical sensor integration.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese and South Korean secure element foundries supplying chip-level encryption for biometric credentials. Raw material dependencies span silicon wafers, lithium coin cells for Bluetooth badges, and specialized antenna substrates. Tariff exposure concentrates in cross-border shipments of cryptographic components from Asian manufacturing hubs. Distribution runs through building automation system integrators and security technology distributors serving corporate and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart badge market functions as a regulatory compounder where EU AI Act biometric data retention mandates and GDPR Article 17 erasure requirements continuously refresh upgrade cycles across European enterprise deployments.
For Market Incumbents: Extend firmware-as-a-service capabilities to capture subscription revenue displacing perpetual licenses, while deepening backward integration into secure element sourcing to mitigate Taiwanese foundry concentration risk. Cloud-connected badge architectures demand ongoing service competencies that hardware-centric competitors cannot replicate. For New Entrants and Emerging Players: Direct-to-channel partnerships with building management system integrators offer lower friction entry than direct enterprise sales, particularly for mid-market commercial real estate lacking dedicated credential administration staff. Brazil's event organizer segment presents penetrable white space for real-time location tracking solutions. For Investors and Strategic Acquirers: Consolidation pressure builds where middleware competencies for legacy Wiegand protocol integration remain scarce among cloud-native badge vendors. Long-term viability favors vendors with modular firmware architectures enabling rapid regulatory adaptation. Watch FDA health sensor reimbursement pathway expansions as inflection indicators for clinical badge demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| On-Device Biometric Processing Migration | Eliminates centralized biometric storage liability under GDPR Article 17 mandates. |
| Subscription Credential Lifecycle Platform | Captures recurring revenue from mid-market enterprises lacking in-house security administration. |
| Legacy Wiegand Middleware Acquisition | Bridges installed building access infrastructure to cloud-connected badge architectures. |
| PLI Scheme Manufacturing Relocation | Reduces tariff exposure and secures BIS certification for Indian domestic market entry. |
| Health Sensor FDA Certification Pathway | Opens hospital reimbursement channels for clinical-grade badge deployments. |
Study Parameters
Direct dialogue with security technology procurement officers, building automation system integrators, biometric sensor module suppliers, and healthcare facility compliance directors grounded qualitative findings, cross-referenced with FCC equipment authorization databases, FDA 510(k) filings for clinical badges, EU AI Act implementation guidance, and customs trade data on secure element imports. Bottom-up segment sizing triangulated against top-down enterprise security spending estimates.
Market value and volume trajectories across the projection horizon reflect modeled adoption curves for NFC, Bluetooth, and biometric credential technologies segmented by healthcare, corporate, event, and education end-use verticals. CAGRs derived from regression analysis of historical replacement cycles, regulatory compliance deadlines, and technology substitution elasticities, with inputs from German industrial corridor deployment timelines and US hospital capital expenditure patterns.
The model assumes a particular technology adoption path; alternative pathways for edge-computing credential verification would alter the outlook if on-device processing costs fall faster than projected. Forecasts embed assumptions around GDPR enforcement consistency and PLI scheme continuation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Level Measuring Instrument Market
Others
Aircraft Exterior Lighting Market
Others
Spain Smart Home Market
Others
Stichtite Market
Others
Global Alpha Cypermethrin Market
Others
Pediatric Measuring Devices Market
Others
Edible Insects for Animal Feed Market
Others
Global Computer Graphics Market
Others
Underwater Communication System Market
Others
Digital Mortgage Software Market
Others
Solar Lighting Tower Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Infant Positioning Aids Market
Others
Global Emergency Spill Response Market
Others
Ultra Mobile Devices (UMD) Market
Others
Global Sports and Fitness Wears Market