
 Smart Home Water Softener Market | 2026-2036
Smart Home Water Softener Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Water Softener Market Insights
Suburban homeowners with hard water concerns are rotating into the dominant buyer archetype for smart home water softeners, displacing traditional commercial procurement channels. Culligan International leverages its dealer network density to sustain installation-service revenue streams alongside hardware sales. EcoWater Systems anchors its position through vertical integration into resin manufacturing and captive distribution. Pentair plc competes on smart monitoring technology leadership, differentiating through connected-home platform integration.
Smart home water softeners are ion-exchange or template-assisted crystallization appliances that reduce calcium and magnesium ion concentrations in residential water supplies, typically processing 20,000 to 80,000 grains of hardness before regeneration cycles. These systems integrate flow sensors, Wi-Fi connectivity, and mobile application interfaces to enable remote monitoring, salt-level alerts, and usage-based regeneration scheduling. Salt-based ion exchange systems occupy the largest installed base due to proven efficacy against extreme hardness levels, while smart monitoring technology represents the fastest-growing segment as consumers prioritize predictive maintenance and water consumption visibility. Dual-tank configurations command premium positioning by ensuring continuous soft water availability during regeneration cycles, creating concentrated margin pools in the upper residential tier.
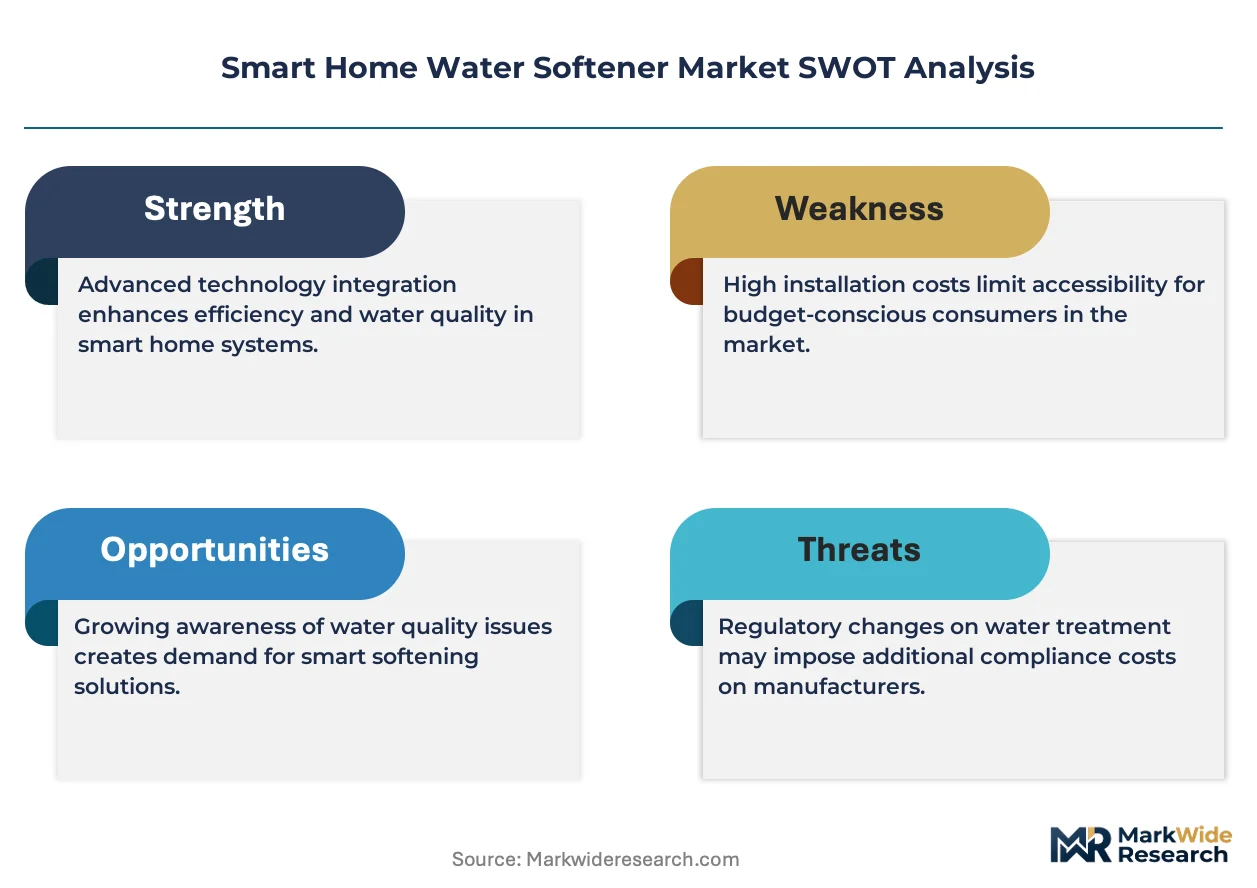
NSF/ANSI Standard 44 certification governs residential cation exchange water softener performance in the United States, with the EPA Safe Drinking Water Act influencing state-level contaminant thresholds that indirectly shape product specification requirements. The Federal Trade Commission's Green Guides constrain environmental marketing claims around salt-free and magnetic systems, compelling manufacturers to substantiate efficacy assertions through validated testing protocols. Stakeholders must monitor evolving state-level restrictions on brine discharge into municipal wastewater systems, as these regulations threaten to reshape regeneration technology roadmaps and installation eligibility across hardness-affected municipalities.
Market Dynamics
The smart home water softener market is undergoing structural reconfiguration as connected-home platform integration becomes the primary battleground for differentiation, forcing hardware manufacturers to choose between proprietary ecosystems and third-party interoperability.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:State-level contaminant threshold tightening in Arizona, Texas, and Florida is accelerating replacement cycles for non-compliant legacy systems.
- Template-assisted crystallization:Salt-free alternatives are capturing environmentally conscious suburban buyers in municipalities with brine discharge restrictions.
- Sun Belt groundwater hardness:Severe calcium and magnesium concentrations across suburban Phoenix, Las Vegas, and Dallas-Fort Worth corridors sustain replacement demand velocity.
Market Restraints
- Resin supply concentration:Specialty ion-exchange resin production clusters in Germany and China create input vulnerability for North American assemblers.
- NSF/ANSI Standard 44 certification timelines:Validation protocols extend product launch windows by 8-14 months for new entrants.
- Magnetic and electronic descalers:Unsubstantiated efficacy claims in the salt-free segment erode consumer trust and compress legitimate premium positioning.
Strategic Opportunities
- Brine discharge regulation divergence:California's SB 552 wastewater restrictions are creating certified-preferred contractor networks that lock in installation channel control.
- Predictive maintenance convergence:Flow sensor data integration with utility smart metering infrastructure enables usage-based service monetization.
- Rural well-water segments:Unpenetrated exurban markets across the Great Plains and Mountain West lack dealer network density, rewarding direct-to-consumer platform investment.
Industry Challenges
- Connected-device cybersecurity:Wi-Fi-enabled softeners face FTC enforcement exposure under Section 5 unfair practice standards for inadequate firmware update protocols.
- Dual-tank configuration complexity:Continuous-availability engineering requires specialized plumbing contractor training, constraining scalable installation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Water Softener Market |
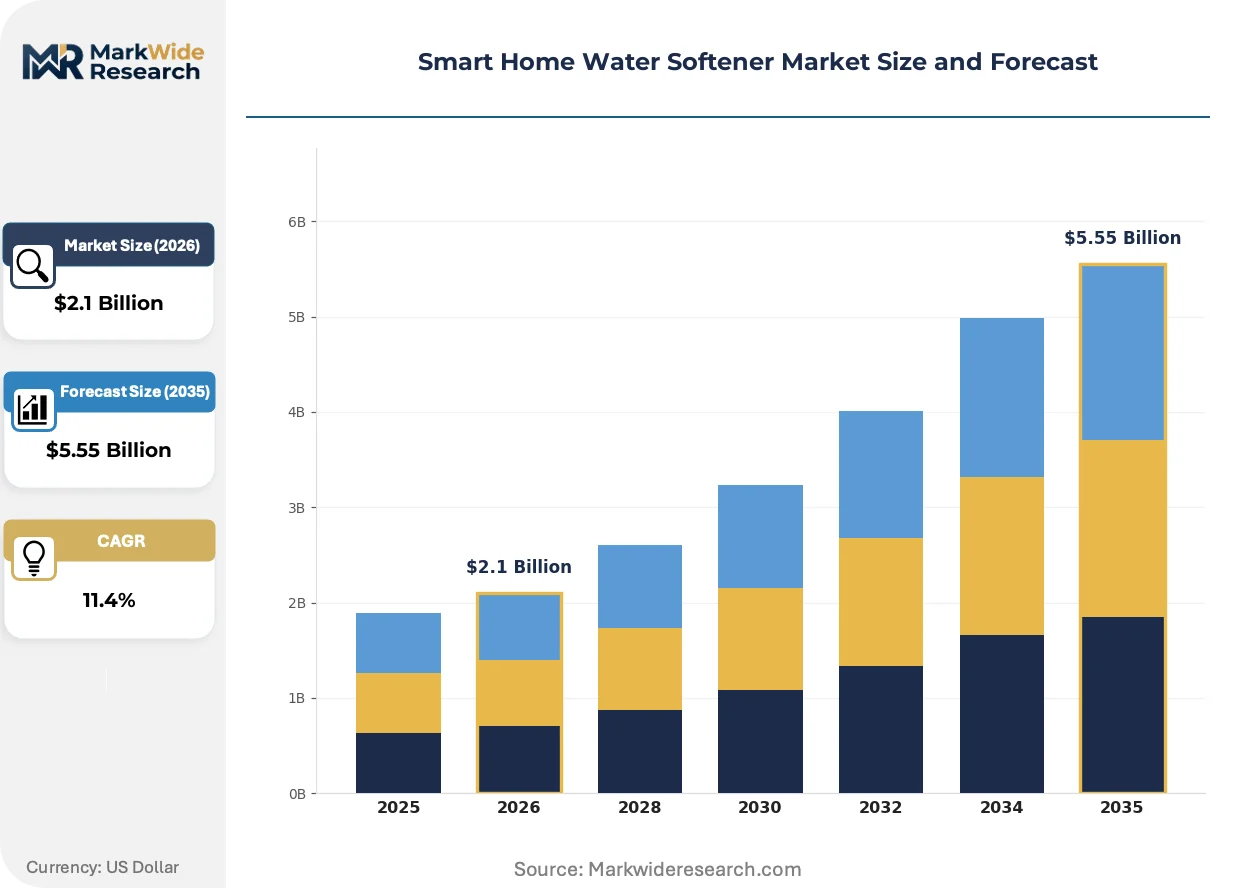
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt-Based, Salt-Free, Dual-Tank, Magnetic Technology: Ion Exchange, Reverse Osmosis, Electromagnetic, Smart Monitoring End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Culligan International, EcoWater Systems, A.O. Smith Corporation, Pentair plc, Kinetico Incorporated, 3M Company, Whirlpool Corporation, SpringWell Water Filtration Systems, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Water Softener Market Trends and Innovations
Smart home water softener innovation vectors are converging on predictive capability and platform openness, with manufacturers racing to embed machine learning into regeneration algorithms before commoditization erodes hardware margins.
Template-assisted crystallization is decomposing the historical salt-based monopoly in moderate-hardness markets. Suburban homeowners in brine-restricted California and Arizona municipalities are adopting these systems at triple the rate of national baselines. The technology is decomposing traditional dealer revenue models by eliminating salt delivery logistics and reducing service call frequency.
The Federal Trade Commission's Green Guides enforcement against unsubstantiated environmental claims is tightening marketing compliance for salt-free system manufacturers. Manufacturers now face mandatory third-party efficacy validation before "eco-friendly" positioning. The salt-free segment bears the heaviest compliance burden, with several 2023-2024 consent orders requiring retroactive claim substantiation.
Installation channel unbundling is fragmenting the traditional dealer-captive model. Big-box retailers and direct-to-consumer platforms are capturing specification influence previously held by Culligan and EcoWater service technicians. This disintermediation is most advanced in Texas and Florida, where homeowner self-installation rates have doubled amid YouTube tutorial proliferation and simplified quick-connect plumbing interfaces.
Smart Home Water Softener Market Segmentation
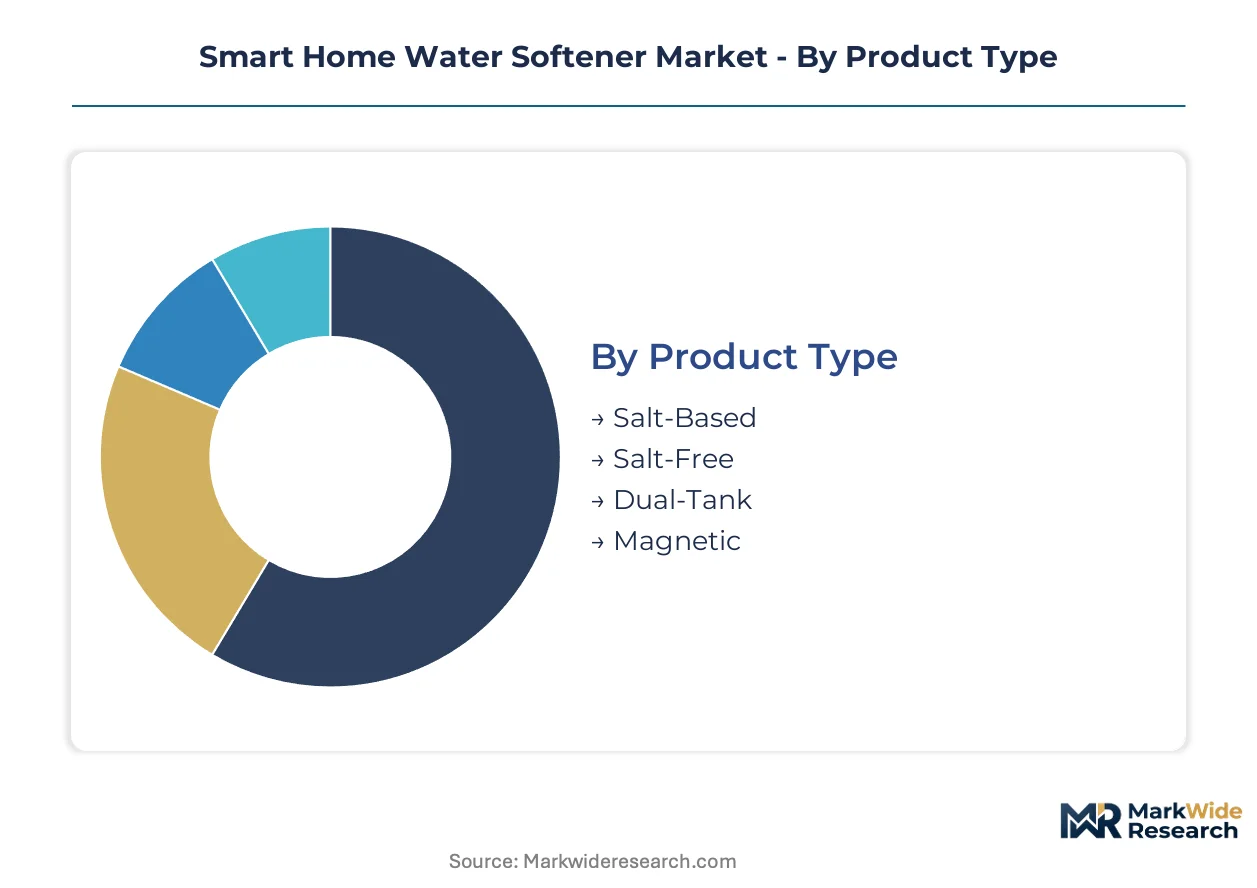
Segmentation in the smart home water softener market reveals how regulatory pressure and installation economics fragment buyer behavior. NSF/ANSI Standard 44 certification requirements and municipal brine discharge rules create divergent product specifications across jurisdictions, forcing manufacturers to maintain parallel SKUs for adjacent markets.
Product Type:
EPA Safe Drinking Water Act amendments and state-level wastewater restrictions are bifurcating product development roadmaps, with salt-based systems facing eligibility constraints in California, Arizona, and Florida municipalities while salt-free alternatives capture specification share in brine-restricted corridors.
- Salt-Based:Ion-exchange systems utilizing sodium or potassium chloride regeneration dominate installed base in severe hardness corridors across Texas, Nevada, and Arizona. Suburban Phoenix and Dallas-Fort Worth homeowners with groundwater hardness exceeding 15 grains per gallon sustain replacement velocity despite rising salt logistics costs and municipal discharge scrutiny.
- Salt-Free:Template-assisted crystallization and catalytic media systems eliminate brine discharge, positioning for California SB 552 compliance and environmentally conscious suburban buyers in Santa Clara County and Orange County municipalities. Adoption rates in brine-restricted markets run triple national baselines.
- Dual-Tank:Continuous-availability configurations command premium positioning through alternating resin bed operation, ensuring zero soft water interruption during regeneration cycles.
- Magnetic:Electromagnetic descalers face FTC Green Guides enforcement exposure for unsubstantiated efficacy claims, compressing legitimate premium positioning and channel access.
Established volume favors Salt-Based; emerging adoption favors Salt-Free.
Technology:
Cost tier differentiation separates proven efficacy platforms from emerging connected-home propositions, with hardware margins compressing fastest in commoditized ion-exchange baselines while predictive maintenance capabilities sustain premium positioning.
- Ion Exchange:Cation resin technology delivers proven calcium and magnesium removal across 20,000 to 80,000 grain capacity ratings. Suburban Sun Belt homeowners with well water or municipal hardness above 10 grains per gallon retain specification preference for resin-based efficacy.
- Smart Monitoring:Wi-Fi-enabled flow sensors and mobile application interfaces enable remote salt-level alerts, usage-based regeneration scheduling, and predictive maintenance monetization. Connected-home platform integration represents the steepest expansion trajectory as consumers prioritize consumption visibility.
- Reverse Osmosis:Membrane-based systems target point-of-use drinking water purification rather than whole-home softening, occupying adjacent specification space with limited overlap.
- Electromagnetic:Coil-based descaling technology lacks validated third-party performance data under NSF/ANSI protocols, constraining channel placement and consumer trust.
Hardware economics concentrate in Ion Exchange; service monetization potential concentrates in Smart Monitoring.
End User:
Application maturity separates residential replacement cycles from commercial procurement patterns, with suburban homeowner self-installation disrupting traditional dealer-captive models while hospitality and industrial segments retain specification gatekeeping through facility management channels.
- Residential:Suburban single-family homeowners with hard water concerns have displaced commercial procurement as the dominant buyer archetype. Self-installation rates have doubled in Texas and Florida amid simplified quick-connect plumbing interfaces and YouTube tutorial proliferation.
- Commercial:Multi-tenant properties, restaurants, and laundromats specify through facility management procurement channels with dealer service contract requirements.
- Industrial:Manufacturing and process water applications demand continuous-availability engineering with specialized plumbing contractor training.
- Hospitality:Hotel and resort properties prioritize guest experience consistency through dual-tank configurations and captive service agreements.
Channel disruption favors Residential; contract stability favors Commercial.
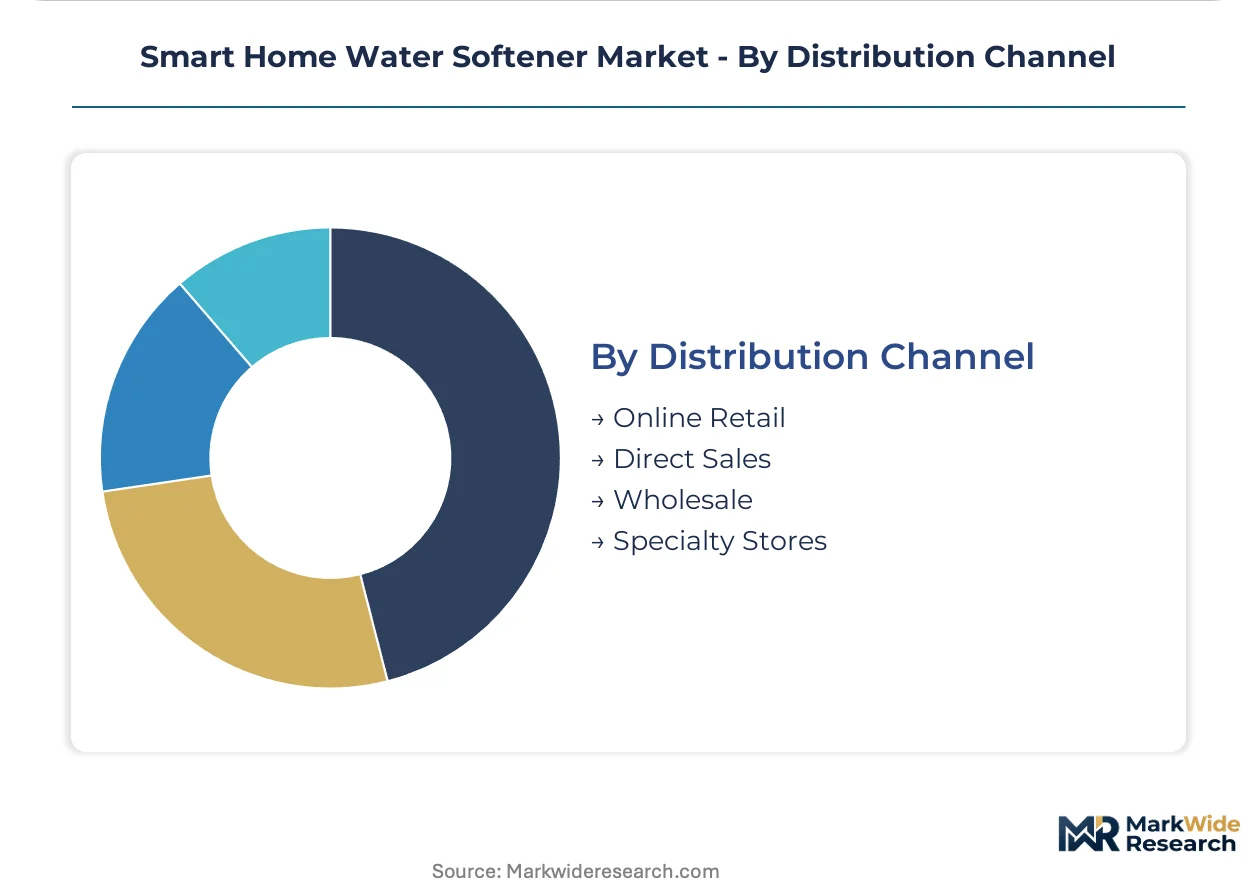
Distribution Channel:
Customer type fragmentation unbundles the traditional dealer network, with direct-to-consumer platforms capturing specification influence previously held by Culligan and EcoWater service technicians while wholesale and specialty retail retain traction in complex installation segments.
- Online Retail:Amazon, Home Depot, and Lowe's platforms capture specification influence through review aggregation and comparison tools. Direct-to-consumer brands bypass dealer markups with simplified installation kits targeting suburban DIY homeowners.
- Direct Sales:Manufacturer-owned installation networks sustain service revenue streams and salt delivery logistics, defending margin pools through recurring consumables.
- Wholesale:Plumbing contractor and builder supply channels retain specification control in new construction and dual-tank configurations requiring specialized installation.
- Specialty Stores:Regional water treatment dealers maintain local market knowledge and water testing services, converting hardness awareness into system specification.
Scalable reach favors Online Retail; installation complexity favors Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suburban homeowners with hard water concerns dominate demand geography, concentrating procurement in groundwater-dependent regions with severe calcium and magnesium concentrations. Municipal brine discharge regulations and NSF certification requirements fragment product eligibility across jurisdictions.
United States
Sun Belt suburban corridors sustain replacement velocity as Phoenix, Las Vegas, and Dallas-Fort Worth homeowners confront groundwater hardness exceeding 15 grains per gallon. EPA Safe Drinking Water Act amendments in Arizona, Texas, and Florida accelerate non-compliant legacy system replacement cycles. California's SB 552 wastewater restrictions are reshaping certified-preferred contractor networks across Santa Clara and Orange County municipalities.
Germany
Specialty ion-exchange resin production clusters in German chemical manufacturing regions create input supply concentration for North American assemblers. REACH chemical regulations govern resin formulation standards and environmental discharge protocols. Industrial water treatment engineering expertise in the Ruhr Valley and Bavaria supports advanced regeneration technology development.
China
Domestic manufacturing capacity expansion targets export assembly for North American and European private-label brands. MIIT standards and GB certification protocols shape product specifications for domestic consumption versus export markets. Yangtze River Delta manufacturing zones concentrate component fabrication and resin processing operations.
Canada
Hard water prevalence across Prairie Provinces and Ontario sustains residential specification demand comparable to US Sun Belt intensity. Health Canada drinking water guidelines influence provincial contaminant threshold settings. Calgary and Edmonton suburban markets exhibit replacement cycle velocity driven by municipal groundwater hardness levels.
Australia
Groundwater-dependent regional communities across Queensland and Western Australia drive demand for compact residential softening systems. TGA and state-level plumbing codes govern installation eligibility and product certification requirements. Perth metropolitan expansion into limestone aquifer regions concentrates suburban buyer archetype formation.
Smart Home Water Softener Market Competitive Landscape
Player mix skews toward vertically integrated specialists with captive distribution networks and diversified industrial conglomerates with smart home platform ambitions. Market structure exhibits moderate consolidation around established water treatment brands with installation-service capabilities. Two strategic archetypes dominate: dealer-network captives defending recurring salt-delivery revenue, and technology-forward platforms prioritizing connected-home integration. Competitive moves concentrate on geographic expansion through certified contractor networks and portfolio diversification into salt-free alternatives.
Among dealer-network specialists, Culligan International and EcoWater Systems exemplify the service-revenue archetype through installation-captive business models. Pentair plc occupies a position on the technology-forward vector, representing smart monitoring platform integration ambitions. These three anchors illustrate the structural tension between hardware commoditization defense and predictive maintenance service monetization.
| Leading Market Players |
|---|
| Culligan International |
| EcoWater Systems |
| A.O. Smith Corporation |
| Pentair plc |
| Kinetico Incorporated |
| 3M Company |
| Whirlpool Corporation |
| SpringWell Water Filtration Systems |
| GE Appliances |
| Others |
Pricing and Supply Chain Analysis
Template-assisted crystallization substitution for ion-exchange resin systems is redrawing supply geography toward catalytic media fabricators in China and Southeast Asia while compressing salt logistics premiums that historically anchored dealer revenue models. This input shift simultaneously erodes captive salt-delivery margins and opens pricing headroom for direct-to-consumer channels.
Pricing Analysis
Cost-plus contracts with salt-indexed pass-through clauses dominate dealer-network arrangements, insulating installers from potassium chloride spot volatility while exposing direct-to-consumer brands to raw material swings. Price differentiation separates NSF/ANSI Standard 44 certified systems from uncertified alternatives, with California SB 552 compliance commanding additional premiums in brine-restricted municipalities. Cost compression in entry-tier salt-based units is intensifying because of resin oversupply from Chinese manufacturers. Suburban DIY homeowners exhibit highest price sensitivity, while hospitality buyers with dual-tank requirements show lowest elasticity due to operational continuity demands.
Supply Chain Analysis
Rhine River chemical corridor transit underwrites specialty ion-exchange resin availability for North American assemblers, creating European chokepoint exposure distinct from Asian component flows. Supply concentrates in Germany, China, and South Korea for cation resin, flow sensors, and Wi-Fi modules respectively. Raw material dependencies span petroleum-derived polystyrene divinylbenzene, rare-earth catalytic media, and semiconductor-grade pressure transducers. Single-source vulnerability sits with German resin formulation IP held by three chemical conglomerates. Distribution runs through captive dealer networks, wholesale plumbing supply, and direct-to-consumer platforms in divergent ratios by installation complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward suburban homeowners as self-installation proliferation fragments dealer-captive procurement, consolidating specification influence in online retail channels and fragmenting traditional service-contract lock-in.
For Market Incumbents: Secure captive resin supply through backward integration into German or Chinese chemical manufacturing partnerships before specialty polymer allocation tightens. Defend installation-channel control by embedding predictive maintenance algorithms into proprietary mobile applications, creating switching costs against third-party platform integration. Salt-free template-assisted crystallization entrants threaten ion-exchange hardware margins in California and Arizona municipalities. For New Entrants and Emerging Players: Differentiate on connected-home platform openness by offering Matter protocol compatibility and utility smart meter API integration, bypassing proprietary ecosystem wars. Target rural well-water segments across the Great Plains and Mountain West where dealer network density remains thinnest. Deploy direct-to-consumer video-supported installation kits with simplified quick-connect plumbing interfaces to capture specification influence from legacy service technicians. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed water treatment dealer networks carrying recurring salt-delivery revenue streams and aging installation contractor relationships. Long-term viability favors platforms with predictive maintenance data monetization capabilities over pure hardware assemblers. Watch California SB 552 expansion patterns as the inflection signal for salt-free technology share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Connected-Home Platform Integration | Matter protocol compatibility unlocks utility smart meter data sharing for usage-based service monetization. |
| Salt-Free Technology Portfolio Expansion | Template-assisted crystallization certification investments secure California SB 552 eligibility in brine-restricted municipalities. |
| Dealer Network Certification Lock-In | Preferred contractor status under municipal wastewater restrictions channels installation revenue toward compliant service providers. |
| Predictive Maintenance Algorithm Development | Machine learning regeneration scheduling transforms hardware margins into recurring SaaS revenue streams. |
| Rural Direct-to-Consumer Channel Buildout | Video-supported installation kits penetrate exurban markets lacking Culligan and EcoWater service density. |
Research Methodology
The analysis maps salt-based ion exchange, template-assisted crystallization, dual-tank configurations, and smart monitoring technology segments, each validated through interviews with water treatment dealer principals, municipal wastewater compliance officers, plumbing contractor purchasing managers, and residential construction procurement leads. Primary fieldwork combined with secondary validation against EPA Safe Drinking Water Act amendments, NSF/ANSI Standard 44 certification databases, state-level brine discharge regulations, and utility smart metering infrastructure disclosures. Bottom-up unit economics triangulated against top-down residential construction permit data and groundwater hardness mapping.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology type, product configuration, end-user application, and distribution channel dimensions alongside regional regulatory cluster variations. CAGRs were derived from replacement cycle velocity analysis, new construction attachment rates, and technology substitution curves. Industry-specific forecast inputs included municipal brine discharge restriction timelines and connected-home platform adoption trajectories.
Material uncertainties — regulatory acceleration in wastewater discharge restrictions, resin supply disruption from European energy volatility, and cybersecurity enforcement exposure under FTC Section 5 standards — sit outside the modeled envelope. Forecasts reflect assumptions around suburban homeowner DIY installation propensity and smart home ecosystem consolidation. Practitioners should keep alternative scenarios live as California SB 552 enforcement patterns and Matter protocol adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Sports Events Market
Others
Powder Coating Equipment Market
Others
Global Pregnancy Tracker Apps Market
Others
Global Virtual Keyboard Market
Others
Lightweight Compact Wheel Loader Market
Others
Server Market
Others
Global Digital Market
Others
Subtilisin Market
Others
Lychee Market
Others
Spain Automotive LED Lighting Market
Others
France Location-Based Services Market
Others
Automatic Barriers and Bollards Market
Others
Global Injectable Nanomedicine Market
Others
Basketball Apparel Market
Others
Asia-Pacific Adtech Market
Others
Edible Insects for Animal Feed Market