
 Power Distribution Cables Market | 2026-2036
Power Distribution Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Power Distribution Cables Market Outlook
Data center operators and renewable developers are redrawing procurement priorities for power distribution cables. Prysmian Group leverages its submarine cable expertise to anchor long-term offshore wind contracts across European waters. Nexans competes aggressively in North American utility undergrounding programs, while Sumitomo Electric Industries specializes in superconducting and high-capacity XLPE systems for dense urban grids.
Power distribution cables are insulated conductors engineered to transmit electrical energy from substations to end-use points, typically rated from low voltage through extra high voltage classes with copper or aluminum cores and polymer-based insulation such as XLPE or EPR designed for thermal stability and dielectric strength. Their primary purpose is to deliver reliable, efficient power across industrial facilities, commercial complexes, and residential neighborhoods while minimizing transmission losses. Low voltage and medium voltage categories dominate installed base volumes, though extra high voltage segments command concentrated margin pools due to specialized manufacturing requirements and limited qualified suppliers. Underground installation methods are gaining fastest across mature grid markets, while aerial systems retain cost advantages in rural and emerging economy deployments.
FERC, EPA, and OSHA frameworks in the United States govern grid reliability standards, environmental permitting for cable routes, and installation worker safety protocols, collectively shaping product certification requirements and project timelines. EMA, REACH, and the EU Green Deal in Europe mandate material traceability, restricted substance compliance, and carbon footprint disclosures that filter through procurement specifications. Stakeholders must monitor evolving cross-border standard harmonization between IEC and national GB codes as manufacturing footprints shift and new conductor materials enter qualification cycles.
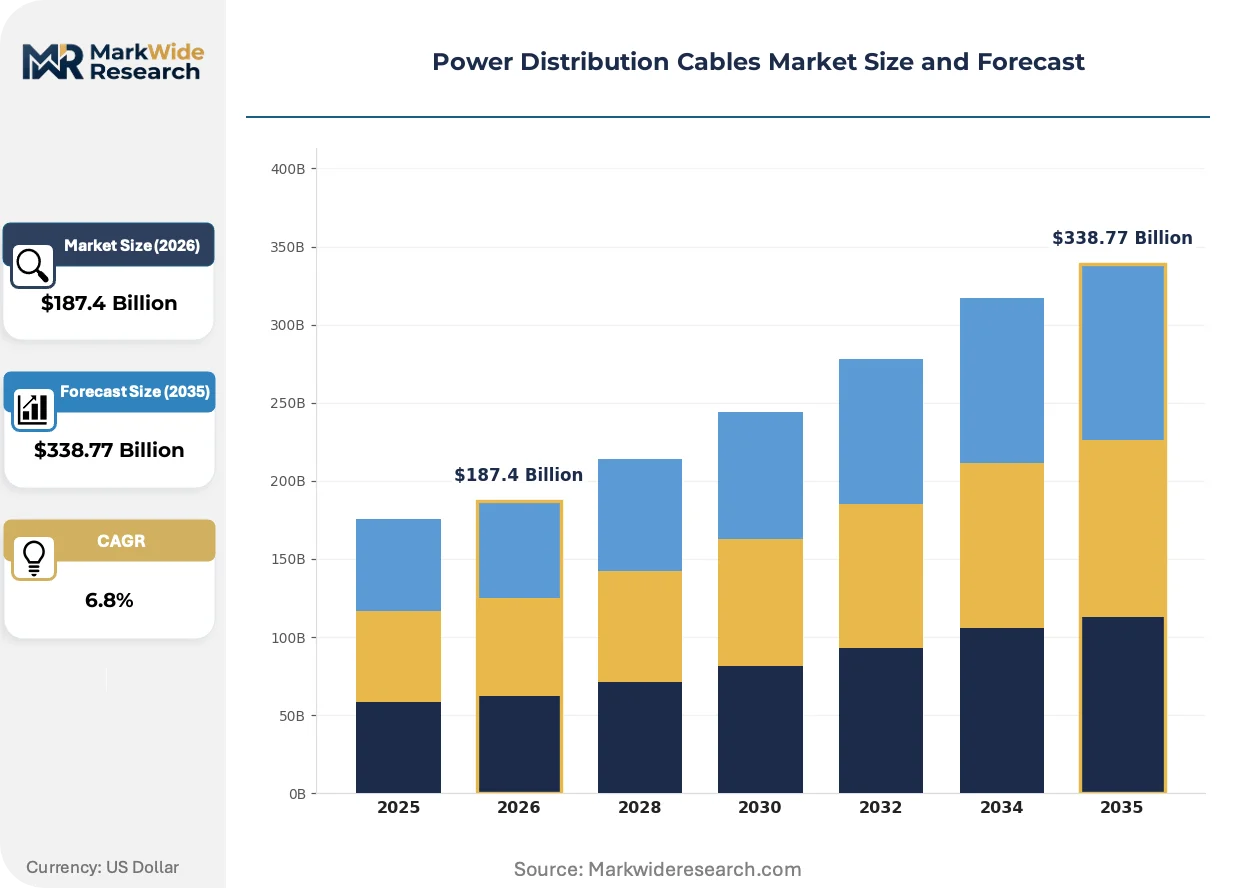
Market Dynamics
Grid undergrounding mandates and offshore wind interconnection requirements are forcing cable manufacturers to requalify product portfolios for submarine and extra-high-voltage applications, compressing development cycles and consolidating procurement around vertically integrated suppliers.
Growth Catalysts
- EU Green Deal grid modernization:National replacement mandates in Germany, France, and Italy are accelerating procurement of XLPE-insulated underground systems for urban resilience.
- Offshore wind transmission:Renewable developers in European waters are contracting submarine cable corridors linking North Sea generation clusters to onshore substations.
- China State Grid urban undergrounding:Massive cross-province ultra-high-voltage interconnectors and metropolitan burial programs are absorbing specialized high-capacity cable output.
Market Restraints
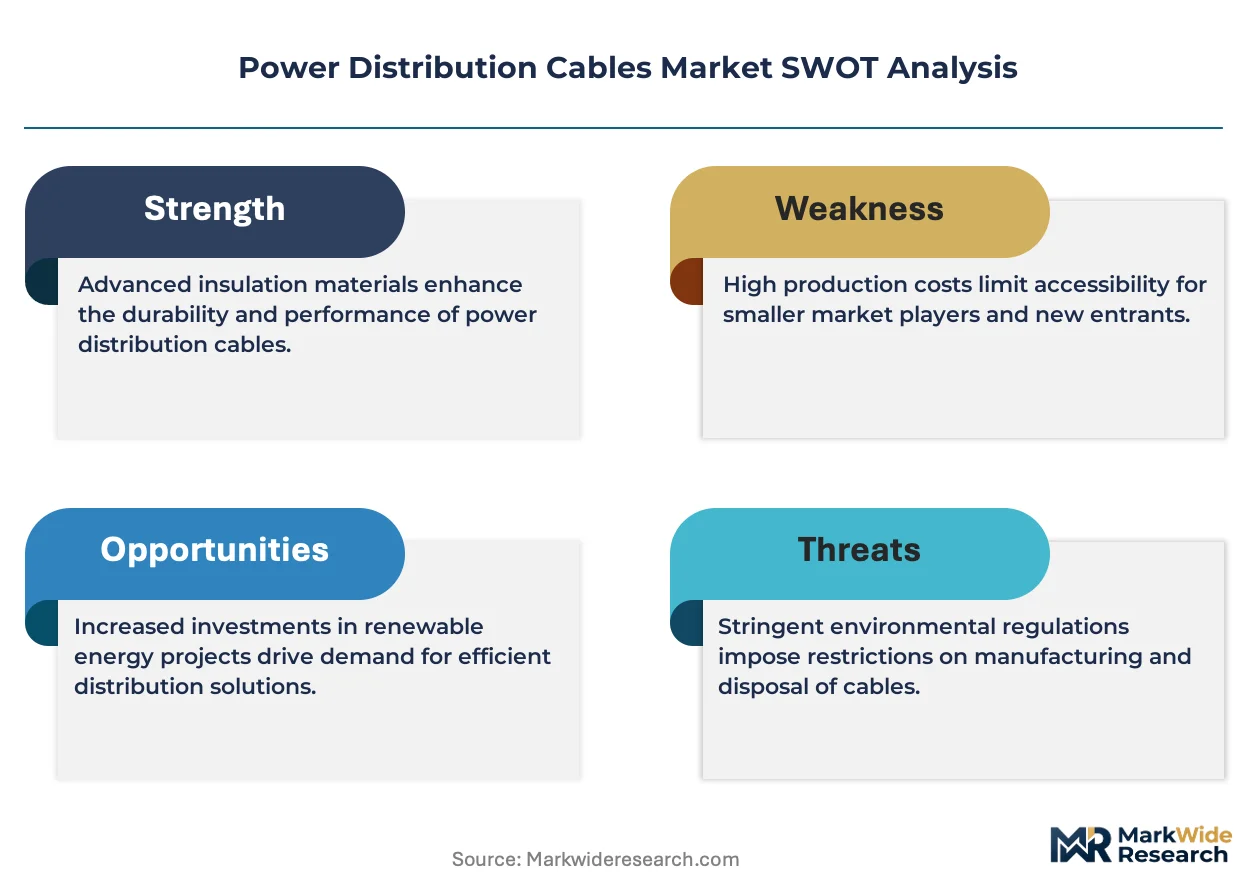
- Copper and aluminum price volatility:Raw metal inputs constitute 60-70% of cable production cost, exposing margins to LME commodity swings without effective hedging mechanisms for mid-tier fabricators.
- Qualified supplier concentration:Extra-high-voltage submarine cable manufacturing concentrates among three European and two Asian producers, creating bottleneck risk for large-scale offshore wind timelines.
- EPR insulation thermal limitations:Ethylene propylene rubber compounds face temperature ceiling constraints in dense urban tunnels where XLPE dominates, restricting material substitution flexibility.
Strategic Opportunities
- India transmission expansion:Central Electricity Authority mandates for renewable evacuation infrastructure create demand for 765kV and 1200kV land cable systems in western and southern states.
- Superconducting cable commercialization:Liquid nitrogen-cooled HTS systems are converging with fault-current limiting applications for data center clusters and dense metropolitan substations.
- US IRA domestic content incentives:Investment tax credit adders for projects sourcing North American-manufactured cable are redirecting procurement toward regional fabrication capacity.
Industry Challenges
- Submarine cable laying vessel scarcity:Specialized installation fleets number fewer than fifteen globally, creating project queue bottlenecks that extend delivery timelines beyond developer financing windows.
- IEC-GB standard harmonization delays:Divergent qualification protocols between international and Chinese national codes force manufacturers to maintain parallel certification tracks, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Distribution Cables Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage Insulation Material: PVC, XLPE, EPR, Rubber Installation Method: Aerial, Underground, Direct Burial, Duct End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | Prysmian Group, Nexans, Sumitomo Electric Industries, LS Cable & System, Southwire Company, General Cable, Schneider Electric, ABB, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Distribution Cables Market Strategic Shifts
Material science advances and installation methodology refinements are compressing the performance gap between established XLPE systems and emerging alternatives, while procurement centralization around utility-scale developers is reshaping supplier relationships.
Cross-linked polyethylene insulation formulations with enhanced treeing resistance and thermal cycling durability are fragmenting the medium-voltage cable landscape. European utilities undergoing undergrounding programs are specifying these modified compounds for 20-30 year service life guarantees. The technology is fragmenting procurement decisions that previously defaulted to conventional EPR or older XLPE grades, forcing manufacturers to maintain multiple compound qualification tracks.
REACH substance restrictions and EU Green Deal carbon footprint disclosure mandates are tightening material traceability requirements across European cable procurement. Suppliers must now document polymer additive origins and halogen-free flame retardant compositions through third-party verification. Submarine cable projects in North Sea waters face the most stringent documentation burdens, with developers pre-qualifying only vendors with certified circular material feedstocks.
Utility procurement departments are consolidating cable purchasing through multi-year framework agreements that bundle engineering, installation supervision, and long-term service contracts. This bundling displaces the traditional model of separate specification, supply, and construction contracts. The shift is most visible in German and French distribution system operator tenders, where integrated service providers capture 70-80% of annual cable volume through single-source arrangements.
Power Distribution Cables Market Segmentation
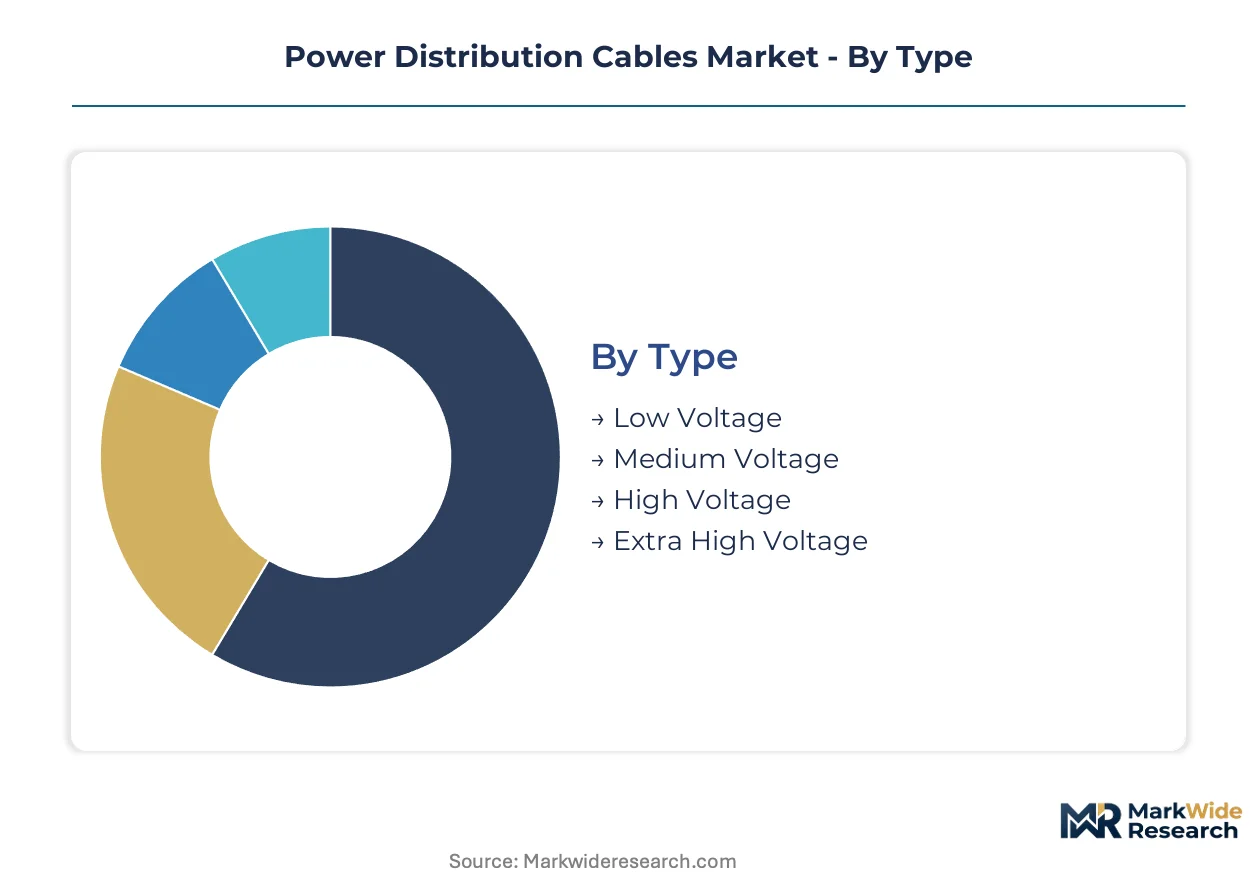
Power distribution cables fragment across voltage classes, insulation chemistries, and installation topologies that each carry distinct regulatory footprints and margin structures. Procurement patterns diverge sharply between utility-scale transmission projects and distributed commercial installations, demanding tailored qualification tracks.
Type:
FERC and national electrical codes in the United States, alongside IEC standards across Europe and GB protocols in China, impose tiered testing regimes that escalate with voltage rating. Certification complexity concentrates supplier pools at upper tiers.
- Low Voltage:Copper and aluminum conductors rated up to 1kV serve building distribution and last-mile residential connections. Demand clusters in Chinese metropolitan undergrounding programs and North American residential construction, where PVC and XLPE insulation dominate procurement specifications.
- Medium Voltage:Systems between 1kV and 33kV incorporate cross-linked polyethylene insulation engineered for thermal cycling durability. European distribution system operators specify these for urban undergrounding mandates in Germany, France, and Italy, absorbing volume through multi-year framework agreements.
- High Voltage:Land-based transmission corridors from 33kV to 220kV require specialized XLPE formulations with enhanced treeing resistance. Indian CEA renewable evacuation mandates and Chinese cross-province interconnectors absorb specialized output.
- Extra High Voltage:Submarine and land cables exceeding 220kV demand extrusion cleanrooms and vertical integration into insulation compound production. Offshore wind developers in European waters contract these through pre-qualified vendor pools numbering fewer than five globally.
Low voltage handles the majority of throughput; extra high voltage is the fastest mover on share.
Insulation Material:
REACH substance restrictions and EU Green Deal carbon disclosure mandates filter procurement toward halogen-free and traceable polymer feedstocks. Cost tier stratification separates commodity compounds from specialized formulations.
- PVC:Polyvinyl chloride compounds offer lowest material cost for low-voltage aerial and building wire applications. REACH phthalate restrictions and EU Green Deal circularity mandates are displacing volumes toward halogen-free alternatives in European tenders.
- XLPE:Cross-linked polyethylene dominates medium and high voltage underground systems through superior thermal stability and dielectric strength. State Grid Corporation procurement in China and German distribution operator undergrounding programs specify enhanced treeing-resistant grades for 20-30 year service guarantees.
- EPR:Ethylene propylene rubber provides flexibility for mobile equipment and harsh industrial environments. Temperature ceiling constraints in dense urban tunnels limit substitution against XLPE, restricting share in stationary transmission applications.
- Rubber:Natural and synthetic rubber compounds serve mining, port, and temporary power applications requiring extreme flexibility. Niche demand concentrates in industrial segments with mechanical stress requirements beyond polymer capabilities.
XLPE commands the dominant share of new procurement; EPR faces the steepest displacement pressure from regulatory tightening.
Installation Method:
Urban density and environmental permitting intensity determine method selection, with underground systems carrying 3-5x capital cost premiums over aerial alternatives. Customer type concentration separates municipal utility mandates from commercial developer discretion.
- Aerial:Overhead conductor systems on utility poles retain cost advantage in rural and emerging economy deployments. Chinese State Grid rural electrification and Indian transmission expansion continue absorbing aluminum conductor volumes.
- Underground:Trench and tunnel installations eliminate visual impact and weather exposure for urban resilience. German, French, and Italian grid modernization mandates accelerate replacement cycles, with integrated service providers capturing 70-80% of annual volume through bundled engineering and construction contracts.
- Direct Burial:Armored cables laid without conduit serve suburban distribution and renewable generation tie-lines. North American utility undergrounding programs and European offshore wind onshore connection corridors absorb specialized armored constructions.
- Duct:Conduit-encased installations enable future cable replacement without excavation in dense metropolitan cores. Data center clusters in Frankfurt, Amsterdam, and Singapore specify duct infrastructure for scalability.
Aerial retains the largest installed base; underground is expanding most quickly in developed markets.
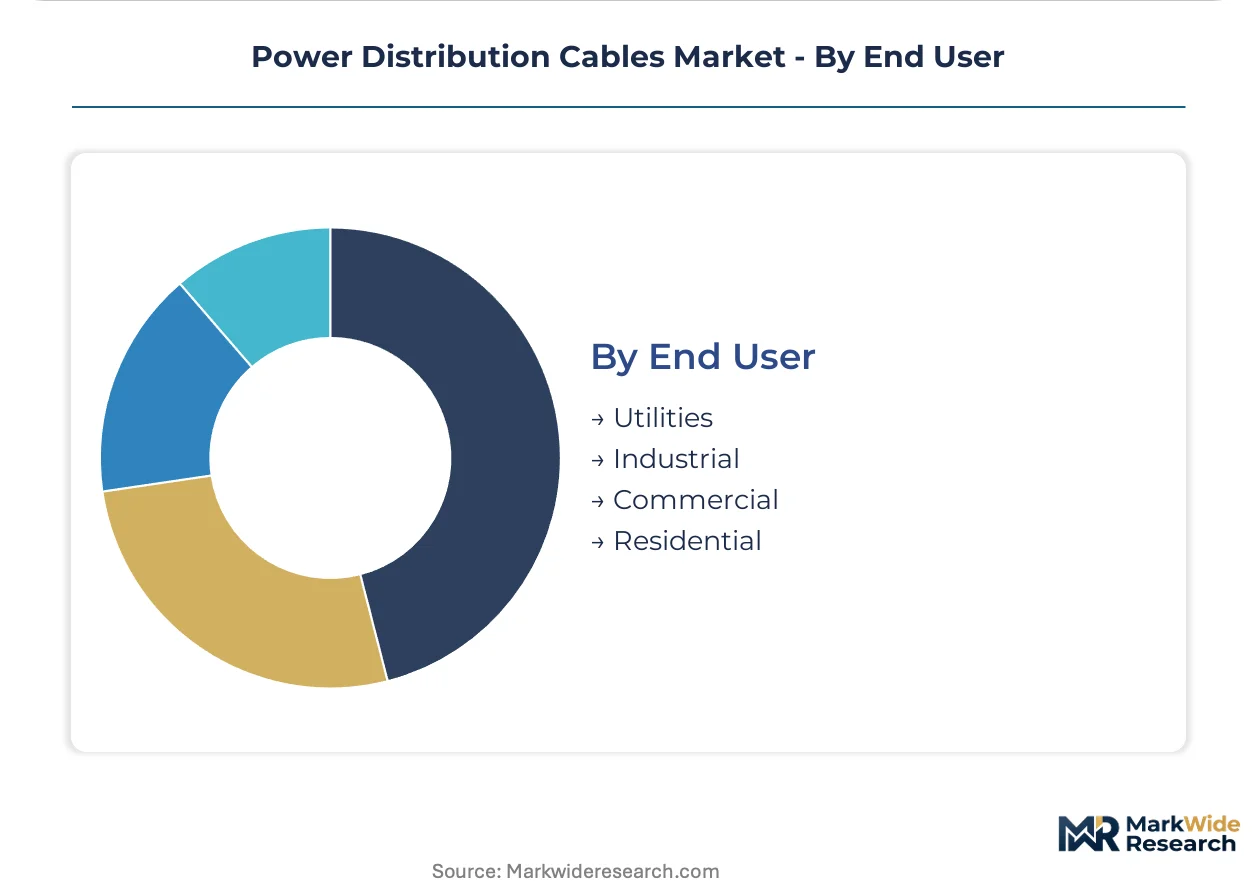
End User:
Procurement centralization varies dramatically: utilities consolidate through multi-year framework agreements, while industrial and commercial buyers negotiate project-specific contracts. Volume concentration sits with transmission system operators.
- Utilities:Transmission and distribution system operators specify cables through centralized procurement with bundled installation supervision. German and French tenders favor integrated service providers, while Chinese State Grid drives massive cross-province ultra-high-voltage programs.
- Industrial:Manufacturing facilities, mining operations, and petrochemical complexes demand specialized mechanical and chemical resistance. Indian industrial corridor expansion and Middle East desalination plants absorb heavy-duty armored constructions.
- Commercial:Office complexes, retail centers, and logistics facilities prioritize fire-rated and halogen-free specifications for occupant safety. European CSRD disclosure requirements and green building certifications tighten material traceability demands.
- Residential:Single-family and multi-unit housing construction drives low-voltage building wire consumption. Chinese urban undergrounding programs and North American housing starts determine cyclical demand patterns.
Utilities absorb the dominant share of high-value cable procurement; commercial segments are gaining share fastest from electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and German cable fabricators export submarine and extra-high-voltage systems to North Sea offshore wind developers, while Chinese State Grid Corporation absorbs domestic ultra-high-voltage output for cross-province interconnectors.
United States
FERC grid reliability standards and EPA environmental permitting compress project timelines for underground transmission corridors. The Inflation Reduction Act domestic content adders redirect procurement toward North American fabrication capacity. Data center clusters in Northern Virginia and Dallas-Fort Worth specify duct infrastructure for scalable power delivery.
Germany
Distribution system operators bundle engineering, installation supervision, and long-term service contracts through multi-year framework agreements. EU Green Deal national replacement mandates accelerate XLPE-insulated underground procurement for urban resilience. Industrial demand concentrates in the Ruhr region and Bavarian manufacturing corridors.
China
State Grid Corporation drives massive metropolitan burial programs and cross-province ultra-high-voltage interconnectors. GB standards and IEC protocols force parallel certification tracks for manufacturers serving both domestic and export markets. Yangtze River Delta cities absorb specialized high-capacity cable output for dense grid infrastructure.
India
Central Electricity Authority mandates for renewable evacuation infrastructure create demand for 765kV and 1200kV land cable systems. BIS certification requirements filter procurement toward qualified domestic and joint-venture suppliers. Western and southern states concentrate manufacturing and installation activity around Mumbai-Pune and Chennai-Bengaluru industrial belts.
France
REACH substance restrictions and EU Green Deal carbon footprint disclosures tighten material traceability requirements across cable procurement. Distribution system operator tenders favor integrated service providers capturing dominant annual volume. Nuclear fleet modernization and offshore wind connection corridors drive specialized submarine cable contracting.
Power Distribution Cables Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and qualification depth. The supplier pool stratifies into three tiers: vertically integrated European majors with submarine cable vessel fleets, Asian conglomerates with captive metal supply and domestic utility relationships, and regional fabricators focused on low-voltage building wire and industrial segments. Consolidation pressure intensifies as extra-high-voltage project scale demands in-house compounding and cleanroom extrusion capabilities. Strategic moves center on backward integration into insulation compound production and multi-year framework agreements bundling engineering with installation supervision.
Among European-based suppliers, Prysmian Group and Nexans occupy positions within the integrated service tier, while Sumitomo Electric Industries exemplifies the Asian conglomerate archetype with diversified industrial and infrastructure exposure. These three anchors represent the qualification bottleneck for extra-high-voltage submarine and land-based transmission projects, where limited certified suppliers concentrate procurement decisions. Regional specialists in low-voltage and medium-voltage categories face margin compression from metal price volatility and centralized utility purchasing power.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Sumitomo Electric Industries |
| LS Cable & System |
| Southwire Company |
| General Cable |
| Schneider Electric |
| ABB |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions and EU Green Deal carbon disclosure mandates gate both supplier qualification and price differentiation simultaneously, forcing cable manufacturers to maintain parallel certification tracks that inflate overhead while segmenting procurement tiers by traceability depth. Buyers with stringent documentation requirements pay premiums for halogen-free compounds and circular feedstocks, while commodity tenders in emerging economies prioritize bare-metal pricing.
Pricing Analysis
Conventional XLPE systems, enhanced treeing-resistant formulations, and emerging superconducting cables occupy distinct pricing tiers separated by manufacturing complexity and qualification depth. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling intensity. Price differentiation hinges on IEC/GB dual certification status and volume scale commitments. Cost compression in standard-grade medium-voltage segments is intensifying because Chinese State Grid procurement centralization concentrates purchasing power. Commercial data center operators exhibit least price sensitivity due to uptime guarantees, while residential construction contractors in North American markets drive hardest bargain negotiations.
Supply Chain Analysis
Extended lead times for specialized insulation compounds and cleanroom extrusion capacity have compressed inventory buffers across the value chain. Manufacturing concentrates in China, Italy, and Germany, with submarine cable laying vessel fleets anchored in European waters. Raw material dependencies center on LME copper cathodes, aluminum ingots, and polymer additives from petrochemical complexes. Single-source vulnerability concentrates in extra-high-voltage cleanroom extrusion capacity numbering fewer than ten qualified facilities globally. Distribution runs through utility procurement departments consolidating multi-year framework agreements with bundled installation supervision.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid undergrounding mandates and offshore wind interconnection requirements fragment procurement across voltage classes and installation methodologies, creating specialized niches for qualified suppliers. Demand-side shift toward bundled engineering-installation-service contracts displaces traditional specification-bid-build models.
For Market Incumbents: Fortify backward integration into insulation compound production to capture margin pools eroding from metal price volatility. Deepen captive supply of enhanced treeing-resistant XLPE formulations to defend against emerging superconducting cable substitutes. Expand cleanroom extrusion capacity in European manufacturing corridors to pre-empt submarine cable project queue bottlenecks. For New Entrants and Emerging Players: Differentiate on superconducting cable fault-current limiting applications for data center clusters and dense metropolitan substations. Target India's 765kV and 1200kV renewable evacuation infrastructure as the most penetrable geography with limited qualified domestic suppliers. Pursue joint-venture partnerships with established metal fabricators to bypass capital barriers in high-voltage certification. For Investors and Strategic Acquirers: EU Green Deal national replacement mandates reshape the acquisition landscape toward integrated service providers with bundled installation capabilities. Five-to-ten-year viability favors vertically integrated cable fabricators with in-house vessel fleets and compound production. Target acquisition archetype: mid-tier European manufacturers with submarine qualification and distressed capacity utilization. Signal to monitor: FERC domestic content rulemaking tightening under IRA implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Production | Captive XLPE formulation supply insulates margins from petrochemical price swings and REACH compliance gaps. |
| Submarine Cable Vessel Fleet Expansion | Dedicated installation capacity breaks project queue bottlenecks threatening offshore wind developer financing windows. |
| Dual IEC-GB Certification Investment | Parallel qualification tracks unlock State Grid procurement while maintaining European export eligibility. |
| Superconducting Cable Commercialization Partnership | Liquid nitrogen-cooled HTS systems target data center fault-current limiting applications in dense urban substations. |
| Multi-Year Framework Agreement Consolidation | Bundled engineering-installation-service contracts capture 70-80% of German and French distribution operator volume. |
Study Parameters
A spread of perspectives from utility procurement directors, submarine cable project developers, EPC contractors, and polymer compound technical leads converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation from IEC certification databases, FERC interconnection filings, State Grid Corporation tender disclosures, and EU Green Deal implementation tracking. Customs records for copper and aluminum trade flows, alongside EIA grid infrastructure investment data, anchored supply-side sizing. Bottom-up project pipeline aggregation triangulated against top-down voltage-class demand modeling.
Voltage class, insulation chemistry, installation topology, and end-user procurement centralization formed the segmentation dimensions modeled across the projection horizon. Analytical framework derived CAGRs from utility capital expenditure trajectories, renewable interconnection queue depth, and grid modernization policy implementation pacing. Forecast inputs incorporated State Grid Corporation five-year plan targets, EU offshore wind connection corridor buildout schedules, and Indian Central Electricity Authority renewable evacuation mandates.
Forecasts assume regulatory continuity in REACH substance restrictions, EU Green Deal carbon disclosure mandates, and FERC grid reliability standards; material policy shifts would require re-modeling. Metal price volatility and submarine cable laying vessel availability constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
AI in Energy Distribution Market
Power Distribution
Distribution Panel Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Global Power Distribution Component Market
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Distribution Board Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Brazil City Gas Distribution Market