
 Cat Food and Snacks Market | 2026-2036
Cat Food and Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Food and Snacks Market Analysis
Urban millennial pet ownership is consolidating as the dominant demand vector for premium formulations. Nestlé Purina PetCare leverages its global manufacturing footprint to anchor shelf presence across mass and specialty channels. Mars Petcare competes through vertical control of protein sourcing and veterinary diet portfolios. Champion Petfoods differentiates via biologically appropriate positioning and limited-ingredient recipes that command price premiums in independent retail.
Cat food and snacks encompass nutritionally complete feeds and intermittent reward products formulated to feline obligate carnivore physiology, typically specifying minimum crude protein thresholds, taurine fortification, and moisture content calibrated to renal health. Wet food and grain-free formulations lead margin pools as consumers trade up from commodity dry kibble toward moisture-rich, ancestral-diet positioning. Treats represent the fastest-growing product type as portion-controlled, functional rewards with dental or hairball claims expand basket size per household. Distribution through pet specialty stores and online retail channels captures the highest-value purchasers, while supermarkets and hypermarkets handle volume tiers.
The FDA enforces food safety standards under the Federal Food, Drug, and Cosmetic Act, while AAFCO establishes model regulations for nutritional adequacy claims that state feed control officials adopt variably. The EU's FEDIAF nutritional guidelines and REACH chemical safety protocols shape ingredient eligibility and labeling for products entering European markets. Stakeholders must monitor evolving regulatory divergence between jurisdictions and decide whether to formulate region-specific recipes or pursue harmonized global standards that simplify supply chain complexity.
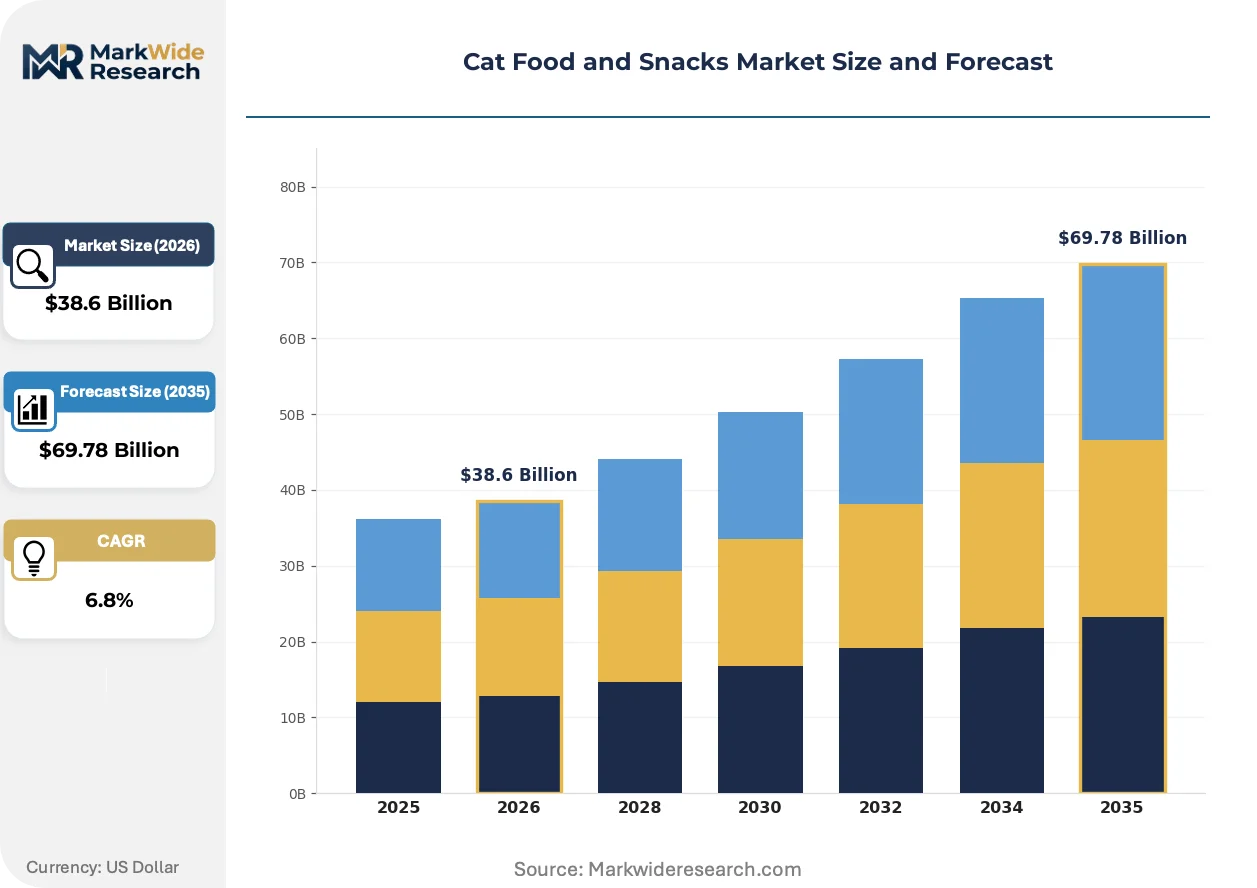
Market Dynamics
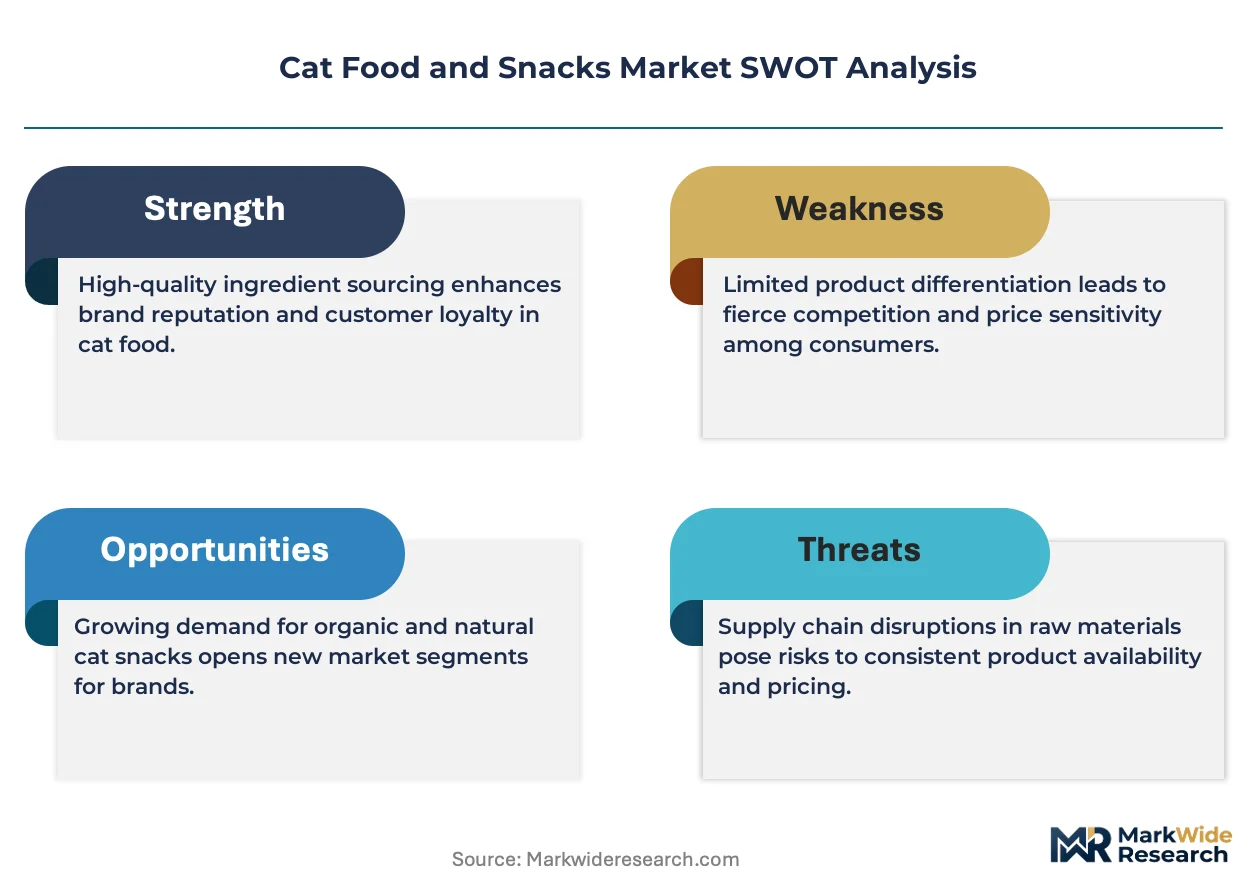
Humanization of feline companionship is consolidating purchasing power toward functional, ingredient-transparent formulations that command sustained price premiums across wet, dry, and treat categories.
Growth Catalysts
- FDA ingredient disclosure mandates:Nutritional transparency requirements under the Federal Food, Drug, and Cosmetic Act compel manufacturers to reformulate with named protein sources, accelerating consumer trust and category trade-up.
- AAFCO nutritional adequacy protocols:State-level adoption of model regulations standardizes taurine fortification and moisture content claims, reducing formulation ambiguity for obligate carnivore physiology.
- Brazilian pet humanization acceleration:Urban household formation and delayed childbearing in São Paulo and Rio de Janeiro concentrate demand for premium wet food and functional treats.
Market Restraints
- Animal protein input volatility:Chicken, fish, and novel protein sourcing face price pressure from human food industry competition and climate-driven supply fluctuations.
- Midwest US rendering concentration:Captive supply of meat meals and fats clusters among a limited processor base, creating single-source vulnerability for co-manufacturers.
- EU REACH chemical safety protocols:Restricted substance lists for packaging materials and processing aids complicate cross-border formulation consistency.
Strategic Opportunities
- Chinese tier-two city penetration:Chengdu, Hangzhou, and Wuhan exhibit underdeveloped specialty retail presence relative to Beijing and Shanghai, creating whitespace for veterinary-channel entry.
- Insect protein convergence with precision fermentation:Black soldier fly larvae and cultivated meat technologies reduce land-use intensity while satisfying ancestral-diet positioning.
- Veterinary telehealth integration:Subscription-based diagnostic platforms embed prescription diet recommendations, locking in recurring therapeutic nutrition revenue.
Industry Challenges
- Feline nutrition specialist scarcity:Veterinary formulation PhDs and clinical trial designers command premium compensation, constraining R&D velocity for mid-tier manufacturers.
- AAFCO feeding trial certification timelines:Six-month protocols for substantiating nutritional adequacy claims delay product launches and tie up capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Food and Snacks Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Type: Meat-Based, Grain-Free, Vegetarian, Organic Distribution Channel: Pet Specialty Stores, Online Retail, Supermarkets, Hypermarkets Package Size: Single Serve, 1-2 lbs, 3-5 lbs, Bulk |
| Companies Covered | General Mills, Champion Petfoods, Nestlé Purina PetCare, Affinity Petcare, Unicharm Corporation, Mars Petcare, The J.M. Smucker Company, WellPet LLC, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Food and Snacks Market Emerging Trajectories
Formulation science and distribution architecture are undergoing parallel reinvention as digital-native consumers demand traceability and convenience simultaneously.
Cold-pressed and minimally processed raw diets are consolidating shelf presence in independent pet specialty channels. Urban millennial adopters in the United States and United Kingdom accept frozen and freeze-dried formats despite refrigeration requirements. This technology is consolidating premium positioning away from extruded kibble by preserving enzyme activity and reducing carbohydrate binding.
EU FEDIAF nutritional guidelines are tightening maximum allowable levels for heavy metals and mycotoxins in complementary pet foods. Manufacturers exporting to Germany, France, and the Netherlands must reformulate treat recipes or source alternative ingredient streams. Wet food and air-dried segments face the steepest compliance costs, accelerating consolidation toward vertically integrated supply chains.
Direct-to-consumer subscription models are compressing traditional distributor margins. Chewy, Amazon, and brand-owned platforms capture recurring dry food and litter bundling relationships that supermarkets cannot match. This channel shift concentrates most visibly in the United States, where same-day delivery infrastructure and auto-ship algorithms lock in household lifetime value.
Cat Food and Snacks Market Segmentation
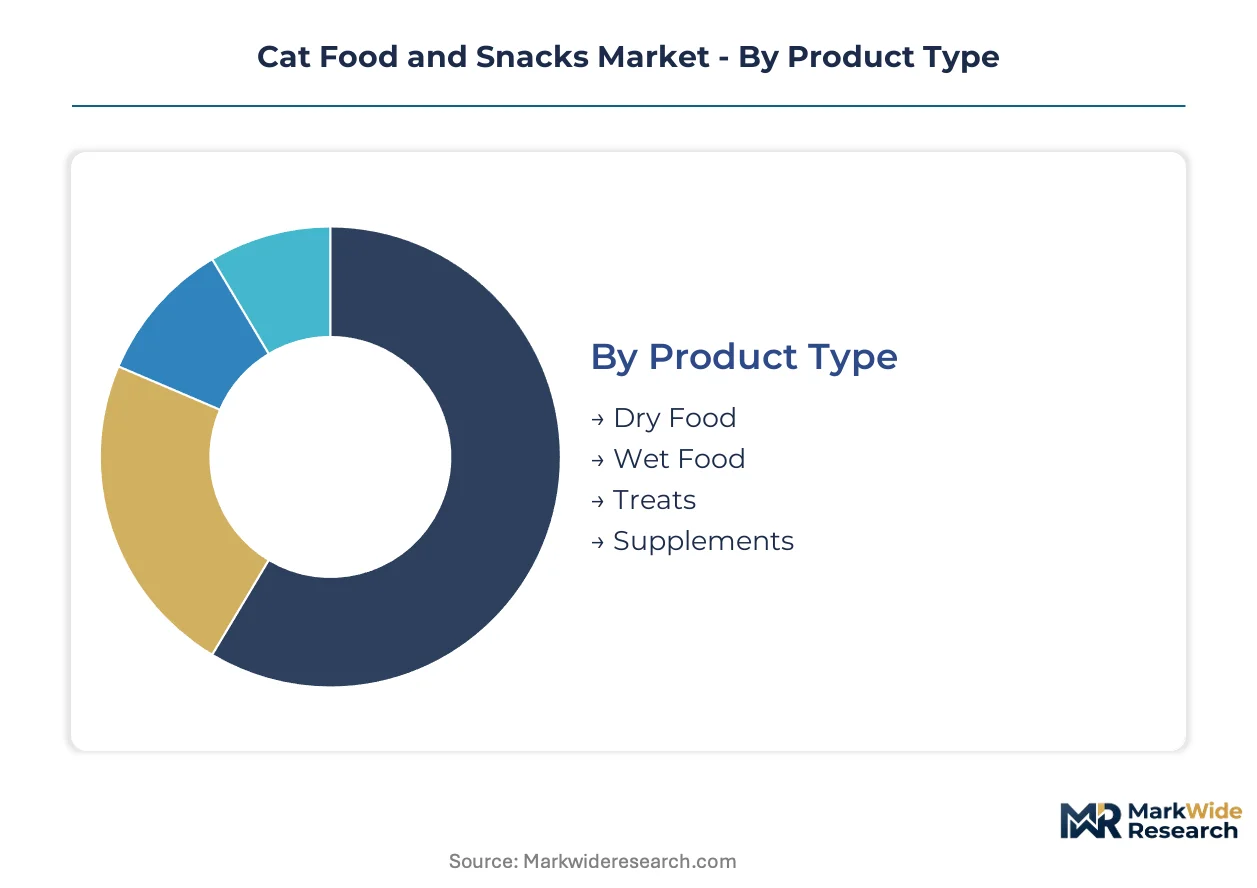
Segmentation in cat food and snacks reveals distinct capital requirements, margin profiles, and channel dependencies that determine manufacturer resource allocation. Each dimension—product format, ingredient sourcing, distribution reach, and packaging scale—imposes unique fixed-cost burdens and working capital cycles.
Product Type:
Capital intensity peaks with wet food manufacturing, where retort processing and sterile filling lines demand eight-figure infrastructure commitments.
- Wet Food:Retort-cooked cans and pouches require sterile filling lines, steam sterilization tunnels, and metal detection systems. Demand concentrates in São Paulo and Shanghai apartment complexes where refrigeration infrastructure supports fresh-portion feeding rituals. The moisture-rich format commands shelf space premiums in pet specialty stores.
- Treats:Extruded and baked reward products carry lower equipment barriers but require rapid flavor-innovation cycles to sustain basket expansion. Urban millennial households in the United States and United Kingdom drive functional treat adoption for dental and hairball management claims.
- Dry Food:Extrusion and coating technology scales efficiently but faces commodity margin compression in mass retail channels.
- Supplements:Powder and liquid fortification products target veterinary-channel distribution with clinical substantiation requirements.
Wet food absorbs the bulk of installed capacity; treats are expanding most quickly.
Ingredient Type:
Formulation costs stratify sharply based on protein provenance and certification overhead, with organic and novel protein streams carrying the steepest procurement premiums.
- Meat-Based:Named muscle meat and organ inclusion satisfies ancestral-diet positioning and AAFCO amino acid thresholds. Brazilian and Chinese consumers trade up for chicken, fish, and beef-first ingredient decks despite input price volatility.
- Grain-Free:Legume and tuber carbohydrate substitution addresses perceived gluten sensitivity while maintaining extrusion functionality. This segment captured early-mover premium positioning before FDA DCM investigations introduced formulation caution.
- Organic:USDA Organic or equivalent certification restricts synthetic additive use and mandates third-party audit trails.
- Vegetarian:Plant-protein concentrates with synthetic taurine fortification target niche ethical-consumption households.
Meat-based formulations dominate volume throughput; grain-free recipes face margin compression from regulatory scrutiny.
Distribution Channel:
Channel selection determines working capital intensity, with direct-to-consumer platforms requiring inventory risk transfer and pet specialty demanding promotional spend.
- Pet Specialty Stores:Independent and chain retailers capture the highest-value purchasers through assisted selling and prescription diet access. The United States and United Kingdom concentrate specialty-format expansion.
- Online Retail:Chewy, Amazon, and brand-owned platforms compress distributor margins through auto-ship algorithms and same-day delivery infrastructure.
- Supermarkets:Mass-market placement drives volume tiers with promotional dependency and private-label competition.
- Hypermarkets:Big-box formats in Brazil and China consolidate one-stop pet care purchasing with bulk-pack velocity.
Pet specialty stores anchor premium pricing power; online retail is gaining share fastest.
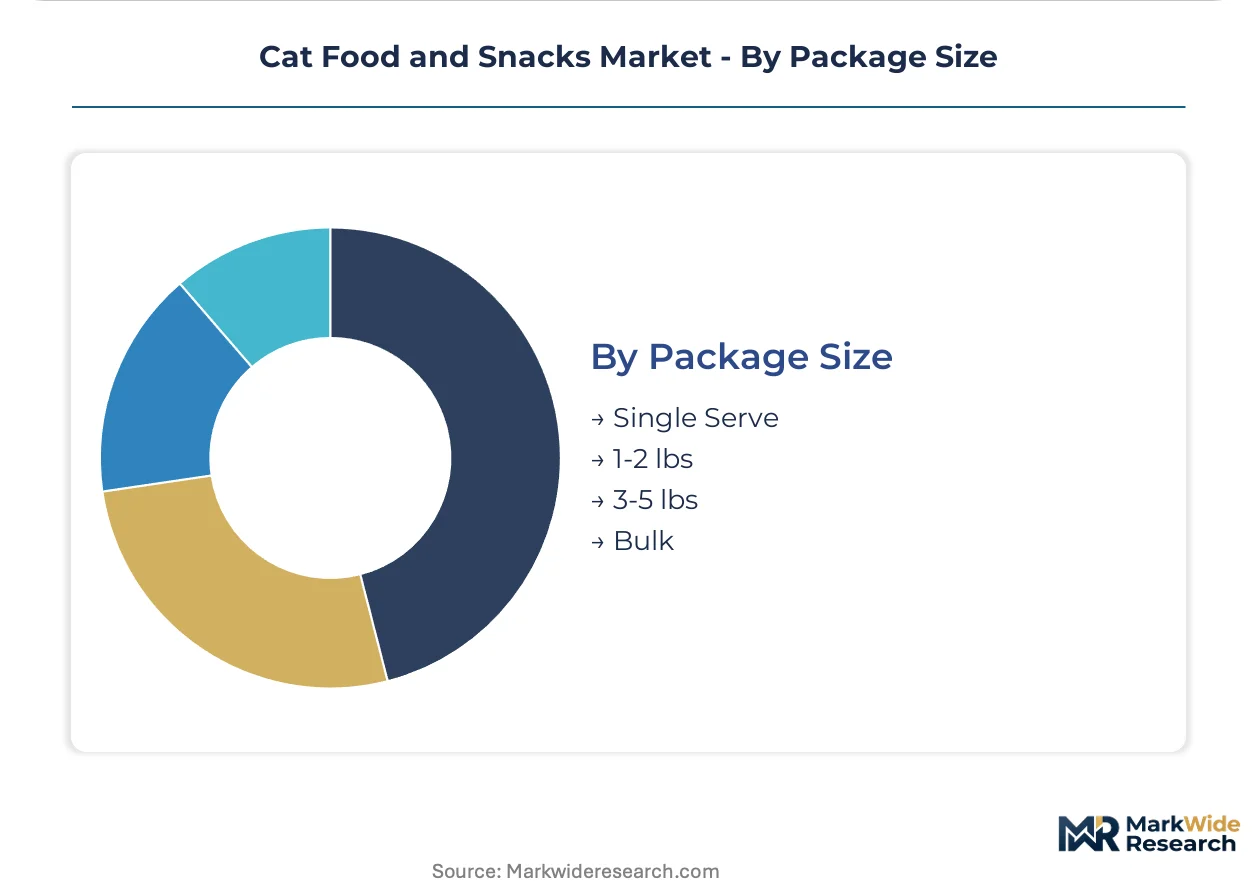
Package Size:
Packaging line changeover economics and logistics density shape profitability across portion formats.
- Single Serve:Individual pouches and cups eliminate refrigeration waste for small households and travel occasions. Urban single-cat apartments in Tokyo and New York drive convenience-premium acceptance.
- 3-5 lbs:Mid-size bags balance freshness preservation with per-pound cost efficiency for multi-cat households.
- 1-2 lbs:Trial-size and rotation-diet formats reduce commitment risk for flavor experimentation.
- Bulk:Warehouse-club and veterinary-channel sacks minimize per-unit packaging cost for stable-formula households.
Bulk formats absorb manufacturing scale efficiencies; single-serve portions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States and Brazil while consumption concentrates in urban China and Western Europe. This geographic split creates trade flows of rendered proteins and specialty ingredients from production hubs to demand centers. Currency volatility and shipping costs periodically reshape procurement patterns.
United States
Millennial pet owners in Austin, Denver, and Seattle drive premium wet food adoption through subscription channels. FDA enforcement of the Food Safety Modernization Act tightens supplier verification requirements for imported fish meals. Rendering infrastructure concentrates in Iowa and Nebraska, supplying meat-based proteins to co-manufacturers nationwide.
China
Apartment-dwelling cat households in Chengdu, Hangzhou, and Wuhan expand faster than specialty retail penetration, creating veterinary-channel whitespace. SAMR implements stricter pet food labeling standards aligning with GB national standards for nutritional claims. Yangtze River Delta manufacturing zones scale freeze-dried treat production for domestic and export markets.
Brazil
São Paulo and Rio de Janeiro pet humanization trends concentrate demand for imported premium formulations despite local currency pressure. ANVISA harmonizes ingredient approval pathways with MERCOSUR trade bloc standards, accelerating novel protein registrations. Southern Brazilian poultry processing clusters supply rendered meals to regional pet food plants.
Germany
Berlin and Munich households lead European adoption of organic and insect-protein cat diets. EFSA and BfR coordinate maximum residue limits for mycotoxins in complementary pet foods, forcing treat reformulation. Bavarian distribution hubs channel Central European logistics for wet food imports from France and the Netherlands.
Japan
Tokyo and Osaka single-person households sustain demand for single-serve pouches and functional dental treats. MAFF and JAS organic certification programs restrict synthetic additive use in premium segments. Chubu region manufacturing bases produce specialized hydrolyzed protein diets for veterinary prescription channels.
Cat Food and Snacks Market Vendor Landscape
Top-tier vendors anchor mass-market shelf presence through global manufacturing footprints, while mid-tier specialists capture premium positioning in independent channels. The vendor base stratifies across three tiers: multinational consumer goods conglomerates with veterinary portfolios, independent biologically-appropriate formulators, and private-label suppliers serving retail banners. Strategic archetypes include protein-source controllers, direct-to-consumer platform operators, and therapeutic nutrition certifiers. Competitive moves concentrate on backward integration into rendering and novel protein cultivation, plus subscription algorithm development for recurring revenue capture.
Within the multinational tier, Nestlé Purina PetCare and Mars Petcare exemplify scale-driven supply chain architectures spanning mass and specialty channels. Champion Petfoods occupies a position exemplifying biologically-appropriate positioning through limited-ingredient recipes. These three anchors demonstrate how geographic manufacturing distribution, protein sourcing depth, and veterinary relationship density separate competitive outcomes in premium versus volume segments.
| Leading Market Players |
|---|
| General Mills |
| Champion Petfoods |
| Nestlé Purina PetCare |
| Affinity Petcare |
| Unicharm Corporation |
| Mars Petcare |
| The J.M. Smucker Company |
| WellPet LLC |
| Hill's Pet Nutrition |
| Others |
Supply Flow & Price Mechanics
EU REACH chemical safety protocols gate both qualified packaging suppliers and premium-tier pricing access, as compliance certification becomes a non-negotiable threshold for European market entry and functional treat positioning.
Pricing Analysis
Margin tightening in standard dry kibble traces to commodity protein input competition from human food sectors and private-label expansion in mass retail channels. Pricing stratifies across premium, standard, and economy tiers based on named-protein ingredient decks and AAFCO feeding trial certification status. Cost compression accelerates in economy tiers as Brazilian and Chinese co-manufacturers absorb currency-driven feedstock volatility. Veterinary-channel therapeutic diets exhibit lowest price sensitivity; supermarket private-label shoppers demonstrate highest elasticity.
Supply Chain Analysis
Animal protein supply rests on Midwest US rendering infrastructure, Thai fish meal processing, and Brazilian poultry byproduct clusters. Key inputs include chicken meal, fish hydrolysates, and novel insect protein streams. Single-source vulnerability concentrates in Iowa-Nebraska meat meal processors, creating disruption risk for co-manufacturers dependent on captive supply. Distribution runs through pet specialty assisted-selling formats for premium tiers, with direct-to-consumer platforms compressing traditional distributor margins in the United States and United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA ingredient disclosure mandates under the Food Safety Modernization Act erect a cost-of-compliance barrier that rewards incumbent scale while filtering out undercapitalized regional formulators.
For Market Incumbents: Extend backward integration into novel protein cultivation and precision fermentation capacity to lock in ancestral-diet positioning as insect-based and cultivated meat alternatives displace conventional rendering. Champion Petfoods and Mars Petcare have already anchored veterinary relationship density; mid-tier players must match AAFCO nutritional adequacy certification velocity or cede shelf space to co-manufacturers with captive clinical trial infrastructure. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for challenger brands, particularly in Chinese tier-two cities where veterinary-channel whitespace exceeds specialty retail development. Freeze-dried treat formats carry lower retort infrastructure barriers than wet food, enabling rapid flavor-innovation cycles without eight-figure capital commitments. Target urban millennial households through functional dental and hairball management claims that command basket expansion premiums. For Investors and Strategic Acquirers: AAFCO feeding trial certification backlog duration is the leading indicator that feline nutrition specialist scarcity will deepen, elevating acquisition premiums for manufacturers with in-house veterinary formulation PhDs and established clinical protocol relationships. Vertically integrated players with rendering assets and direct-to-consumer algorithm development capabilities represent the most defensible long-term positioning across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Novel Protein Supply Agreement | Black soldier fly larvae contracts with Dutch and Singaporean cultivators secure ancestral-diet positioning credentials for premium treat lines. |
| Veterinary Telehealth Integration | Subscription diagnostic platforms embedding Hill's Pet Nutrition prescription recommendations lock recurring therapeutic nutrition revenue streams. |
| Cold-Pressed Manufacturing Scale-Up | Freeze-dried and raw diet capacity expansion in Colorado and Bavaria captures urban millennial trade-up from extruded kibble. |
| AAFCO Certification Fast-Track | Six-month feeding trial protocol acceleration reduces inventory lock-up and improves new product launch velocity against competitors. |
| Single-Serve Packaging Innovation | Retort pouch line investments in Yangtze River Delta manufacturing zones address Tokyo and New York apartment-dwelling convenience demand. |
Methodological Framework
Multi-period observation of FDA enforcement patterns, AAFCO model regulation adoption timelines, and SAMR labeling standard implementations anchored the trend analysis, supplemented by interviews with pet food formulation scientists, veterinary nutrition specialists, pet specialty retail category managers, and co-manufacturing procurement directors. Secondary validation drew from FDA Warning Letter databases, FEDIAF nutritional guideline publications, ANVISA ingredient approval registries, and customs trade flow records for rendered protein inputs. Bottom-up SKU-level pricing analysis triangulated against top-down manufacturer revenue segmentation.
Segment-weighting across product format, ingredient sourcing tier, distribution channel, and package size dimensions informed volume and value projections throughout the forecast period. CAGRs were derived from category growth rate differentials applied to base-year market sizing, with wet food and treat segment trajectories calibrated against pet humanization indices in the United States, China, and Brazil. Novel protein technology adoption curves and veterinary telehealth penetration rates supplied industry-specific forecast inputs.
Inputs from regulatory filing databases and retail audit panels were available through the study window; gaps in private-label manufacturer cost structures and exact co-manufacturing contract terms introduce uncertainty bands around margin compression assumptions. Forecasts reflect documented assumptions regarding currency stability and protein input price trajectories. AAFCO protocol timeline revisions, REACH substance list updates, and Brazilian real volatility warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Process Equipment Market
Others
PC As a Service Market
Others
Sports Events Market
Others
Global Augmented Reality in Retail Market
Others
Legal Services Market
Others
Three Proofing Rugged Tablet Market
Others
Spain Automotive LED Lighting Market
Others
Document Camera Market
Others
Space Power Supply Market
Others
Safety Critical Software Testing Market
Others
Egg Market
Others
United States Printed Signage Market
Others
Ceramic Machinery Market
Others
Australia Content Services Platform Market
Others
Europe Flow Battery Market
Others
Mobile Social Networks Market