
 Balsa Wood Market | 2026-2036
Balsa Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Balsa Wood Market Analysis
Modular core kit configurations are shifting buyer procurement patterns in wind energy and marine composites, replacing bulk raw purchases with precision-cut, bonded panel assemblies. 3A Composites GmbH leverages its European finishing infrastructure to supply pre-engineered balsa kits directly to blade molders. Gurit Holding AG sustains competitive position through captive plantation partnerships in Ecuador that anchor raw fiber supply. DIAB International AB differentiates via hybrid core systems that integrate balsa with PET and PVC foam alternatives.
Balsa wood is a tropical hardwood derived from Ochroma pyramidale, distinguished by density gradients ranging from 40 kg/m³ to 340 kg/m³ that engineers match to specific flexural and compressive load requirements in sandwich composite structures. Solid balsa dominates industrial volume due to its through-thickness shear strength and compatibility with vacuum infusion processes used in wind blade production. Marine applications represent the fastest-growing segment as boat builders substitute synthetic cores with FSC-certified balsa to satisfy ESG-linked procurement mandates from European and North American yacht brands.
Ecuador's Ministry of Environment and the Forest Stewardship Council jointly govern export licensing for balsa plantations, while the EU Timber Regulation and REACH constrain chemical treatments applied during core processing. The US EPA and Lacey Act enforcement divisions scrutinize import documentation for illegally harvested tropical timber entering composite supply chains. Stakeholders must monitor certification fragmentation between FSC, PEFC, and emerging national standards as procurement teams harden deforestation-free sourcing requirements without unified audit protocols.
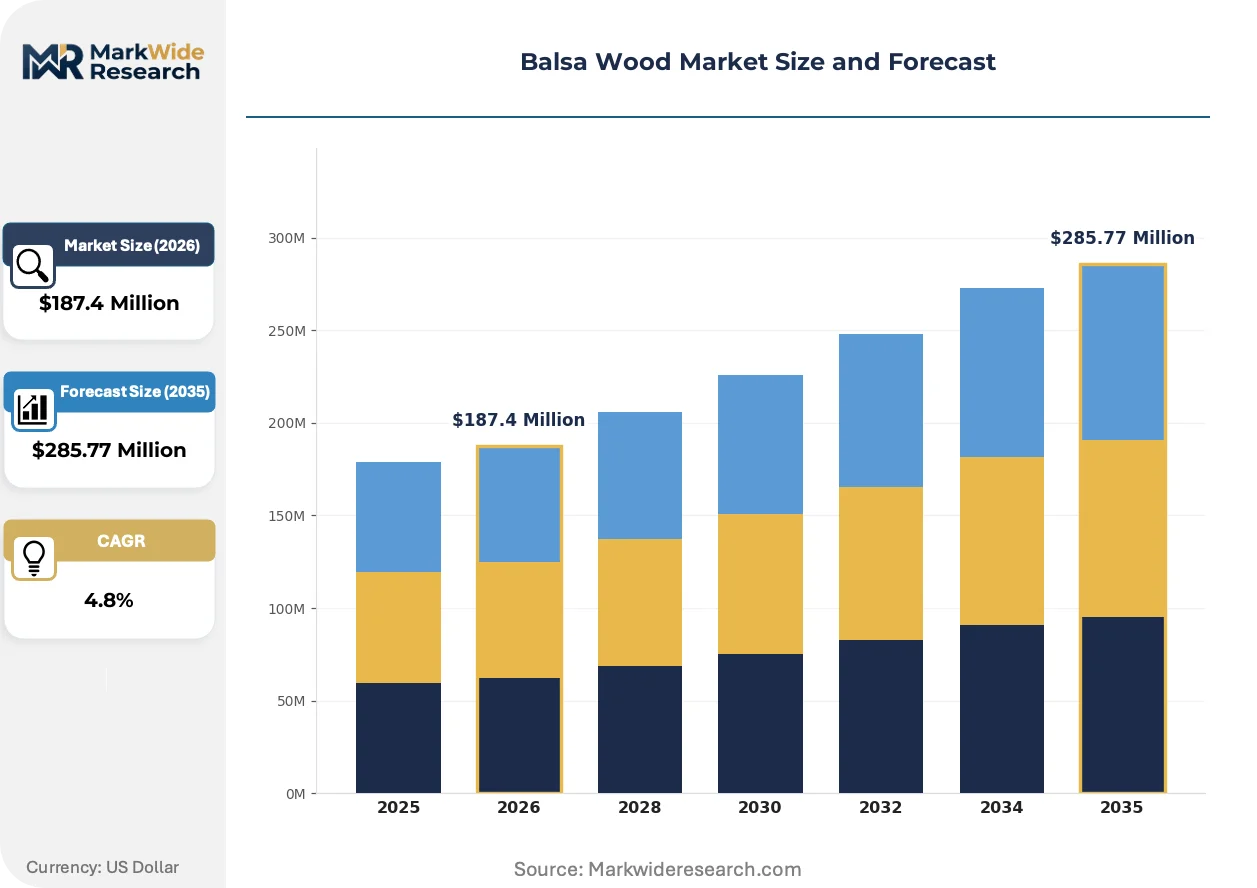
Market Dynamics
Wind turbine OEMs are consolidating core kit procurement around pre-engineered balsa assemblies, compressing raw material spot markets while elevating traceability requirements through FSC chain-of-custody mandates.
Growth Catalysts
- REACH chemical compliance:European blade manufacturers favor balsa over PVC foam cores to avoid restricted substance liabilities under ECHA guidelines.
- Marine composite substitution:Yacht builders in Italy and the Netherlands replace synthetic cores with FSC-certified balsa to meet ESG-linked procurement clauses from charter fleet operators.
- Vacuum infusion compatibility:Solid balsa's through-thickness shear strength enables single-shot resin infusion cycles that reduce blade production time.
Market Restraints
- Ecuador supply concentration:Over sixty percent of plantation volume originates from coastal provinces, exposing buyers to climate-induced harvest volatility and port congestion.
- Petrochemical core substitution:PET and PVC foam alternatives from DIAB and Gurit compete on price stability where balsa density grading adds procurement complexity.
- Wild harvest regulatory friction:Papua New Guinea's export licensing delays under national forestry codes extend lead times for uncertified fiber.
Strategic Opportunities
- India wind installation pipeline:State-level renewable purchase obligations in Gujarat and Tamil Nadu create demand for lightweight blade cores as domestic turbine assembly expands.
- Hybrid core system convergence:Balsa-PET sandwich configurations enable density-graded panels that optimize material cost against aerodynamic load requirements.
- EU Green Deal procurement mandates:Public tender rules for offshore wind projects favor deforestation-free certification, advantaging plantation-traceable balsa over uncertified alternatives.
Industry Challenges
- FSC audit timeline compression:Certification bodies face backlog in plantation assessments, delaying export eligibility for new Ecuadorian suppliers entering European supply chains.
- Precision cutting capex requirements:CNC kit fabrication demands capital investment in moisture-controlled finishing facilities that small plantation operators cannot finance independently.
- Density grading skill scarcity:Manual inspection protocols for matching balsa density to blade station specifications require trained technicians absent in emerging supply regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balsa Wood Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Balsa, Balsa Sheets, Balsa Blocks, Balsa Sticks Application: Model Airplane Construction, Craft Projects, Educational Purposes, Marine Applications End User: Hobbyists, Schools, Manufacturers, Architects Distribution Channel: Online Retail, Specialty Stores, Distributors, Wholesale |
| Companies Covered | CoreLite Inc., Auszac Pty Ltd, 3A Composites GmbH, BALTEK Corporation, Carbon-Core Corp., Gurit Holding AG, Schweiter Technologies AG, GM Balsa Composite S.A., DIAB International AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balsa Wood Market Emerging Trajectories
Material science advances and procurement digitization are converging to transform how balsa core reaches composite manufacturers, with sustainability verification becoming as critical as mechanical performance.
Hybrid core technology is integrating balsa end-grain sections with thermoplastic foam layers to create functionally graded panels. Blade molders in Denmark and Spain are adopting these configurations for root sections where compressive loads peak. The approach is integrating density-specific material placement that reduces overall core mass while preserving structural margins.
EU Timber Regulation enforcement is tightening documentation requirements for tropical hardwood imports into European composite facilities. Customs authorities in Rotterdam and Hamburg now demand GPS-tracked harvest coordinates alongside FSC certificates. Marine yacht builders face the strictest scrutiny, with charter fleet operators auditing supply chain software for real-time chain-of-custody verification.
Direct mill-to-molder contracts are displacing commodity traders in wind blade core procurement. Tier-one turbine OEMs in Germany and China now negotiate multi-year offtake agreements with Ecuadorian plantation groups, bypassing spot markets. This consolidation concentrates volume with vertically integrated processors capable of bonded panel kit delivery, marginalizing raw balsa exporters without finishing infrastructure.
Balsa Wood Market Segmentation
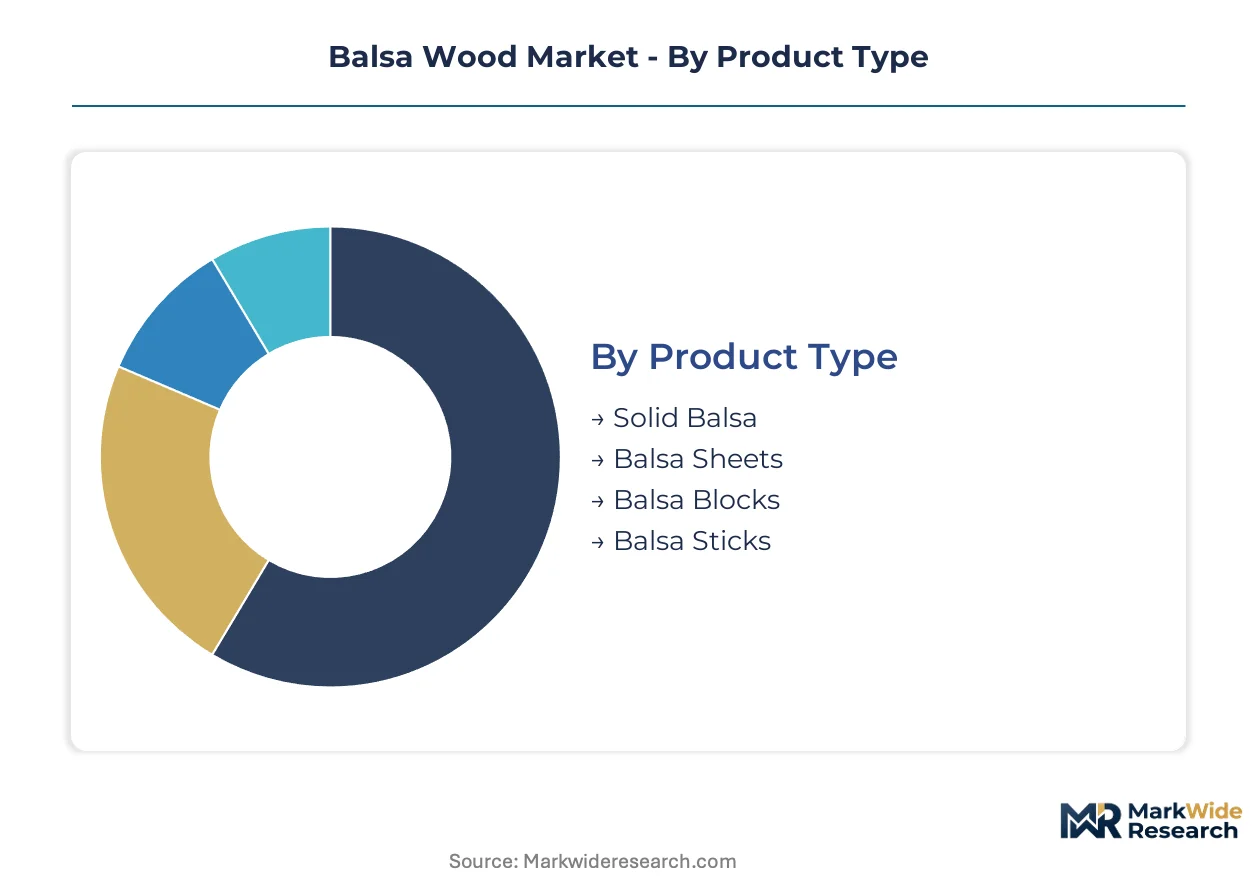
Engineers and procurement teams select balsa grades based on density tolerances and finishing requirements that vary sharply across wind blade fabrication, marine lamination, and precision modeling. Segmentation reveals how raw plantation output funnels into diverging value chains with distinct certification, cutting, and logistics specifications.
Product Type:
Buyers differentiate by structural load requirements and processing compatibility rather than price alone.
- Solid Balsa:End-grain blocks with density gradients from 40 to 340 kg/m³ enable precise matching to flexural modulus targets in wind turbine root sections. Demand concentrates with blade molders in Denmark and Spain pursuing vacuum infusion cycle efficiency.
- Balsa Sheets:Cross-grain panels bonded into core kits supply marine laminators in Italy and the Netherlands replacing synthetic foam under ESG procurement clauses. Kit suppliers capture margin through CNC contouring and moisture-controlled finishing.
- Balsa Blocks:Rough-sawn plantation output serves intermediate processors lacking bonded panel fabrication capacity.
- Balsa Sticks:Dimensioned stock supports model aircraft builders and architectural mockup studios with tight dimensional tolerances.
Volume sits with Solid Balsa; growth tilts toward Balsa Sheets.
Application:
End-use specifications determine whether buyers prioritize FSC certification, density grading precision, or raw material cost.
- Marine Applications:Yacht builders in Italy and the Netherlands substitute FSC-certified balsa for PVC foam cores to satisfy charter fleet ESG audits. REACH compliance advantages over petrochemical alternatives accelerate specification shifts.
- Model Airplane Construction:Competitive glider and RC aircraft builders demand ultra-light 40-80 kg/m³ grades with tight moisture content control.
- Craft Projects:Hobbyist segment purchases smaller dimensional stock through online retail and specialty store channels with limited certification requirements.
- Educational Purposes:School procurement favors standardized block sizes and pre-cut kits over density-graded material.
Marine Applications command premium pricing; Model Airplane Construction maintains volume stability.
End User:
Procurement sophistication spans from spot commodity purchases to multi-year offtake agreements with plantation traceability.
- Manufacturers:Wind turbine OEMs and marine composite laminators negotiate direct mill contracts with Ecuadorian plantation groups, bypassing traders. These buyers demand GPS-tracked harvest coordinates and FSC chain-of-custody documentation.
- Hobbyists:Individual model builders purchase through online retail with minimal traceability requirements and high price sensitivity.
- Schools:Institutional buyers prioritize standardized dimensions and reliable delivery over density grading precision.
- Architects:Scale model studios require tight dimensional tolerances and aesthetic-grade finishing for client presentation work.
Manufacturers dominate absolute consumption; Architects represent the steepest expansion trajectory as presentation model standards tighten.
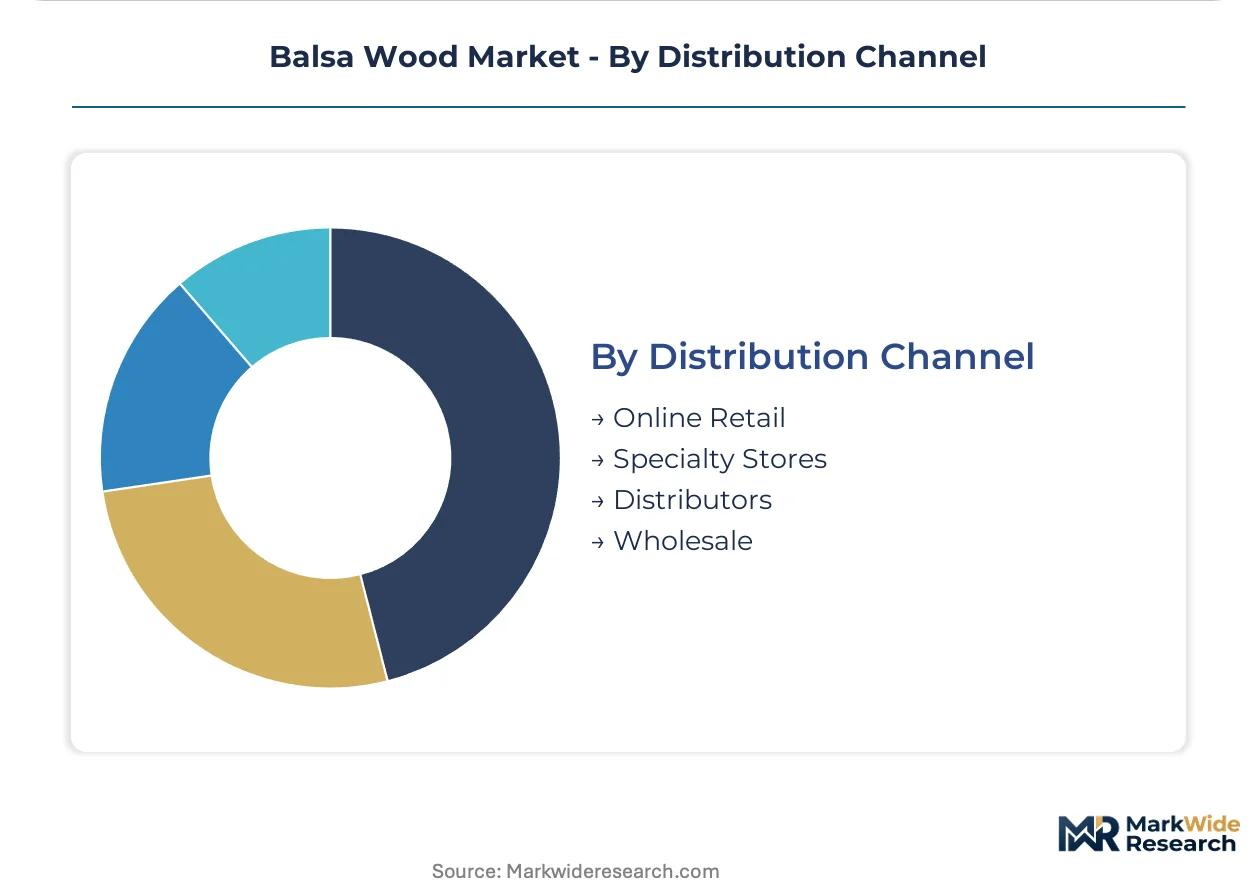
Distribution Channel:
Channel selection reflects buyer scale, technical support needs, and certification documentation requirements.
- Direct Mill Contracts:Tier-one turbine OEMs in Germany and China negotiate multi-year offtake agreements with Ecuadorian plantation processors capable of bonded panel kit delivery.
- Distributors:Regional composite material distributors serve mid-size marine laminators lacking volume for direct plantation contracts.
- Online Retail:Hobbyist and educational segments purchase dimensioned stock through e-commerce platforms with limited technical support.
- Specialty Stores:Model aircraft and craft supply retailers stock standardized sizes for walk-in hobbyist demand.
Direct Mill Contracts capture value; Online Retail expands access fastest in emerging supply regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plantation output concentrates in Ecuador and Papua New Guinea, while consumption clusters in European wind blade fabrication and Asian turbine assembly. This geographic split creates long-haul logistics dependencies and certification friction at destination ports.
Germany
Siemens Gamesa and Nordex blade facilities in Rostock and Bremerhaven drive precision-cut core kit demand. ECHA REACH enforcement restricts PVC foam alternatives, advantaging balsa in vacuum infusion processes. Hamburg customs authorities now require GPS-tracked harvest coordinates alongside FSC chain-of-custody documentation for tropical hardwood imports.
China
Goldwind and Envision turbine assembly lines in Jiangsu and Guangdong provinces scale domestic blade production for offshore wind pipelines. MIIT industrial standards for composite materials emphasize lightweight core adoption in renewable energy equipment. Yangtze River Delta fabricators negotiate direct mill contracts with Ecuadorian plantation groups, bypassing spot commodity markets.
Spain
LM Wind Power and Siemens Gamesa blade molders in Castellón and A Coruña specify density-graded balsa for root sections under compressive load. Spanish port authorities enforce EU Timber Regulation documentation requirements with Rotterdam-equivalent stringency. Basque Country composite clusters test hybrid balsa-PET configurations for next-generation offshore blade designs.
Italy
Ferretti Group and Azimut-Benetti yacht builders in Viareggio and Savona substitute FSC-certified balsa for synthetic cores under charter fleet ESG procurement clauses. Italian environmental regulators align with EU Green Deal deforestation-free mandates for public tender eligibility. Adriatic marine laminators source cross-grain panel kits through regional distributors lacking direct plantation contracts.
India
Suzlon and ReNew Power turbine assembly in Gujarat and Tamil Nadu creates emerging demand for lightweight blade cores under state renewable purchase obligations. BIS standards for wind turbine components remain under development, creating certification gaps for imported core materials. Mundra and Chennai ports handle growing balsa volumes despite limited local density-grading infrastructure.
Balsa Wood Market Vendor Landscape
The competitive structure tilts toward vertically integrated plantation-to-kit processors controlling both raw fiber supply and precision finishing capacity. Market concentration is moderate, with three to five groups capturing wind blade OEM direct contracts while smaller operators serve marine and hobbyist segments through distributor channels. Two archetypes dominate: captive plantation owners with bonded panel fabrication infrastructure, and hybrid core specialists integrating balsa with thermoplastic foam alternatives. Competitive moves center on multi-year offtake agreements with turbine OEMs and backward integration into Ecuadorian plantation partnerships.
Among European-integrated fabricators, 3A Composites GmbH and DIAB International AB exemplify the hybrid core archetype, combining balsa end-grain sections with PET and PVC foam layers for functionally graded panels. Gurit Holding AG represents the captive supply model, with plantation partnerships in Ecuador anchoring raw fiber access for precision-cut kit delivery. These three groups occupy positions that concentrate wind blade OEM procurement, marginalizing raw exporters without finishing infrastructure.
| Leading Market Players |
|---|
| CoreLite Inc. |
| Auszac Pty Ltd |
| 3A Composites GmbH |
| BALTEK Corporation |
| Carbon-Core Corp. |
| Gurit Holding AG |
| Schweiter Technologies AG |
| GM Balsa Composite S.A. |
| DIAB International AB |
| Others |
Supply Flow & Price Mechanics
Plantation gate prices for Ochroma pyramidale fiber cascade through bonded panel fabrication premiums into three-tier pricing structures that separate FSC-certified kit suppliers from raw block exporters and spot-market traders serving hobbyist channels.
Pricing Analysis
Cost-down pressure on precision-cut core kits accelerates because wind turbine OEMs consolidate procurement around multi-year offtake agreements with bonded panel fabricators. Pricing stratifies across premium, standard, and economy tiers based on FSC chain-of-custody certification and density grading precision. Margin tightening in raw block exports traces to petrochemical foam substitution in cost-sensitive marine applications. Hobbyist buyers exhibit highest price sensitivity, while German and Chinese turbine OEMs prioritize traceability over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European hub-and-spoke patterns for FSC-certified material entering blade molders. Raw fiber supply concentrates in Ecuador, Papua New Guinea, and Indonesian plantation developments. Downstream distribution runs through direct mill contracts for tier-one OEMs and composite material distributors serving mid-size marine laminators. Single-source vulnerability in Ecuador's coastal provinces exposes buyers to climate-induced harvest volatility and port congestion at Guayaquil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Balsa Wood Market is consolidating around vertically integrated plantation-to-kit processors as precision cutting capex requirements and FSC audit backlogs force smaller raw exporters from European supply chains.
For Market Incumbents: Anchor competitive position through captive plantation partnerships in Ecuador that secure raw fiber access for bonded panel fabrication. Invest in CNC contouring infrastructure to capture wind blade OEM direct contracts displacing commodity traders. Defend against hybrid balsa-PET substitution by emphasizing REACH compliance advantages in European vacuum infusion applications. For New Entrants and Emerging Players: Regional composite material distributors represent the most accessible channel partner type for penetrating mid-size marine laminators in Italy and the Netherlands lacking volume for direct plantation contracts. Target white-space in India's emerging wind installation pipeline where domestic density-grading infrastructure remains underdeveloped. Pursue kit assembly partnerships with Ecuadorian plantation groups rather than greenfield processing investment. For Investors and Strategic Acquirers: The window for entry favors plantation-integrated processors with FSC certification infrastructure and European finishing capacity. Long-term viability hinges on deforestation-free sourcing mandates hardening across EU Green Deal procurement rules. Watch FSC audit timeline compression as the signal indicating export eligibility bottlenecks for new Ecuadorian suppliers entering premium supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plantation Partnership | Secures raw fiber supply for Gurit and similar integrated processors serving German turbine OEMs. |
| Hybrid Core System Development | Enables DIAB to differentiate through balsa-PET functionally graded panels for Danish blade root sections. |
| Direct Mill Contract Negotiation | Allows 3A Composites to bypass spot markets and supply pre-engineered kits to Spanish molders. |
| FSC Certification Investment | Qualifies Ecuadorian suppliers for EU Timber Regulation compliance and Green Deal tender eligibility. |
| CNC Kit Fabrication Capacity | Creates barrier to entry against raw block exporters lacking moisture-controlled finishing infrastructure. |
Methodological Framework
Multi-period observation of plantation harvest volumes, export licensing timelines, and blade OEM procurement patterns anchored the trend analysis, supplemented by interviews with plantation operations managers, composite material procurement leads at wind turbine manufacturers, marine laminator technical directors, FSC certification auditors, and bonded panel fabrication engineers. Secondary validation drew from Ecuadorian Ministry of Environment export statistics, EU Timber Regulation enforcement disclosures, ECHA REACH guidance documents, and wind industry association supply chain reports. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end user segments.
Input-output matrices structured demand forecasting across density grade tiers, finishing requirements, certification levels, and regional regulatory clusters throughout the projection horizon. CAGRs were derived from segmented growth rate analysis applied to baseline volume estimates. Forecast inputs incorporated wind turbine installation pipelines by country, marine composite substitution rates for synthetic cores, and FSC certification penetration trajectories in plantation supply.
Caveats apply where climate-induced harvest disruptions, Papua New Guinea export licensing delays, or petrochemical foam price volatility could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Computing Devices Market
Others
Middle East Smart Home Market
Others
Computer on Module Market
Others
Global Aircraft Sensors Market
Others
Bimodal Identity Management Solutions Market
Others
Hydrostatic Testing Market
Others
Global Thermally Conductive Grease Market
Others
Military Sensors Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Tunnel Lighting Market
Others
Server Market
Others
Versatile Video Coding Market
Others
Stichtite Market
Others
Pediatric Measuring Devices Market
Others
Global Mobile Video Optimization Market
Others
Mobile Computer Market