
 Wind and Solar Hybrid Street Light Market | 2026-2036
Wind and Solar Hybrid Street Light Market Size, Share, and Industry Trends Forecast 2026-2036
Wind and Solar Hybrid Street Light Market Insights
Municipal procurement channels is fragmenting as city governments bypass traditional electrical contractors and issue direct tenders to renewable lighting specialists. UGE leverages its vertical turbine expertise to anchor large-scale deployments across North American harbor districts. Guangzhou HY Energy Technology dominates manufacturing scale for integrated pole systems shipped to African and Latin American buyers. Eolgreen differentiates through European certification depth, sustaining premium positioning in French and Spanish municipal frameworks.
Wind and solar hybrid street lights combine small-scale vertical axis wind turbines with photovoltaic panels, battery storage, and LED luminaires in a single pole-mounted system designed to operate independently of grid infrastructure. Typical installations incorporate 200-400W wind turbines paired with 100-150W solar arrays and lithium-ion or gel battery banks rated for 3-5 days of autonomous operation, primarily serving roadway illumination in remote, coastal, or grid-constrained environments. Smart Lighting and LED Street Lights command the dominant share of product-type revenue as municipalities prioritize dimming controls and connected infrastructure management. Standalone installations lead deployment volumes where grid extension proves economically unviable, while Integrated systems capture margin pools in urban retrofit projects requiring aesthetic cohesion with existing street furniture.
FCC guidelines govern electromagnetic emissions from wireless control modules embedded in U.S. smart lighting deployments, while the EU Green Deal and F-Gas Regulation restrict refrigerants and insulation materials used in battery thermal management systems sold across European markets. India's BIS certification mandates solar panel efficiency thresholds and wind turbine safety standards for products qualifying under central government street lighting subsidy schemes. Stakeholders must monitor evolving battery chemistry regulations and local content requirements that threaten to segment supply chains into incompatible regional compliance zones.
Market Dynamics
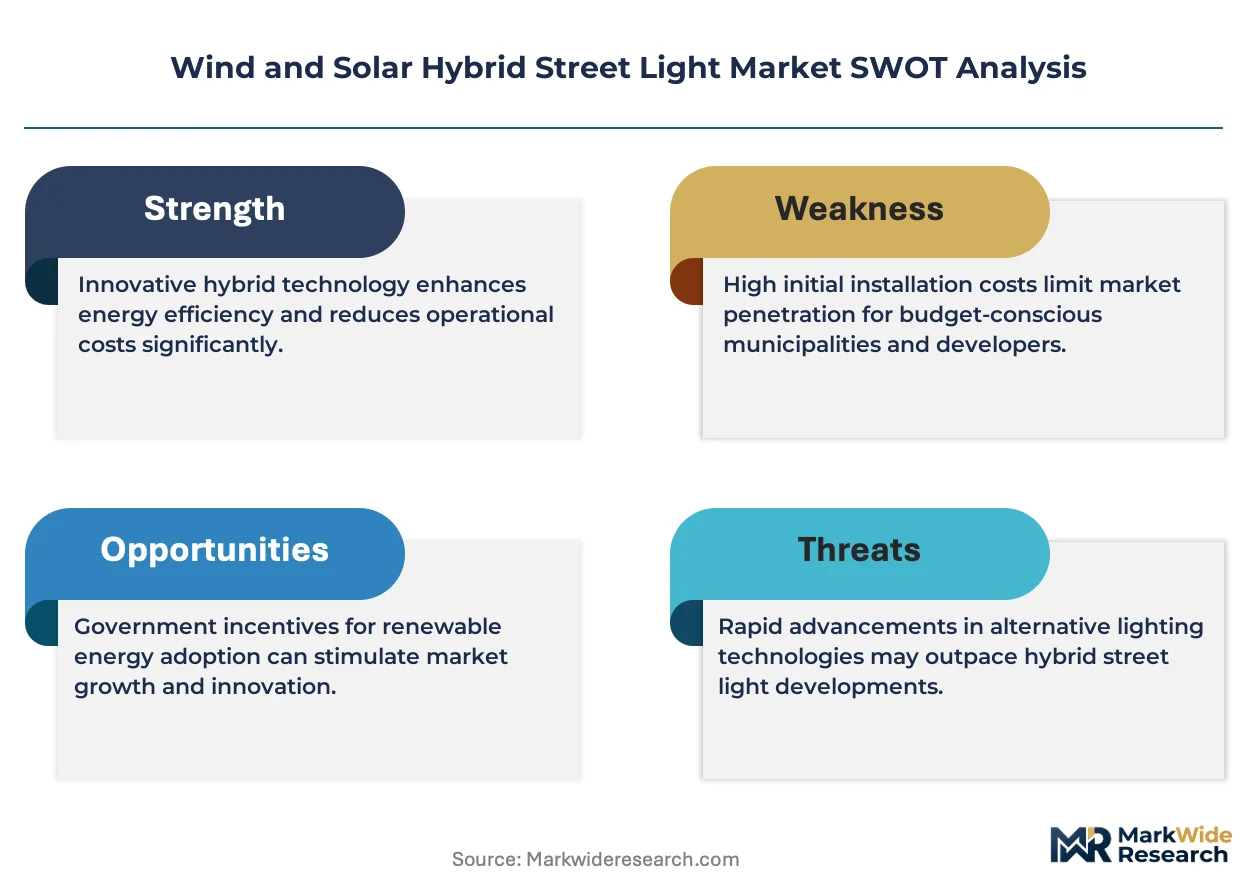
China's dual carbon goals and the EU Green Deal are tightening outdoor lighting efficiency standards, forcing developers toward integrated wind-solar designs that bypass grid dependency entirely. Municipal procurement channels fragment as city governments issue direct tenders to renewable lighting specialists, bypassing traditional electrical contractors.
Growth Catalysts
- India's PLI scheme:Central government street lighting subsidies accelerate adoption across smart city projects, with BIS certification mandating minimum solar panel efficiency thresholds for qualifying products.
- Vertical axis wind turbines:Coastal municipalities in high-wind corridors deploy small-scale VAWT systems paired with photovoltaic arrays to achieve renewable energy mandates without grid extension costs.
- Island nations:Southeast Asian archipelago states prioritize standalone hybrid installations where diesel generator dependence has proven economically unsustainable.
Market Restraints
- Lithium-ion battery supply:Concentration of cathode material processing in China creates input cost volatility and geopolitical exposure for system integrators.
- Technical limitation:Vertical axis wind turbines exhibit reduced efficiency in low-wind urban canyon environments, constraining deployment in dense metropolitan cores.
- EU F-Gas Regulation:Restrictions on refrigerants and insulation materials used in battery thermal management systems add compliance layers for European-bound shipments.
Strategic Opportunities
- African municipal grids:Grid reliability gaps in sub-Saharan urban peripheries create first-mover advantage for standalone hybrid systems with multi-day battery autonomy.
- Smart city convergence:Integration of wind-solar poles with IoT sensors and edge computing nodes transforms street furniture into distributed infrastructure platforms.
- French municipal frameworks:European certification depth unlocks premium positioning in public tender processes that weight environmental performance scoring.
Industry Challenges
- Electromechanical integration expertise:Shortage of technicians capable of servicing combined wind turbine, photovoltaic, and battery storage systems in field conditions.
- Multi-jurisdiction certification timelines:FCC electromagnetic emissions testing for U.S. wireless control modules runs parallel to EU CE marking and Indian BIS processes, stretching product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind and Solar Hybrid Street Light Market |
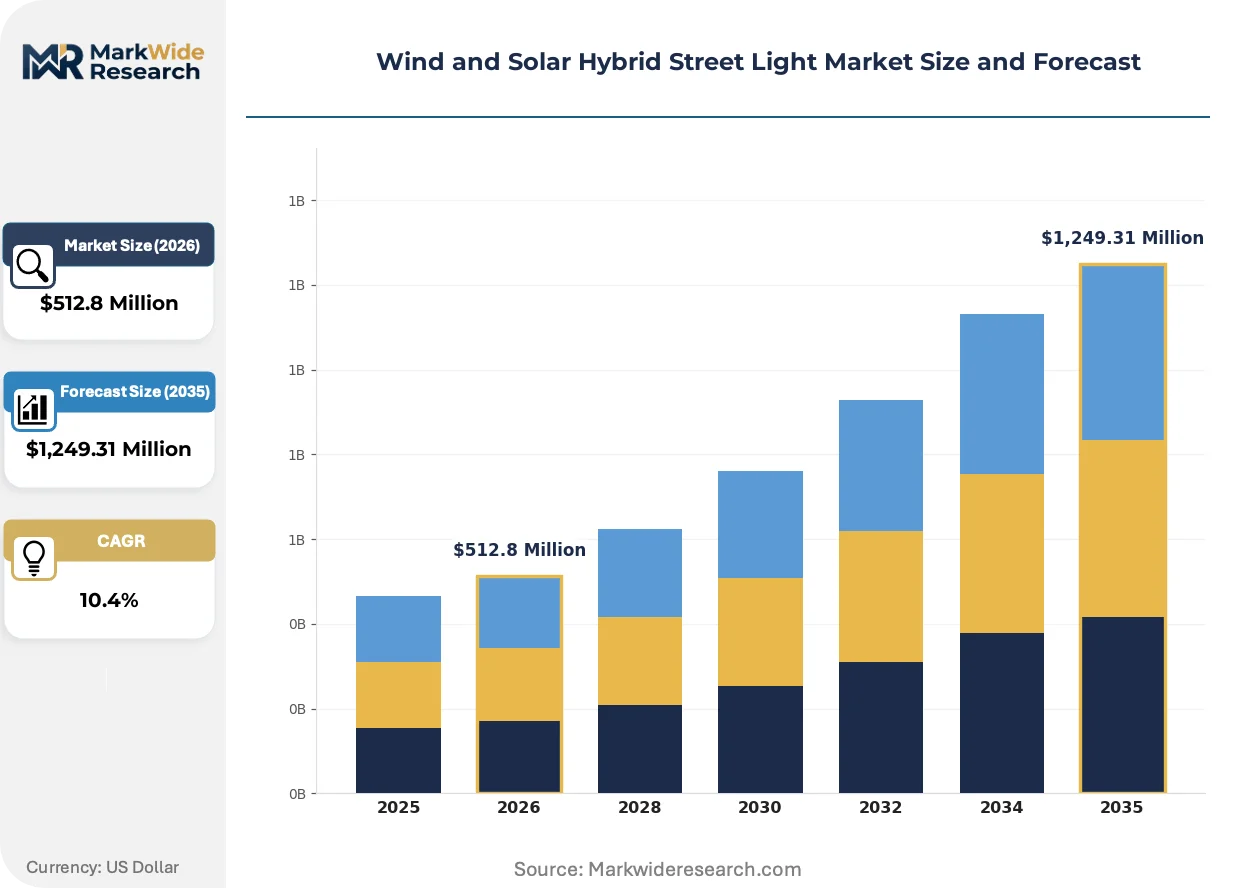
| Market Size in 2026 | $512.8 Million |
| Market Size in 2035 | $1,249.31 Million |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, LED Street Lights, Solar Street Lights, Wind-Powered Lights Installation Type: Standalone, Integrated, Remote, Centralized Power Source: Hybrid, Solar Energy, Wind Energy, Battery Backup End User: Municipalities, Urban Developers, Parks & Recreation, Commercial Properties |
| Companies Covered | UGE, Solar Wind Technologies, Eolgreen, Guangzhou HY Energy Technology, Phono Solar, Shanghai Ghrepower Green Energy, WindStream Energy Technologies, Signify, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind and Solar Hybrid Street Light Market Trends and Innovations
Solid-state battery chemistry and bladeless wind harvesting concepts are compressing the traditional mechanical-electric interface in outdoor lighting infrastructure. These developments reshape competitive positioning around energy density and maintenance intervals rather than component sourcing.
Solid-state lithium-metal batteries with ceramic electrolytes are rendering obsolete gel-cell and conventional lithium-ion configurations in pole-mounted storage applications. Harbor districts across North American coastal zones pilot these systems for their reduced thermal runaway risk and extended cycle life. The technology is rendering obsolete the three-to-five-year battery replacement schedules that have dominated municipal maintenance budgeting.
The EU Green Deal's outdoor lighting efficiency standards now require lifecycle carbon accounting for luminaires and supporting infrastructure. Manufacturers must document embodied emissions from wind turbine casting through battery cell production to qualify for public procurement frameworks. French and Spanish municipal tenders increasingly weight these disclosures above upfront capital cost in award criteria.
Municipal engineering departments now bundle street lighting procurement with smart city sensor deployment, unbundling the traditional electrical contractor relationship. Direct tendering to renewable energy specialists displaces generalist infrastructure bids in coastal Indian states and Southeast Asian island jurisdictions. Vietnam's emerging smart city corridors exhibit this pattern most acutely, with port authorities leading integrated infrastructure pilots.
Wind and Solar Hybrid Street Light Market Segmentation
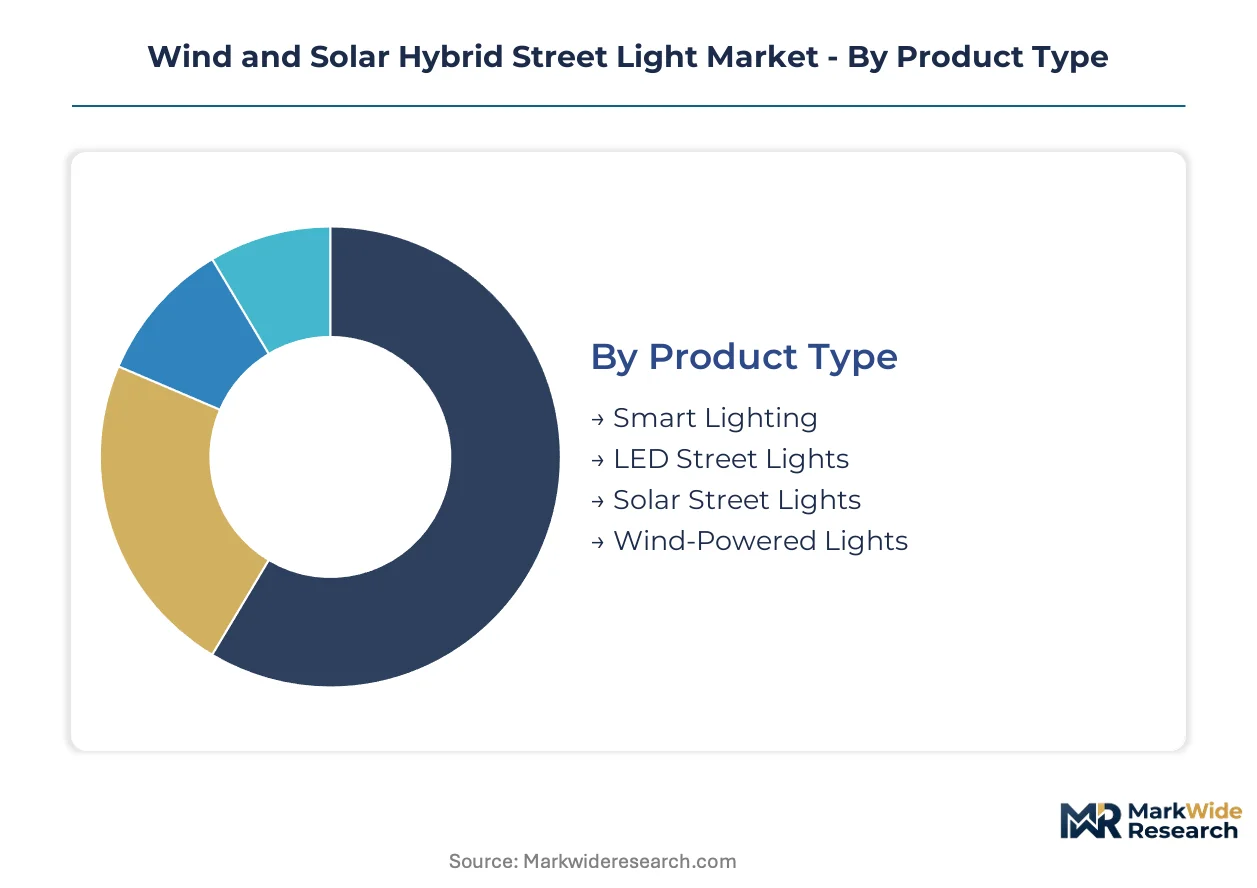
Segmentation in wind-solar hybrid street lighting reveals distinct procurement patterns across technical configurations and institutional buyers. Installation topology and power architecture decisions directly determine system autonomy, maintenance burden, and eligibility for municipal subsidy frameworks.
Product Type:
Cost tier stratification separates premium smart infrastructure from basic illumination hardware, with connectivity modules and sensor integration driving price multiples.
- Smart Lighting:Embedded IoT controllers enable remote dimming, outage detection, and environmental sensor hosting. Coastal Indian municipalities and Vietnamese port authorities bundle these systems with air quality monitoring in direct tender structures.
- LED Street Lights:Solid-state luminaires with 130-150 lm/W efficacy form the baseline illumination layer. Sub-Saharan African urban peripheries prioritize these for standalone deployments where grid extension costs prove prohibitive.
- Solar Street Lights:Photovoltaic-only configurations without wind turbine integration serve low-wind urban canyon environments.
- Wind-Powered Lights:Turbine-dominant systems deploy where consistent coastal or elevated wind resources offset solar intermittency.
Smart Lighting holds installed capacity. LED Street Lights is rotating up the share rankings.
Installation Type:
Application context dictates whether systems operate as isolated infrastructure nodes or mesh with existing electrical and data networks.
- Standalone:Fully autonomous poles with integrated battery banks eliminate trenching and grid connection costs. Southeast Asian island nations and sub-Saharan African municipalities deploy these where diesel generator dependence has collapsed economically.
- Integrated:Aesthetic cohesion with existing street furniture matters in European urban retrofit projects. French and Spanish tenders weight visual integration alongside technical performance in scoring matrices.
- Remote:Satellite-monitored systems serve mining access roads and pipeline corridors with minimal maintenance access.
- Centralized:Pole clusters feed into microgrids with shared battery and control infrastructure.
Standalone captures volume leadership. Integrated is climbing the fastest as urban retrofit accelerates.
Power Source:
Volume concentration in hybrid architectures reflects procurement mandates for renewable redundancy and multi-day autonomy.
- Hybrid:Combined vertical axis wind turbines and photovoltaic arrays with lithium-ion storage dominate municipal procurement. China's dual carbon goals and EU Green Deal efficiency standards push developers toward these grid-independent designs.
- Solar Energy:PV-only systems concentrate in equatorial latitudes with minimal seasonal irradiance variation.
- Wind Energy:Turbine-primary configurations deploy in North American harbor districts and coastal high-wind corridors where VAWT efficiency peaks.
- Battery Backup:Storage-dominant systems extend autonomy in hybrid configurations, with solid-state lithium-metal chemistry displacing conventional lithium-ion in pilot deployments.
Hybrid leads deployment value. Battery Backup is gaining share fastest as chemistry innovations compress replacement cycles.
End User:
Customer type determines procurement channel structure, with direct municipal tenders displacing traditional electrical contractor intermediation.
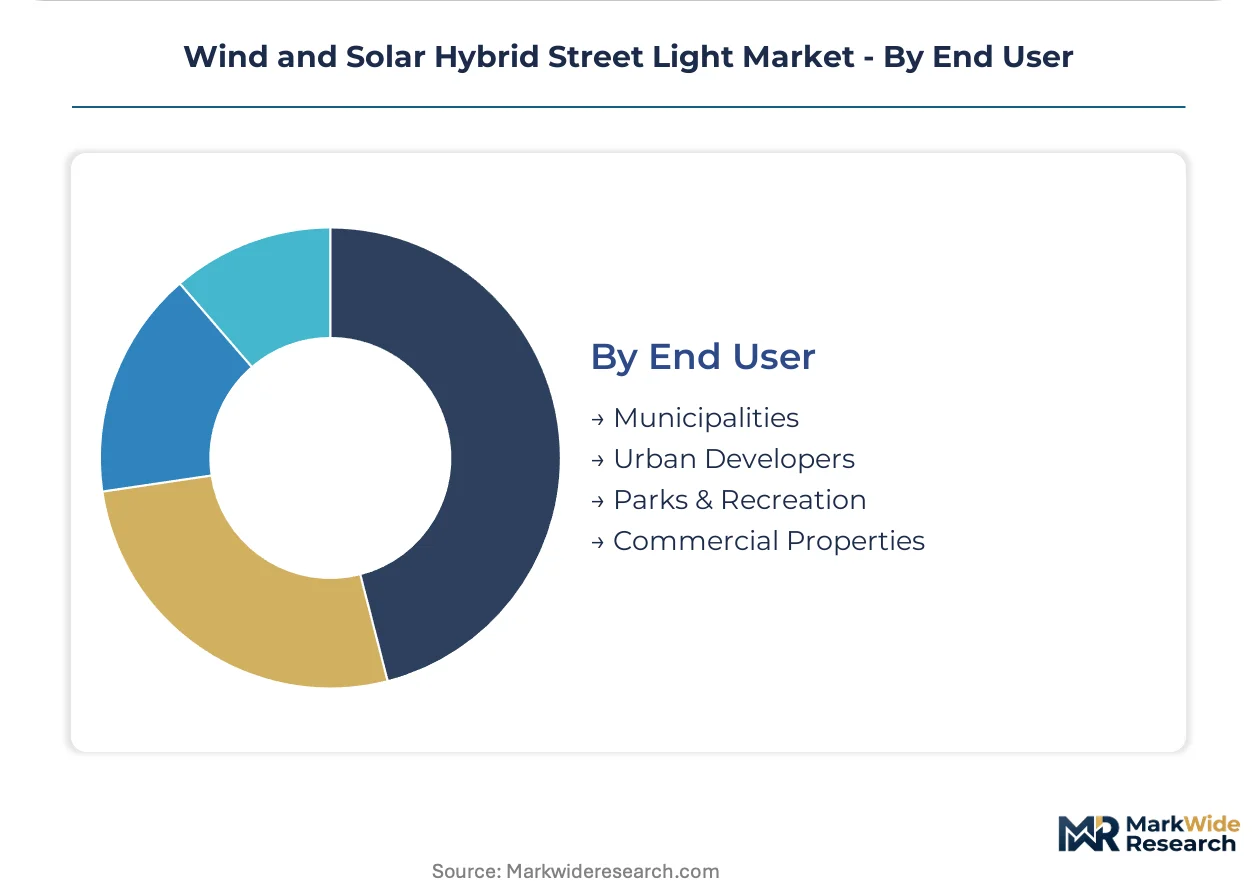
- Municipalities:City governments issue direct tenders to renewable lighting specialists, bypassing generalist infrastructure contractors. India's smart city projects and central government street lighting subsidies concentrate demand here.
- Urban Developers:Private master-planned communities and commercial districts specify hybrid systems for sustainability certifications and resilience marketing.
- Parks & Recreation:Remote trail and campground illumination drives demand for low-maintenance standalone units with extended battery autonomy.
- Commercial Properties:Industrial parks and logistics centers deploy perimeter lighting with integrated security sensor hosting.
Municipalities anchor procurement volume. Urban Developers is expanding most quickly as ESG-linked financing penetrates real estate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's hydrogen import terminal and North Sea offshore grid interconnect anchor Europe's renewable infrastructure corridor, while China's coastal manufacturing belts and India's Delhi-Mumbai Industrial Corridor concentrate hybrid lighting procurement volumes.
United States
Coastal harbor districts and hurricane-prone Gulf municipalities drive procurement of autonomous lighting systems. FCC electromagnetic emissions guidelines govern wireless control modules in smart lighting deployments. North Carolina's Outer Banks and Florida's coastal counties lead pilot programs for vertical turbine integration.
China
Dual carbon goals and MIIT efficiency mandates accelerate integrated wind-solar designs across smart city corridors. GB standards and SAMR certification requirements shape product specifications for domestic and export markets. Yangtze River Delta manufacturing clusters anchor production scale for integrated pole systems.
India
Central government PLI scheme subsidies and BIS certification mandates concentrate demand in smart city projects. CEA grid reliability standards push urban peripheries toward standalone autonomous systems. Gujarat and Tamil Nadu coastal municipalities issue direct tenders bypassing traditional electrical contractors.
Germany
EU Green Deal efficiency standards and F-Gas Regulation compliance layers drive premium procurement in municipal frameworks. CE marking and ECHA material disclosure requirements weight lifecycle carbon accounting in tender scoring. North Rhine-Westphalia's industrial cities and Bavarian municipal networks prioritize certified integrated systems.
Vietnam
Southeast Asian archipelago geography and intermittent grid reliability create first-mover conditions for standalone hybrid installations. National smart city corridor development concentrates demand in port authority infrastructure pilots. Ho Chi Minh City's emerging urban zones exhibit acute direct-tendering patterns to renewable specialists.
Wind and Solar Hybrid Street Light Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive component production and certified system integration capabilities. Tiered competitive positioning separates premium-certified European specialists from scale-driven Asian fabricators and regional project developers. Three archetypes dominate: turbine-technology originators pivoting into full-system integration, photovoltaic manufacturers backward-integrating into wind-solar hybrid designs, and municipal-focused engineering specialists capturing direct procurement channels. Dominant competitive moves include strategic partnerships with battery chemistry innovators and geographic expansion through local assembly licensing to bypass import tariff exposure.
Among turbine-technology originators, UGE exemplifies the vertical-axis wind specialist archetype that has expanded into full pole-integrated system supply. Eolgreen occupies a position within the European certification-depth tier, anchoring premium municipal framework positioning. Guangzhou HY Energy Technology represents the manufacturing-scale archetype, with integrated pole system production serving export markets across Africa and Latin America.
| Leading Market Players |
|---|
| UGE |
| Solar Wind Technologies |
| Eolgreen |
| Guangzhou HY Energy Technology |
| Phono Solar |
| Shanghai Ghrepower Green Energy |
| WindStream Energy Technologies |
| Signify |
| Panasonic |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta manufacturing clusters anchor global production scale for integrated pole systems, translating concentrated fabrication capacity into asymmetric pricing power for Chinese exporters serving African and Latin American procurement channels. Municipal buyers in grid-constrained environments face compressed negotiation leverage when sourcing turnkey hybrid systems, as vertical integration into turbine casting and photovoltaic lamination concentrates margin capture upstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates European-certified systems with CE marking and lifecycle carbon disclosures from basic LED-wind configurations serving sub-Saharan African urban peripheries. Certification depth and smart city sensor integration drive price differentiation, with French municipal tenders weighting environmental performance scoring above upfront capital cost. Cost compression in the economy tier is intensifying because Vietnamese and Indian fabricators are backward-integrating into lithium-ion battery pack assembly. Sub-Saharan African municipalities exhibit highest price sensitivity due to foreign exchange constraints, while North American harbor districts demonstrate lowest sensitivity given resilience-premium budgeting.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for system integrators serving North American coastal municipalities. Manufacturing concentrates in China, Vietnam, and India, with Yangtze River Delta clusters supplying vertical axis wind turbine castings and photovoltaic laminates. Raw material dependencies draw from lithium carbonate processing hubs, rare earth magnet suppliers, and aluminum extrusion facilities. Single-source vulnerability in cathode material refining creates geopolitical exposure for battery storage subsystems. Distribution runs through direct municipal tender channels that displace traditional electrical contractor intermediation in coastal Indian states and Southeast Asian island jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification depth and multi-jurisdiction compliance timelines create switching costs that lock municipal buyers into established supplier relationships.
For Market Incumbents: Harden certification portfolios against emerging Chinese competitors by accelerating BIS, CE marking, and FCC electromagnetic emissions testing parallelization. Deepen upstream control over solid-state battery chemistry partnerships to compress replacement cycle advantages. Defend against photovoltaic manufacturers backward-integrating into wind-solar hybrid designs by locking multi-year direct tender relationships with Indian smart city authorities and Vietnamese port administrations. For New Entrants and Emerging Players: Build out local assembly licensing arrangements in sub-Saharan African urban peripheries to bypass import tariff exposure and currency conversion frictions. Target standalone autonomous system deployments where grid reliability gaps exceed 40 percent downtime annually. Penetrate through after-sales service bundling that addresses the electromechanical integration expertise shortage constraining competitor field support capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility hybrid play because municipal procurement channel fragmentation creates recurring revenue visibility through maintenance and battery replacement cycles. Acquisition targets should display captive turbine technology or certified European framework positioning rather than pure manufacturing scale. Monitor solid-state lithium-metal battery pilot deployment outcomes in North American harbor districts as the inflection signal for chemistry-driven competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Smart City Sensor Integration | Vietnamese port authorities bundle air quality monitoring with lighting infrastructure in direct tenders. |
| Solid-State Battery Licensing | Harbor districts in North Carolina and Florida pilot ceramic electrolyte systems for extended cycle life. |
| European Certification Depth Investment | French and Spanish municipal frameworks weight lifecycle carbon accounting above capital cost in scoring. |
| Local Assembly Licensing | Sub-Saharan African urban peripheries require bypass structures for import tariff and currency exposure. |
| Vertical Turbine R&D Partnership | Coastal high-wind corridors demand efficiency improvements in low-wind urban canyon environments. |
Research Methodology
Initial hypotheses were tested against primary input from municipal procurement officers, renewable lighting system integrators, battery chemistry specialists, and EPC contractors active in harbor infrastructure, then refined through secondary validation against MIIT efficiency mandate filings, EU Green Deal implementation guidance, Indian BIS certification registries, and FERC interconnection queue data. Bottom-up unit economics from pole-level bill-of-materials were triangulated against top-down municipal budget allocation tracking across smart city programs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type connectivity tier, installation topology autonomy level, power source architecture, and end-user procurement channel structure. CAGRs were derived from installation volume trajectories and average selling price evolution by certification tier. Industry-specific forecast inputs incorporated lithium-ion cathode material pricing volatility and vertical axis wind turbine efficiency curves by wind resource class.
Stress conditions across battery chemistry substitution timelines, municipal subsidy continuity, and grid extension cost trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory mandate enforcement intensity and technology cost reduction slopes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wearable AI Market
Others
North America Astrology Market
Others
Global Military Apparel Market
Others
Fluorite Market
Others
Coloring Apps Market
Others
Canada Laser Hair Removal Market
Others
Global Optical Comparator Market
Others
Czech Republic Market
Others
Idaas Market
Others
Smart Home Water Softener Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Baking Paper Market
Others
Dried Egg Market
Others
ISO Cylinder Market
Others
Subtilisin Market
Others
PC As a Service Market