
 Global Healthcare/Medical Simulation Market | 2026-2036
Global Healthcare/Medical Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare/Medical Simulation Market Foresight
The global clinical educator workforce is bifurcating into technology-native instructors and legacy practitioners, creating uneven simulation adoption across teaching hospitals. CAE Healthcare leverages its integrated digital platform to sustain instructor-training programs that reduce onboarding friction. Laerdal Medical anchors Nordic markets through its emergency response drill installations, while Gaumard Scientific competes on obstetric simulation fidelity with programmable maternal physiology.
Healthcare and medical simulation encompasses mannequin-based, virtual reality, task trainer, and mixed reality systems that replicate anatomical structures, physiological responses, and procedural environments for risk-free clinical training. These platforms employ haptic feedback engines, computational physiology models, and cloud-rendered immersive graphics to enable repeatable skill acquisition without patient exposure. Mannequin-based simulators retain the largest installed base across medical schools, though virtual reality systems capture accelerating replacement cycles as hardware costs decline and software libraries expand. Surgical training applications command premium pricing due to procedure-specific content development, while emergency response drills penetrate military medical units through standardized scenario protocols.
FDA 510(k) premarket notification governs hardware-software combinations in the United States, compelling developers to validate physiological accuracy against clinical reference standards. EMA's Medical Device Regulation and Japan's PMDA software-as-medical-device guidelines impose parallel conformity requirements that fragment certification timelines across jurisdictions. Stakeholders must monitor regulatory divergence between cloud-based delivery modes and on-premise installations, as data residency rules increasingly determine platform architecture decisions.
Market Dynamics
The clinical educator workforce bifurcation between technology-native instructors and legacy practitioners creates uneven simulation adoption across teaching hospitals, forcing vendors to sustain dual training infrastructures.
Growth Catalysts
- Clinical Placement Shortages:Nursing institutes across Germany, the United Kingdom, and Australia are scaling simulator purchases to address bed shortages and patient safety constraints. This institutional procurement wave sustains hardware replacement cycles.
- FDA 510(k) Pathway:The United States premarket notification framework for virtual reality surgical trainers accelerates product commercialization timelines. Developers validate physiological accuracy against clinical reference standards to secure clearance.
- Haptic Feedback Engines:Advances in force-feedback hardware reduce the fidelity gap between virtual and mannequin-based systems. Medical schools in Japan and South Korea are piloting these platforms for procedural training.
Market Restraints
- Software-as-Medical-Device Fragmentation:EMA's Medical Device Regulation and Japan's PMDA guidelines impose parallel conformity requirements that extend certification timelines. Cloud-based delivery modes face additional data residency compliance burdens.
- Instructor Training Bottlenecks:Simulation centers require dedicated educators proficient in both clinical content and platform operation. The scarcity of dual-qualified personnel limits deployment velocity at university hospitals.
- High-Fidelity Content Development Costs:Procedure-specific surgical modules demand anatomical modeling and physiological scripting investments that compress margins for specialized applications.
Strategic Opportunities
- Military Medical Units:Standardized emergency response drill protocols create recurring demand for trauma simulation systems. Defense procurement channels in the United States and NATO member states offer multi-year contract structures.
- Cloud-Rendered Immersive Graphics:Convergence of edge computing and low-latency streaming enables browser-based simulation access. This architecture reduces on-premise hardware requirements for resource-constrained training programs.
- India's PLI Scheme:Production-linked incentives for medical device manufacturing attract component suppliers to establish domestic assembly. Local value addition requirements favor joint ventures with established simulation hardware producers.
Industry Challenges
- Legacy System Integration:Hospital IT departments struggle to embed cloud-based simulation platforms within existing credentialing and learning management architectures. Data interoperability standards remain immature across vendors.
- Computational Physiology Model Validation:Regulatory bodies demand evidence packages demonstrating algorithmic accuracy against clinical datasets. The burden of generating peer-reviewed validation studies falls disproportionately on smaller developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare/Medical Simulation Market |
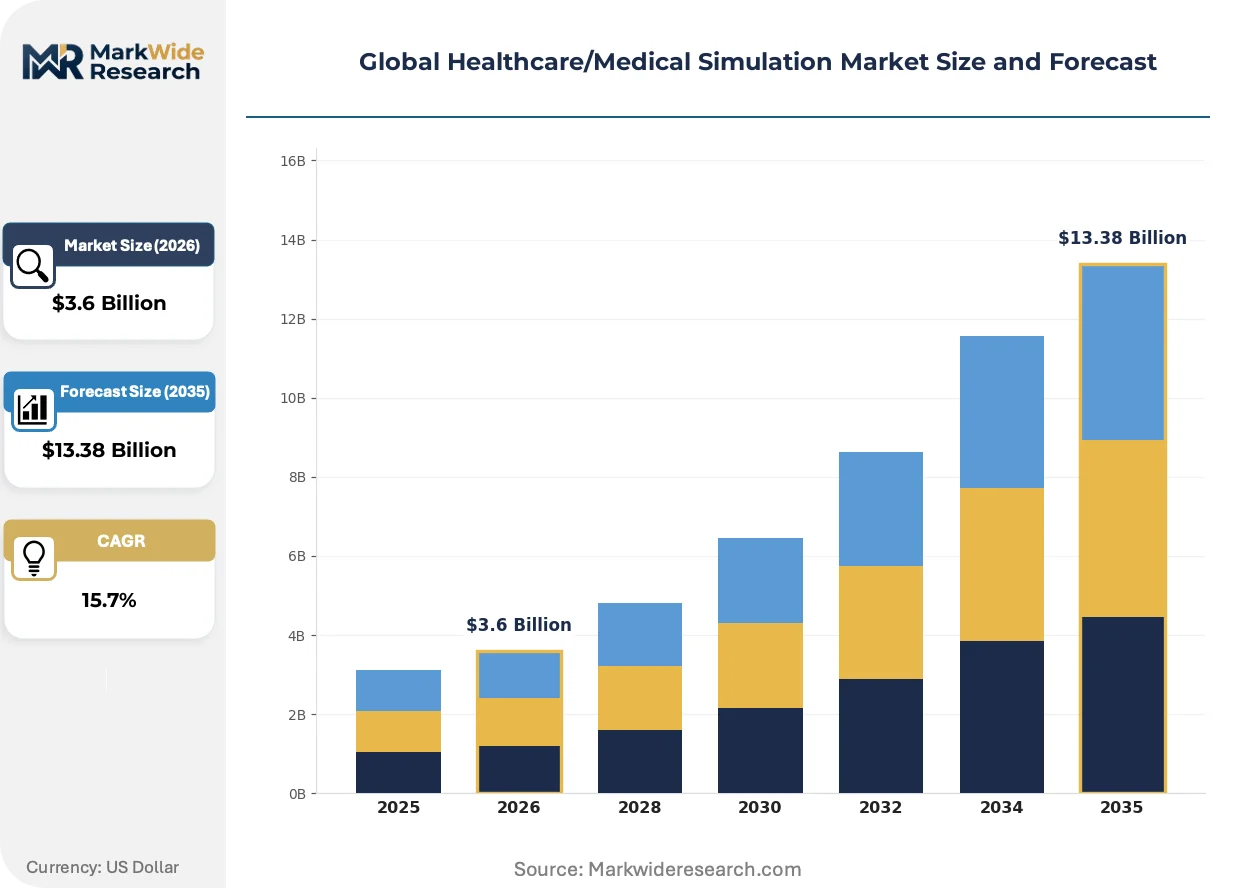
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality Simulators, Mannequin-Based Simulators, Task Trainers, Mixed Reality Simulators Application: Surgical Training, Medical Diagnosis Practice, Patient Treatment Planning, Emergency Response Drills End User: Medical Schools, Nursing Institutes, Research Organizations, Military Medical Units Delivery Mode: Cloud-Based, On-Premise Software, Hybrid Platforms, Mobile Applications |
| Companies Covered | CAE Healthcare, Laerdal Medical, Gaumard Scientific, Surgical Science Sweden AB, Simulab Corporation, Mentice AB, Kyoto Kagaku, Anatomage, Limbs & Things, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare/Medical Simulation Market Shifts & Advancements
Computational physiology models and immersive rendering pipelines are compressing the cost-performance frontier, enabling scenario complexity previously restricted to high-end installations.
Cloud-native simulation platforms are decomposing the traditional capital expenditure model for medical schools. Subscription-based access to surgical content libraries allows programs in Brazil, Mexico, and South Africa to deploy scenarios exceeding their hardware budgets. This architecture shift compresses the installed base advantage of legacy mannequin vendors.
EMA's Medical Device Regulation software classification rules are forcing developers to restructure quality management systems. The industrial consequence is a bifurcation between platforms pursuing full medical device certification and those positioning as educational tools. Surgical training applications face the strictest scrutiny, with several manufacturers withdrawing procedure-specific modules from European markets rather than absorb compliance costs.
Teaching hospitals are unbundling after-sales service contracts from initial hardware purchases. Procurement teams in the United Kingdom and Netherlands now negotiate simulator maintenance, content updates, and instructor training as separate line items. This pattern shifts vendor revenue toward recurring service streams and pressures pure-equipment manufacturers without training infrastructure.
Global Healthcare/Medical Simulation Market Segmentation
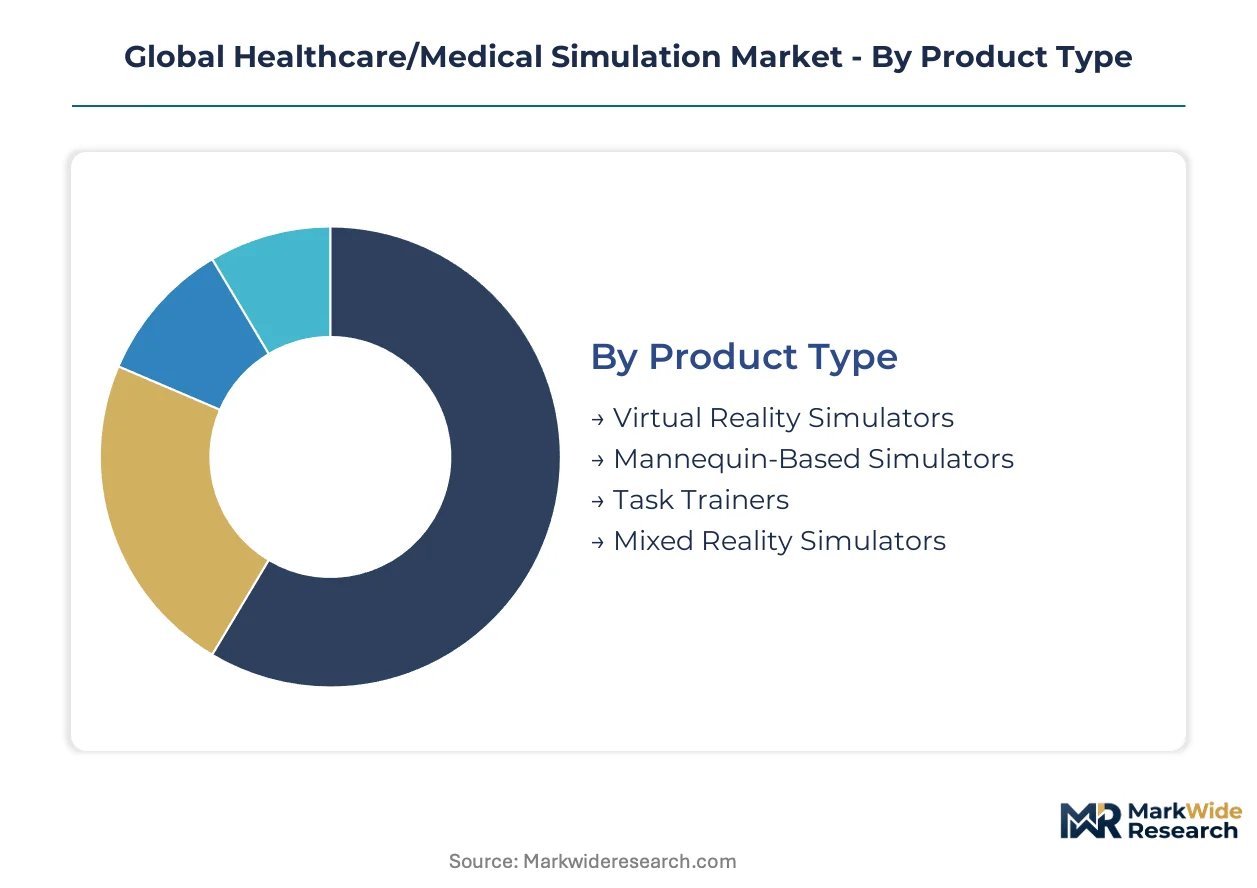
Segmentation reveals how procurement priorities diverge across institutional budgets, regulatory environments, and training mandates. Product type and delivery mode choices increasingly determine vendor selection, while application specificity governs content licensing economics.
Product Type:
Domestic assembly concentrates mannequin-based systems in Germany and the United States, whereas virtual reality hardware flows predominantly from East Asian manufacturing clusters.
- Mannequin-Based Simulators:These systems integrate pneumatic actuators, fluid circulation loops, and programmable physiological responses into full-body patient replicas. University hospitals in Germany operate centralized simulation centers with state-level funding that sustains high-fidelity mannequin deployments. Mannequin-based simulators retain the largest installed base across medical schools.
- Virtual Reality Simulators:Head-mounted displays with haptic controllers render immersive procedural environments without physical patient models. Medical schools in Japan and South Korea pilot these platforms as hardware costs decline and software libraries expand. Momentum sits with virtual reality systems.
- Task Trainers:Anatomically accurate partial-body models isolate specific procedures such as lumbar puncture or central line insertion.
- Mixed Reality Simulators:These platforms overlay digital content onto physical mannequins, blending tactile feedback with visual augmentation.
Mannequin-based simulators hold the largest share; momentum sits with virtual reality systems.
Application:
Cost tier stratification separates premium-priced surgical modules from standardized emergency drill protocols purchased through defense procurement channels.
- Surgical Training:Procedure-specific content development demands anatomical modeling and physiological scripting investments that command premium pricing. The FDA's 510(k) clearance pathway for virtual reality surgical trainers accelerates product commercialization in the United States. Surgical training applications face the strictest regulatory scrutiny.
- Emergency Response Drills:Standardized trauma scenarios with repeatable protocols penetrate military medical units through multi-year contract structures. NATO member states and United States defense channels create recurring demand for these systems. Emergency response drills are climbing the fastest.
- Medical Diagnosis Practice:Virtual patient encounters train clinical reasoning through branching case narratives with diagnostic consequence modeling.
- Patient Treatment Planning:Preoperative rehearsal platforms allow surgeons to navigate patient-specific anatomy reconstructed from imaging datasets.
Surgical training commands premium pricing; emergency response drills are expanding most quickly through defense channels.
End User:
Customer type determines procurement velocity, with military units executing rapid standardized purchases while academic institutions navigate extended capital approval cycles.
- Medical Schools:These institutions deploy comprehensive simulation centers requiring instructor training infrastructure and curriculum integration support. The United Kingdom and Netherlands procurement teams now negotiate maintenance, content updates, and instructor training as separate line items. Medical schools represent the most complex sales cycle.
- Nursing Institutes:Clinical placement shortages across Germany, the United Kingdom, and Australia are scaling simulator purchases to address bed constraints and patient safety requirements. This institutional procurement wave sustains hardware replacement cycles. Nursing institutes are gaining share fastest.
- Military Medical Units:Defense procurement channels in the United States and NATO member states offer multi-year contract structures for trauma simulation systems.
- Research Organizations:These users validate computational physiology models against clinical datasets to support regulatory submission packages.
Medical schools hold the largest share; nursing institutes are gaining share fastest.
Delivery Mode:
Supply concentration in cloud infrastructure providers is reshaping how simulation vendors architect platform delivery across data residency jurisdictions.
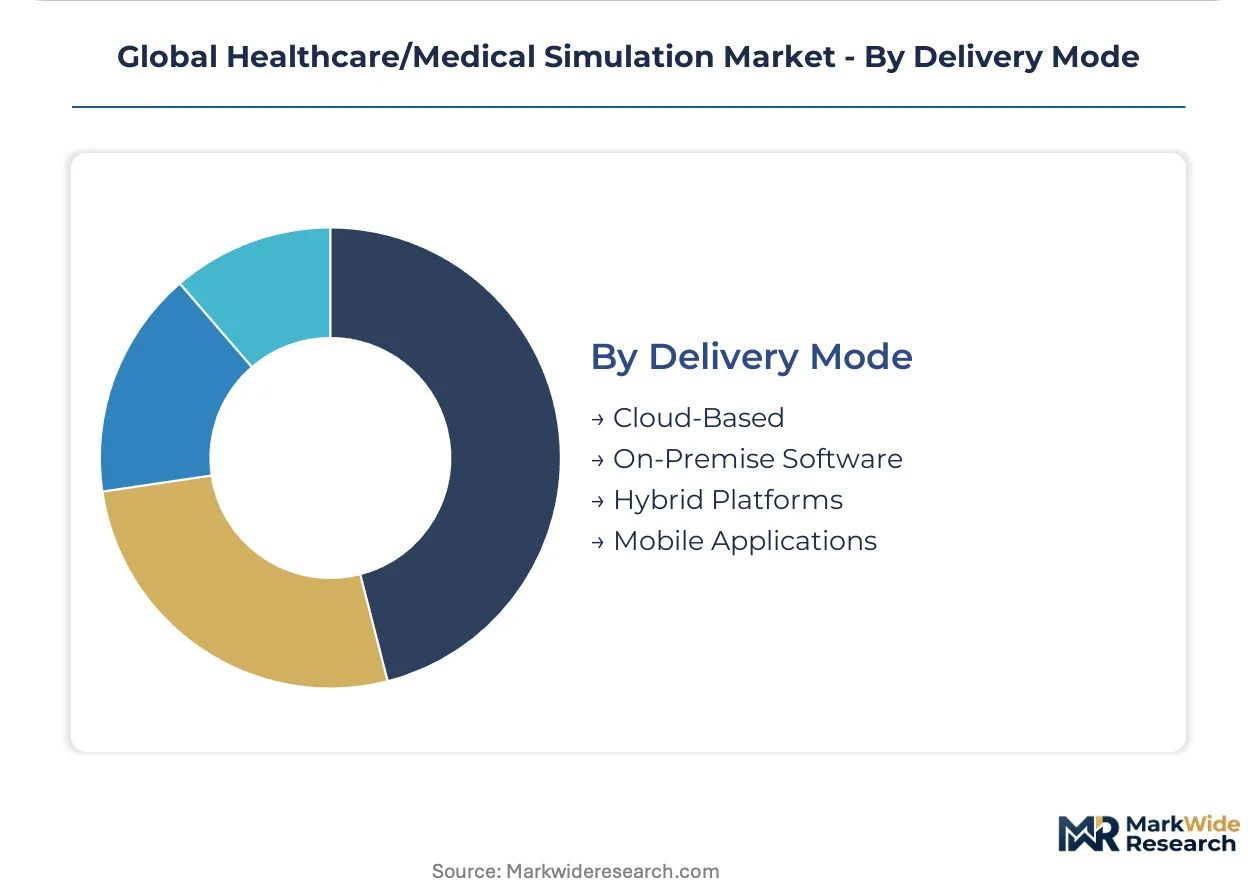
- Cloud-Based:Browser-based access to surgical content libraries enables programs in Brazil, Mexico, and South Africa to deploy scenarios exceeding their hardware budgets. EMA's Medical Device Regulation and Japan's PMDA software-as-medical-device guidelines impose parallel conformity requirements that fragment certification timelines. Cloud-based delivery is climbing the fastest.
- On-Premise Software:Local installation satisfies hospital IT departments struggling to embed external platforms within existing credentialing and learning management architectures. Data residency rules increasingly determine platform architecture decisions for this delivery mode.
- Hybrid Platforms:These architectures combine local rendering for latency-sensitive haptic feedback with cloud content streaming for scenario libraries.
- Mobile Applications:Smartphone and tablet-based training modules support just-in-time skill refreshment and assessment.
On-premise software holds the largest share; cloud-based delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 510(k) premarket notification pathway anchors the United States as the regulatory benchmark for virtual reality surgical trainers, while university hospitals in Germany and procurement waves across nursing institutes in Australia and the United Kingdom concentrate demand in distinct institutional configurations.
United States
Military medical units and academic medical centers drive procurement through defense channels and federal research grants. FDA's 510(k) clearance framework accelerates commercialization timelines for hardware-software combinations. The Greater Boston and San Francisco Bay Area clusters host concentrated simulation research programs at teaching hospitals.
Germany
State-level funding sustains centralized simulation centers at university hospitals in Bavaria and North Rhine-Westphalia. EMA's Medical Device Regulation imposes conformity requirements that extend certification timelines for cloud-based platforms. Baden-Württemberg's medical technology corridor concentrates mannequin-based system assembly operations.
United Kingdom
Nursing institutes scale simulator purchases to address clinical placement shortages and patient safety constraints. Procurement teams in London and the Midlands negotiate maintenance, content updates, and instructor training as separate contract line items. The National Health Service's regional training networks standardize emergency response drill protocols.
Japan
Medical schools in Tokyo and Osaka pilot haptic feedback platforms as hardware costs decline and software libraries expand. PMDA's software-as-medical-device guidelines impose parallel conformity requirements that fragment certification timelines for cloud-based delivery. The Kanto region's electronics manufacturing base supplies force-feedback engine components.
Australia
Nursing institutes across New South Wales and Victoria sustain hardware replacement cycles through institutional procurement addressing bed constraints. TGA's medical device framework governs local market entry requirements. Sydney's simulation centers operate with curriculum integration support from specialized educator training programs.
Global Healthcare/Medical Simulation Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium pricing through bundled hardware-software-service offerings while specialists compete on anatomical fidelity in narrow procedural domains. The market structure rewards vendors with captive instructor-training infrastructure and penalizes pure-equipment manufacturers without curriculum integration capabilities. Three archetypes dominate: integrated platform providers with digital ecosystems, fidelity specialists in obstetric or emergency simulation, and regional assemblers serving price-sensitive procurement channels. Competitive moves concentrate on strategic partnerships with nursing institutes and defense procurement channels, plus portfolio diversification into cloud-rendered content libraries.
Within the integrated platform tier, CAE Healthcare and Laerdal Medical exemplify vendors sustaining dual training infrastructures for technology-native and legacy practitioner cohorts. Kyoto Kagaku occupies a position among Asia-Pacific-based specialists, while Gaumard Scientific sits within the fidelity-specialist segment. These companies represent contrasting geographic origins—Canadian, Nordic, Japanese, and American respectively—reflecting how regional manufacturing clusters and regulatory proximity shape competitive positioning without determining specific market outcomes.
| Leading Market Players |
|---|
| CAE Healthcare |
| Laerdal Medical |
| Gaumard Scientific |
| Surgical Science Sweden AB |
| Simulab Corporation |
| Mentice AB |
| Kyoto Kagaku |
| Anatomage |
| Limbs & Things |
| Others |
Supply & Pricing Matrix
Multi-year defense procurement contracts lock in supply access for trauma simulation systems while anchoring price visibility across NATO member states and United States military medical units. These contractual structures insulate vendors from spot-market volatility in haptic feedback engine components and cloud infrastructure services.
Pricing Analysis
Price spreads between German university hospitals and Brazilian nursing institutes exceed threefold for equivalent mannequin-based systems after accounting for curriculum integration and instructor training bundling. Subscription-based SaaS tiers for cloud-rendered surgical content are displacing perpetual licenses as nursing institutes in Mexico and South Africa prioritize operational expenditure flexibility. Cost compression in mid-fidelity task trainers intensifies as domestic assembly under India's PLI scheme expands component supply. Academic medical centers exhibit lowest price sensitivity due to federal research grant funding, while resource-constrained nursing programs in emerging markets drive hardest bargain negotiations.
Supply Chain Analysis
Container availability constraints on East Asian trade lanes elevate inbound logistics costs for head-mounted display assemblies and force-feedback engine components sourced from Japan and South Korea. Manufacturing concentration for mannequin-based systems centers on Germany and the United States, while virtual reality hardware flows predominantly from Chinese and Taiwanese electronics clusters. Key input dependencies span pneumatic actuators from Baden-Württemberg, computational physiology modeling software from Greater Boston, and cloud rendering infrastructure from hyperscale providers. Single-source vulnerability in haptic controller chipsets poses structural risk. Distribution runs through specialized medical device distributors with hospital GPO relationships and direct defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as cloud-native simulation architectures decouple content libraries from hardware installations, creating interoperability standards that favor ecosystem orchestrators over point-solution vendors.
For Market Incumbents: Consolidate instructor-training infrastructure through acquisition of specialized educator certification programs to defend against cloud-native entrants lacking curriculum integration capabilities. Deepen backward integration into haptic feedback engine production to secure component supply amid Taiwan semiconductor foundry constraints. Lock in nursing institute relationships via bundled maintenance and content update contracts before subscription models commoditize hardware margins. For New Entrants and Emerging Players: FDA 510(k) premarket notification fast-track for virtual reality surgical trainers offers regulatory pathway acceleration relative to EMA Medical Device Regulation timelines. White-space opportunities concentrate in browser-based emergency response drill protocols for NATO defense procurement channels and cloud-rendered obstetric simulation for India's nursing institutes under PLI scheme incentives. Go-to-market execution should anchor in pay-per-use pricing that converts capital-constrained training programs without upfront hardware commitments. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vendors with captive cloud infrastructure and recurring revenue streams over pure-equipment manufacturers. Long-term viability over the coming decade hinges on content library depth and data residency compliance architecture across multiple jurisdictions. Acquisition target archetype: mid-cap fidelity specialists in obstetric or trauma simulation with FDA-cleared modules but underdeveloped SaaS delivery capabilities. Signal to watch: nursing institute procurement velocity in Germany and Australia as indicator of hardware replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance unlocks university hospital procurement across Germany and Netherlands. |
| Hospital System Partnership | Curriculum integration with NHS regional training networks standardizes emergency drill protocols. |
| Software Companion Development | Cloud-rendered mobile modules extend reach to Brazil and South Africa resource-constrained programs. |
| Reimbursement Strategy | Federal research grant alignment secures academic medical center purchasing committee access. |
| FDA Submission | 510(k) clearance accelerates commercialization timelines for VR surgical trainers in United States. |
Research Methodology
A standing panel of simulation center directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EMA Medical Device Regulation submissions, hospital procurement databases, and defense contracting announcements. Primary fieldwork combined structured interviews with curriculum integration specialists and scenario content developers. Bottom-up sizing of installed base units triangulated against top-down expenditure estimates from federal research grant disclosures and nursing institute capital budgets.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler cloud infrastructure capex allocations and medical device trade flow data. Segmentation modeling spanned product type, application specificity, end-user institutional category, and delivery mode architecture across the analysis window. CAGRs derived from regression analysis of replacement cycle frequencies and procurement wave timing. Industry-specific forecast inputs incorporated instructor training bottleneck severity indices and regulatory pathway duration differentials between FDA and EMA jurisdictions.
Decision-makers should treat outputs as directional under assumptions of sustained clinical placement shortages and stable defense procurement channel access; material deviation in nursing student enrollment trends or NATO budget allocations would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Linear Shaft Market
Others
Sunflower Husk Pellets Market
Others
Moveable Water Tap Market
Others
Rope Market
Others
US Legal Services Market
Others
Europe Polycarbonate Sheets Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Billet Market
Others
Inorganic Tin Chemicals Market
Others
Aluminium Clad Printed Circuit Board Market
Others
North America Commercial Vehicles Lubricants Market
Others
Lychee Market
Others
Pollen Allergy Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
US Mobile MRI Services Market
Others
Europe Indoor Air Purification Market