
 Handheld Mobile Computers Market | 2026-2036
Handheld Mobile Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Mobile Computers Market Insights
Healthcare is restructuring demand patterns across the handheld mobile computers landscape as hospitals replace consumer-grade tablets with disinfectant-ready clinical devices. Zebra Technologies anchors the North American enterprise segment through its TC-series healthcare portfolio. Honeywell International Inc. differentiates via its operational technology software stack bundled with rugged hardware. CipherLab Co., Ltd. competes aggressively on price in the Asia-Pacific SME channel.
Handheld mobile computers are portable data-capture terminals integrating barcode imagers, RFID modules, and wireless radios within IP65+ sealed enclosures designed for industrial duty cycles. These devices execute real-time inventory transactions, patient identity verification, and field-service documentation across environments where consumer smartphones fail structurally. Barcode scanners and RFID readers dominate installed value, though mobile POS terminals are capturing margin pools in retail omni-channel fulfillment. The cellular connectivity segment is outpacing Wi-Fi-only configurations as distributed workforces require seamless handoff between warehouse floors and delivery routes.
FCC certification governs radio transmission protocols for devices entering the US market, while the EU Radio Equipment Directive mandates interoperability testing and electromagnetic compatibility disclosure. Japan's METI enforces JIS durability standards that shape procurement specifications for domestic logistics providers. Stakeholders must monitor evolving battery transportation regulations and decide whether to internalize certification expertise or outsource compliance to regional testing laboratories.
Market Dynamics
Enterprise migration from Windows Embedded Handheld to Android 11+ is forcing OEMs to rebuild software stacks while warehouse operators accelerate rugged device refresh cycles to capture real-time inventory visibility.
Growth Catalysts
- EU REACH compliance mandates:Chemical disclosure requirements for battery materials are pushing manufacturers toward certified component suppliers, creating procurement alignment with sustainability-focused logistics operators in Germany.
- Automotive supplier traceability:Tier-1 manufacturers in Stuttgart and Wolfsburg now mandate serialized component tracking from dock to assembly line, expanding fleet deployments of 2D imager-equipped terminals.
- 5G private networks:Low-latency campus connectivity is enabling voice-directed picking and augmented reality troubleshooting in high-velocity distribution centers.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing dominates in East Asian chemical parks, exposing European OEMs to freight cost volatility and export license uncertainty.
- RF module certification timelines:FCC Part 15 and EU RED testing protocols add 14-22 weeks to product launch schedules, compressing margin capture windows for mid-cycle hardware refreshes.
- Consumer smartphone substitution:Bring-your-own-device policies in light-industrial settings erode addressable market for purpose-built rugged terminals in last-mile delivery segments.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for component manufacturing are attracting assembly investments targeting domestic logistics modernization and export markets.
- Cold-chain pharmaceutical tracking:Temperature-logging RFID sleds paired with handheld hosts address WHO GDP compliance for vaccine distribution networks.
- Japan's JIS Z 2801 antimicrobial standards:Disinfectant-ready device certifications open clinical workflow segments previously served by consumer tablets in Tokyo and Osaka hospital systems.
Industry Challenges
- Android fragmentation management:OEMs must maintain security patch pipelines across Qualcomm, MediaTek, and proprietary SoC platforms while supporting 5+ year hardware lifecycles promised to enterprise accounts.
- Legacy WMS integration:SAP and Oracle warehouse management instances running on-premise require middleware development for REST API compatibility with modern mobile clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Mobile Computers Market |
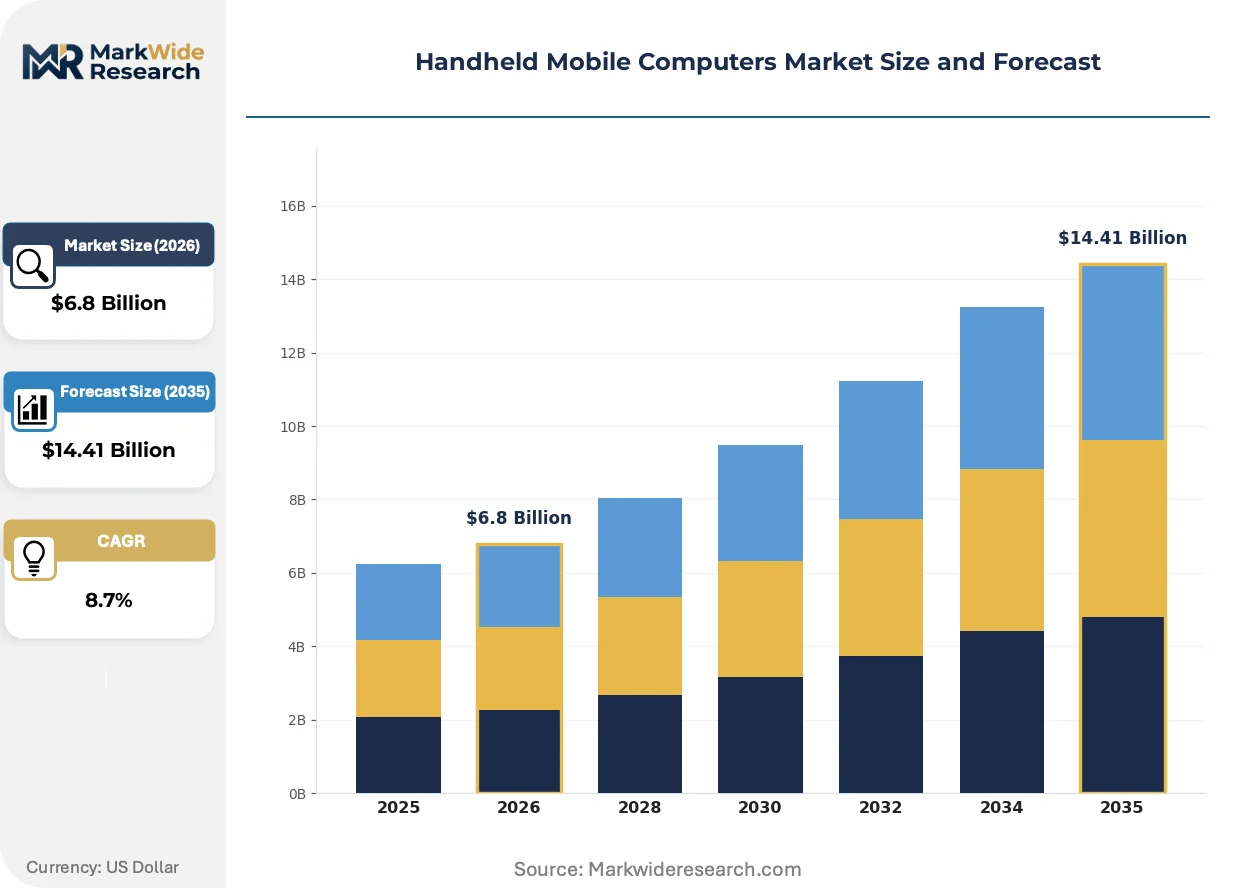
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barcode Scanners, RFID Readers, Mobile POS, Tablet Computers Connectivity: Wi-Fi, Bluetooth, Cellular, NFC End User: Healthcare, Retail, Logistics, Manufacturing Application: Inventory Management, Asset Tracking, Patient Care, Payment Processing |
| Companies Covered | Zebra Technologies, Honeywell International Inc., Datalogic S.p.A, Panasonic Corporation, Bluebird Inc., Getac Technology Corporation, CipherLab Co., Ltd., Motorola Solutions, Handheld Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Mobile Computers Market Trends and Innovations
Device architecture is converging around modular computing cores that separate processing, radio, and power subsystems into field-replaceable units. This shift extends hardware refresh intervals while enabling rapid technology insertion without full platform replacement.
Ultra-wideband positioning chips are consolidating indoor location accuracy to 10-centimeter resolution, displacing legacy Wi-Fi triangulation in high-density storage environments. Third-party logistics operators in the Netherlands and Belgium are deploying UWB-enabled terminals for precise pallet localization within multi-story automated warehouses. The technology is consolidating vendor selection criteria around spatial computing capabilities rather than barcode scanning speed alone.
Japan's METI has issued revised JIS durability standards requiring 1.8-meter drop survival onto concrete and IP67 sealing verification under thermal cycling. Domestic OEMs must submit test reports to designated conformity assessment bodies before market placement. Automotive parts distributors in Nagoya and Yokohama are now specifying JIS-certified devices exclusively, creating specification divergence from FCC-centric North American procurement patterns.
Hospital IT departments are unbundling hardware acquisition from software licensing, preferring device-as-a-service contracts with guaranteed uptime SLAs. This procurement model shifts capital expenditure to operational budgets while transferring firmware maintenance liability to OEMs. The transition is most visible in Germany's university hospital networks, where disinfectant-ready Android terminals are displacing legacy Windows CE devices under 36-month refresh agreements.
Handheld Mobile Computers Market Segmentation
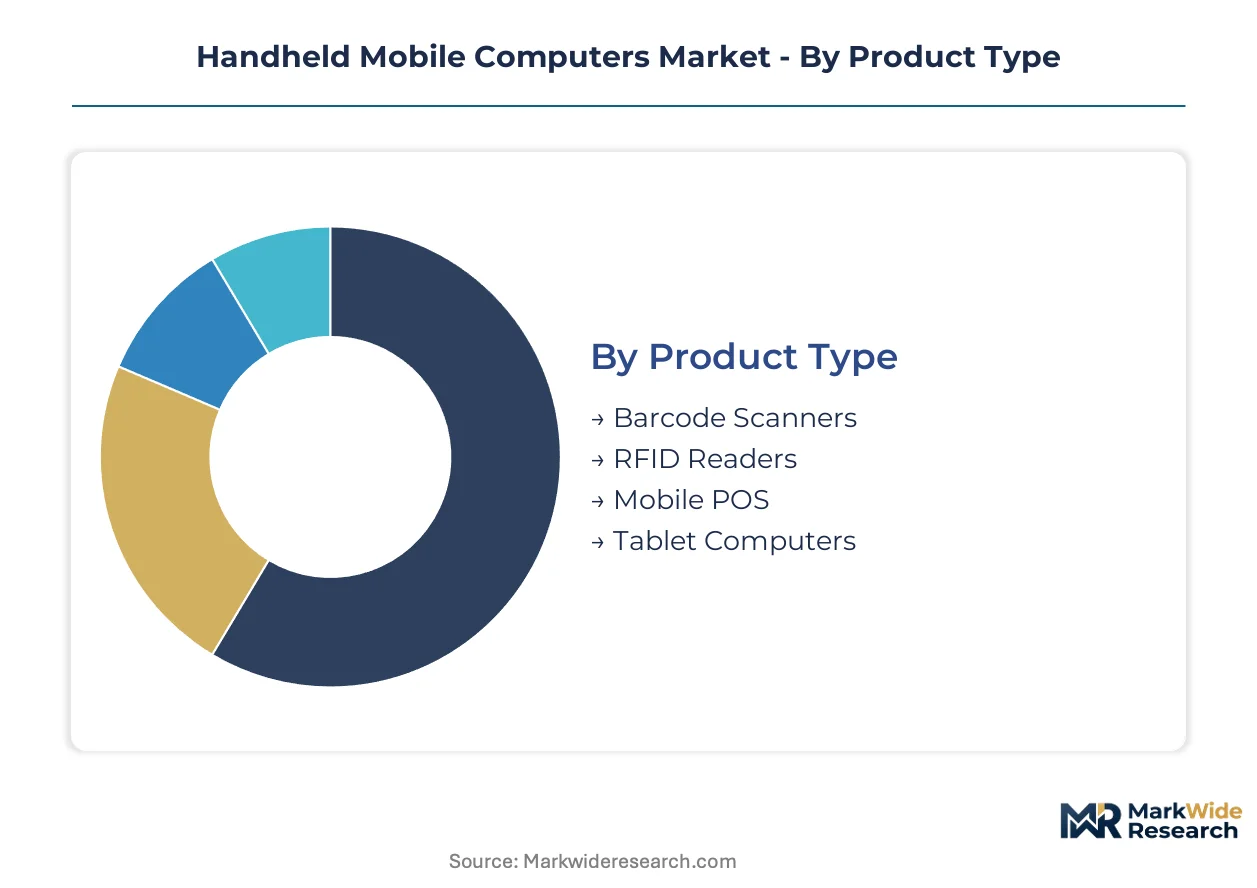
Handheld mobile computer buyers segment procurement by environmental durability, data-capture modality, and integration depth with enterprise software stacks. Device selection hinges on IP ratings, scan engine specifications, and API compatibility rather than hardware cost alone.
Product Type:
Purchase decisions in this category diverge between enterprises prioritizing scan speed accuracy versus those requiring multi-function computing platforms.
- Barcode Scanners:Laser and 2D imager configurations dominate warehouse floors where high-velocity omnidirectional scanning is mandatory. German automotive suppliers in Stuttgart mandate serialized component tracking, expanding deployments of high-density imager modules. Volume sits with Barcode Scanners; growth tilts toward RFID Readers.
- RFID Readers:UHF handheld terminals integrate multi-tag batch reading for pallet-level reconciliation without line-of-sight constraints. Cold-chain pharmaceutical distributors in Belgium deploy temperature-logging RFID sleds paired with host devices for WHO GDP compliance.
- Mobile POS:PCI-DSS certified terminals with integrated PIN pads and receipt printing serve omni-channel retail fulfillment.
- Tablet Computers:Ruggedized 8-10 inch displays with active stylus support enable field-service documentation and digital work instructions.
Procurement volume clusters around scan-centric hardware; computing-intensive form factors expand most quickly in clinical and field-service segments.
Connectivity:
Radio configuration determines workforce mobility boundaries and real-time data synchronization latency.
- Cellular:LTE and 5G modules with dual-SIM architecture enable seamless handoff between warehouse floors and delivery routes. Private 5G network deployments in Dutch distribution centers are accelerating cellular-equipped terminal refresh cycles.
- Wi-Fi:Wi-Fi 6/6E radios with WPA3-Enterprise security dominate fixed-facility deployments where roaming between access points is contained within building perimeters. Japan's METI electromagnetic compatibility disclosure requirements shape module certification timelines for Wi-Fi-only configurations.
- Bluetooth:Low-energy protocols tether peripheral devices including ring scanners, printer sleds, and wearable displays.
- NFC:13.56 MHz contactless interfaces support employee badge authentication and payment tokenization in retail environments.
Fixed infrastructure reliance sustains Wi-Fi volume; distributed workforce requirements are concentrating new investment in cellular configurations.
End User:
Vertical-specific compliance mandates and environmental exposure dictate ruggedization tier and disinfectant readiness.
- Logistics:3PL operators in the Netherlands and Belgium specify IP67 sealing and 1.8-meter drop survival for multi-story automated warehouse deployments. EU REACH chemical disclosure requirements for battery materials are elevating procurement alignment with certified component suppliers.
- Healthcare:Disinfectant-ready enclosures with JIS Z 2801 antimicrobial certification are displacing consumer tablets in Tokyo and Osaka hospital systems. Germany's university hospital networks prefer device-as-a-service contracts with guaranteed uptime SLAs.
- Retail:Omni-channel fulfillment drives mobile POS and inventory lookup terminal deployment across store networks.
- Manufacturing:Shop-floor traceability mandates from tier-1 automotive suppliers require serialized component tracking from dock to assembly line.
Logistics commands installed base volume; healthcare represents the steepest expansion trajectory as clinical workflow digitization accelerates.
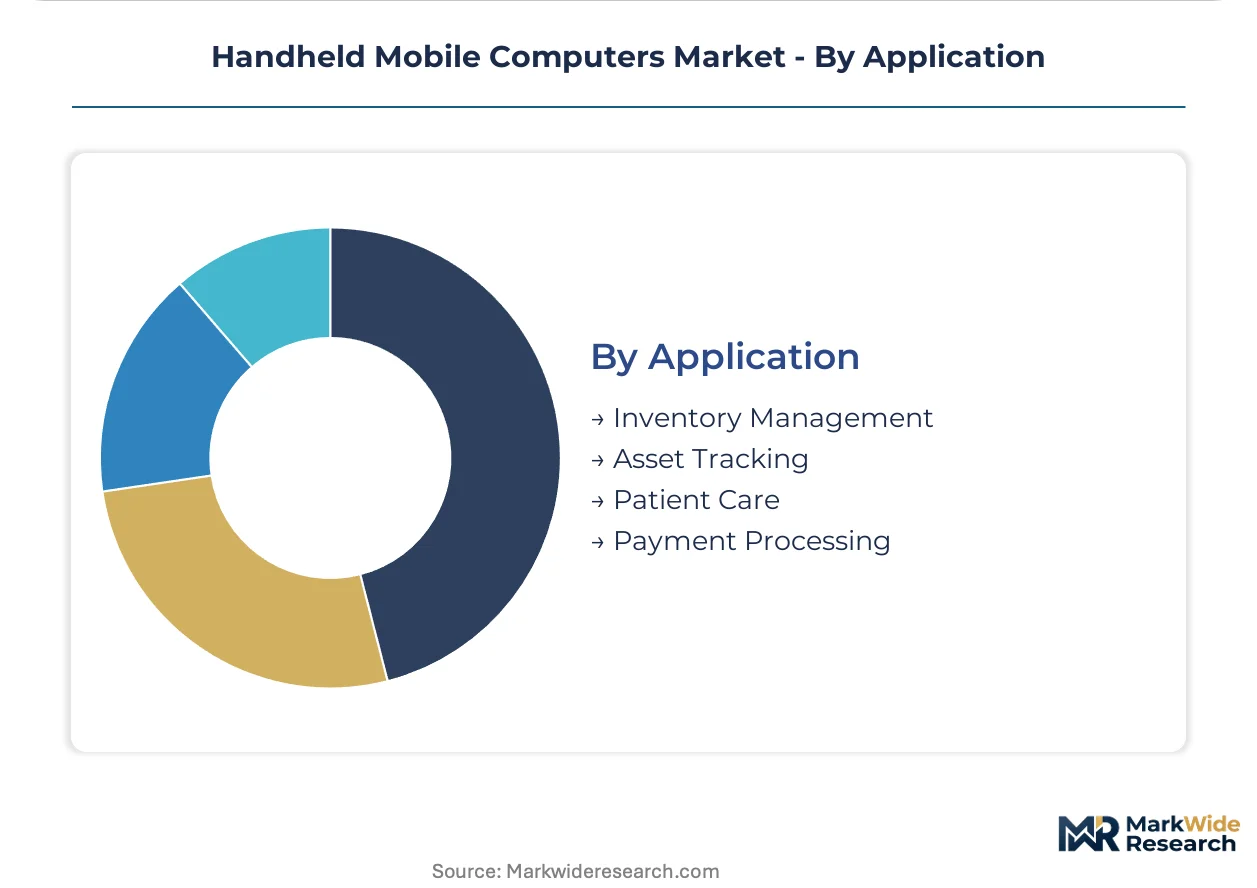
Application:
Use-case complexity determines whether buyers prioritize scan speed, location accuracy, or payment security certification.
- Inventory Management:Real-time stock visibility systems integrate barcode and RFID data capture with WMS middleware. SAP and Oracle warehouse management instances running on-premise require API development for REST compatibility with modern mobile clients.
- Asset Tracking:Ultra-wideband positioning chips consolidate indoor location accuracy to 10-centimeter resolution, displacing legacy Wi-Fi triangulation in high-density storage environments.
- Patient Care:Positive patient identification workflows mandate disinfectant-ready devices with barcode and NFC capabilities for medication administration.
- Payment Processing:PCI-DSS Level 1 certification and end-to-end encryption are non-negotiable for retail mobile POS deployments.
Operational visibility applications anchor current volume; patient safety and payment security use cases are gaining share fastest as regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian production clusters supply the majority of rugged device assemblies, while European and North American end-users drive consumption through logistics modernization mandates. Component concentration in Taiwan and South Korean memory fabrication creates supply vulnerability for Western OEMs. Procurement patterns diverge sharply between FCC-governed North American specifications and JIS-certified Japanese durability requirements.
United States
Warehouse operators across the Midwest and Southeast are refreshing rugged Android fleets to replace legacy Windows Embedded Handheld terminals. FCC Part 15 certification timelines for RF modules extend product launch schedules by 14-22 weeks, compressing margin windows. Chicago and Atlanta distribution corridors specify IP65+ sealed devices with 2D imagers for omnidirectional scanning in high-velocity fulfillment centers.
Germany
Automotive suppliers in Stuttgart and Wolfsburg mandate serialized component tracking from dock to assembly line, expanding deployments of UHF RFID-enabled terminals. EU REACH chemical disclosure requirements for battery materials elevate procurement alignment with certified component suppliers. The Ruhr industrial corridor concentrates demand for disinfectant-ready clinical devices as university hospital networks transition to device-as-a-service contracts.
Japan
Domestic logistics providers specify JIS Z 2801 antimicrobial certification and 1.8-meter drop survival onto concrete under revised METI durability standards. METI electromagnetic compatibility disclosure requirements shape module certification timelines for Wi-Fi-only configurations. Automotive parts distributors in Nagoya and Yokohama now require JIS-certified devices exclusively, creating specification divergence from North American procurement patterns.
Netherlands
Third-party logistics operators deploy UWB-enabled terminals for 10-centimeter resolution pallet localization within multi-story automated warehouses. Private 5G network rollouts accelerate cellular-equipped terminal refresh cycles across Rotterdam and Eindhoven distribution hubs. EU Radio Equipment Directive interoperability testing adds compliance cost layers for devices entering the Benelux market.
India
Production-linked incentives for electronics manufacturing attract assembly investments targeting domestic logistics modernization and export markets. BIS certification requirements for telecom equipment create entry barriers for unregistered foreign suppliers. Mumbai and Bangalore logistics corridors are expanding rugged device procurement as e-commerce fulfillment networks densify.
Handheld Mobile Computers Market Competitive Landscape
Top-tier vendors anchor enterprise-grade rugged portfolios, while mid-tier specialists compete on price in regional SME channels. The vendor base stratifies across three tiers: full-stack platform providers bundling hardware with operational software, component-assembly houses serving private-label contracts, and niche specialists targeting single-vertical certifications. Strategic moves concentrate on Android 11+ software stack rebuilds and modular computing architectures that separate processing subsystems into field-replaceable units.
Within the full-stack platform tier, Zebra Technologies and Honeywell International Inc. exemplify integrated hardware-software positioning, while CipherLab Co., Ltd. occupies a distinct value-tier position competing aggressively on price in Asia-Pacific SME distribution. Datalogic S.p.A represents European engineering heritage in automated data capture, anchoring Mediterranean and Central European procurement specifications. These three archetypes—North American platform bundlers, Asian value optimizers, and European precision specialists—collectively define competitive tension across procurement segments.
| Leading Market Players |
|---|
| Zebra Technologies |
| Honeywell International Inc. |
| Datalogic S.p.A |
| Panasonic Corporation |
| Bluebird Inc. |
| Getac Technology Corporation |
| CipherLab Co., Ltd. |
| Motorola Solutions |
| Handheld Group |
| Others |
Pricing and Supply Chain Analysis
Firmware engineering talent concentration in Taiwan and South Korea generates labor-cost differentials that widen pricing-tier spreads between premium enterprise platforms and economy SME devices.
Pricing Analysis
Margin tightening in mid-tier configurations reflects Android 11+ software stack rebuild costs and extended FCC Part 15 certification timelines. Pricing stratifies across premium, standard, and economy tiers based on IP rating certification and after-sales service bundling. Cost compression accelerates in Wi-Fi-only configurations as distributed workforces shift procurement toward cellular-equipped alternatives. SME channel buyers in Asia-Pacific exhibit highest price sensitivity; automotive tier-1 suppliers in Germany demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with cathode material processing concentrated in East Asian chemical parks. Component assembly draws from Taiwan, South Korea, and China for memory fabrication, display modules, and RF chipsets. Lithium-ion cell supply concentration exposes European OEMs to freight cost volatility and export license uncertainty. Distribution runs through authorized distributor networks serving vertical-specific certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over RF module certification and battery cell supply determines margin capture.
For Market Incumbents: Anticipate margin compression from consumer smartphone substitution in last-mile delivery segments by deepening software stack differentiation and securing captive battery supply agreements. Prioritize modular computing architectures that extend hardware refresh intervals while transferring firmware maintenance liability to OEM balance sheets under device-as-a-service contracts. For New Entrants and Emerging Players: The price-point gap between premium healthcare-certified terminals and economy logistics devices offers white-space entry through JIS Z 2801 antimicrobial certification targeting Tokyo and Osaka hospital procurement. India's PLI scheme for electronics manufacturing provides assembly cost advantages for domestic logistics modernization. Pursue channel partnerships with regional distributors serving SME warehouse operators. For Investors and Strategic Acquirers: Re-rating potential sits with modular architecture specialists given enterprise migration from Windows Embedded Handheld to Android 11+ platforms. Long-term viability hinges on five-to-ten year hardware lifecycle commitments and security patch pipeline maintenance across Qualcomm and MediaTek SoC platforms. Monitor private 5G network deployment velocity in Dutch and Belgian distribution centers as inflection indicator for cellular-equipped terminal refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Computing Architecture Development | Field-replaceable processing subsystems extend refresh intervals while enabling rapid technology insertion without platform replacement. |
| Private 5G Network Partnership | Low-latency campus connectivity in Rotterdam and Eindhoven accelerates voice-directed picking and augmented reality troubleshooting deployments. |
| JIS Z 2801 Certification Investment | Antimicrobial device standards open clinical workflow segments in Tokyo and Osaka hospital systems previously served by consumer tablets. |
| Device-as-a-Service Contract Expansion | Guaranteed uptime SLAs shift capital expenditure to operational budgets while transferring firmware liability to OEMs in German university hospital networks. |
| RF Module Certification Internalization | In-house FCC Part 15 and EU RED testing expertise compresses 14-22 week product launch schedules for mid-cycle hardware refreshes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with warehouse operations directors, hospital procurement committees, automotive supply chain managers, and rugged device OEM product strategists validated demand assumptions. FCC certification databases, EU REACH chemical disclosure registries, and Japan METI conformity assessment body reports supplied regulatory timeline inputs. Bottom-up shipment estimates by product type and connectivity configuration triangulated against top-down enterprise IT spending surveys.
Granularity-level modeling disaggregated volume and value projections across barcode scanners, RFID readers, mobile POS terminals, and tablet computers by cellular, Wi-Fi, Bluetooth, and NFC connectivity variants. End-use segmentation captured logistics, healthcare, retail, and manufacturing verticals with application-level splits for inventory management, asset tracking, patient care, and payment processing. CAGRs derived from regression analysis against industrial automation capital expenditure indices and e-commerce fulfillment network densification rates.
Inputs from OEM product roadmaps and hospital procurement databases were available through the study window; gaps in private 5G network deployment schedules and lithium-ion export license timelines introduce uncertainty bands around cellular connectivity adoption curves. Forecasts reflect documented assumptions regarding Android fragmentation management costs and legacy WMS integration complexity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Vortexers Market
Others
Cloud DVR Market
Others
Mexico 3D Printing Construction Market
Others
Global Personal Care Packaging Market
Others
Middle East and Africa Surface Analysis Market
Others
Griffin Beaker Market
Others
Global Automotive LED Lighting Market
Others
Operator Training Simulator Market
Others
Europe Video Encoder Market
Others
Global Smartphone ODM Market
Others
Fresh Durian Market
Others
Europe Street Lighting Market
Others
Storage Dewar and Dry Shipper Market
Others
Level Measuring Instrument Market
Others
Convenience Stores Market
Others
Brazil Cane Sugar Market