
 Rugged Tablet Market | 2026-2036
Rugged Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Rugged Tablet Market Analysis
Taiwanese ODM capacity is expanding to serve the surge in military-specification tablet orders. Panasonic leverages its Toughbook heritage to sustain premium positioning across defense and public safety verticals. Getac dominates the fully rugged segment through in-house thermal engineering and MIL-STD-810H certification capabilities. Honeywell International anchors industrial channel access with its established barcode and mobile computing distribution network.
A rugged tablet is a portable computing device engineered to withstand extreme temperatures, shock, vibration, dust ingress, and liquid immersion, typically certified to MIL-STD-810H and IP65 or higher ingress protection ratings, designed for mission-critical data capture and communication in environments where consumer-grade electronics would fail. The fully rugged product category commands the highest margin pools due to specialized thermal management and reinforced chassis manufacturing. Android-based systems represent the fastest-expanding technology segment as open-source flexibility enables custom kernel development for specialized sensor integration and secure boot requirements in field service and transportation deployments.
The U.S. Department of Defense mandates FIPS 140-2 encryption compliance through NIST for all mobile computing devices handling classified data, while the EU's CE marking and RoHS directives restrict hazardous substance use and establish electromagnetic compatibility benchmarks for hardware sold across member states. The U.S. Federal Communications Commission certifies LTE and NFC radio modules, creating pre-approval dependencies that shape product development timelines and geographic launch sequencing. Stakeholders must monitor evolving defense procurement specifications and sustainability disclosure requirements as dual-use technology classifications and carbon-footprint transparency reshape supplier qualification criteria.
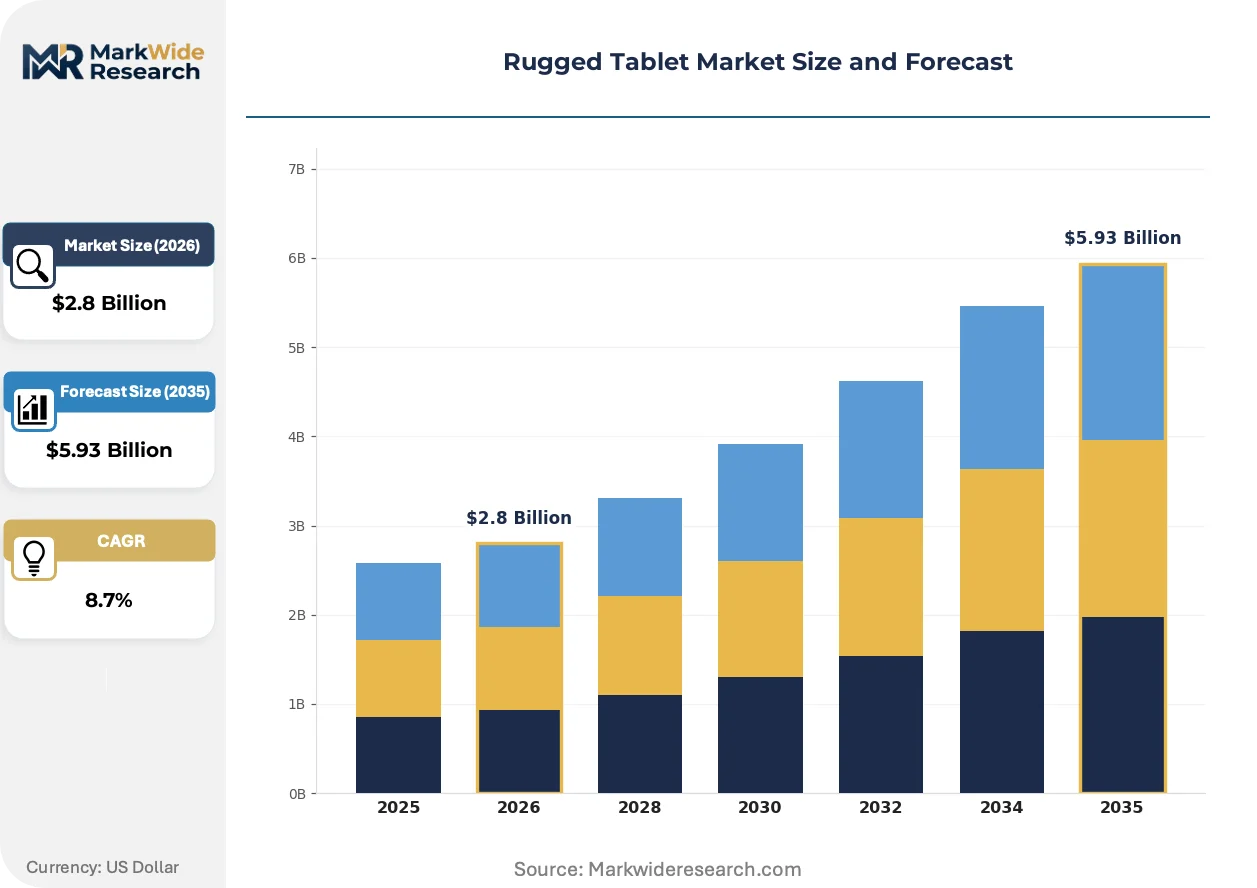
Market Dynamics
Defense procurement specifications are hardening around FIPS 140-2 encryption and MIL-STD-810H certification, forcing suppliers to requalify chassis designs and thermal architectures for NATO-aligned military contracts.
Growth Catalysts
- Ecodesign for Sustainable Products Regulation:The European Union's tightening material compliance mandates are accelerating recyclability investments across electronics hardware supply chains serving industrial OEMs.
- Automotive factory-floor digitization:Germany's industrial corridor is specifying IP65-rated tablets for production-line quality control and predictive maintenance workflows.
- Android open-source flexibility:Custom kernel development for specialized sensor integration is expanding deployment in field service and transportation verticals.
Market Restraints
- Specialized component sourcing:MIL-grade thermal management materials concentrate among a limited set of qualified Japanese and Taiwanese suppliers, creating input bottlenecks.
- Radio module pre-approval dependencies:FCC certification timelines for LTE and NFC modules extend product development cycles by six to nine months.
- Reinforced chassis manufacturing costs:Magnesium alloy housings and gasketing systems carry 3-4x cost premiums versus consumer-grade enclosures.
Strategic Opportunities
- Carbon-footprint transparency mandates:The EU's CSRD disclosure requirements are creating first-mover advantage for suppliers with lifecycle-assessed supply chains.
- Secure boot customization:Convergence of hardware security modules with biometric authentication is opening federal law enforcement and border control procurement channels.
- India's defense modernization:The country's PLI scheme for electronics manufacturing is attracting contract assembly investment for ruggedized computing platforms.
Industry Challenges
- MIL-STD-810H certification timelines:Environmental testing for shock, vibration, and temperature extremes requires 12-18 month validation cycles that compress product refresh windows.
- Legacy system integration:Defense and industrial buyers demand backward compatibility with Windows 7-era software stacks that conflict with modern secure boot architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugged Tablet Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Military, Construction, Field Service, Transportation Technology: Windows, Android, Linux, iOS Product Type: Fully Rugged, Semi-Rugged, Ultra-Rugged, Handheld Connectivity: Wi-Fi, Bluetooth, LTE, NFC |
| Companies Covered | Dell, Honeywell International, Zebra Technologies, RuggON, Winmate, Getac, Xplore Technologies, MobileDemand, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugged Tablet Market Emerging Trajectories
Hardware security architectures and sustainable material sourcing are converging to redefine supplier qualification criteria across defense and industrial procurement channels.
Hardware security modules with tamper-evident enclosures are integrating FIPS 140-2 Level 3 encryption directly into tablet motherboard designs. Defense agencies and federal law enforcement units are specifying these modules for classified data handling. This integration is compressing the competitive set to suppliers with in-house cryptographic engineering capabilities.
REACH substance restrictions and RoHS hazardous material limits are forcing reformulation of solder alloys and flame-retardant chassis coatings. Electronics manufacturers serving European industrial OEMs must now document full material declarations through supply chain tiers. Fully rugged product categories face the steepest compliance burden due to specialized thermal interface materials.
Defense procurement offices are consolidating vendor lists around dual-use technology classifications that satisfy both military and civilian agency requirements. This consolidation is displacing single-purpose hardware suppliers from prime contract eligibility. The shift is most visible in U.S. federal solicitations where NIST encryption mandates intersect with GSA schedule purchasing vehicles.
Rugged Tablet Market Segmentation
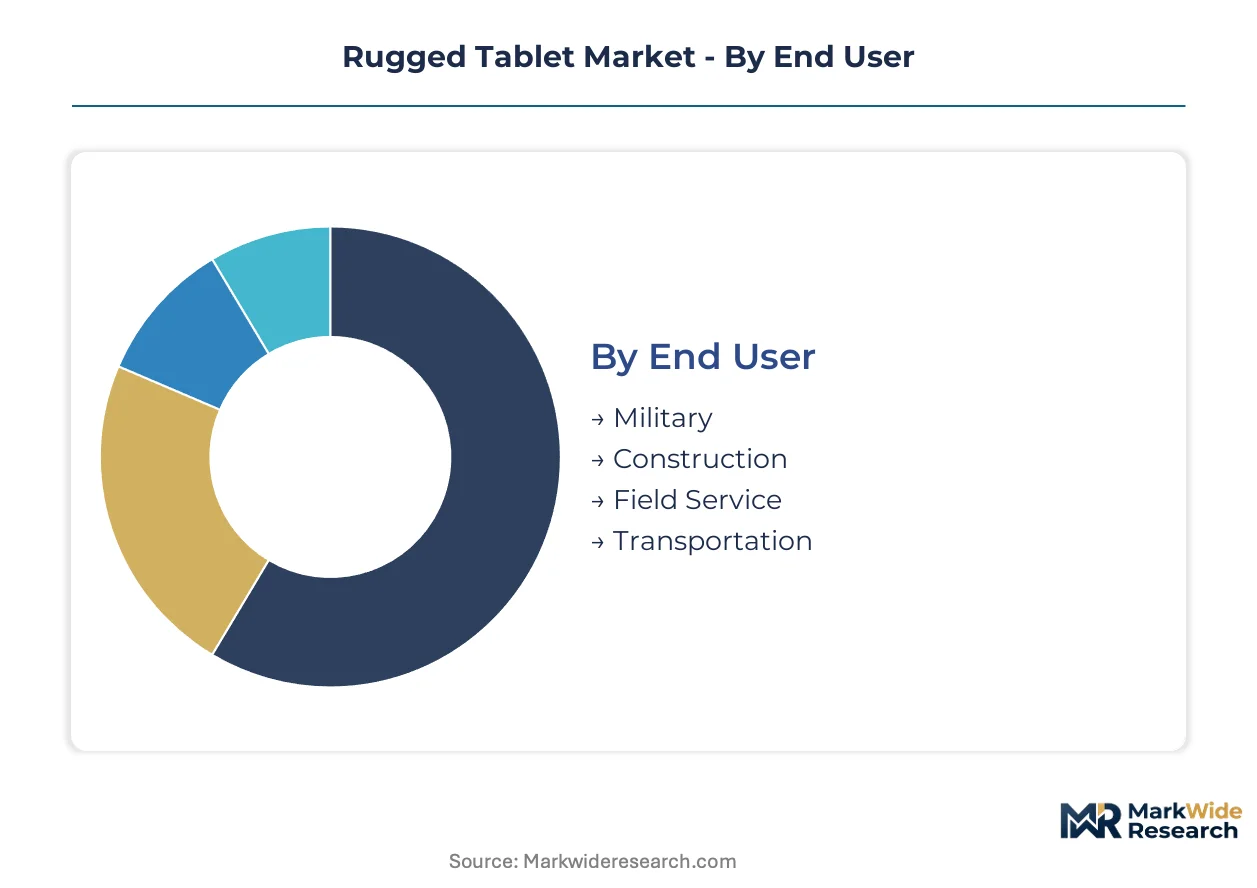
Rugged tablet procurement patterns diverge sharply across end-use environments, with military buyers prioritizing MIL-STD certification while industrial purchasers emphasize total cost of ownership. Technology and connectivity choices increasingly determine supplier qualification for specific vertical channels.
End User:
Military contracts anchor premium pricing tiers through hardened security mandates, while construction and field service segments drive volume scale.
- Military:NATO-aligned defense agencies specify FIPS 140-2 encryption and MIL-STD-810H environmental certification for mission-critical battlefield computing. Procurement concentrates in Germany and the United States, where defense modernization budgets are expanding secure mobile computing infrastructure.
- Field Service:Utility inspection and telecommunications maintenance crews demand Android-based platforms with custom sensor integration for predictive maintenance workflows. Germany's industrial corridor represents the densest geographic concentration of fleet deployments.
- Construction:Heavy equipment operators and site supervisors utilize semi-rugged tablets for blueprint access and equipment telematics in dust-heavy environments.
- Transportation:Fleet managers deploy LTE-connected devices for route optimization and regulatory compliance documentation across logistics networks.
Today's leader: Military. Tomorrow's challenger: Field Service.
Technology:
Operating system selection governs hardware security module compatibility and kernel customization depth for specialized industrial applications.
- Android:Open-source architecture enables custom kernel development for proprietary sensor stacks and secure boot configurations. Transportation and field service verticals in Germany and India are expanding deployment fastest due to integration flexibility.
- Windows:Legacy application compatibility dominates defense and federal law enforcement procurement, though secure boot conflicts with Windows 7-era software stacks create integration friction.
- Linux:Specialized distributions serve embedded systems and edge computing nodes requiring minimal attack surface.
- iOS:Consumer-derived ecosystem limits penetration in fully rugged deployments due to hardware customization restrictions and closed-source security architecture.
Android gains share fastest in industrial channels; Windows defends position in classified environments.
Product Type:
Durability tier determines margin structure, with fully rugged systems commanding specialized thermal engineering premiums.
- Fully Rugged:Magnesium alloy chassis with MIL-STD-810H certification and IP65+ ingress protection withstand extreme temperature swings and shock loading. Military and emergency response units in the United States specify these systems for operational continuity in contested environments.
- Semi-Rugged:Reinforced polymer housings balance drop protection with weight reduction for mobile workforce applications. German automotive OEMs are standardizing these for factory-floor quality control stations.
- Ultra-Rugged:Extended temperature range and submersion resistance target oil and gas exploration in arctic and desert conditions.
- Handheld:Compact form factors integrate barcode scanning and RFID for inventory management in warehouse and retail backroom operations.
Fully Rugged captures margin concentration; Semi-Rugged scales volume expansion.
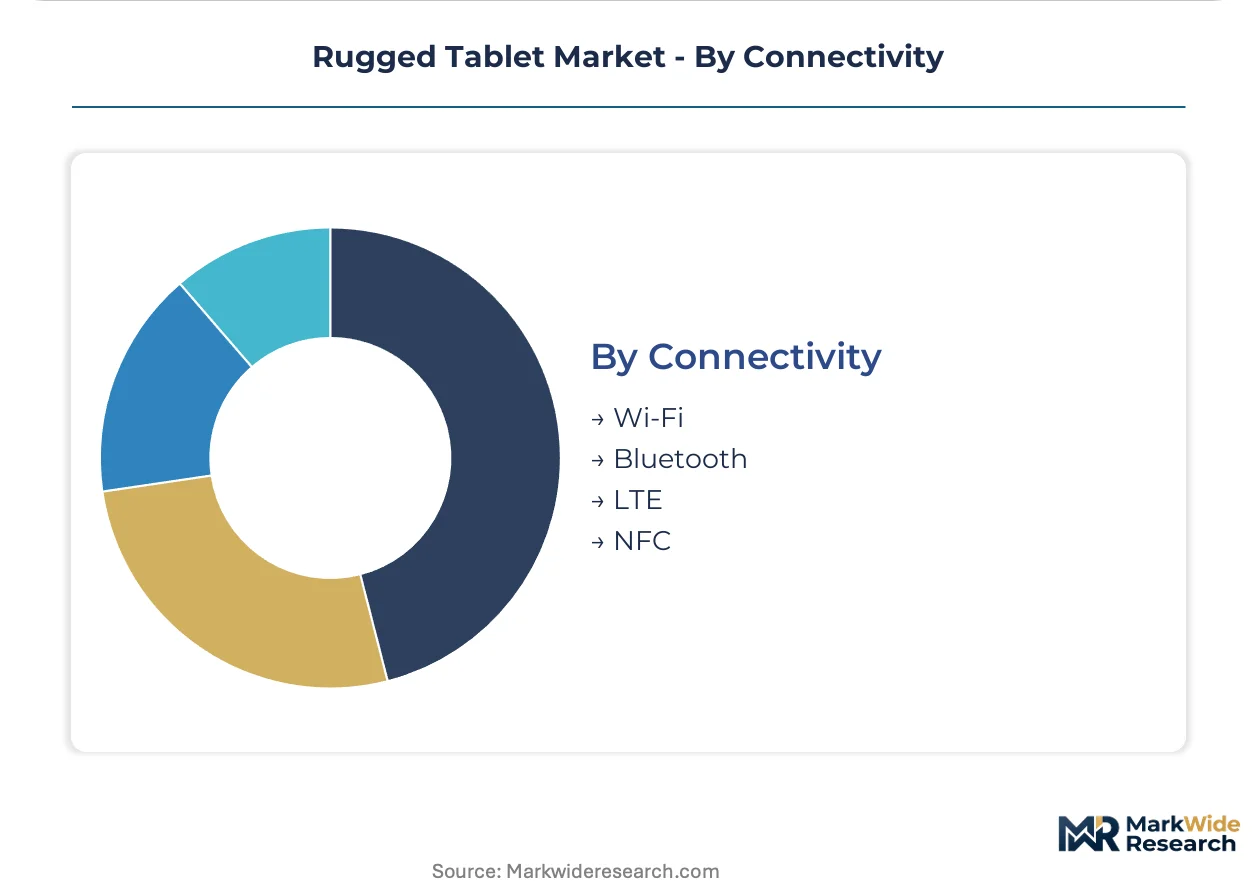
Connectivity:
Radio module certification timelines create geographic launch sequencing dependencies that shape regional product availability.
- LTE:Wide-area cellular connectivity enables real-time data synchronization for dispersed field teams and vehicle-mounted applications. FCC certification requirements in the United States extend development cycles, creating first-mover advantage for suppliers with pre-approved module portfolios.
- Wi-Fi:High-bandwidth local networking supports factory-floor integration with industrial IoT backbone infrastructure. German manufacturing clusters are driving Wi-Fi 6E adoption for low-latency machine control.
- Bluetooth:Peripheral pairing for barcode scanners, biometric readers, and wearable sensors in close-range operational contexts.
- NFC:Contactless authentication and payment processing for secure facility access and mobile point-of-service in transportation hubs.
LTE dominates mobility use cases; Wi-Fi anchors fixed industrial deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense procurement dwarfs civilian industrial demand, while Germany's automotive OEMs specify IP65-rated tablets at comparable per-unit volumes to NATO military orders.
United States
The Department of Defense mandates FIPS 140-2 encryption through NIST for all mobile computing devices handling classified data, compressing supplier qualification to vendors with in-house cryptographic engineering. FCC certification timelines for LTE and NFC radio modules extend product development cycles by six to nine months, creating first-mover advantage for suppliers with pre-approved module portfolios. Austin and San Antonio defense technology corridors concentrate procurement offices consolidating vendor lists around dual-use technology classifications.
Germany
Automotive factory-floor digitization in Stuttgart and Wolfsburg drives IP65-rated tablet deployment for production-line quality control and predictive maintenance workflows. The EU's Ecodesign for Sustainable Products Regulation tightens material compliance and recyclability mandates, forcing reformulation of solder alloys and flame-retardant chassis coatings. Bavaria's industrial corridor anchors the densest geographic concentration of semi-rugged fleet deployments for manufacturing quality stations.
India
The country's defense modernization programs under the PLI scheme for electronics manufacturing attract contract assembly investment for ruggedized computing platforms. BIS certification requirements for electronic goods create pre-market testing dependencies that shape product launch sequencing. Bengaluru and Hyderabad defense technology clusters concentrate procurement for mission-ready computing platforms serving domestic military modernization.
Japan
MIL-grade thermal management materials concentrate among qualified Japanese suppliers, creating input bottlenecks for magnesium alloy housings and gasketing systems. METI industrial standards guide procurement specifications for factory-floor mobile computing in automotive and precision manufacturing sectors. Nagoya and Osaka industrial corridors specify fully rugged systems for operational continuity in high-vibration manufacturing environments.
Taiwan
ODM capacity expansion serves the surge in military-specification tablet orders from NATO-aligned defense agencies. TRAI-equivalent regulations govern radio module certification for devices deployed in domestic industrial and transportation applications. Taipei and Taichung electronics manufacturing clusters concentrate thermal engineering capabilities for MIL-STD-810H certification requirements.
Rugged Tablet Market Vendor Landscape
Japanese and Taiwanese producers anchor the component supply tier; American and European specialists hold prime contract eligibility for defense and industrial end-use channels. The vendor structure concentrates around three strategic archetypes: diversified electronics conglomerates with defense heritage, pure-play rugged computing specialists with in-house certification capabilities, and industrial automation incumbents leveraging distribution network density. Competitive moves center on backward integration into thermal materials supply and geographic expansion into India's PLI-subsidized assembly corridors.
Among diversified technology conglomerates, Dell and Honeywell International exemplify archetypes leveraging established government procurement relationships and industrial channel access respectively. Getac occupies a position within the pure-play rugged specialist tier, representing in-house MIL-STD-810H certification and thermal engineering capabilities. These three anchors illustrate how supplier qualification criteria increasingly favor vendors with integrated security module design and sustainable material documentation.
| Leading Market Players |
|---|
| Dell |
| Honeywell International |
| Zebra Technologies |
| RuggON |
| Winmate |
| Getac |
| Xplore Technologies |
| MobileDemand |
| Panasonic |
| Others |
Supply Flow & Price Mechanics
Magnesium alloy spot pricing in East Asian metals exchanges cascades through three distinct cost tiers, compressing margins for semi-rugged chassis manufacturers while amplifying premium capture for fully rugged suppliers with captive Taiwanese smelter relationships.
Pricing Analysis
Distributor markups of 18-25% separate factory gate from end-user pricing across defense and industrial channels. Three-tier pricing stratifies across MIL-STD-810H certified fully rugged, IP65-rated semi-rugged, and enterprise-hardened handheld tiers. Cost compression in semi-rugged segments intensifies as German automotive OEMs consolidate volume procurement around standardized specifications. Military buyers exhibit lowest price sensitivity due to mission-critical reliability mandates, while transportation fleet managers drive hardest bargain on per-unit acquisition costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense procurement from United States and German buyers, while distributor networks serve fragmented field service and construction segments. Manufacturing concentrates in Taiwan, China, and Japan for magnesium alloy housings, thermal interface materials, and MIL-grade gasketing systems. Input dependencies center on rare earth elements for magnet assemblies, specialized solder alloys for RoHS compliance, and FIPS 140-2 certified cryptographic modules. Single-source vulnerability in Japanese thermal material suppliers creates chokepoint exposure. Distribution runs through authorized defense technology resellers and industrial automation distributors with certified service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
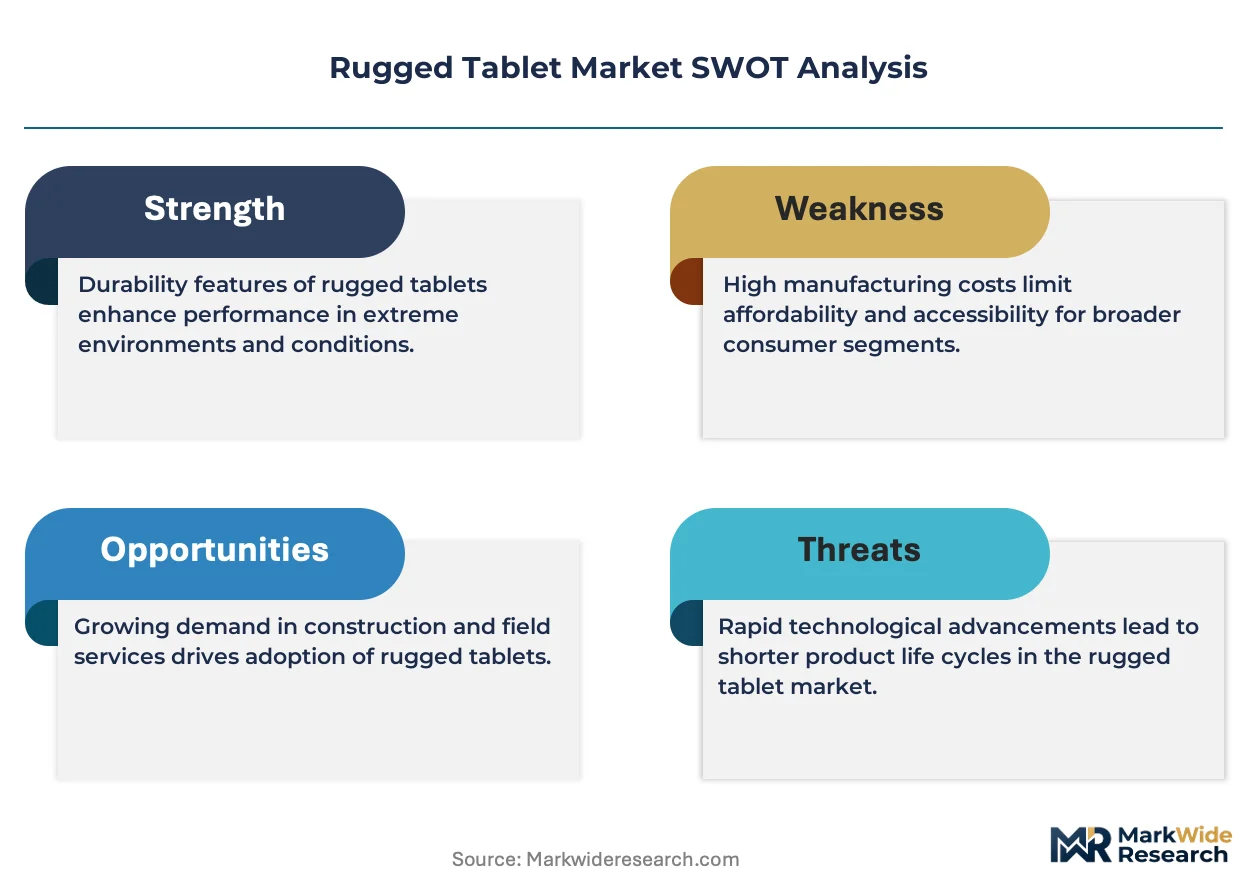
This market compounds regulatory value through cascading encryption mandates, with the EU's Ecodesign for Sustainable Products Regulation and U.S. NIST FIPS 140-2 requirements creating dual compliance premiums that reshape supplier economics.
For Market Incumbents: Lock in backward integration into Taiwanese magnesium alloy supply and Japanese thermal material sourcing before qualification windows narrow. Secure MIL-STD-810H pre-certification for next-generation chassis designs to defend against emerging pure-play specialists with faster validation cycles. Channel control through GSA schedule positioning and EU defense procurement frameworks represents the critical defensive lever against conglomerate competitors leveraging cross-selling scale. For New Entrants and Emerging Players: The EU's CSRD disclosure requirements in Germany open a window for first-mover advantage in lifecycle-assessed supply chains serving automotive OEMs. India's PLI scheme for electronics manufacturing offers contract assembly entry with lower capital intensity than full ODM development. Target field service verticals in Germany and India with Android-based custom kernel platforms, bypassing defense certification barriers that protect incumbent lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play rugged specialists possessing in-house thermal engineering and cryptographic module design capabilities. Long-term viability hinges on dual-use technology classification eligibility that spans defense and federal law enforcement procurement. Watch for BIS certification acceleration in India and carbon-footprint disclosure enforcement in Germany as inflection signals for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| FIPS 140-2 Level 3 Module Integration | Compresses supplier qualification to vendors with in-house cryptographic engineering for U.S. defense contracts. |
| Backward Integration into Thermal Materials | Captures margin concentration in MIL-grade magnesium alloy and gasketing systems from Japanese suppliers. |
| CSRD-Compliant Supply Chain Documentation | Creates first-mover advantage for EU automotive OEM procurement under Ecodesign sustainability mandates. |
| Android Custom Kernel Development | Enables sensor integration flexibility for field service and transportation verticals in Germany and India. |
| India PLI Contract Assembly Investment | Reduces landed cost exposure for NATO-aligned defense orders while satisfying domestic content requirements. |
Methodological Framework
Bottom-up defense procurement modeling reconciled against top-down ODM capacity tracking forms the analytical core of this study. Primary interviews with rugged tablet product managers, defense procurement officers at NATO member agencies, industrial automation distributors, and thermal materials sourcing executives informed demand-side validation. Secondary sources include FCC equipment authorization databases, EU Tenders Electronic Daily defense solicitations, BIS certification registries, and SEC filings from diversified electronics conglomerates with rugged computing divisions.
Input-output matrices connect end-user segment demand (military, field service, construction, transportation) against technology choices (Android, Windows, Linux), product durability tiers (fully rugged, semi-rugged, ultra-rugged, handheld), and connectivity specifications (LTE, Wi-Fi, Bluetooth, NFC). CAGRs derive from regression analysis of procurement volume trends, certification timeline compression, and material cost trajectories across the projection horizon. Forecast inputs incorporate PLI scheme subsidy trajectories in India, REACH substance restriction phase-ins, and FCC radio module pre-approval pipeline data.
Revisions become necessary when defense budget authorization delays, thermal material supply disruptions, or encryption standard upgrades materialize outside modeled pathways. Forecasts reflect documented assumptions regarding NATO procurement consolidation timelines and EU sustainability disclosure enforcement cadence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Construction Wearables Market
Others
Rope Market
Others
Badminton Apparel Market
Others
Handheld Mobile Computers Market
Others
North America Wiring Duct Market
Others
North America Micro Market
Others
Global Hair Loss Treatment Products Market
Others
Asia-Pacific Air Separation Unit Market
Others
Channel-In-A-Box (Ciab) Market
Others
Connected Living Room Market
Others
Latin America Contract Packaging Market
Others
North America Orange Market
Others
India Smart Home Market
Others
Molybdenum-99 Market
Others
Latin America Fire Sprinklers Market
Others
Smart Badge Market