
 North America Ultraviolet Disinfection Equipment Market | 2026-2036
North America Ultraviolet Disinfection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ultraviolet Disinfection Equipment Market Intelligence
Canadian and Mexican municipal infrastructure investment is fragmenting the competitive landscape, once dominated by US-based suppliers. Xylem Inc. leverages its extensive water technology portfolio to secure large-scale contracts in the United States. Trojan Technologies specializes in municipal water and wastewater treatment solutions across North America. Halma PLC differentiates through its focus on specialized UV systems for healthcare and industrial applications.
Ultraviolet disinfection equipment utilizes germicidal UV-C light, typically at a wavelength of 254 nanometers, to inactivate microorganisms. This chemical-free process disrupts the DNA of bacteria, viruses, and protozoa, rendering them unable to reproduce and cause disease in water, air, or on surfaces. Continuous flow systems represent the largest product type, driven by municipal water treatment applications. Within end-user segments, healthcare facilities show high growth for air purification and surface disinfection units, commanding premium pricing for certified performance.
The U.S. Environmental Protection Agency (EPA) and Health Canada set stringent microbial standards for drinking water, directly mandating UV system adoption in many municipalities. Concurrently, the FDA's guidelines for food processing and healthcare settings influence equipment design and validation protocols for surface disinfection. Supplier success will depend on navigating the divergent validation requirements and performance standards between municipal water and high-purity industrial applications.
Market Dynamics
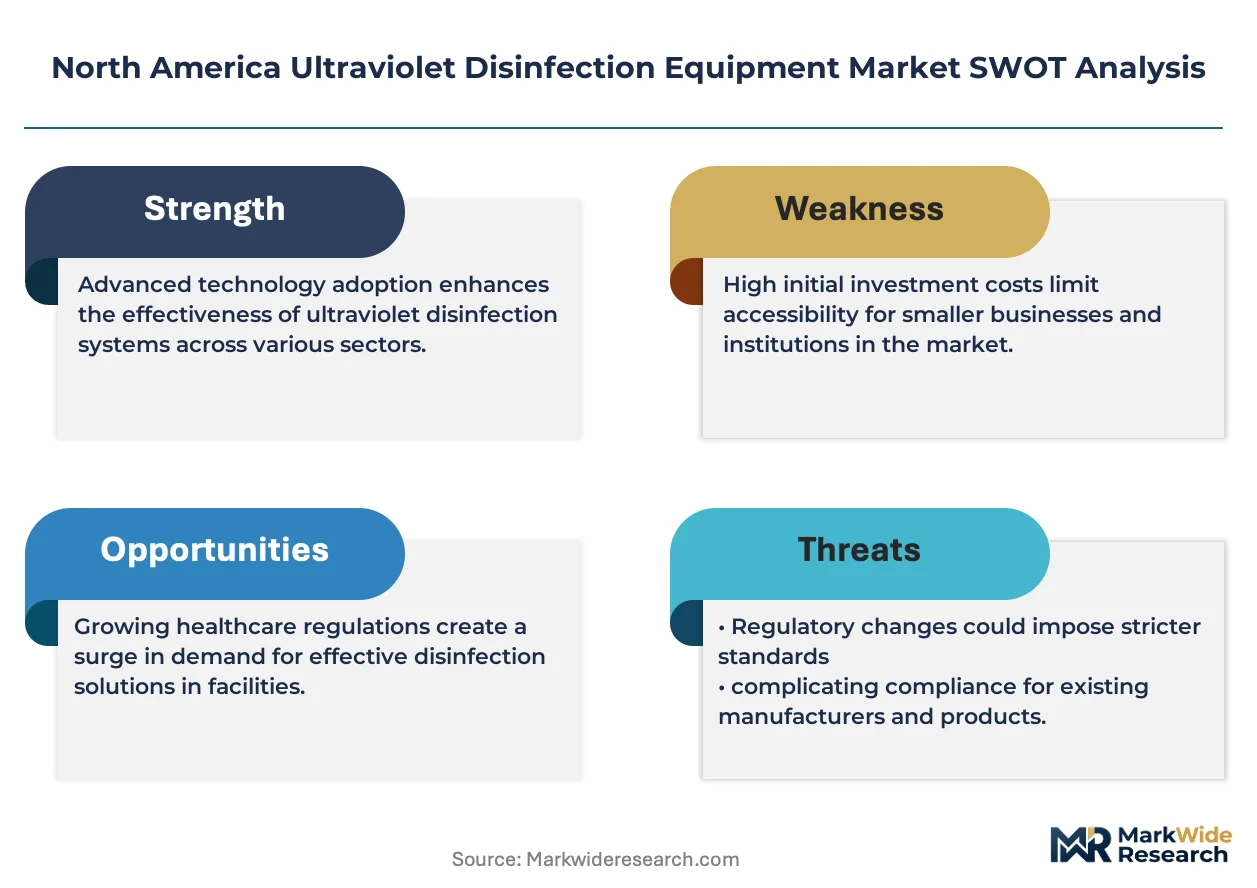
The central tension in the North America market is the divergence between large-scale, cost-sensitive municipal water projects and high-margin, performance-certified applications in healthcare and food processing. This bifurcation shapes technology development, regulatory compliance strategies, and competitive positioning for all suppliers.
Growth Catalysts
- Stricter Water Regulations:The EPA's microbial contaminant rules for drinking water and wastewater discharge are compelling municipalities across the United States to invest in UV disinfection systems as a primary or secondary treatment barrier.
- Healthcare-Associated Infections:Heightened focus on preventing HAIs in hospitals and clinics across Canada and the U.S. drives adoption of mobile and fixed UV-C systems for surface and air disinfection, particularly in operating rooms.
- Mexican Infrastructure Modernization:Federal and state-level investment in upgrading municipal water and wastewater treatment infrastructure in Mexico creates new demand for continuous flow UV systems, diversifying the market beyond the US and Canada.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of large-scale UV disinfection systems presents a substantial barrier for smaller municipalities in the United States and Canada with constrained capital budgets, delaying infrastructure upgrades.
- Performance Sensitivity:UV efficacy is significantly reduced by turbidity and suspended solids in water, requiring costly pre-filtration systems that increase the total cost and complexity of municipal water treatment projects.
- Specialized Component Dependency:The supply of high-output, medium-pressure UV-C lamps is concentrated among a few global manufacturers, creating potential supply chain vulnerabilities and pricing power that impacts equipment producers across North America.
Strategic Opportunities
- Food and Beverage Processing:Expanding applications in the food and beverage sector for process water disinfection, surface sanitization of conveyor belts, and packaging sterilization represents a significant growth vector beyond traditional water treatment.
- UV-C LED Integration:The maturation of UV-C LED technology offers opportunities for developing compact, mercury-free, and point-of-use disinfection systems for consumer, commercial, and specialized industrial applications previously unaddressable by conventional lamp technology.
- Service and Retrofit Market:A large installed base of aging UV systems in North American municipalities creates a substantial opportunity for service contracts, performance upgrades, and retrofitting with more efficient lamp and ballast technologies.
Industry Challenges
- Divergent Validation Protocols:Equipment suppliers face the operational challenge of navigating different validation and certification requirements between the EPA for municipal water, the FDA for medical devices, and USDA for food contact surfaces.
- Integration with Legacy Infrastructure:Retrofitting modern UV equipment into decades-old water treatment plants across the United States presents significant engineering and integration challenges, often requiring custom designs and extended plant downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ultraviolet Disinfection Equipment Market |
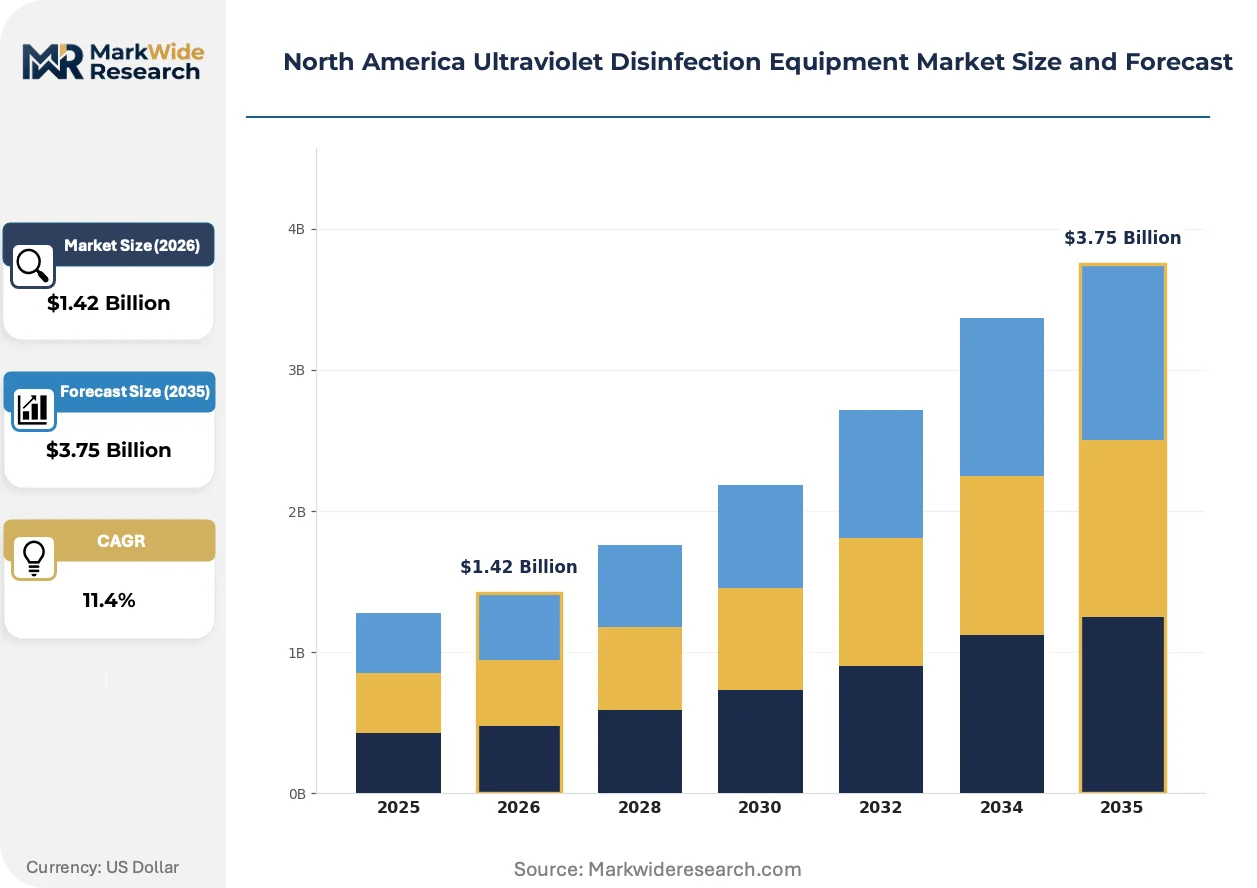
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Chamber Systems, Continuous Flow Systems, Chemical Feed Systems Application: Water Treatment, Air Purification, Surface Disinfection, Chemical Processing End User: Healthcare Facilities, Food Processing, Residential, Industrial Installation: Wall-Mounted, Ceiling-Mounted, Sink-Mounted, Standalone |
| Companies Covered | Xylem Inc., Trojan Technologies, Halma PLC, Atlantic Ultraviolet Corporation, Advanced UV, Inc., American Ultraviolet, Lumalier Corporation, Evoqua Water Technologies LLC, Calgon Carbon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ultraviolet Disinfection Equipment Market Strategic Shifts & Innovations
The market is shifting from a focus on hardware sales toward data-enabled system performance and lifecycle management. This evolution is driven by advancements in sensor technology and regulatory demands for verifiable, continuous disinfection efficacy in critical applications across North America.
Sensor integration is a defining technological shift. Real-time UV intensity sensors, flow meters, and water quality monitors provide continuous feedback on system performance. Large municipalities are the primary adopters, seeking to optimize energy consumption and validate regulatory compliance. This infusion of data is digitizing maintenance schedules, moving from preventative to predictive models and reducing operational costs.
EPA regulations, specifically the Long Term 2 Enhanced Surface Water Treatment Rule, directly mandate treatment for chlorine-resistant protozoa like Cryptosporidium. This rule makes UV disinfection a non-negotiable technology for many public water systems in the United States that use surface water sources. The municipal water treatment segment is most affected, forcing investment in validated UV systems to achieve compliance.
Municipal procurement behavior is evolving from single capital purchases to longer-term service and performance-based contracts. This model shifts the burden of system upkeep, lamp replacement, and performance guarantees to the equipment supplier. The trend is most visible in large-scale infrastructure projects across the United States, where cities seek to de-risk technology ownership and ensure predictable operational expenses.
North America Ultraviolet Disinfection Equipment Market Segmentation
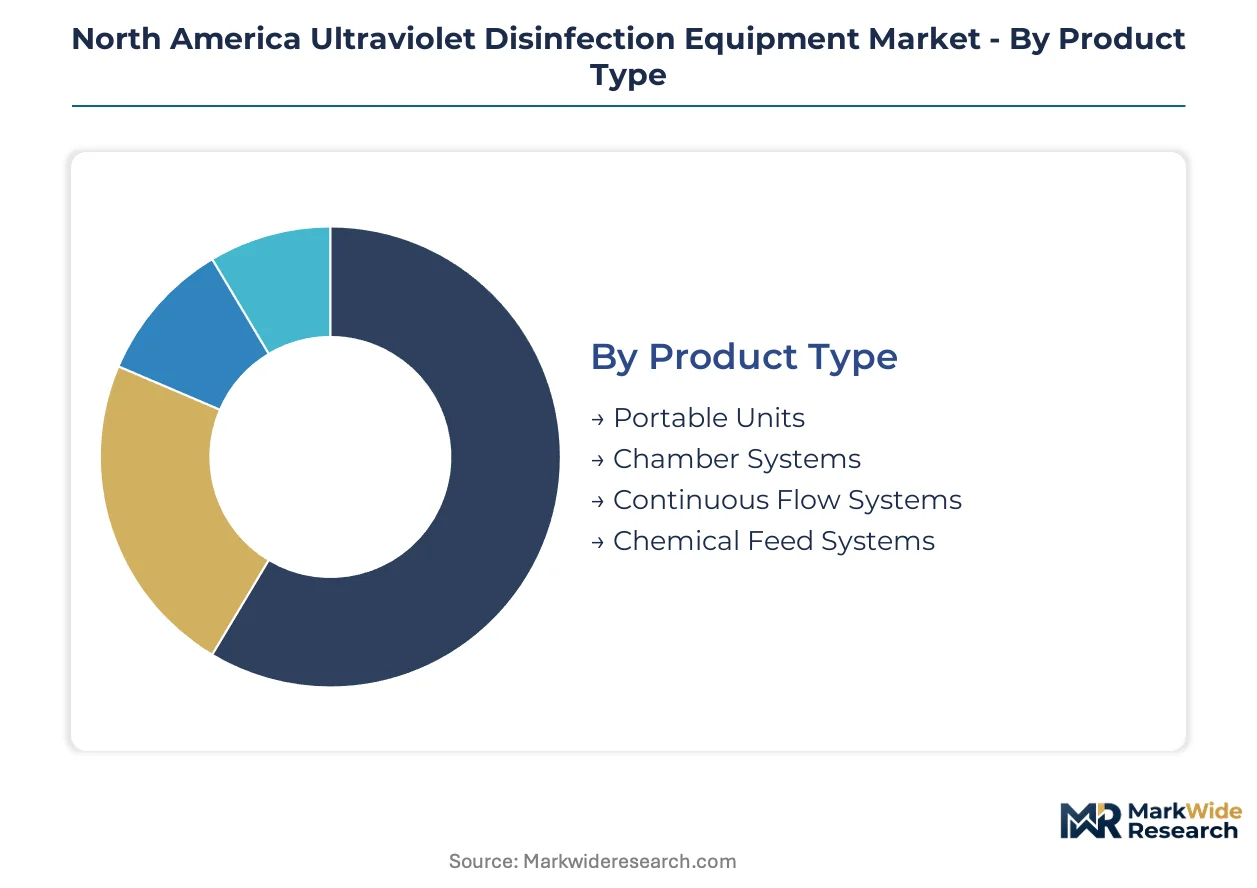
The North America ultraviolet disinfection equipment market is highly diversified, reflecting varied requirements across municipal, industrial, and healthcare sectors. Understanding these distinct segments is crucial for suppliers to tailor product development, pricing strategies, and market penetration efforts across the United States, Canada, and Mexico.
Product Type:
After-sales service intensity varies significantly across product types, with complex continuous flow systems requiring specialized maintenance and lamp replacement schedules to ensure regulatory compliance and performance guarantees.
- Continuous Flow Systems:These large-scale units integrate into pipelines to treat water or wastewater as it passes, ensuring continuous disinfection. Demand is concentrating in municipal water projects across the United States and Canada, driven by stringent EPA and Health Canada regulations for microbial contaminants.
- Portable Units:Compact, mobile devices designed for on-demand disinfection of surfaces or air in various settings. Healthcare facilities in the U.S. and Canada are adopting these for targeted surface sanitization in operating rooms, commanding premium pricing for certified efficacy against healthcare-associated infections.
- Chamber Systems:These systems treat a batch of water or air within a contained chamber, suitable for lower flow rates or specific industrial processes. Mexico's industrial sector is gradually increasing its adoption for process water treatment in manufacturing.
- Chemical Feed Systems:UV systems combined with chemical dosing for enhanced or synergistic disinfection, often used in complex industrial wastewater applications. Industrial facilities in the U.S. leverage these for advanced oxidation processes in specific chemical processing streams.
By volume, Continuous Flow Systems leads. By growth pace, Portable Units is ahead.
Application:
The specific application dictates the required UV dose, system design, and validation protocols, creating distinct product development pathways for manufacturers serving different needs.
- Water Treatment:This application focuses on disinfecting potable water, wastewater, and process water to inactivate pathogens. Municipalities in the United States and Canada represent the largest customer base, driven by EPA and Health Canada mandates for Cryptosporidium inactivation.
- Surface Disinfection:Utilizes UV-C light to sanitize surfaces in healthcare, food processing, and commercial environments. Healthcare facilities in North America are primary adopters for preventing the spread of hospital-acquired infections, requiring validated performance.
- Air Purification:Employs UV-C lamps to inactivate airborne pathogens in HVAC systems or standalone air purifiers. Commercial buildings and healthcare settings in the U.S. are increasingly investing in these systems for improved indoor air quality.
- Chemical Processing:UV systems are used for advanced oxidation processes, TOC reduction, or disinfection of ultrapure water in sensitive industrial applications. Semiconductor manufacturing in the United States requires high-purity water, often relying on UV for final disinfection stages.
The integration requirements for Water Treatment are more complex than for Air Purification.
End User:
Customer type significantly influences procurement cycles, budget constraints, and regulatory compliance requirements, shaping supplier engagement strategies.
- Healthcare Facilities:Hospitals, clinics, and long-term care facilities use UV for air, surface, and water disinfection to control infections. These facilities across North America prioritize certified performance and ease of integration into existing infection control protocols.
- Industrial:Diverse applications across manufacturing, power generation, and chemical industries for process water, wastewater, and air treatment. Mexican industrial growth in sectors like automotive and electronics is driving demand for robust UV solutions.
- Food Processing:UV systems disinfect process water, sanitize contact surfaces, and sterilize packaging to meet stringent food safety standards. Food and beverage manufacturers in the U.S. are expanding UV adoption to reduce chemical usage and ensure product integrity.
- Residential:Smaller-scale UV systems for point-of-entry or point-of-use water purification in homes. Consumer demand for chemical-free water treatment in the United States supports the market for compact, easy-to-install units.
The demand elasticity for Healthcare Facilities differs significantly from Residential.
Installation:
The installation method dictates system footprint, power requirements, and integration complexity, influencing product design and deployment logistics.
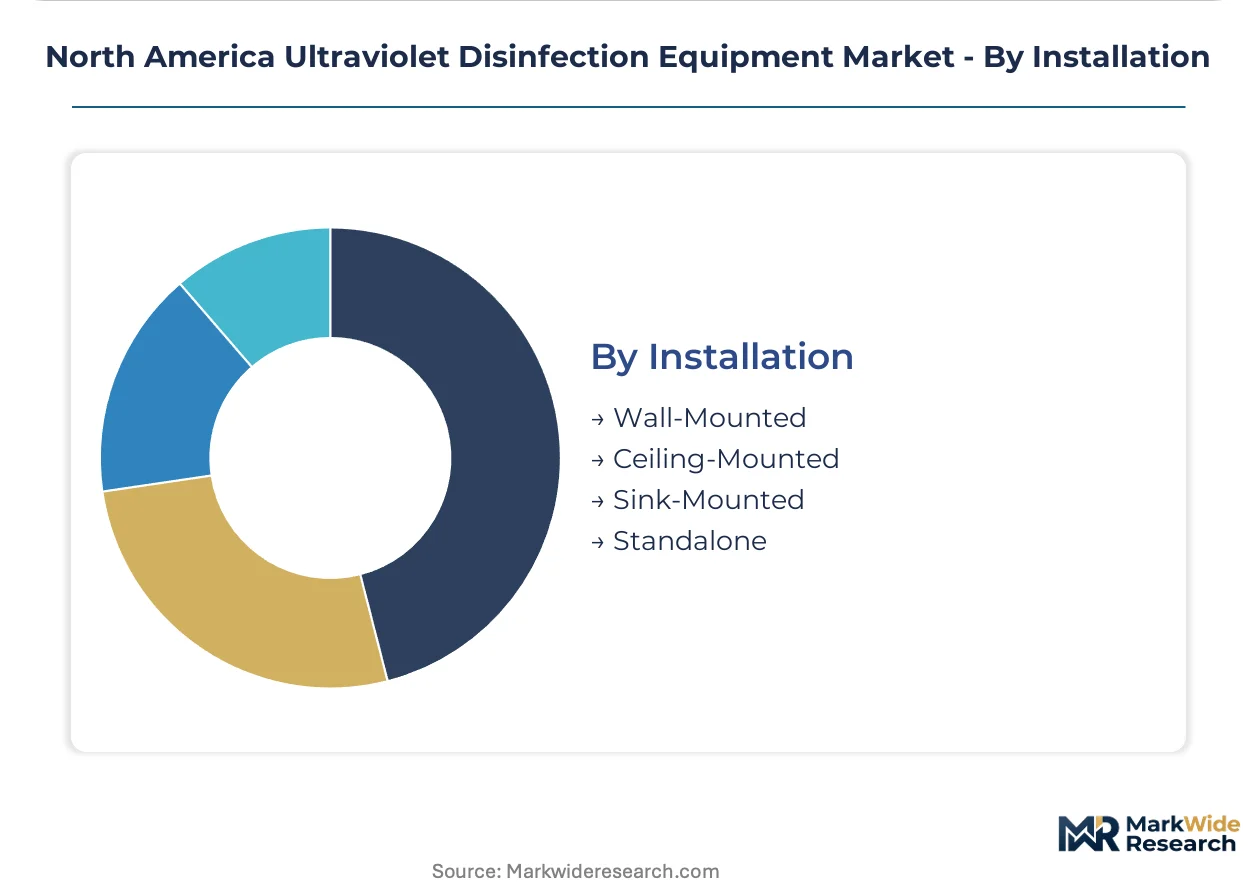
- Standalone:Self-contained units that operate independently, offering flexibility and mobility. Portable UV-C disinfection robots for healthcare facilities represent a significant segment within standalone installations across the U.S. and Canada.
- Wall-Mounted:Fixed units attached to walls, typically for air purification in rooms or surface disinfection in specific zones. Commercial kitchens in North America frequently utilize wall-mounted UV systems for continuous air and surface sanitization.
- Ceiling-Mounted:Integrated into overhead structures, often for continuous air disinfection in occupied spaces. Hospitals in the United States are installing ceiling-mounted UV-C systems in waiting areas to reduce airborne pathogen transmission.
- Sink-Mounted:Compact units installed directly at water faucets for point-of-use water disinfection. Residential consumers seeking purified drinking water often choose sink-mounted UV filters for convenience and effectiveness.
Regulatory oversight is more pronounced for Standalone systems compared to Sink-Mounted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply of specialized UV-C lamps and high-output systems concentrates among a few global manufacturers, influencing equipment producers across North America. Significant investments in municipal water infrastructure and healthcare facilities drive regional demand. Regulatory compliance remains a primary catalyst for market expansion.
United States
Demand for UV disinfection systems stems from stringent EPA regulations on drinking water contaminants and heightened focus on healthcare-associated infections. The Long Term 2 Enhanced Surface Water Treatment Rule mandates UV for Cryptosporidium inactivation in public water systems. Major metropolitan areas like Los Angeles are upgrading water treatment plants with advanced UV technologies to ensure public health.
Canada
Canadian municipalities are investing in UV systems due to Health Canada's microbial standards for drinking water and wastewater. Federal and provincial funding programs support infrastructure modernization efforts across the country. Cities such as Toronto are implementing large-scale UV disinfection for their municipal water supplies.
Mexico
Mexican municipal infrastructure modernization creates new demand for continuous flow UV systems, particularly in water and wastewater treatment. Federal and state-level investments target upgrading aging facilities to improve public health outcomes. Industrial corridors in Nuevo León are adopting UV for process water treatment in manufacturing.
US Northeast Corridor
Densely populated urban centers in the US Northeast Corridor require robust UV solutions for both municipal water and healthcare applications. Older infrastructure in cities like New York City faces mandates from the EPA for improved water quality. Hospitals in Boston are implementing advanced UV-C systems for surface and air disinfection to combat infection spread.
North America Ultraviolet Disinfection Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the North America ultraviolet disinfection equipment market. The competitive landscape fragments across large multi-national water technology providers and niche UV system manufacturers. Strategic archetypes include comprehensive water solution providers, specialized municipal UV experts, and focused healthcare UV system suppliers. Geographic expansion into emerging markets like Mexico and portfolio diversification into new applications represent dominant competitive moves among these players.
Among the comprehensive water solution providers, US-based Xylem Inc. represents a player leveraging an extensive technology portfolio across various applications, securing large-scale contracts in the United States. Canadian-headquartered Trojan Technologies exemplifies a specialist in municipal water and wastewater treatment solutions throughout North America, focusing on critical infrastructure projects. UK-based Halma PLC occupies a position as a differentiated supplier, focusing on specialized UV systems for high-purity industrial and healthcare applications, commanding premium pricing for certified performance.
| Leading Market Players |
|---|
| Xylem Inc. |
| Trojan Technologies |
| Halma PLC |
| Atlantic Ultraviolet Corporation |
| Advanced UV, Inc. |
| American Ultraviolet |
| Lumalier Corporation |
| Evoqua Water Technologies LLC |
| Calgon Carbon Corporation |
| Others |
Cost & Logistics Intelligence
Global manufacturing hubs for high-output UV-C lamps dictate downstream equipment pricing power. This concentration creates pricing leverage for component specialists, impacting system integrators across North America.
Pricing Analysis
EPA regulations for microbial contaminants dictate the pricing tier structure for continuous flow systems in municipal water projects. Project-based pricing dominates large-scale infrastructure, while value-based pricing applies to specialized healthcare and industrial applications. Price differentiation hinges on certified performance validation for critical applications and the intensity of bundled after-sales service. Pricing pressure stems from cost-sensitive municipal procurement behavior, particularly for smaller municipalities with constrained budgets. Healthcare facilities, prioritizing validated efficacy, exhibit the least price sensitivity.
Supply Chain Analysis
The global production of high-output, medium-pressure UV-C lamps forms the critical upstream feedstock for disinfection equipment. This production concentrates among a few specialized manufacturers, leading to component dependencies for North American system integrators. Key inputs include these specialized UV-C lamps and advanced ballast technologies. A structural risk involves single-source vulnerability, impacting equipment producers' costs and lead times. Distribution runs through direct sales channels for large municipal and industrial projects, complemented by specialized distributors for healthcare and smaller commercial units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a significant service-attach opportunity, as performance-based contracts and lifecycle management services are expanding faster than initial hardware sales. This shift allows for recurring revenue streams beyond capital expenditure.
For Market Incumbents: Harden core market share within municipal water treatment by securing long-term service and performance-based contracts. This defends against margin pressure from cost-sensitive procurement and new technology entrants like UV-C LED. Deepen vertical integration into specialized lamp or ballast production to mitigate supply chain vulnerabilities. Invest in advanced sensor integration and data analytics to provide verifiable, continuous disinfection efficacy, a key lever for regulatory compliance.
For New Entrants and Emerging Players: Build out niche solutions leveraging UV-C LED technology for compact, mercury-free point-of-use systems in commercial and residential settings. Target the food and beverage processing sector, which represents a penetrable segment for surface sanitization and process water disinfection. A focused go-to-market angle involves offering highly validated, energy-efficient solutions that reduce chemical usage and simplify installation for smaller-scale industrial users.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven infrastructure play because essential public health mandates underpin sustained demand for UV disinfection. Acquisition targets should focus on specialized municipal UV experts with strong service contract portfolios or niche players in high-margin healthcare and food processing applications. The signal to watch is the widespread commercial adoption of UV-C LED technology, indicating a shift towards more compact and sustainable disinfection solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Performance-Based Service Contracts | Shifts risk from municipalities to suppliers, ensuring predictable operational expenses for cities like Toronto. |
| Invest in UV-C LED R&D | Develops mercury-free, compact disinfection systems for consumer and specialized industrial applications. |
| Deepen Regulatory Validation Expertise | Navigates divergent EPA and FDA requirements, commanding premium pricing in healthcare facilities. |
| Geographic Expansion into Mexico | Captures new demand from federal and state-level infrastructure modernization projects in Nuevo León. |
| Integrate Advanced Sensor Technology | Provides continuous feedback for optimizing energy consumption and validating regulatory compliance in large municipalities. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews. These included plant managers from municipal water treatment facilities, infection control specialists, and R&D directors from equipment manufacturers. Secondary validation utilized EPA reports, Health Canada guidelines, FDA validation protocols, and relevant company filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and comprehensive market sizing.
The analytical framework was calibrated using historical market performance and future growth projections across the analysis window. Segmentation dimensions modeled included product type, application, end-user, installation, and regional regulatory frameworks. Compound Annual Growth Rates were derived from a multi-factor growth model. Key industry-specific forecast inputs included municipal infrastructure investment cycles and healthcare infection rates.
Sensitivities concentrate around macroeconomic shifts, evolving regulatory mandates, and technological advancements. Forecasts reflect assumptions regarding continued infrastructure investment and healthcare spending. Cross-checking against external benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Rope Market
Others
Storm Surge Barriers Market
Others
Palatants Market
Others
Digital Media Adaptor (DMA) Market
Others
Global Smartphone ODM Market
Others
Asia-Pacific Medical Simulation Market
Others
Global Luxury High End Furniture Market
Others
Reusable Wine Bags Market
Others
Global Application Testing Services Market
Others
Mainframe Computers Market
Others
Quadrant Scale Market
Others
Dried Egg Market
Others
Latin America Domestic CEP Market
Others
Digital Transformation of Maritime Freight Market
Others
Gas Holders Market
Others
Profilometer Market