
 Novel Drug Delivery Systems in Cancer Therapy Market | 2026-2036
Novel Drug Delivery Systems in Cancer Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Novel Drug Delivery Systems in Cancer Therapy Market Outlook
North American biopharma manufacturing is repositioning its sterile fill-finish capacity toward complex injectable formats. Johnson & Johnson Services, Inc. leverages its Janssen oncology division to sustain leadership in nanoparticle-drug conjugate development. Bristol-Myers Squibb Company anchors its immuno-oncology franchise through sustained-release depot formulations. Novartis AG differentiates via its established liposomal manufacturing infrastructure and radioligand therapy distribution networks.
Novel drug delivery systems in cancer therapy comprise engineered platforms—liposomes typically 100-400 nm, polymeric micelles 10-100 nm, and antibody-drug conjugates with defined drug-to-antibody ratios—that modulate pharmacokinetics to improve tumor accumulation and reduce systemic toxicity. These systems serve the primary commercial purpose of rescuing or extending the therapeutic index of cytotoxic agents that otherwise face dose-limiting toxicities. Liposomes occupy the most mature margin pool within product type segments, while biologics represent the fastest-expanding category driven by antibody-drug conjugate approvals. Targeted delivery technology leads technology segments in clinical pipeline volume, whereas smart biomaterials command premium pricing due to stimulus-responsive release kinetics.
The FDA's breakthrough therapy designation and EMA's PRIME scheme are compressing development timelines and reshaping investment priorities for platform sponsors. The EPA and OSHA jointly govern the occupational exposure limits for cytotoxic drug handling during manufacturing, directly influencing facility capital requirements and geographic siting decisions. Stakeholders must monitor how the EU AI Act and FDA's evolving guidance on real-world evidence will intersect to redefine post-market surveillance obligations for algorithm-guided dosing systems.
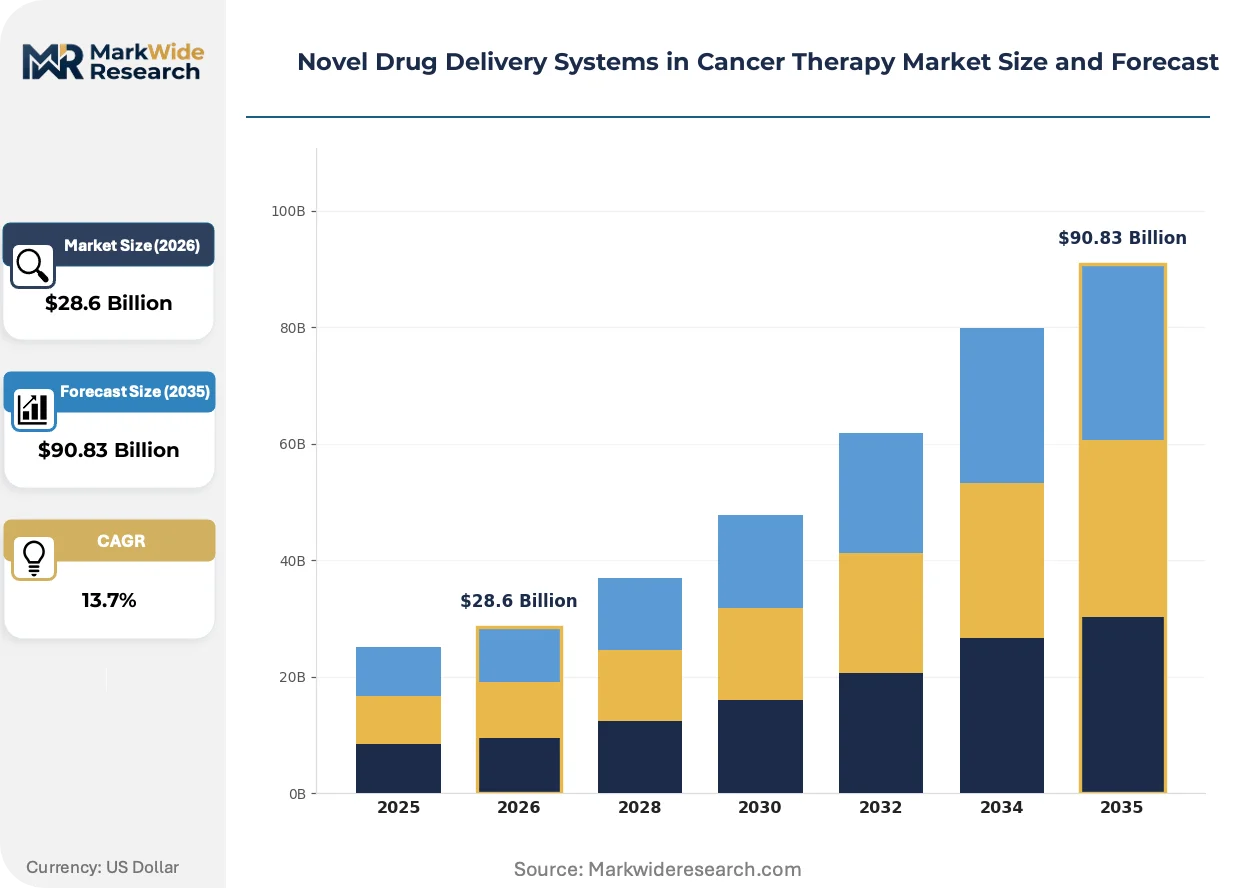
Market Dynamics
The FDA's breakthrough therapy designation and EMA's PRIME scheme are compressing development timelines from clinical proof to commercial launch, while manufacturing capacity for sterile liposomal formulations concentrates among a handful of contract development and manufacturing organizations.
Growth Catalysts
- Accelerated approval frameworks:The FDA's breakthrough therapy pathway and EMA's PRIME scheme compress Phase III-to-launch timelines for liposomal and antibody-drug conjugate candidates. Sponsors redirect R&D budgets toward platform technologies qualifying for these expedited tracks.
- Smart biomaterials in German oncology centers:University medical centers across Germany are integrating stimulus-responsive release platforms into standard-of-care protocols for aggressive solid tumors. This creates pull-through demand for regional manufacturing capacity.
- Nanoparticle infusion infrastructure:Oncology hospitals throughout the United States are expanding dedicated infusion center capacity to accommodate complex nanoparticle-based regimens requiring extended administration protocols and specialized nursing protocols.
Market Restraints
- High-purity lipid input concentration:Synthetic phospholipid supply concentrates among specialty chemical producers in Switzerland and Japan, exposing formulation sponsors to price volatility and allocation risk during demand surges.
- Sterile manufacturing facility scarcity:Aseptic fill-finish capacity for complex injectables remains limited to a small number of FDA- and EMA-inspected sites, creating bottlenecks for late-stage clinical supply and commercial launch.
- Cytotoxic handling compliance burden:EPA and OSHA occupational exposure limits for cytotoxic drug manufacturing impose capital-intensive containment infrastructure requirements that deter new facility entrants.
Strategic Opportunities
- India's biosimilar ADC pathway:CDSCO's evolving framework for antibody-drug conjugate biosimilars creates first-mover positioning for platform sponsors establishing local partnerships ahead of regulatory clarity.
- Home-based subcutaneous depot delivery:Sustained-release depot formulations for immuno-oncology maintenance therapy enable channel shift from hospital infusion to specialty pharmacy distribution, capturing margin from site-of-care economics.
- Algorithm-guided dosing integration:The EU AI Act's risk-classification framework for clinical decision support creates regulatory tailwind for sponsors embedding real-world evidence platforms into post-market surveillance obligations.
Industry Challenges
- Bioconjugate process development talent scarcity:The specialized skill set spanning protein engineering, linker chemistry, and analytical characterization for antibody-drug conjugates concentrates among a small cohort of experienced scientists, constraining pipeline expansion.
- Multi-jurisdictional quality system harmonization:Sponsors must reconcile FDA's evolving guidance on real-world evidence with EMA's GMP Annex 1 revisions and the EU AI Act's post-market monitoring requirements, extending compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Novel Drug Delivery Systems in Cancer Therapy Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Liposomes, Micelles, Biologics Technology: Targeted Delivery, Sustained Release, Smart Biomaterials, Implantable Devices End User: Hospitals, Research Institutions, Clinics, Home Care Therapy Area: Chemotherapy, Immunotherapy, Targeted Therapy, Personalized Medicine |
| Companies Covered | Johnson & Johnson Services, Inc., Teva Pharmaceutical Industries Ltd., Bristol-Myers Squibb Company, Galen Limited, Samyang Biopharmaceuticals Corporation, Spectrum Pharmaceuticals, Inc., Merrimack Pharmaceuticals, Inc., NanoCarrier Co., Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Novel Drug Delivery Systems in Cancer Therapy Market Strategic Shifts
Platform engineering is converging with digital infrastructure to reshape how drug delivery systems are developed, validated, and deployed across clinical and commercial settings. Three interconnected developments are compressing traditional boundaries between formulation science, regulatory strategy, and patient access.
Liposomal encapsulation technology is expanding into radioligand therapy distribution networks, where the established cold-chain infrastructure and sterile handling protocols originally developed for cytotoxic liposomes now support short-half-life radiopharmaceuticals. Novartis AG and specialized radiopharmacy networks in Germany and the United States are repurposing this capacity to enable same-day patient dosing for lutetium-based therapies. The structural consequence is cross-platform utilization of manufacturing assets that were previously siloed by modality.
REACH regulation amendments governing persistent organic pollutants and the EU AI Act's risk-based classification for clinical decision support systems are jointly elevating documentation requirements for smart biomaterial platforms. Sponsors must now demonstrate stimulus-responsive release kinetics through validated algorithmic controls, not merely bench-scale proof-of-concept. The antibody-drug conjugate segment faces the steepest compliance curve, as drug-to-antibody ratio consistency must be proven across AI-guided process analytical technology.
Oncology procurement at integrated delivery networks is consolidating supplier relationships around platform sponsors offering bundled formulation development, regulatory submission support, and commercial manufacturing. Hospital systems in the United States are narrowing their approved vendor lists for nanoparticle-based regimens to three or fewer CDMO partners with demonstrated FDA inspection history. This concentration is most visible in Texas and California, where major cancer centers are standardizing on single-source contracts for liposomal and polymeric micelle formulations.
Novel Drug Delivery Systems in Cancer Therapy Market Segmentation
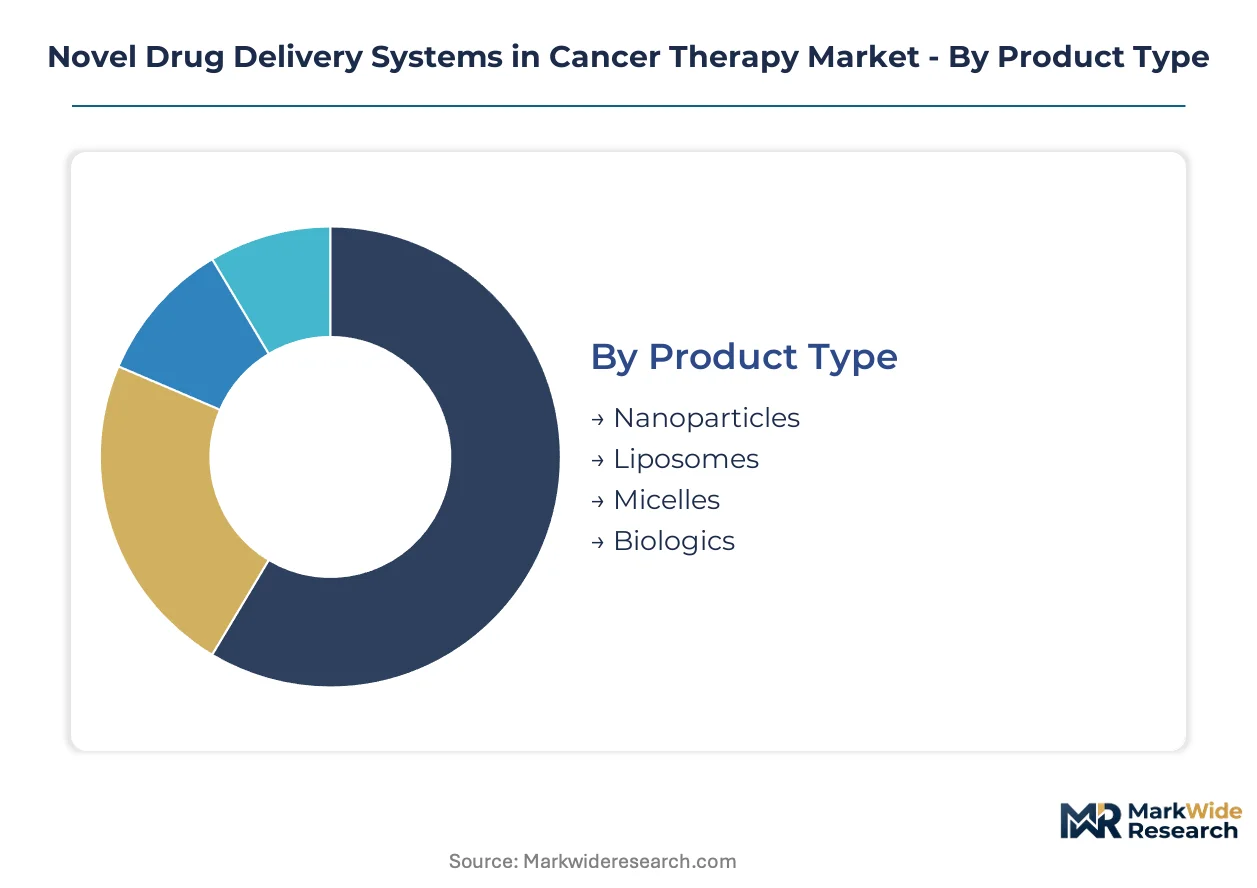
Segmentation in cancer drug delivery reveals how formulation sophistication maps to clinical utility and reimbursement tiers. Platform selection determines manufacturing complexity, regulatory pathway, and site-of-care requirements. Understanding these divisions exposes where margin pools concentrate and which technologies are displacing legacy standards.
Product Type:
Volume concentration sits with established encapsulation platforms, while premium pricing attaches to biological conjugation technologies that command orphan drug economics.
- Liposomes:Phospholipid bilayer vesicles 100-400 nm in diameter encapsulate cytotoxic agents to reduce cardiotoxicity and myelosuppression. Demand concentrates in United States oncology hospitals expanding infusion capacity for Doxil-equivalent regimens, constrained by synthetic phospholipid supply bottlenecks from Swiss and Japanese specialty chemical producers.
- Biologics:Antibody-drug conjugates with defined drug-to-antibody ratios enable tumor-selective payload release through lysosomal proteolysis. German university medical centers are integrating these platforms into aggressive solid tumor protocols, creating pull-through demand for regional fill-finish capacity.
- Nanoparticles:Polymeric or inorganic carriers below 100 nm exploit enhanced permeability and retention effect for passive tumor accumulation.
- Micelles:Amphiphilic block copolymer assemblies 10-100 nm solubilize hydrophobic agents for intravenous administration.
Today's leader: Liposomes. Tomorrow's challenger: Biologics.
Technology:
Clinical pipeline volume clusters around precision targeting mechanisms, though manufacturing margin concentrates with stimulus-responsive systems that justify premium reimbursement through differentiated pharmacokinetics.
- Targeted Delivery:Ligand-directed platforms—folate receptors, transferrin, or antibodies—achieve active tumor homing beyond passive accumulation. United States integrated delivery networks are narrowing approved vendor lists to CDMOs with demonstrated FDA inspection history for these complex bioconjugates.
- Smart Biomaterials:pH-, temperature-, or enzyme-responsive matrices enable triggered release at tumor microenvironments. EU AI Act documentation requirements now mandate validated algorithmic controls for stimulus-responsive kinetics, elevating compliance costs for platform sponsors.
- Sustained Release:Depot formulations extend dosing intervals for maintenance therapy.
- Implantable Devices:Biodegradable wafers and pumps enable localized drug delivery to resection cavities.
Targeted Delivery dominates pipeline submissions. Smart Biomaterials capture the steepest pricing premiums.
End User:
Site-of-care economics are shifting therapy administration from hospital-based infusion to specialty pharmacy channels where subcutaneous depot formulations enable home-based maintenance.
- Hospitals:Academic medical centers and community oncology programs administer complex nanoparticle regimens requiring specialized nursing protocols and extended infusion monitoring. Texas and California cancer centers are standardizing on single-source CDMO contracts to secure supply continuity.
- Home Care:Subcutaneous sustained-release depots for immuno-oncology maintenance enable channel migration from infusion centers to patient self-administration, capturing margin from reduced site-of-care costs.
- Research Institutions:Preclinical and clinical trial sponsors evaluate novel platform pharmacokinetics.
- Clinics:Community oncology practices handle stable, approved regimens with lower complexity.
Hospital infrastructure anchors current revenue. Home Care represents the fastest channel expansion trajectory.
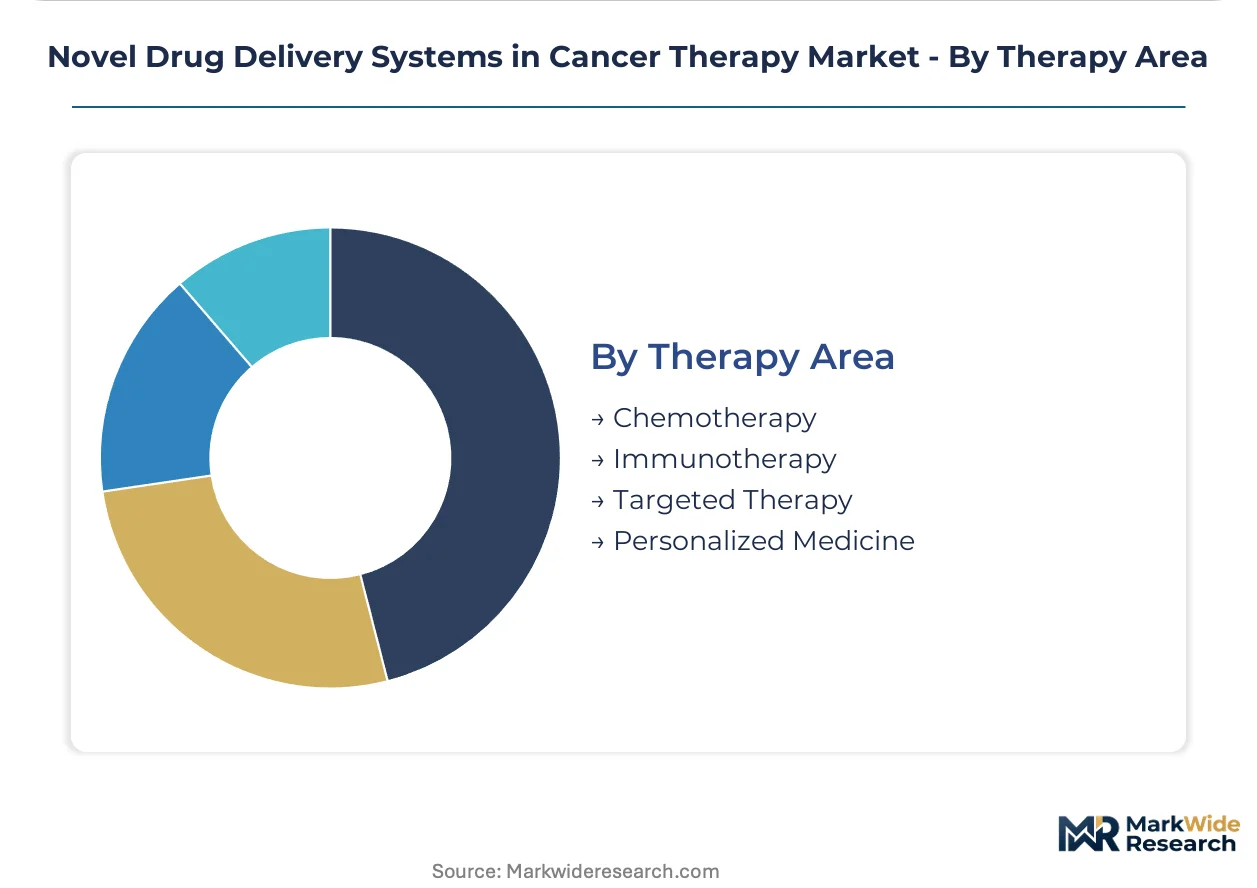
Therapy Area:
Application breadth stretches from cytotoxic rescue to biological modulation, with regulatory tailwinds compressing development timelines for breakthrough-designated modalities.
- Chemotherapy:Liposomal and nanoparticle formulations of taxanes, anthracyclines, and platinum agents rescue therapeutic index for dose-limited cytotoxics. FDA breakthrough therapy designation and EMA PRIME scheme are accelerating Phase III-to-launch timelines for these platform improvements.
- Immunotherapy:Sustained-release depots and antibody-drug conjugates extend checkpoint inhibitor durability and enable combination regimens.
- Targeted Therapy:Small molecule kinase inhibitors formulated in micelles or nanoparticles improve bioavailability.
- Personalized Medicine:Patient-specific dosing algorithms integrate pharmacogenomic data with drug delivery kinetics.
Chemotherapy platforms generate current cash flows. Immunotherapy applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's university medical centers are integrating smart biomaterial platforms faster than United States oncology hospitals can expand infusion infrastructure, creating divergent regional growth trajectories across the developed markets.
United States
Oncology hospitals in Texas and California are expanding dedicated infusion center capacity for nanoparticle-based regimens requiring extended administration protocols. FDA's breakthrough therapy designation compresses Phase III-to-launch timelines for liposomal candidates. The Greater Boston cluster anchors bioconjugate process development talent concentration.
Germany
University medical centers across Bavaria and North Rhine-Westphalia are embedding stimulus-responsive release platforms into standard-of-care protocols for aggressive solid tumors. EMA's PRIME scheme accelerates regulatory pathways for platform sponsors. The Munich-Stuttgart corridor concentrates radioligand therapy distribution infrastructure repurposed from liposomal cold-chain networks.
Switzerland
Synthetic phospholipid production concentrates among specialty chemical producers serving global liposomal formulation demand. Swissmedic maintains stringent GMP standards that influence facility capital requirements across European manufacturing. The Basel-Zurich axis hosts contract development organizations with demonstrated FDA and EMA inspection history.
Japan
PMDA's evolving framework for antibody-drug conjugate approvals creates regulatory tailwind for biologics segment expansion. METI's industrial policy supports domestic manufacturing capacity for complex injectable formats. The Kanto region around Tokyo anchors nanoparticle process development infrastructure serving Asia-Pacific clinical trial supply.
India
CDSCO's developing biosimilar ADC pathway attracts platform sponsors establishing local partnerships ahead of regulatory clarity. The PLI scheme for pharmaceuticals incentivizes sterile fill-finish capacity expansion for export markets. Maharashtra and Gujarat clusters concentrate contract manufacturing organizations targeting European and North American sponsor demand.
Novel Drug Delivery Systems in Cancer Therapy Market Competitive Environment
United States producers anchor one tier of the competitive structure; Swiss and Japanese specialists hold critical input supply positions that influence formulation economics. The vendor base concentrates around three strategic archetypes: diversified pharmaceutical conglomerates with captive oncology divisions, pure-play bioconjugate developers, and specialized contract manufacturing organizations with regulatory inspection history. Competitive moves center on sterile manufacturing capacity expansion and strategic partnerships to secure synthetic phospholipid supply allocation.
Within the diversified pharmaceutical tier, Johnson & Johnson Services, Inc. and Novartis AG exemplify platform sponsors leveraging established manufacturing infrastructure and distribution networks. Bristol-Myers Squibb Company occupies a position representing immuno-oncology franchise anchoring through sustained-release depot capabilities. These three entities sit within the segment of players repurposing liposomal cold-chain assets for emerging radioligand therapy distribution.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Bristol-Myers Squibb Company |
| Galen Limited |
| Samyang Biopharmaceuticals Corporation |
| Spectrum Pharmaceuticals, Inc. |
| Merrimack Pharmaceuticals, Inc. |
| NanoCarrier Co., Ltd. |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Synthetic phospholipid costs cascade from Swiss and Japanese specialty chemical producers through liposomal formulation sponsors to United States oncology hospitals, with price premiums widening at each tier based on GMP certification grade and FDA inspection history.
Pricing Analysis
Distributor margins for sterile liposomal formulations compress as hospital procurement consolidates around single-source CDMO contracts in Texas and California. Three-tier pricing structure across GMP-certified premium, standard clinical-grade, and research-use economy levels separates formulation sponsors by regulatory track record. Cost compression in the economy tier intensifies because Indian contract manufacturers are expanding sterile fill-finish capacity for export markets. Academic medical centers exhibit the highest price sensitivity due to fixed reimbursement schedules, while German university hospitals accept premium pricing for stimulus-responsive smart biomaterials.
Supply Chain Analysis
Dual-sourcing requirements for high-purity synthetic phospholipids mandate qualification of both Swiss and Japanese suppliers among liposomal formulation sponsors, though actual allocation concentrates with Swiss producers. Raw material dependencies center on hydrogenated soy phosphatidylcholine, polyethylene glycol-lipid conjugates, and cholesterol derivatives. Single-source vulnerability in aseptic fill-finish capacity creates bottlenecks for late-stage clinical supply. Distribution runs through specialized radiopharmacy networks repurposed from cytotoxic liposomal cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are tightening as German oncology centers mandate validated algorithmic controls for stimulus-responsive release kinetics, favoring platform sponsors with demonstrated regulatory inspection history over cost-competitive alternatives.
For Market Incumbents: Hedge against biosimilar ADC competition by securing captive synthetic phospholipid supply through backward integration into Swiss specialty chemical partnerships. Add sterile manufacturing capacity in the Munich-Stuttgart corridor to capture radioligand therapy distribution synergies. FDA breakthrough therapy designation momentum requires expanded bioconjugate process development teams in Greater Boston.
For New Entrants and Emerging Players: Launch via India's CDSCO biosimilar ADC pathway ahead of regulatory clarity, partnering with Maharashtra and Gujarat contract manufacturers for sterile fill-finish capacity. White-space concentration sits with home-based subcutaneous depot formulations for immuno-oncology maintenance therapy. Target Texas and California integrated delivery networks with bundled formulation development and regulatory submission support.
For Investors and Strategic Acquirers: Consolidation pressure builds where bioconjugate process development talent concentrates among a small cohort of experienced scientists. Long-term viability favors platform sponsors with demonstrated EMA PRIME scheme traction and repurposable liposomal cold-chain assets. Watch for CDSCO regulatory clarity on ADC biosimilars as inflection indicator for Indian manufacturing investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase III-to-launch timelines for liposomal candidates. |
| Manufacturing Scale-Up | Aseptic fill-finish capacity expansion in Germany repurposes radioligand therapy cold-chain infrastructure. |
| Backward Integration | Captive synthetic phospholipid supply from Swiss producers reduces allocation risk during demand surges. |
| Licensing Agreement | CDSCO biosimilar ADC partnerships in India establish first-mover positioning ahead of regulatory clarity. |
| Pipeline Diversification | Smart biomaterial platforms with EU AI Act-compliant algorithmic controls command premium reimbursement. |
Study Parameters
Coverage spans the United States, Germany, Switzerland, Japan, and India, with primary inputs from each market combining structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions include product type, technology platform, end-user channel, and therapy area, with regional regulatory clusters as an additional cross-cutting variable. CAGRs derive from fitted growth curves applied to validated base-year estimates, incorporating antibody-drug conjugate approval velocity and smart biomaterial pricing premiums as key inputs.
Several conditions sit outside the modeled scope, including specific clinical trial outcomes, individual regulatory submission decisions, and unforeseen manufacturing disruptions. Deviation in FDA or EMA guidance on real-world evidence integration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Ceftriaxone Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Tetanus Market