
 Immunosuppressive Drugs Market | 2026-2036
Immunosuppressive Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Immunosuppressive Drugs Market Outlook
Hospital and specialty pharmacy procurement channels are rewriting how immunosuppressive therapies reach end users. Novartis AG leverages its transplant franchise to sustain dominance in calcineurin inhibitor supply chains across European and North American transplant networks. Astellas Pharma anchors its position through deep specialization in prophylactic regimens for kidney and liver transplant recipients. Bristol-Myers Squibb competes aggressively in the T-cell costimulation blockade segment with belatacept, differentiating its portfolio from conventional small-molecule immunosuppressants.
Immunosuppressive drugs are pharmacologic agents that attenuate immune system activity through targeted interference with T-cell activation, cytokine signaling, or lymphocyte proliferation, typically formulated as oral tablets, intravenous infusions, or subcutaneous injections for chronic administration in transplant maintenance and autoimmune disease management. Calcineurin inhibitors constitute the mature revenue backbone of the market, while mTOR inhibitors capture expanding use in malignancy-sparing transplant protocols where sirolimus and everolimus reduce long-term neoplasia risk. Oral administration routes dominate volume due to patient compliance advantages in maintenance therapy, though intravenous formulations retain critical roles in perioperative induction and acute rejection rescue settings.
FDA, EMA, and PMDA frameworks enforce stringent bioequivalence and immunogenicity standards that shape development timelines and market access for both originator and biosimilar immunosuppressants. The FDA's Risk Evaluation and Mitigation Strategies for mTOR inhibitors and calcineurin antagonists mandate specialized prescriber certification, directly constraining which channels can dispense these therapies. Stakeholders must monitor evolving pharmacovigilance requirements and biosimilar interchangeability designations as these regulatory instruments determine competitive substitution dynamics and pricing power across patient type segments.
Market Dynamics
Transplant centers in Germany, Japan, and the United States are consolidating procurement around biologic immunosuppressants as calcineurin inhibitor maintenance regimens face intensifying pharmacovigilance scrutiny under FDA Risk Evaluation and Mitigation Strategies and EMA post-authorization safety study mandates.
Growth Catalysts
- EMA tightened pharmacovigilance frameworks:Post-authorization safety studies for mTOR inhibitors now mandate real-world evidence collection, accelerating hospital adoption of integrated monitoring systems that lock in recurring biologic purchases.
- Chronic kidney allograft dysfunction protocols:Transplant networks in Japan are expanding belatacept-based T-cell costimulation blockade regimens to reduce calcineurin inhibitor nephrotoxicity, creating new therapeutic sequences.
- Autoimmune clinic expansion:Rheumatology centers across the United States are adding infusion suites for intravenous induction therapies, expanding addressable patient pools beyond transplant maintenance.
Market Restraints
- API supply concentration:Tacrolimus and cyclosporine active pharmaceutical ingredient production concentrates in Chinese and Indian contract manufacturers, exposing formulators to customs delays and geopolitical friction.
- Biosimilar immunogenicity thresholds:FDA interchangeability designations require switching studies that extend development timelines by 18-24 months, compressing first-mover windows for follow-on entrants.
- Specialized cold chain requirements:Monoclonal antibody immunosuppressants demand 2-8°C distribution infrastructure that rural transplant centers in Brazil and India cannot consistently maintain.
Strategic Opportunities
- Subcutaneous formulation development:Self-administered belatacept alternatives would unlock home-based maintenance therapy, reducing infusion center burden and capturing patient convenience premiums.
- PMDA regenerative medicine product pathways:Japan's conditional early approval framework for combination cell-immunosuppressant therapies offers accelerated entry for novel induction protocols.
- Pharmacogenomic companion diagnostics:CYP3A5 genotyping to personalize tacrolimus dosing represents an unbundled service opportunity for molecular diagnostic laboratories serving transplant programs.
Industry Challenges
- Immunogenicity assay standardization:Variability in anti-drug antibody detection methods across reference laboratories complicates cross-trial comparisons and regulatory submissions.
- Perioperative inventory management:Transplant centers must maintain dual formularies for both intravenous induction and oral maintenance therapies, straining pharmacy procurement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunosuppressive Drugs Market |
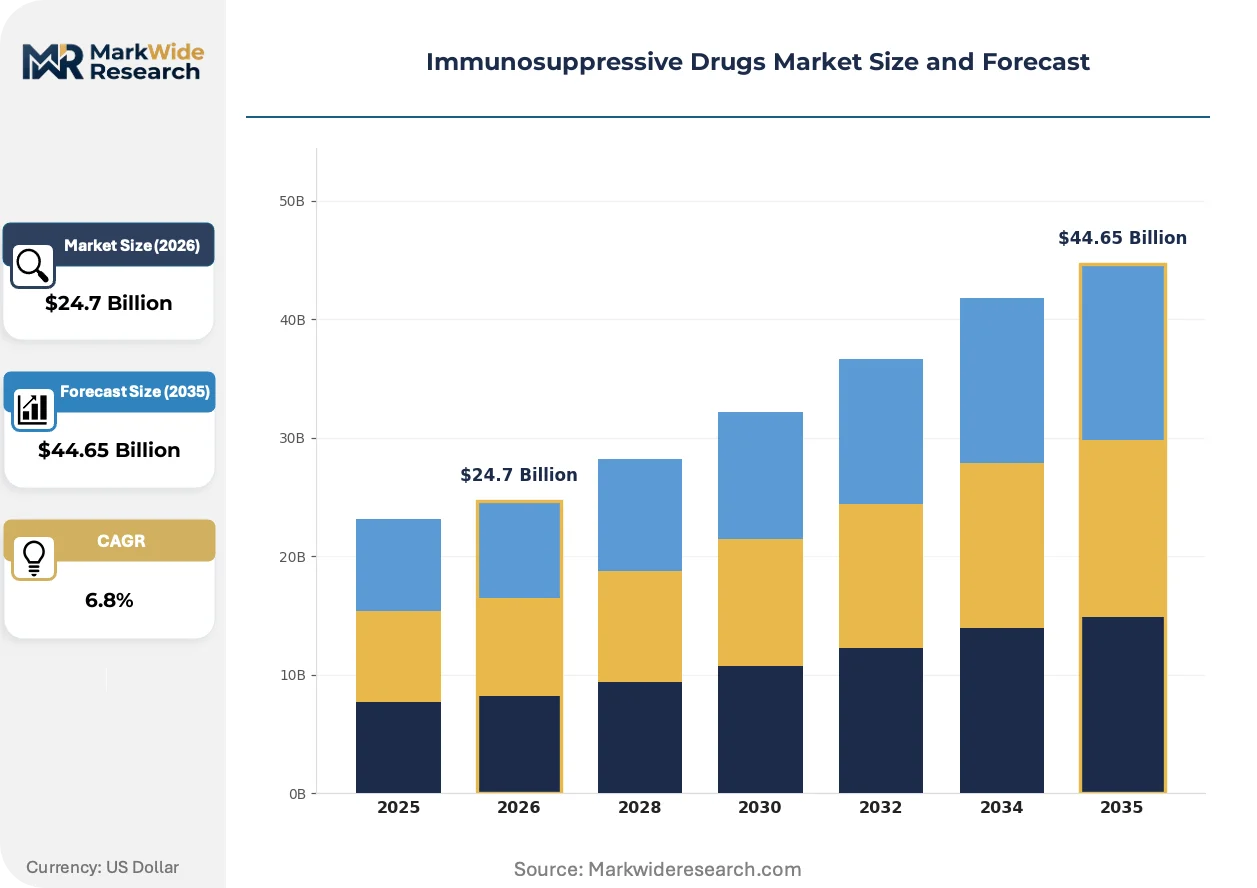
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
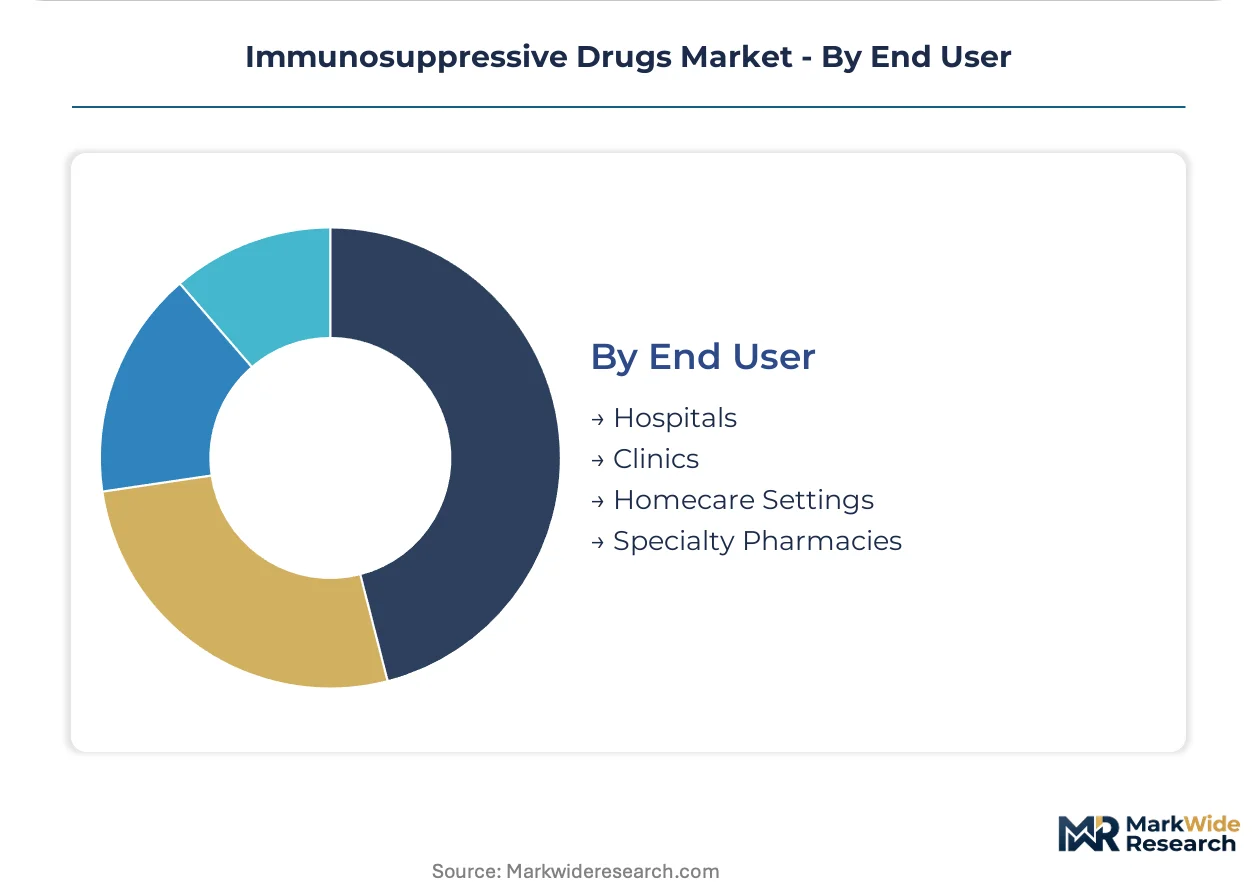
| Segmentation | Product Type: Corticosteroids, Calcineurin Inhibitors, mTOR Inhibitors, Antiproliferative Agents Administration Route: Oral, Intravenous, Topical, Subcutaneous Patient Type: Transplant Recipients, Autoimmune Disorder Patients, Rheumatoid Arthritis Patients, Psoriasis Patients End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies |
| Companies Covered | Novartis AG, Astellas Pharma, Bristol-Myers Squibb, F. Hoffmann-La Roche Ltd, Sanofi, Pfizer, AbbVie, GlaxoSmithKline, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunosuppressive Drugs Market Strategic Shifts
Digital therapeutics and remote patient monitoring platforms are penetrating immunosuppressant adherence programs, while regulatory agencies on three continents tighten real-world evidence requirements for long-term safety surveillance.
Machine learning algorithms trained on electronic health record data are digitizing rejection risk stratification for transplant recipients. Large academic medical centers in the United States and Germany are deploying these tools to compress the interval between biomarker signal and therapeutic intervention. The technology is digitizing how transplant pharmacists prioritize which patients require immediate trough level adjustments versus routine monitoring.
EMA's extended pharmacovigilance mandates for mTOR inhibitors now require 15-year follow-up studies capturing malignancy and metabolic outcomes. This regulatory burden is forcing manufacturers to fund external data consortiums linking national transplant registries with prescription records. Kidney transplant maintenance protocols face the steepest compliance costs, prompting some European centers to reconsider sirolimus-based sparing regimens.
Hospital specialty pharmacy carve-outs are consolidating immunosuppressant dispensing under integrated delivery networks. United States transplant centers are displacing independent retail pharmacies for maintenance therapy fulfillment, capturing 340B drug pricing advantages and adherence data streams. This channel compression is most advanced in Medicare-dependent populations where outcomes-based contracting with payers demands closed-loop medication management.
Immunosuppressive Drugs Market Segmentation
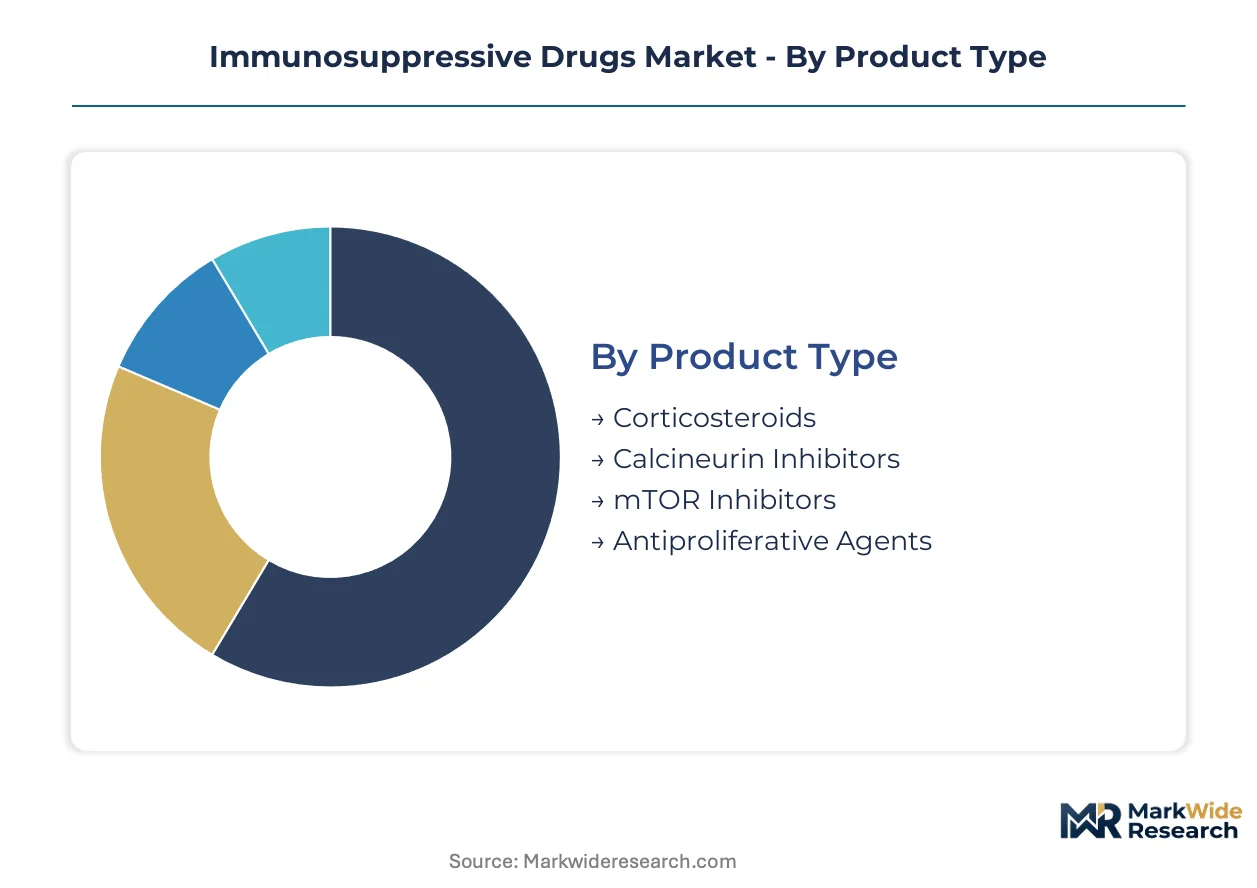
Immunosuppressive drug purchasing cycles vary dramatically across patient populations and care settings, with transplant maintenance therapies generating recurring refill demand while induction protocols drive acute procurement spikes. Understanding these velocity differentials helps manufacturers align inventory positioning with cash conversion patterns across hospital, clinic, and homecare channels.
Product Type:
Calcineurin inhibitors turn inventory fastest due to chronic daily dosing in maintenance populations, while mTOR inhibitors cycle more slowly as malignancy-sparing protocols extend dosing intervals.
- Calcineurin Inhibitors:Tacrolimus and cyclosporine formulations dominate chronic kidney and liver transplant maintenance through potent T-cell activation blockade. German and Japanese transplant centers standardize these agents as backbone immunosuppression, though EMA post-authorization safety studies now mandate enhanced nephrotoxicity monitoring that constrains dose escalation.
- mTOR Inhibitors:Sirolimus and everolimus interrupt IL-2 signaling downstream from calcineurin blockade, finding expanding use in conversion protocols seeking to reduce long-term malignancy risk. United States transplant networks increasingly deploy these agents in kidney recipients with prior skin cancer history, despite FDA Risk Evaluation and Mitigation Strategies requiring specialized prescriber certification.
- Corticosteroids:Methylprednisolone and prednisone remain ubiquitous for acute rejection rescue and early maintenance bridging.
- Antiproliferative Agents:Mycophenolate mofetil and azathioprine suppress lymphocyte proliferation through purine synthesis inhibition, typically combined with calcineurin inhibitors.
Calcineurin inhibitors anchor the volume base while mTOR inhibitors gain share at the steepest rate.
Administration Route:
Cost tiers separate acute intravenous induction from maintenance oral therapies, with subcutaneous biologics commanding premium positioning for patient convenience.
- Oral:Tablet and capsule formulations dominate maintenance phase economics through patient self-administration and pharmacy dispensing efficiency. Rheumatoid arthritis patients in United States specialty pharmacies drive substantial oral volume through methotrexate and mycophenolate protocols.
- Intravenous:Infusion-based delivery captures perioperative induction and acute rejection rescue where rapid immunosuppression loading proves critical. Hospital infusion suites in Japan concentrate intravenous belatacept use for kidney transplant induction.
- Subcutaneous:Self-injected biologics enable home-based maintenance for compliant transplant populations.
- Topical:Localized corticosteroid and calcineurin inhibitor preparations address limited psoriasis and dermatitis indications.
Oral administration generates the highest prescription volume while subcutaneous delivery climbs the fastest as patient convenience preferences reshape maintenance protocols.
Patient Type:
Application urgency varies sharply, with transplant recipients demanding immediate therapy initiation while autoimmune patients tolerate longer diagnostic and titration timelines.
- Transplant Recipients:Kidney, liver, and heart transplant populations require lifelong immunosuppression with narrow therapeutic windows demanding frequent drug level monitoring. United States Medicare-dependent transplant centers concentrate procurement for this segment through 340B pricing mechanisms.
- Autoimmune Disorder Patients:Systemic lupus erythematosus and inflammatory bowel disease populations utilize immunosuppressants for flare management and remission maintenance.
- Rheumatoid Arthritis Patients:Methotrexate-refractory populations escalate to biologic immunosuppressants through step-therapy protocols.
- Psoriasis Patients:Moderate-to-severe cutaneous disease drives systemic immunosuppressant use when topical therapy fails.
Transplant recipients anchor the volume base while rheumatoid arthritis patients gain share at the steepest rate as biologic penetration deepens in rheumatology.
End User:
Customer type determines procurement complexity, with hospital formularies demanding multi-stakeholder approval while homecare channels simplify reorder workflows.
- Hospitals:Academic medical centers and transplant institutes maintain dual formularies for intravenous induction and oral maintenance, capturing integrated delivery network advantages through specialty pharmacy carve-outs. German university hospitals consolidate immunosuppressant procurement under centralized pharmacy governance.
- Specialty Pharmacies:United States 340B-eligible entities displace retail channels for maintenance therapy fulfillment, capturing adherence data and outcomes-based contracting leverage.
- Clinics:Rheumatology and dermatology infusion centers handle biologic administration for autoimmune populations.
- Homecare Settings:Self-administered oral and subcutaneous therapies shift fulfillment toward mail-order and retail channels.
Hospitals anchor the volume base while specialty pharmacies gain share at the steepest rate as channel compression accelerates in Medicare populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Risk Evaluation and Mitigation Strategies anchor procurement patterns in the United States, while EMA pharmacovigilance frameworks and PMDA regenerative medicine pathways shape parallel dynamics across Germany and Japan. These three regulators collectively determine bioequivalence standards, prescriber certification requirements, and real-world evidence collection mandates that filter through hospital formularies and specialty pharmacy networks.
United States
Medicare-dependent transplant centers drive calcineurin inhibitor volume through 340B drug pricing mechanisms. FDA Risk Evaluation and Mitigation Strategies for mTOR inhibitors mandate specialized prescriber certification, constraining which channels can dispense these therapies. Large academic medical centers in Boston and the Research Triangle deploy machine learning algorithms for rejection risk stratification.
Germany
University hospitals consolidate immunosuppressant procurement under centralized pharmacy governance, standardizing tacrolimus and cyclosporine formularies across transplant networks. EMA post-authorization safety studies mandate enhanced nephrotoxicity monitoring that constrains dose escalation protocols. The Rhine-Ruhr and Bavarian medical clusters anchor biologic immunosuppressant adoption.
Japan
Transplant networks expand belatacept-based T-cell costimulation blockade regimens to reduce calcineurin inhibitor nephrotoxicity. PMDA regenerative medicine product pathways offer conditional early approval for combination cell-immunosuppressant therapies. Tokyo and Osaka metropolitan hospitals concentrate intravenous belatacept use for kidney transplant induction.
India
Domestic contract manufacturers supply tacrolimus and cyclosporine active pharmaceutical ingredients to global formulators, exposing the market to customs delays and geopolitical friction. The country's national pharmaceutical regulator enforces bioequivalence standards for biosimilar immunosuppressants. Hyderabad and Ahmedabad clusters concentrate API production capacity.
United Kingdom
NHS specialty pharmacy carve-outs consolidate immunosuppressant dispensing under integrated delivery networks, capturing adherence data and outcomes-based contracting leverage. MHRA pharmacovigilance requirements align with EMA frameworks for post-authorization safety studies. London and Manchester transplant centers drive biologic immunosuppressant procurement.
Immunosuppressive Drugs Market Competitive Environment
Specialized pharmaceutical conglomerates and diversified biopharmaceutical majors split the market into distinct competitive spheres. The vendor base concentrates around calcineurin inhibitor franchises and biologic immunosuppressant portfolios, with calcineurin specialists and mTOR platform holders representing the dominant strategic archetypes. Competitive moves center on transplant network exclusivity agreements and specialty pharmacy carve-out partnerships that lock in recurring maintenance therapy revenue.
Among Swiss and Japanese pharmaceutical conglomerates, Novartis AG and Astellas Pharma exemplify the calcineurin-dominant archetype, while Bristol-Myers Squibb occupies a position within the biologic immunosuppressant tier. These three entities represent contrasting strategic postures: Novartis AG leverages transplant franchise depth across European and North American networks, Astellas Pharma anchors through kidney and liver prophylactic regimen specialization, and Bristol-Myers Squibb differentiates via T-cell costimulation blockade positioning against conventional small-molecule alternatives.
| Leading Market Players |
|---|
| Novartis AG |
| Astellas Pharma |
| Bristol-Myers Squibb |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| Pfizer |
| AbbVie |
| GlaxoSmithKline |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese and Indian tacrolimus API manufacturers compresses pricing power for formulators while amplifying tariff exposure across European and North American transplant networks. This concentration geometry forces a three-tier pricing structure across premium originator, standard generic, and economy biosimilar levels, with supply chain redundancy investments directly feeding into margin compression at the mid-tier.
Pricing Analysis
The customization-premium spread separates patient-specific dosing protocols from standard maintenance regimens, with pharmacogenomic-guided tacrolimus titration commanding substantial service premiums. Pricing stratifies across premium biologic induction, standard small-molecule maintenance, and economy generic continuation tiers, with quality grade and prescriber certification level as primary differentiation drivers. Cost compression in the economy tier is intensifying because 340B-eligible entities capture increasing volume share. Autoimmune patients in retail channels exhibit highest price sensitivity, while transplant centers under bundled payment models show lowest sensitivity due to outcomes-based contracting leverage.
Supply Chain Analysis
Export-control regime scrutiny on pharmaceutical manufacturing equipment limits capacity expansion in certain jurisdictions, constraining global tacrolimus and cyclosporine API flows. Supply concentrates in China, India, and Italy for active pharmaceutical ingredients, with formulation finishing distributed across Germany, Japan, and the United States. Raw material dependencies include fermentation-derived starting materials, specialized chromatography resins, and cold-chain packaging components. Single-source vulnerability characterizes the API tier, where customs delays at Mumbai and Shanghai ports propagate through downstream inventory cycles. Distribution runs through hospital specialty pharmacy carve-outs in Medicare-dependent markets and centralized university hospital governance in European networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
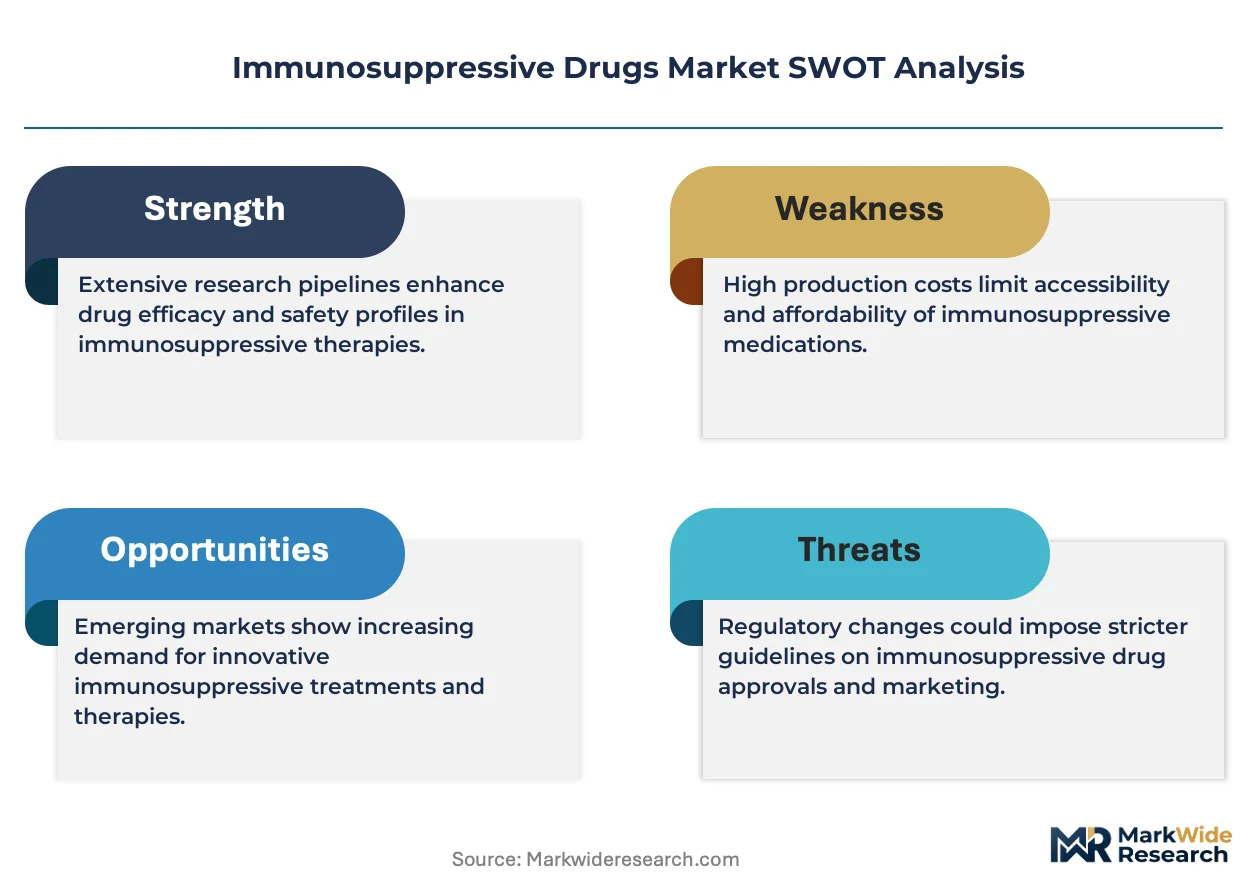
Biosimilar immunosuppressants threaten incumbent pricing architecture, forcing originators to defend through service bundling and data lock-in rather than molecule exclusivity alone.
For Market Incumbents: Build formulary data moats through integrated adherence monitoring platforms that transplant centers cannot easily displace. Anchor calcineurin inhibitor franchises by embedding pharmacogenomic companion services into standard care protocols, raising switching costs for follow-on entrants. Capacity addition in Singapore or Switzerland mitigates geopolitical exposure from concentrated API sourcing. Certification investment in FDA Risk Evaluation and Mitigation Strategies prescriber programs preserves channel control against biosimilar challengers. For New Entrants and Emerging Players: Rural transplant centers in Brazil and India represent underpenetration where cold-chain infrastructure gaps deter incumbent biologics. Target these geographies with room-temperature-stable formulations or localized compounding partnerships that bypass distribution constraints. The most penetrable segment lies in rheumatology infusion suites seeking alternatives to calcineurin nephrotoxicity. A go-to-market angle through molecular diagnostic laboratories unbundles pharmacogenomic testing from drug sales, avoiding direct formulary battles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with integrated delivery network relationships over standalone molecule plays. Long-term viability hinges on recurring revenue capture through maintenance therapy lock-in rather than induction protocol share. Acquisition target archetypes include specialty pharmacy operators with 340B pricing advantages and adherence data streams. The signal to watch is FDA interchangeability designation velocity for biosimilar tacrolimus, which would accelerate pricing erosion and trigger portfolio restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Companion Diagnostic Launch | CYP3A5 genotyping services embed incumbents into dosing protocols at transplant centers. |
| Subcutaneous Formulation Development | Self-administered belatacept alternatives unlock home-based maintenance therapy revenue pools. |
| Specialty Pharmacy Carve-Out Partnership | Integrated delivery network exclusivity agreements capture 340B pricing and adherence data. |
| API Manufacturing Footprint Diversification | Singapore or Switzerland production reduces tariff exposure from concentrated Asian sourcing. |
| Regulatory Approval Pathway Optimization | PMDA regenerative medicine product pathways accelerate novel induction protocol entry in Japan. |
Study Parameters
Initial hypotheses were tested against primary input from transplant pharmacists, formulary directors, regulatory affairs leads, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and national transplant registry databases. Bottom-up patient volume estimates across administration routes and patient types were triangulated with top-down manufacturer revenue assessments to constrain forecast variance.
Demand-supply balance dynamics across the analysis window were modeled through segmented projections by product class, administration route, patient population, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to observed pricing trajectories and volume shifts in Medicare claims data. Forecast inputs incorporated biosimilar interchangeability designation timelines, pharmacovigilance mandate compliance costs, and channel migration patterns toward specialty pharmacy carve-outs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich diversified pharmaceutical conglomerates entering through acquisition would shift outcomes. Material shifts in FDA biosimilar interchangeability standards or EMA pharmacovigilance burden allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market