
 Over-The-Counter (OTC) Analgesics Market | 2026-2036
Over-The-Counter (OTC) Analgesics Market Size, Share, and Industry Trends Forecast 2026-2036
Over-The-Counter (OTC) Analgesics Market Analytics
Acetaminophen is repositioning product economics as manufacturers reformulate away from higher-risk NSAID combinations to meet cardiovascular safety expectations. Johnson & Johnson leverages its pediatric dosing expertise to anchor shelf space in retail pharmacy chains. Bayer AG sustains brand loyalty through its century-old aspirin franchise while competing aggressively in topical analgesic extensions. Haleon PLC differentiates through digestive-friendly ibuprofen formulations that command premium positioning in European markets.
Over-the-counter analgesics encompass non-prescription pharmacological agents—primarily acetaminophen, ibuprofen, aspirin, and naproxen—formulated in dosages typically ranging from 200 mg to 500 mg per unit, designed to inhibit cyclooxygenase enzymes or elevate pain thresholds without physician supervision. These compounds serve the primary commercial purpose of enabling consumers to self-manage mild-to-moderate pain, fever, and inflammation across acute and chronic conditions. Ibuprofen tablets occupy the largest volume share due to their dual anti-inflammatory and analgesic properties, while liquid formulations for pediatric end users represent the fastest-expanding margin pool as caregivers prioritize precise dosing convenience. Retail pharmacies control the dominant distribution channel, though online stores are capturing incremental growth through subscription replenishment models.
The FDA's OTC monograph reform and the EMA's pharmacovigilance requirements for NSAID cardiovascular labeling collectively tighten formulation standards while expanding eligible active ingredients. The WHO's essential medicines list inclusion of specific analgesic compounds shapes procurement patterns in national health systems across developing markets. Stakeholders must monitor regulatory divergence between the FDA's streamlined monograph system and the EU MDR's device-drug combination rules for topical delivery formats, as this fragmentation will determine which manufacturers can operate across both jurisdictions without duplicative compliance investments.
Market Dynamics
Self-medication among aging populations in home healthcare settings is expanding the consumer base for non-prescription pain relief, while regulatory transitions accelerate prescription-to-OTC switches that reshape competitive positioning.
Growth Catalysts
- Monograph Reform:The FDA's evolving OTC monograph process accelerates the transition of certain prescription NSAIDs to non-prescription status in the United States.
- Pharmacy Modernization:Retail network expansion across Southeast Asia concentrates demand in emerging economies where pharmacy infrastructure is upgrading rapidly.
- Pediatric Formulation Demand:Caregivers prioritize precise dosing convenience, driving liquid formulation development for pediatric end users.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production concentrates in specific Asian manufacturing clusters, creating vulnerability to supply disruption.
- Cardiovascular Labeling Requirements:EMA pharmacovigilance mandates for NSAID cardiovascular safety tighten formulation standards and extend compliance timelines.
- Acetaminophen Substitution Pressure:Manufacturers reformulate away from higher-risk NSAID combinations, compressing margin structures on legacy products.
Strategic Opportunities
- Topical Delivery Innovation:Device-drug combination formats under EU MDR rules create white space for manufacturers with dual jurisdiction compliance capabilities.
- Subscription Replenishment Models:Online stores capture incremental growth through automated recurring purchase systems for chronic pain management users.
- Digestive-Friendly Positioning:Premium ibuprofen formulations that reduce gastric irritation command price differentiation in European pharmacy channels.
Industry Challenges
- Regulatory Divergence Management:Manufacturers face duplicative compliance investments where FDA streamlined monograph systems diverge from EU MDR device-drug combination rules.
- Formulation Talent Scarcity:Specialized expertise in pediatric dosing precision and topical delivery systems concentrates among limited specialist teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over-The-Counter (OTC) Analgesics Market |
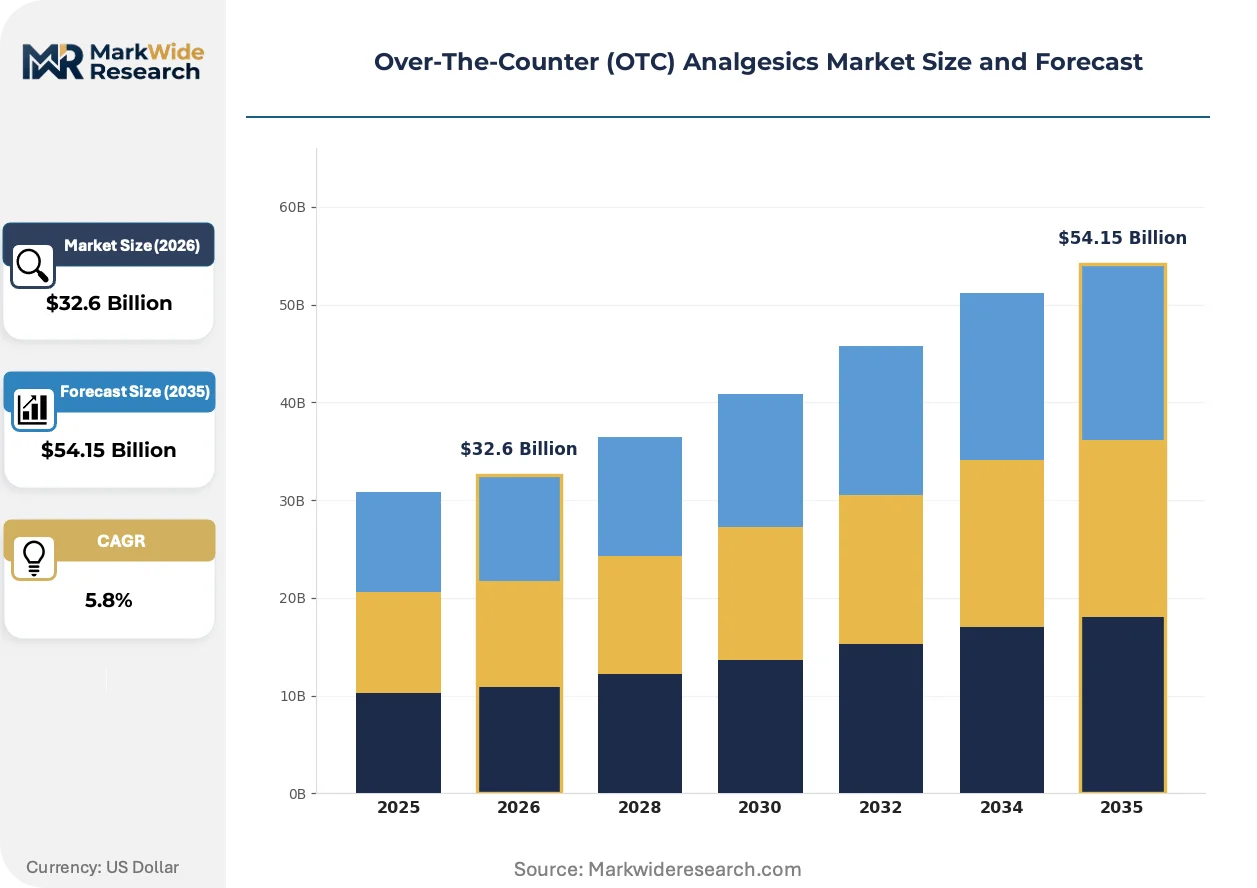
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $54.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetaminophen, Ibuprofen, Aspirin, Naproxen Dosage Form: Tablets, Capsules, Liquid, Gel Distribution Channel: Retail Pharmacies, Online Stores, Supermarkets, Convenience Stores End User: Adults, Children, Seniors, Caregivers |
| Companies Covered | Johnson & Johnson, Bayer AG, Haleon PLC, Reckitt Benckiser Group PLC, Sanofi, Pfizer Inc., GlaxoSmithKline plc, Novartis AG, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over-The-Counter (OTC) Analgesics Market Evolving Landscape
Formulation science and delivery mechanism innovation are actively reshaping how analgesic compounds reach consumers, with regulatory frameworks and purchasing behaviors evolving in parallel.
Solubilized ibuprofen technologies that accelerate absorption are overtaking standard tablet formats in the acute pain management segment. Athletes and shift workers seeking faster onset are adopting these formulations at accelerating rates. This technology is compressing the competitive window for conventional immediate-release products.
REACH compliance requirements for excipient safety are forcing reformulation of topical analgesic bases across European manufacturing operations. Industrial consequence includes accelerated substitution of traditional penetration enhancers with bio-based alternatives. Transdermal gel manufacturers serving German and French markets are responding by requalifying supplier networks.
Caregiver purchasing for pediatric populations is fragmenting across digital channels as subscription services displace single-transaction pharmacy visits. Parents managing recurring fever or teething episodes are migrating to auto-replenishment platforms. This behavioral shift is most visible in United States urban markets where same-day delivery infrastructure has matured.
Over-The-Counter (OTC) Analgesics Market Segmentation
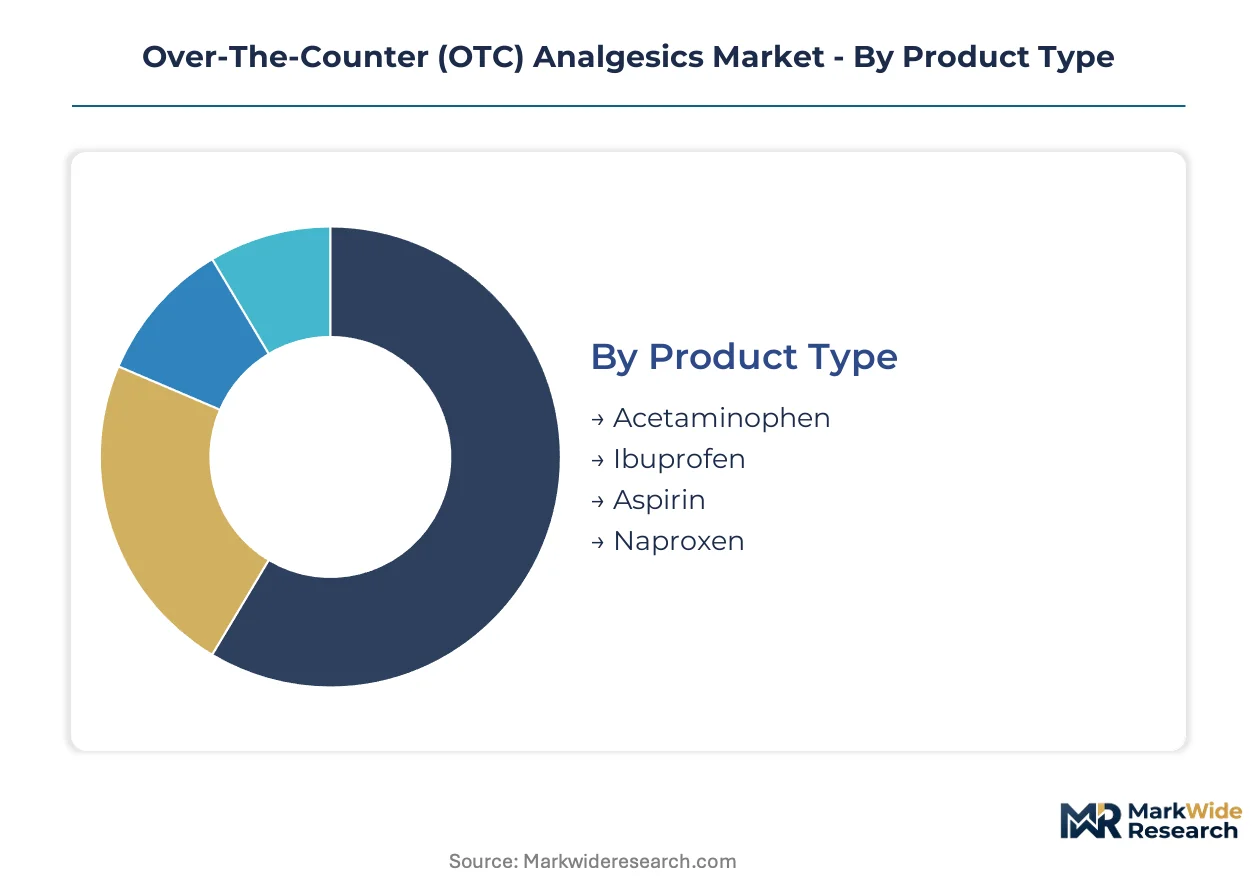
OTC analgesic manufacturers compete across distinct product chemistries, physical formats, and purchasing contexts. Each segmentation dimension carries different margin profiles, regulatory requirements, and competitive intensity that shape portfolio allocation decisions.
Product Type:
Volume concentration clusters in ibuprofen and acetaminophen, while aspirin and naproxen occupy differentiated therapeutic niches with distinct margin economics.
- Ibuprofen:Non-steroidal anti-inflammatory compound formulated at 200-400 mg OTC strengths. Demand concentrates among athletes and manual laborers in the United States and Germany seeking dual pain and inflammation relief. Solubilized rapid-absorption variants are displacing standard tablets in acute pain applications.
- Acetaminophen:Centrally acting analgesic without anti-inflammatory properties, preferred for cardiovascular-sensitive populations. Pediatric liquid formulations and hospital discharge protocols in France and Japan drive volume. Reformulation away from combination products is compressing legacy margins.
- Aspirin:Acetylsalicylic acid with antiplatelet properties at low doses, positioned for cardiovascular prophylaxis alongside pain relief. Bayer's century-old franchise sustains brand loyalty in European pharmacy channels.
- Naproxen:Longer half-life NSAID offering extended duration of action for chronic conditions. Prescription-to-OTC switch momentum under FDA monograph reform is expanding eligible dosage strengths.
Mature deployment sits with ibuprofen standard tablets. Newer deployment is concentrated in solubilized acetaminophen liquids and naproxen extended-release formats.
Dosage Form:
Physical delivery mechanisms determine absorption kinetics, patient compliance, and manufacturing capital requirements across the value chain.
- Tablets:Compressed solid dosage forms dominating unit volume through cost efficiency and stability. Standard immediate-release tablets face margin pressure from faster-absorbing alternatives in United States retail.
- Liquid:Aqueous or suspension formulations enabling precise pediatric and geriatric dosing. Caregiver preference for measurement accuracy is driving fastest expansion in auto-replenishment subscription channels.
- Capsules:Gelatin shells containing powder or liquid fill, offering taste masking and modified release capabilities. Soft-gel liquid fills command premium positioning for rapid onset claims.
- Gel:Topical semisolid formulations delivering localized action with reduced systemic exposure. EU MDR device-drug combination rules are reshaping compliance requirements for transdermal manufacturers in Germany and Italy.
Tablet manufacturing capacity is most mature across Asian contract manufacturers. Gel formulation expertise is concentrating in European specialty houses with REACH-compliant excipient portfolios.
Distribution Channel:
Channel selection determines pricing architecture, promotional intensity, and patient counseling requirements that vary by jurisdiction.
- Retail Pharmacies:Professional counseling environments controlling dominant value share through pharmacist recommendation influence. Southeast Asian pharmacy modernization is expanding shelf space for premium formulations in Thailand and Vietnam.
- Online Stores:Digital platforms capturing recurring purchase automation for chronic pain management. Subscription replenishment models are displacing single-transaction behavior in United States urban markets with same-day delivery infrastructure.
- Supermarkets:Mass merchandisers emphasizing price competition and impulse purchase placement. Limited pharmacist interaction restricts certain switch-status products in regulated jurisdictions.
- Convenience Stores:Extended-hour access points for acute pain episodes with restricted SKU breadth. Travel-size and single-dose packaging dominates this channel.
Pharmacy chains anchor volume in regulated European markets. Online deployment is climbing fastest in North American metropolitan corridors.
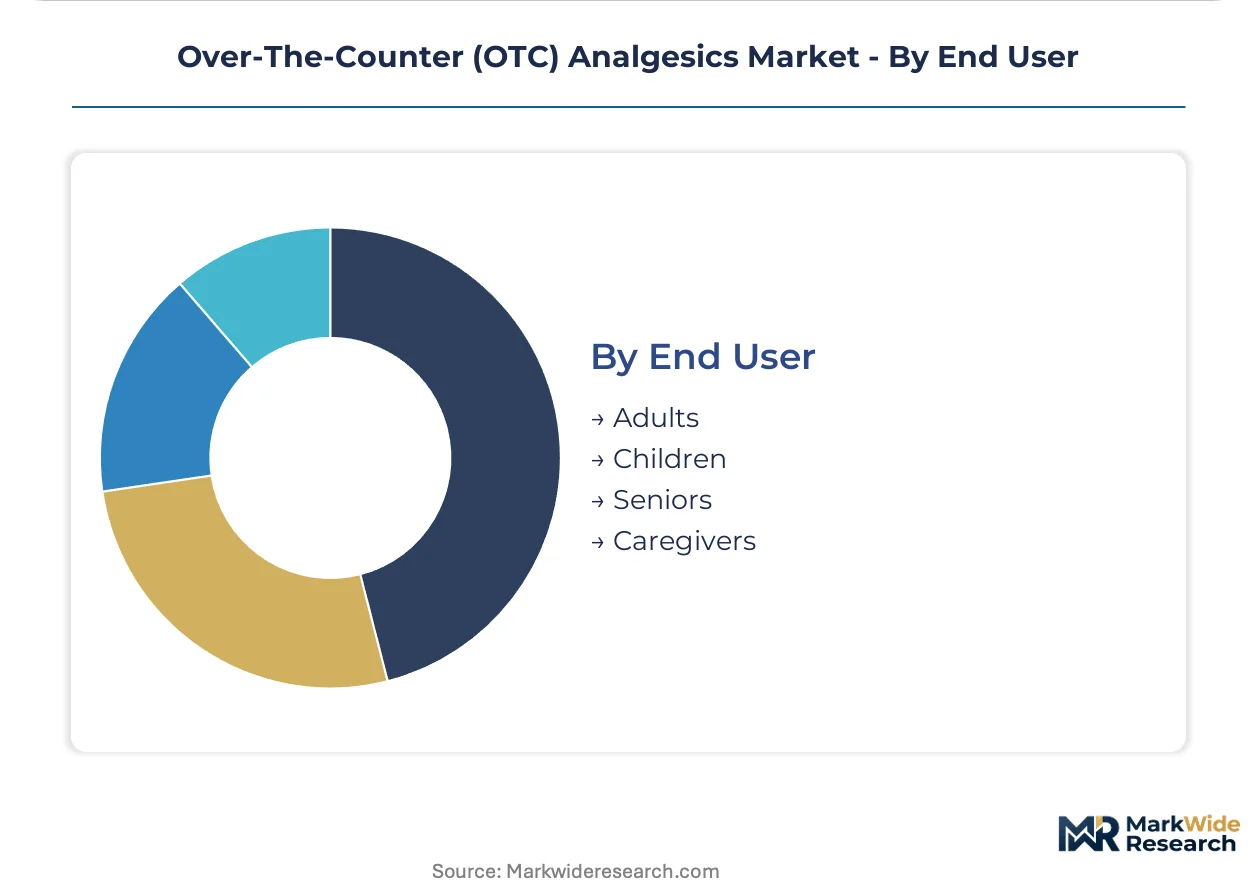
End User:
Demographic targeting shapes formulation safety profiles, dosing precision requirements, and marketing communication strategies.
- Adults:Core user base spanning 18-64 years with self-diagnosed mild-to-moderate pain conditions. Workforce pain management and athletic recovery drive repeat purchase frequency.
- Children:Pediatric populations requiring weight-calibrated dosing and palatable formulations. Caregiver anxiety about precise measurement is accelerating liquid and dissolvable tablet adoption.
- Seniors:Aging populations with polypharmacy considerations and heightened NSAID cardiovascular risk. Home healthcare settings in Japan and Italy are expanding self-medication scope for this cohort.
- Caregivers:Proxy purchasers managing medication decisions for dependent children or elderly relatives. Digital subscription adoption is highest among this segment seeking inventory automation.
Adult self-medication represents mature demand. Caregiver-mediated purchasing is expanding most quickly through digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in aging populations across developed economies where self-medication trends intersect with pharmacy retail modernization. The United States and Germany anchor volume through established OTC distribution infrastructure, while Southeast Asian markets expand through pharmacy network upgrades.
United States
Athletes and shift workers drive solubilized ibuprofen adoption for faster pain relief onset. FDA monograph reform accelerates prescription-to-OTC switches for naproxen and other NSAIDs. Chicago and Philadelphia retail corridors concentrate pharmacy chain competition for premium shelf positioning.
Germany
Manual laborers and aging industrial workers sustain demand for dual-action anti-inflammatory analgesics. REACH compliance mandates force reformulation of topical gel excipients across manufacturing operations. The Rhine-Ruhr industrial belt hosts specialized transdermal formulation houses adapting to EU MDR device-drug combination rules.
Japan
Seniors in home healthcare settings expand self-medication scope for mild chronic pain management. PMDA pharmacovigilance requirements tighten labeling for cardiovascular risk in NSAID products. Osaka and Nagoya pharmacy networks modernize through digital inventory systems supporting caregiver purchasing.
France
Hospital discharge protocols drive acetaminophen volume for post-operative pain management at home. ANSM oversight of pediatric liquid formulations enforces precise dosing calibration standards. The Paris metropolitan corridor concentrates retail pharmacy chains competing on pharmacist consultation services.
Thailand
Middle-class urban consumers adopt Western-format OTC products through modernizing pharmacy retail. The national pharmaceutical regulator aligns labeling standards with ASEAN harmonization initiatives. Bangkok and Chiang Mai host expanding pharmacy franchise networks capturing demand from aging demographic segments.
Over-The-Counter (OTC) Analgesics Market Competitive Landscape
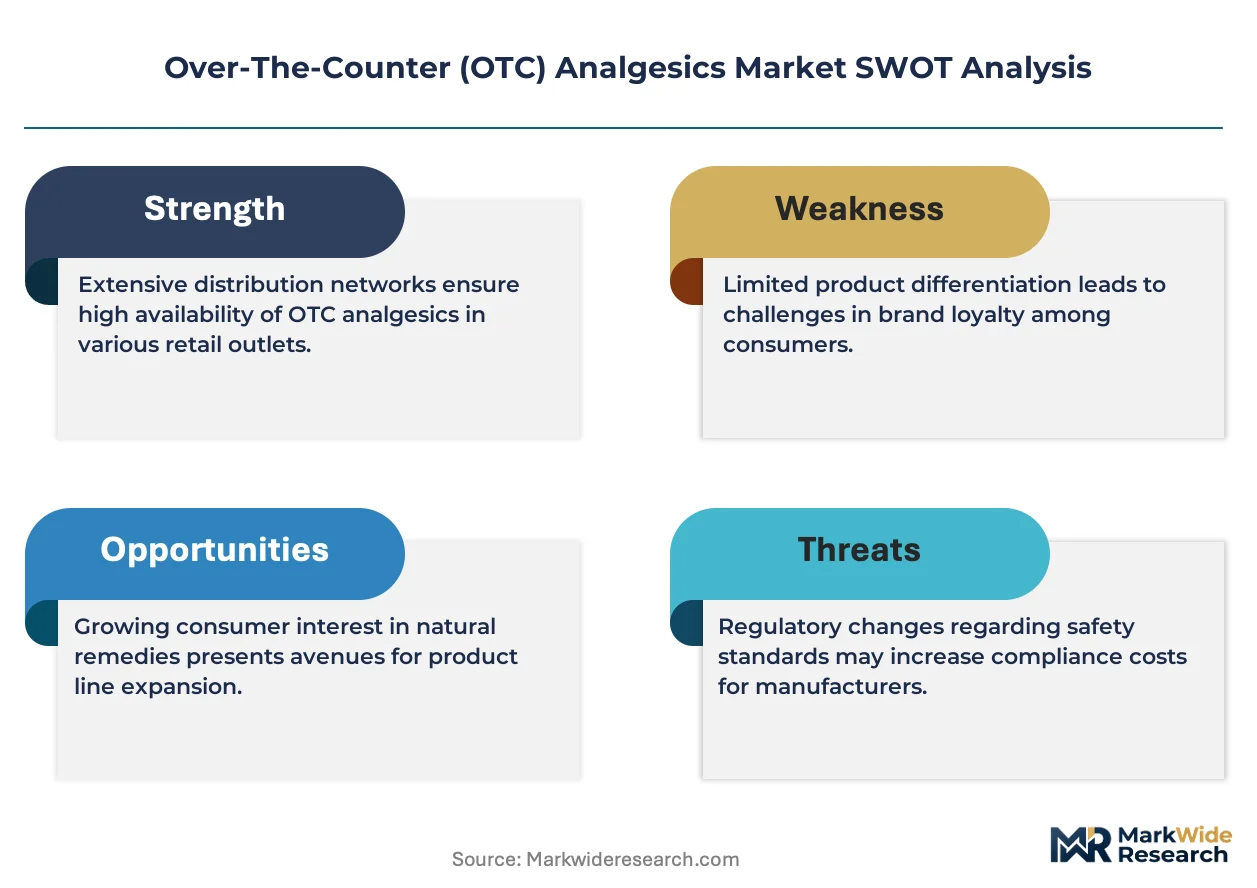
Portfolio diversification dominates the current landscape as manufacturers reformulate away from higher-risk NSAID combinations toward cardiovascular-friendly alternatives. The market structure concentrates around multinational pharmaceutical conglomerates with established consumer health divisions, mid-sized regional specialists, and private-label contract manufacturers. Three archetypes prevail: legacy brand stewards leveraging century-old franchises, science-driven innovators in delivery mechanism technology, and efficiency-focused private-label suppliers. Capacity expansion in pediatric liquid formulations and strategic partnerships for topical delivery expertise represent the dominant competitive vectors reshaping positioning.
Within the legacy brand steward tier, Johnson & Johnson, Bayer AG, and Haleon PLC exemplify divergent strategic anchors. Johnson & Johnson occupies a position centered on pediatric dosing precision and retail pharmacy chain relationships. Bayer AG exemplifies the century-old franchise model through sustained aspirin brand equity and topical extension development. Haleon PLC represents digestive-friendly formulation differentiation commanding premium positioning in regulated European pharmacy channels. These three entities collectively illustrate how brand heritage, therapeutic specialization, and regional regulatory navigation define competitive separation in OTC analgesics.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Bayer AG |
| Haleon PLC |
| Reckitt Benckiser Group PLC |
| Sanofi |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Viatris Inc. |
| Others |
Value Network & Pricing Analysis
Caregiver-mediated subscription purchasers in United States urban corridors anchor pricing power for liquid pediatric formulations, while retail pharmacy chains in Germany and France command premium positioning through pharmacist consultation bundling. This buyer concentration reinforces a three-tier pricing structure across premium digestive-friendly formulations, standard immediate-release tablets, and economy private-label offerings, with cost compression in legacy NSAID combinations intensifying as manufacturers reformulate toward cardiovascular-safe alternatives.
Pricing Analysis
Volume concentrates in standard ibuprofen and acetaminophen tablets where price competition is fiercest, while margins expand fastest in solubilized rapid-absorption formats and pediatric liquid formulations. Pricing stratifies across premium, standard, and economy tiers based on brand heritage certification and delivery mechanism complexity, with premium tiers commanding differentiation through FDA monograph compliance speed and EU MDR device-drug combination capabilities. Price erosion runs through standard tablet categories as Asian contract manufacturers expand capacity and private-label substitution accelerates. Caregiver purchasers through subscription channels exhibit lowest price sensitivity due to convenience premium, while supermarket impulse buyers drive hardest bargain on single-unit transactions.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled batches concentrate compliance burden on manufacturers with direct-to-pharmacy distribution, particularly for temperature-sensitive liquid formulations requiring cold-chain documentation. Active pharmaceutical ingredient production draws from manufacturing clusters in India and China, with ibuprofen and acetaminophen intermediates resting on para-aminophenol and propionic acid derivative supply streams. Single-source vulnerability concentrates in specialized rapid-absorption excipients sourced from limited European specialty chemical houses. Distribution runs through pharmacy wholesale networks in regulated markets, while direct-to-consumer platforms bypass traditional tiered markups in North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into API manufacturing and captive control over pediatric formulation capacity represent the dominant vertical-integration race, as regulatory divergence between FDA and EU MDR compliance multiplies qualification costs for outsourced production.
For Market Incumbents: Lock in pediatric liquid formulation capacity through dedicated manufacturing investments or exclusive tolling agreements, as caregiver subscription demand outpaces supply. Secure dual-jurisdiction compliance capabilities spanning FDA streamlined monograph systems and EU MDR device-drug rules before regulatory divergence widens qualification gaps. Defend margin position by anchoring retail pharmacy shelf space through pharmacist education programs on cardiovascular safety differentiation. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting caregiver segments in United States urban markets with same-day delivery infrastructure, bypassing entrenched pharmacy chain gatekeepers. Target white space in topical gel formulations serving German and French industrial corridors, where REACH-compliant excipient sourcing creates barrier to rapid imitation. Pursue partnership routes with Asian API manufacturers for cost-competitive ibuprofen entry, then differentiate through rapid-absorption technology licensing. For Investors and Strategic Acquirers: The window for entry favors specialized topical delivery houses with EU MDR technical file capabilities and established REACH-compliant supplier networks. Long-term viability hinges on consolidation of fragmented pediatric formulation expertise, as talent scarcity in precise dosing calibration concentrates among limited specialist teams. Monitor FDA monograph reform acceleration and EMA cardiovascular labeling mandate implementation as inflection indicators for prescription-to-OTC switch momentum and subsequent margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Capacity Expansion | Captures fastest-expanding margin pool as caregiver subscription demand concentrates in liquid and dissolvable formats. |
| Dual-Jurisdiction Compliance Investment | Enables seamless operation across FDA monograph and EU MDR rules without duplicative qualification costs. |
| Rapid-Absorption Technology Licensing | Compresses competitive window for standard tablets among athletes and shift workers seeking faster onset. |
| Subscription Platform Partnership | Displaces single-transaction pharmacy visits through auto-replenishment automation in United States urban markets. |
| REACH-Compliant Excipient Requalification | Secures continued European market access as ECHA mandates force substitution of traditional penetration enhancers. |
Research Methodology
Multi-period observation of FDA monograph reform progression, EMA pharmacovigilance mandate implementation, and prescription-to-OTC switch volumes anchored the trend analysis, supplemented by interviews with regulatory affairs leads at multinational consumer health divisions, pharmacy chain category managers, pediatric formulation specialists, API procurement directors, and caregiver panel participants. Secondary validation drew from FDA Orange Book filings, EMA EPAR assessments, WHO essential medicines list revisions, and pharmacy retail audit data spanning Nielsen and IQVIA channels. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers.
The input-output matrix framed demand modeling across product chemistry, dosage form, distribution channel, and end-user demographic dimensions throughout the forecast period. CAGRs derived from regression analysis of historical switch volumes, aging population projections, and pharmacy modernization indices. Industry-specific forecast inputs incorporated PMDA pharmacovigilance timeline assumptions and ASEAN regulatory harmonization progress.
Regulatory approval delays, API supply disruption events, and caregiver channel migration acceleration are the dominant revision risks that could alter trajectory. Practitioners should monitor FDA monograph reform implementation pace and EMA cardiovascular labeling enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
Urinary Retention Drugs Market