
 Spain Over-The-Counter (OTC) Drugs Market | 2026-2036
Spain Over-The-Counter (OTC) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Over-The-Counter (OTC) Drugs Market Analytics
Market Context
Retail buyer concentration in Spain is consolidating as pharmacy cooperatives and supermarket chains expand their OTC purchasing alliances. Sanofi SA leverages its analgesics portfolio to sustain shelf dominance across major Spanish drugstore networks. Bayer competes through vitamin and supplement lines that anchor its position in supermarket health aisles.
Technical Definition and Segments
Over-the-counter drugs are non-prescription pharmaceutical formulations containing active ingredients below regulated thresholds, manufactured through validated processes meeting stability and bioavailability specifications for consumer-directed symptom relief. Pain relievers generate the largest revenue pool among product types, while vitamins and supplements represent the fastest-growing segment as Spanish consumers shift toward preventive health. E-commerce platforms now capture expanding volume share within distribution channels, challenging traditional drugstore and hypermarket routes.
Regulatory Outlook
AEMPS governs prescription-to-OTC switches and labeling requirements, while the European Medicines Agency provides centralized guidance on active substance classifications that Spanish regulators implement. Bilingual packaging mandates and advertising restrictions under Spanish consumer protection law shape product development costs and market access timelines. Stakeholders must monitor AEMPS reclassification proceedings and pharmacy channel regulations to anticipate portfolio eligibility shifts.
Market Dynamics
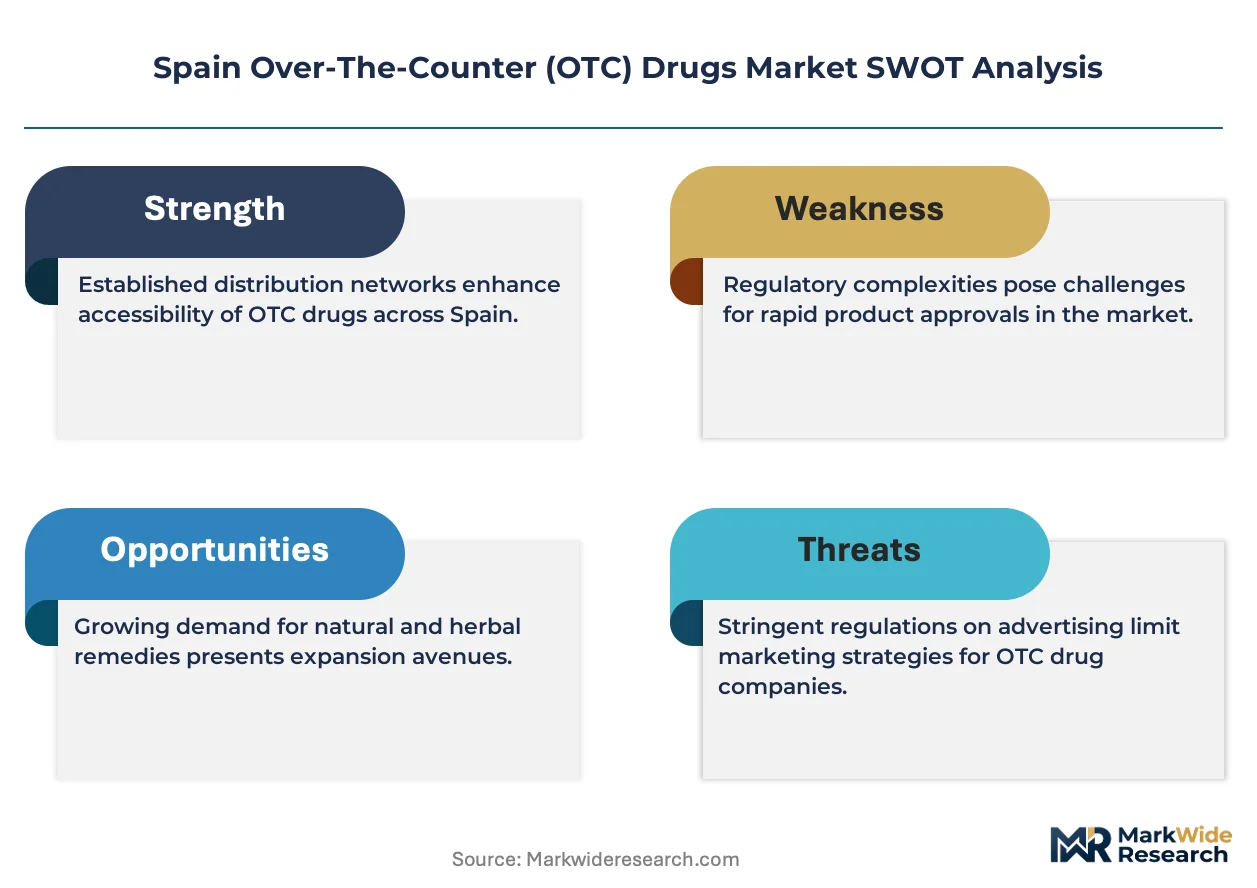
Pharmacy cooperative consolidation across Spain is concentrating procurement leverage among fewer retail buyers, forcing manufacturers to restructure distribution terms and shelf-access negotiations.
Growth Catalysts
- AEMPS Reclassification Pathway:Spain's national pharmaceutical regulator maintains streamlined procedures for prescription-to-OTC switches, expanding eligible product portfolios for domestic manufacturers.
- Urban Pharmacy Density:Madrid and Barcelona sustain the highest pharmacy-per-capita ratios in Southern Europe, creating concentrated demand nodes for self-medication products.
- Preventive Health Pivot:Spanish consumers allocate higher spending shares toward vitamin and supplement categories, pulling formulation investment away from acute symptom relief.
Market Restraints
- API Import Dependency:Active pharmaceutical ingredient sourcing concentrates among Asian suppliers, exposing Spanish formulators to shipping cost volatility and customs clearance delays.
- Bilingual Packaging Mandates:Spanish consumer protection law requires Castilian and co-official regional language labeling, inflating production runs and inventory complexity for national distribution.
- Supermarket Channel Restrictions:AEMPS limits certain analgesic categories to pharmacy-only sales, capping volume potential in hypermarket and supermarket retail formats.
Strategic Opportunities
- Andalusian and Galician Expansion:Pharmacy penetration lags below national averages in southern and northwestern Spanish regions, offering whitespace for cooperative network expansion.
- E-Commerce Platform Integration:Dedicated pharmaceutical delivery services and marketplace health sections unlock direct-to-consumer channels previously restricted by physical retail dominance.
- EU Green Deal Alignment:Sustainable packaging mandates and carbon footprint disclosure requirements favor early-adopting Spanish manufacturers in cross-border European distribution.
Industry Challenges
- Formulation Specialist Scarcity:Spanish universities produce insufficient graduates in pharmaceutical technology and galenic formulation, constraining R&D pipeline velocity for domestic OTC developers.
- Legacy ERP Integration:Pharmacy cooperatives operate heterogeneous inventory management systems, complicating real-time sales data exchange and demand forecasting for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Over-The-Counter (OTC) Drugs Market |
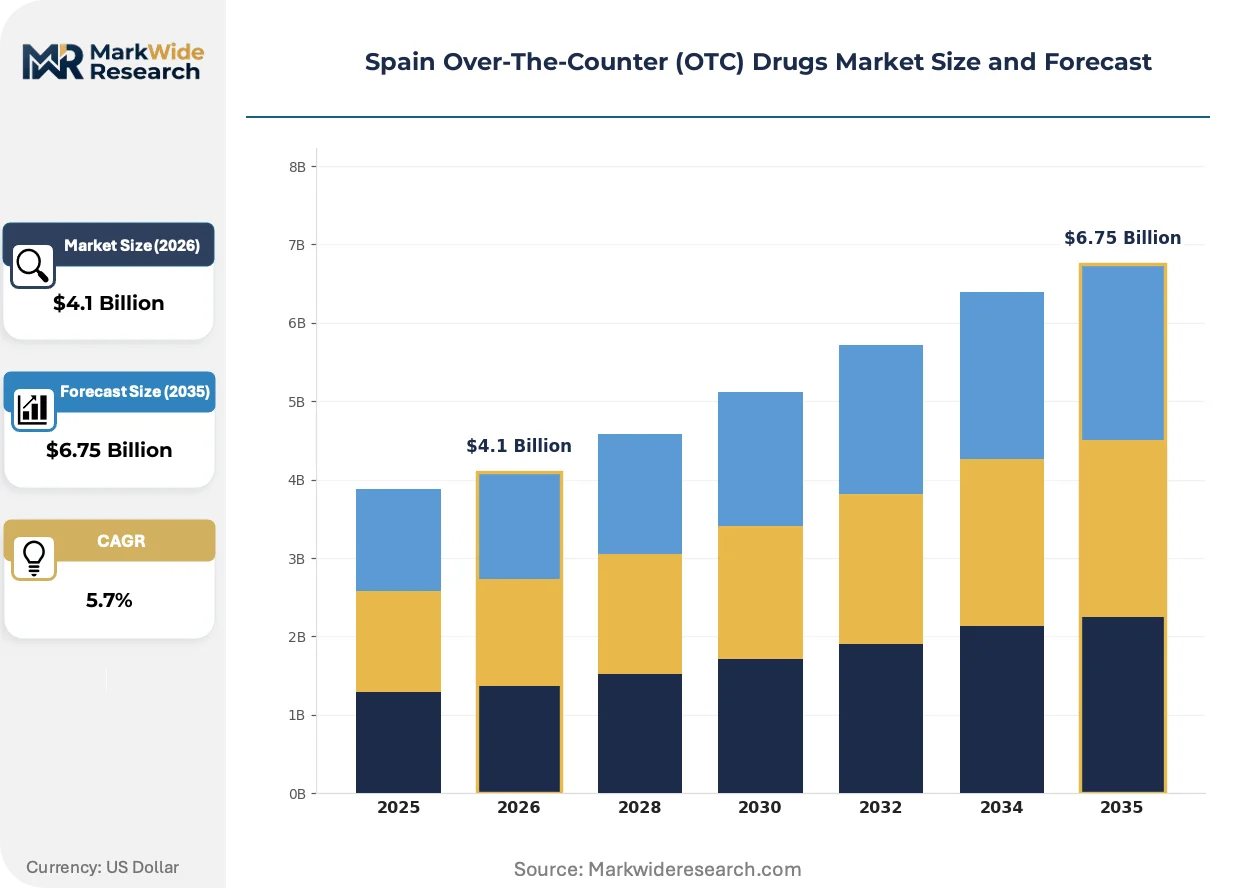
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.75 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relievers, Cold & Allergy Medications, Vitamins & Supplements, Digestive Aids Customer Type: Retail Consumers, Pharmacies, Supermarkets, E-commerce Platforms Packaging Type: Blister Packs, Bottles, Sachets, Tablets Distribution Channel: Online Sales, Drugstores, Convenience Stores, Hypermarkets |
| Companies Covered | Sanofi SA, GlaxoSmithKline PLC, Bayer, Reckitt Benckiser Group PLC, Pfizer Inc., Johnson & Johnson, Cinfa, Almirall, Faes Farma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Over-The-Counter (OTC) Drugs Market Evolving Landscape
Digital health integration and sustainability mandates are restructuring how Spanish consumers discover, evaluate, and purchase self-medication products outside traditional pharmacy environments.
Smart packaging embedded with NFC tags and QR-linked dosing instructions is converging with pharmacy mobile applications, enabling real-time adherence tracking. Regional pharmacy chains in Catalonia and the Basque Country pilot these systems for chronic condition management. This technology convergence is compressing the information gap between manufacturer and end-user, bypassing traditional pharmacist consultation intermediation.
AEMPS advertising restrictions under Spanish consumer protection law now extend to social media influencer partnerships and algorithmic targeting. The industrial consequence is a wholesale shift toward owned-content strategies and pharmacy-sponsored health education platforms. Analgesic and cough-cold segments face the strictest creative constraints, driving marketing investment toward vitamin and supplement categories with lighter regulatory scrutiny.
Spanish households now initiate product searches through voice-activated assistants and pharmacy aggregator apps before physical store visits. Supermarket health aisles in Madrid and Barcelona respond with expanded self-service diagnostic displays and automated shelf-talkers. This behavioral rotation is most pronounced among urban millennials, who treat pharmacy visits as fulfillment endpoints rather than consultation occasions.
Spain Over-The-Counter (OTC) Drugs Market Segmentation
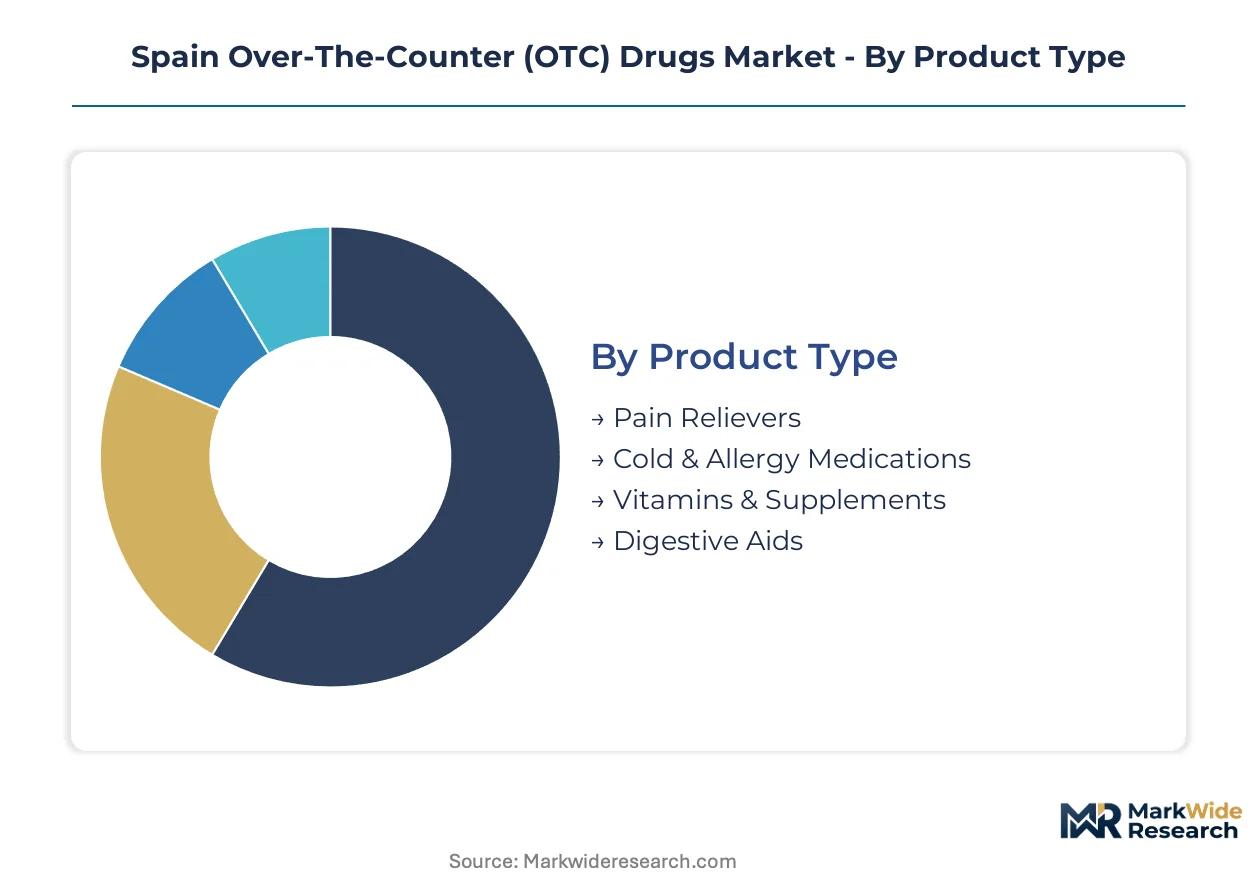
Segmentation in the Spanish OTC market reveals how AEMPS regulations and retail consolidation reshape where capital deploys. Manufacturers must align formulation investments with channel-specific compliance burdens and regional pharmacy density.
Product Type:
Pain relievers demand the heaviest upfront investment due to AEMPS pharmacy-only restrictions and stability testing requirements. Vitamins and supplements carry lighter regulatory entry costs but compete on formulation differentiation.
- Pain Relievers:Analgesic formulations containing ibuprofen, paracetamol, or acetylsalicylic acid require bioequivalence studies and shelf-life validation under AEMPS guidelines. Madrid and Barcelona pharmacies generate concentrated demand, though AEMPS limits supermarket channel access for higher-dose variants.
- Vitamins & Supplements:Preventive health formulations span multivitamins, minerals, and botanical extracts with lighter AEMPS scrutiny than pharmaceutical categories. Spanish consumers in urban centers allocate rising spending shares here, pulling R&D investment from acute symptom relief.
- Cold & Allergy Medications:Decongestant and antihistamine combinations face strict advertising restrictions under Spanish consumer protection law.
- Digestive Aids:Probiotic and antacid formulations target pharmacy cooperative procurement networks with seasonal demand spikes.
Most installed capacity flows through pain relievers. Expansion is steepest in vitamins and supplements.
Customer Type:
Channel concentration determines working capital intensity, with pharmacy cooperatives demanding extended payment terms and supermarket chains requiring promotional fund commitments.
- Retail Consumers:Individual purchasers driving self-medication decisions, concentrated in Madrid and Barcelona urban corridors where pharmacy density and health awareness run highest.
- Pharmacies:Cooperative networks and independent drugstores remain the dominant OTC channel under AEMPS regulations, capturing prescription-to-OTC switch volumes.
- Supermarkets:Hypermarket and supermarket health aisles face AEMPS category restrictions, limiting analgesic access while expanding vitamin and supplement placement.
- E-commerce Platforms:Dedicated pharmaceutical delivery services and marketplace health sections unlock direct-to-consumer channels, bypassing traditional pharmacy intermediation.
Pharmacy networks dominate current volume. E-commerce platforms are gaining share fastest.
Packaging Type:
Unit economics and AEMPS labeling mandates drive format selection, with bilingual packaging requirements inflating production complexity for national distribution.
- Blister Packs:Unit-dose aluminum-plastic combinations dominate analgesic and cold medication formats, enabling precise dosing and tamper evidence.
- Bottles:HDPE and glass containers serve liquid formulations and bulk tablet counts, common in vitamin and supplement categories with longer consumption cycles.
- Sachets:Single-use powder and granule formats target travel and on-the-go digestive aid consumption.
- Tablets:Direct compression and film-coated solid oral dosages remain the standard for high-volume pain reliever production.
Blister packs handle the largest production volumes. Sachets are climbing the fastest on convenience positioning.
Distribution Channel:
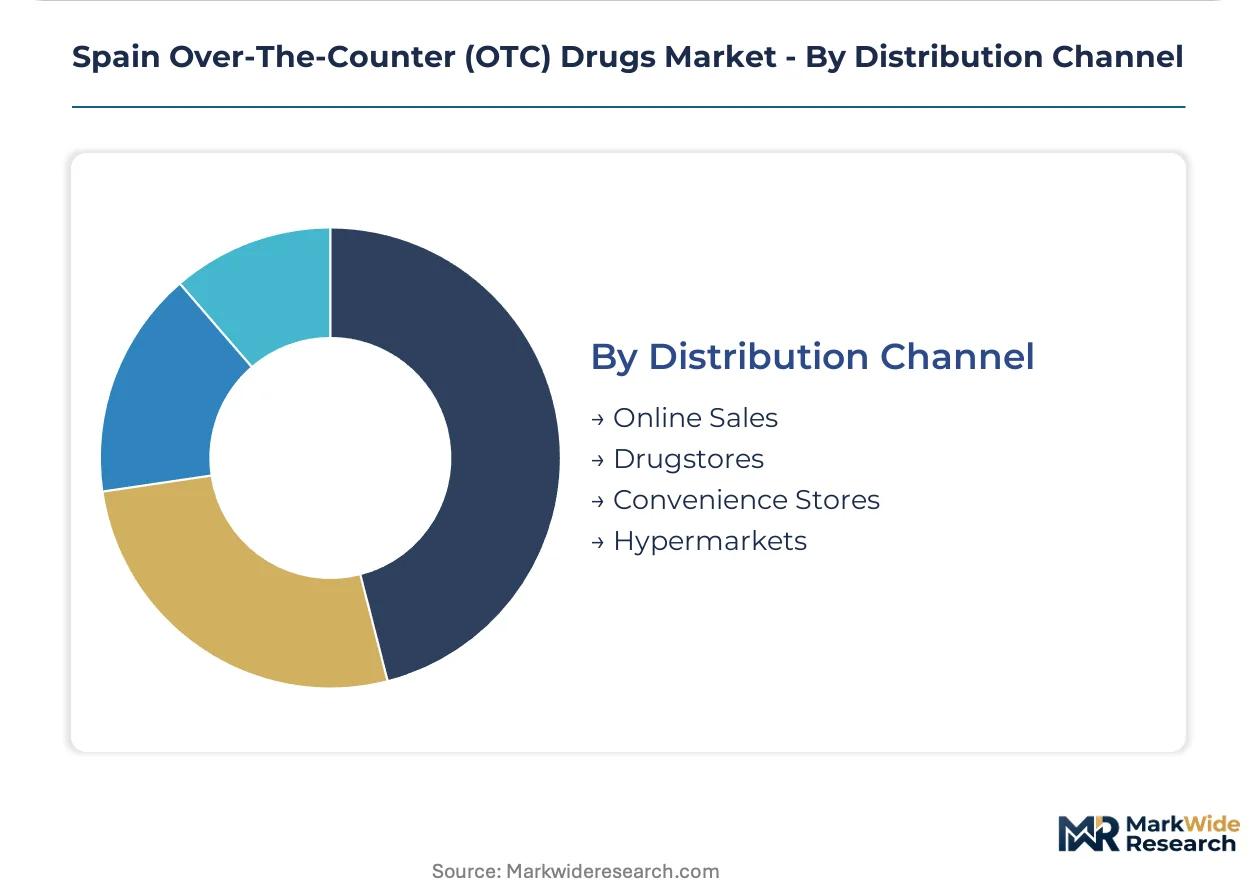
Channel access determines margin structure, with online platforms compressing intermediation costs while drugstores retain premium positioning through pharmacist consultation.
- Drugstores:Physical pharmacy locations, including cooperative chains and independent operators, maintain AEMPS-mandated exclusivity for certain analgesic categories.
- Hypermarkets:Large-format retail health aisles in Madrid and Barcelona expand self-service diagnostic displays, constrained by AEMPS product restrictions.
- Online Sales:Dedicated pharmaceutical marketplaces and aggregator apps capture millennial demand, with voice-activated search initiating purchase journeys.
- Convenience Stores:Limited urban footprint for emergency and travel-size OTC purchases, restricted to non-pharmacy-only categories.
Drugstores anchor current distribution. Online sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy density and AEMPS regulatory harmonization anchor Spain's OTC distribution geography. Regional pharmacy cooperatives concentrate procurement power unevenly across autonomous communities.
Madrid
Spain's capital sustains the highest pharmacy-per-capita ratio nationally, driving concentrated demand for self-medication products. AEMPS maintains streamlined prescription-to-OTC switch procedures that expand eligible portfolios for Madrid-based formulators. The metropolitan corridor hosts headquarters operations for major pharmacy cooperative networks negotiating national distribution terms.
Catalonia
Barcelona anchors pharmaceutical manufacturing clusters with specialized galenic formulation capabilities serving domestic and export markets. Bilingual packaging mandates under Spanish consumer protection law require Castilian and Catalan labeling, inflating production complexity. Regional pharmacy chains pilot NFC-enabled smart packaging for chronic condition management applications.
Basque Country
Industrial pharmaceutical production concentrates around Bilbao and San Sebastián with legacy formulation expertise. AEMPS advertising restrictions extend to social media influencer partnerships, forcing owned-content strategies. The region's cooperative pharmacy networks operate heterogeneous ERP systems complicating supplier demand forecasting.
Andalusia
Pharmacy penetration lags below national averages across Seville, Málaga, and Granada corridors, presenting whitespace for cooperative network expansion. AEMPS limits certain analgesic categories to pharmacy-only sales, constraining supermarket channel development. Regional health authorities promote preventive health initiatives accelerating vitamin and supplement category growth.
Valencia
The Levante corridor balances industrial formulation capacity with expanding retail pharmacy networks. E-commerce platform integration unlocks direct-to-consumer channels bypassing traditional pharmacy intermediation. Valencia-based logistics hubs serve pharmaceutical delivery services capturing millennial demand from urban centers.
Spain Over-The-Counter (OTC) Drugs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's OTC landscape. The market structure tilts toward consolidation as pharmacy cooperative procurement centralization favors suppliers with national scale. Three archetypes dominate: multinational pharmaceutical conglomerates with broad analgesic portfolios, European consumer health specialists with vitamin and supplement concentration, and domestic Spanish formulators with regional pharmacy network relationships. Competitive moves center on AEMPS reclassification pathway navigation and e-commerce platform integration partnerships.
Among multinational conglomerates, Sanofi SA and Bayer exemplify scale-driven archetypes with shelf dominance across major Spanish drugstore networks. Johnson & Johnson occupies a position bridging pharmaceutical and consumer health positioning. Domestic specialists including Almirall and Faes Farma sit within the regional formulator tier, leveraging AEMPS regulatory familiarity and cooperative pharmacy relationships. Cinfa represents the mid-cap Spanish player archetype with concentrated Iberian market presence.
| Leading Market Players |
|---|
| Sanofi SA |
| GlaxoSmithKline PLC |
| Bayer |
| Reckitt Benckiser Group PLC |
| Pfizer Inc. |
| Johnson & Johnson |
| Cinfa |
| Almirall |
| Faes Farma |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging mandates gate qualified supply and premium-tier pricing access for Spanish OTC manufacturers, bifurcating the market between certified sustainable suppliers commanding shelf placement premiums and conventional producers facing margin compression from compliance retrofit costs.
Pricing Analysis
Pharmacy consultation bundling versus unbundled self-service retail splits pricing architectures across Spanish OTC channels. Three-tier pricing structure across premium, standard, and economy levels reflects AEMPS regulatory tier and pharmacist involvement depth. Price differentiation rests on bilingual packaging complexity and regional co-official language requirements. Cost compression in economy-tier analgesics is intensifying because supermarket chains demand promotional fund commitments. Retail consumers in Madrid and Barcelona corridors show lowest price sensitivity; rural pharmacy cooperatives exhibit highest.
Supply Chain Analysis
Freight cost volatility from Asian API suppliers compounds margin pressure for Spanish formulators dependent on imported active ingredients. Active pharmaceutical ingredient sourcing concentrates in India and China, with secondary supply from Italy and Germany. Spanish manufacturers draw from ibuprofen, paracetamol, and excipient streams vulnerable to customs clearance delays. Single-source vulnerability runs through concentrated Asian chemical intermediate suppliers. Distribution runs through pharmacy cooperative networks with extended payment terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's OTC market reads as a late-cycle quality story where AEMPS reclassification pathways and preventive health spending shifts favor premium vitamin and supplement specifications over commoditized acute symptom relief.
For Market Incumbents: Anchor shelf dominance through AEMPS regulatory navigation capabilities and pharmacy cooperative procurement centralization. Defend against e-commerce platform disintermediation by embedding NFC-enabled adherence tracking into packaging. Prioritize backward integration into sustainable packaging supply to preempt EU Green Deal compliance costs. For New Entrants and Emerging Players: Launch via dedicated pharmaceutical delivery services targeting millennial voice-search initiation patterns. Whitespace concentrates in Andalusian and Galician pharmacy network expansion where penetration lags national averages. Galenic formulation specialization for probiotic and botanical categories offers lowest regulatory entry barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap Spanish formulators with concentrated Iberian presence because pharmacy cooperative consolidation demands suppliers with national scale and AEMPS relationship depth. Five-to-ten-year viability hinges on e-commerce platform integration completion. Monitor AEMPS reclassification proceeding velocity as inflection signal for portfolio eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AEMPS Reclassification Navigation | Prescription-to-OTC switch expertise unlocks pharmacy-exclusive volume pools. |
| E-Commerce Platform Integration | Aggregator app partnerships capture millennial voice-search purchase initiation. |
| Sustainable Packaging Transition | EU Green Deal alignment secures cross-border European distribution access. |
| Galenic Formulation Investment | Probiotic and botanical specialization addresses preventive health demand pivot. |
| Pharmacy Cooperative Network Expansion | Andalusian and Galician whitespace builds procurement leverage against retail concentration. |
Research Methodology
Direct dialogue with pharmacy cooperative procurement directors, AEMPS regulatory affairs specialists, galenic formulation R&D leads, and supermarket chain category buyers grounds qualitative insights validated against AEMPS filing databases, Spanish consumer protection law regulatory texts, pharmacy sales audit data, and EU pharmaceutical trade statistics. Bottom-up demand modeling triangulates with top-down market sizing across product type, customer channel, packaging format, and autonomous community regulatory clusters.
Bottom-up volume builds aggregate from pharmacy cooperative shipment data and e-commerce platform transaction records; top-down validation cross-references against AEMPS authorization registries and Spanish pharmaceutical industry association aggregate disclosures. Segmentation dimensions span pain reliever, vitamin and supplement, cold and allergy, and digestive aid categories crossed with drugstore, hypermarket, online, and convenience store channels. CAGRs derive from trend extrapolation of AEMPS reclassification velocity and preventive health spending elasticity. Forecast inputs incorporate API import cost trajectories and bilingual packaging mandate compliance cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under AEMPS regulatory delay scenarios or API supply chain disruption events. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market