
 Global Immuno Oncology Drugs Market | 2026-2036
Global Immuno Oncology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immuno Oncology Drugs Market Intelligence
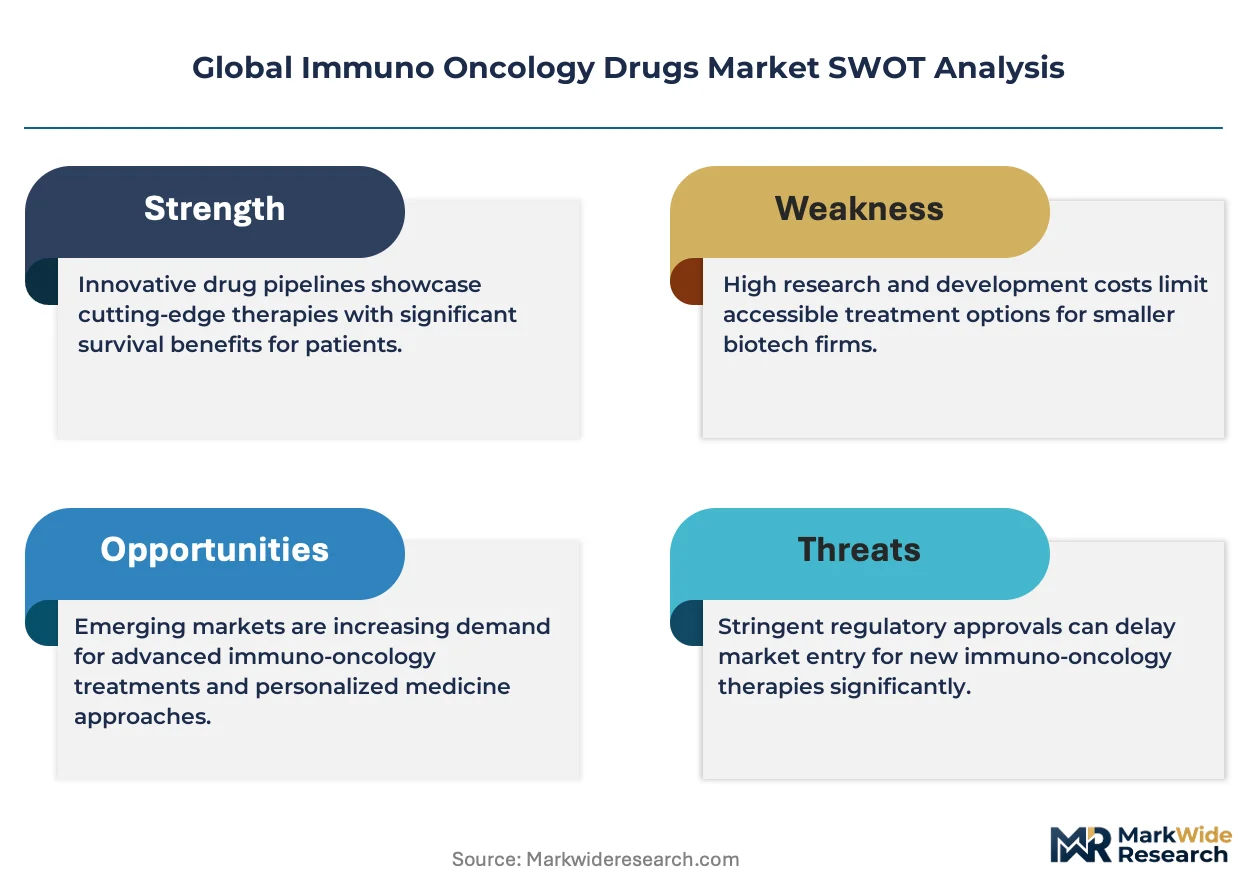
The proliferation of risk-sharing agreements between payers and manufacturers is rewriting the competitive rules for market access. Bristol Myers Squibb Company leverages its extensive clinical trial data to secure favorable terms for its checkpoint inhibitors. F. Hoffmann-La Roche Ltd. differentiates through its companion diagnostics strategy, linking drug efficacy to specific patient biomarkers. AstraZeneca plc sustains its position with a deep pipeline of combination therapies.
Immuno-oncology drugs are a class of biotherapeutics designed to harness a patient's own immune system to recognize and eradicate cancer cells. These therapies function by targeting specific molecular pathways, such as the PD-1/PD-L1 axis, to overcome tumor-induced immunosuppression. Checkpoint inhibitors, a type of monoclonal antibody, constitute the dominant product category due to their broad efficacy. Applications in solid tumors represent the largest and most established therapy area, driving volume.
Market access is governed by stringent regulatory reviews from agencies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These bodies mandate rigorous clinical evidence for safety and efficacy, setting the bar for product approval. Success for developers will hinge on navigating complex and divergent global reimbursement policies to ensure patient access.
Market Dynamics
The central dynamic in the immuno-oncology drug market is the friction between accelerated regulatory pathways and stringent payer reimbursement hurdles. This tension forces developers to generate extensive real-world evidence post-approval to justify high costs and secure market access.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's accelerated approval program, mirrored by similar initiatives globally, allows for earlier market entry based on surrogate endpoints.
- Advanced Biomarker Discovery:Progress in genomics and proteomics is improving the identification of patient-specific biomarkers, enhancing the efficacy of targeted immunotherapies.
- Regulatory Reforms in China:China's NMPA has streamlined its drug approval process and expanded reimbursement lists, unlocking significant demand from a large patient population.
Market Restraints
- Extreme Treatment Costs:The high price of immuno-oncology drugs creates significant affordability barriers for patients and strains healthcare system budgets, leading to access restrictions.
- Severe Immune-Related Adverse Events:Therapies like CAR-T can induce life-threatening side effects, such as Cytokine Release Syndrome (CRS), requiring specialized management and limiting their use.
- Divergent Reimbursement Policies:Navigating disparate and complex reimbursement requirements from US payers, European HTA bodies, and other national authorities creates significant delays and uncertainty.
Strategic Opportunities
- Personalized Neoantigen Vaccines:Developing therapies that target patient-specific tumor neoantigens offers a path toward truly individualized cancer treatment with high specificity.
- Novel Combination Therapies:Integrating immuno-oncology agents with other modalities like antibody-drug conjugates (ADCs) or radiotherapy can overcome resistance and improve response rates.
- Expansion in Latin America:Underpenetrated markets like Brazil present growth avenues as regulatory bodies such as ANVISA modernize their approval and access frameworks for complex biologics.
Industry Challenges
- Cell Therapy Manufacturing Scalability:The complex, patient-specific nature of autologous cell therapies creates major logistical and cost challenges for consistent, large-scale manufacturing and delivery.
- Intellectual Property Litigation:The crowded patent landscape around foundational targets like PD-1 and CTLA-4 results in frequent and costly legal disputes over intellectual property rights.
- Specialized Talent Scarcity:A shortage of skilled personnel in areas like cell therapy process development, bioinformatics, and regulatory science constrains research and production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immuno Oncology Drugs Market |
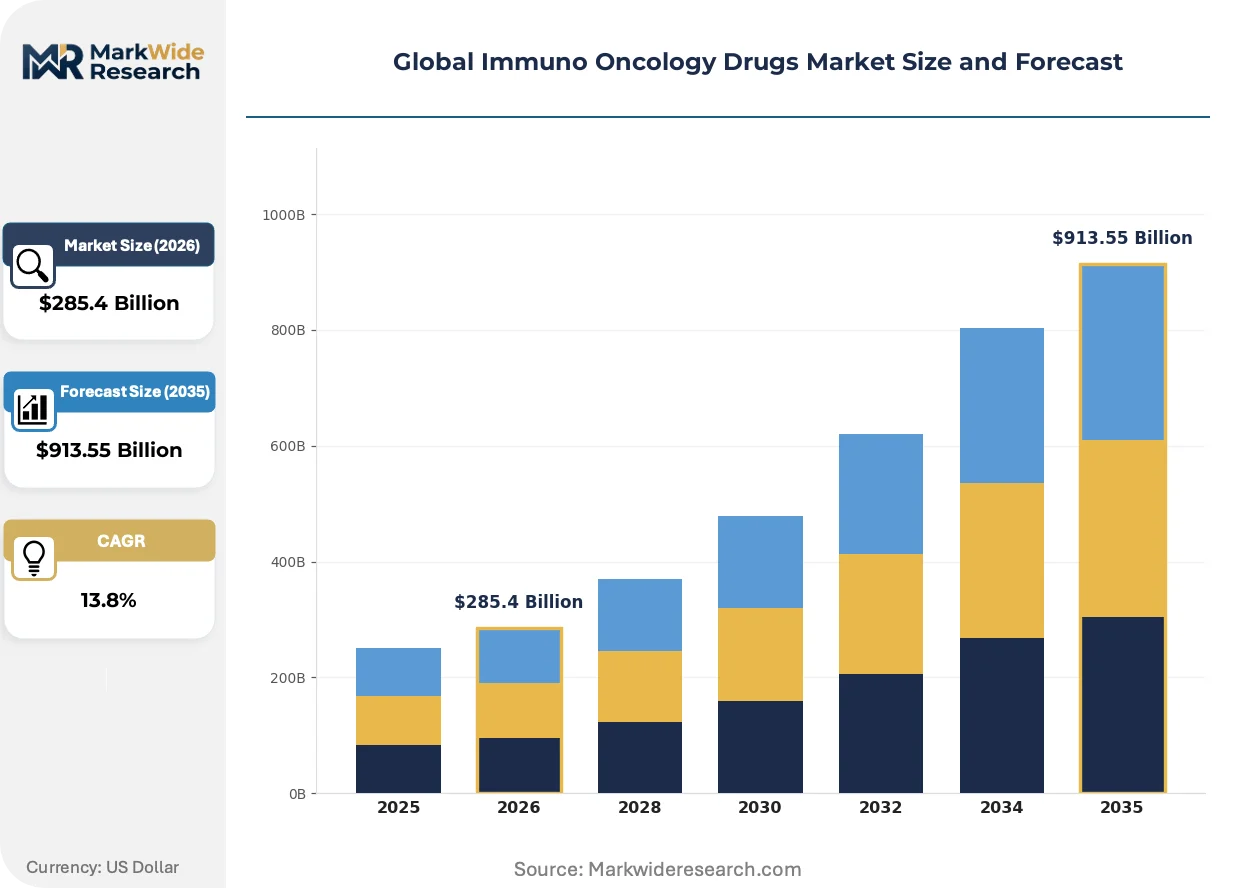
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $913.55 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Checkpoint Inhibitors, Cytokines, Oncolytic Virus Therapy Therapy Area: Solid Tumors, Hematological Malignancies, Cancer Immunotherapy, Neoantigen Targeting Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Research Institutions, Specialty Clinics, Independent Laboratories |
| Companies Covered | Merck & Co., Inc., Bristol Myers Squibb Company, F. Hoffmann-La Roche Ltd., AstraZeneca plc, Novartis AG, Pfizer Inc., AbbVie Inc., Amgen Inc., GSK Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immuno Oncology Drugs Market Strategic Shifts & Innovations
Innovation in immuno-oncology is moving beyond monoclonal antibodies toward multi-modal treatment regimens. The field is defined by a push for greater personalization, combining therapeutics with advanced diagnostics and novel delivery platforms to overcome resistance and improve patient outcomes.
Cell therapies like Chimeric Antigen Receptor T-cell (CAR-T) technology function by genetically engineering a patient's T-cells to target specific cancer antigens. Clinical adoption is accelerating in hematologic cancers, with research expanding into solid tumors. The therapeutic paradigm is migrating from broad immune system activation to highly targeted, living drugs designed for individual cancer profiles.
The European Medicines Agency's PRIME (PRIority MEdicines) scheme provides early and enhanced support to developers of promising new medicines. This regulatory framework accelerates the assessment of therapies that target an unmet medical need, streamlining the path to authorization. Developers of advanced cell and gene therapies for rare oncological indications are most impacted, gaining earlier scientific advice from the EMA.
Payers are implementing value-based contracts for expensive immuno-oncology treatments, linking payment to clinical outcomes. This shift disrupts traditional fee-for-service models, requiring manufacturers to provide robust evidence of long-term efficacy and cost-effectiveness. The practice is most prevalent in single-payer healthcare systems in Europe, such as the UK's National Health Service, influencing global pricing strategies.
Global Immuno Oncology Drugs Market Segmentation
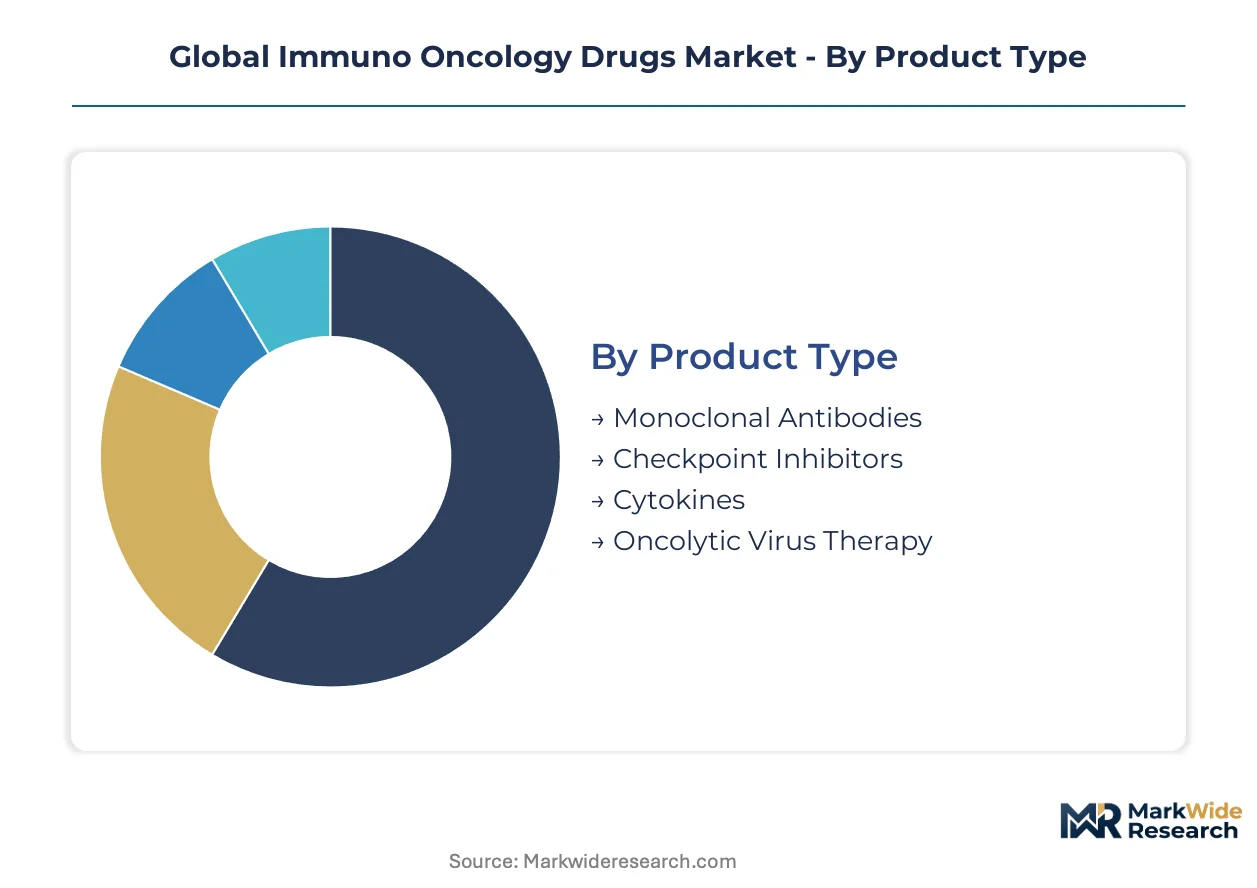
The immuno-oncology drugs market segments reflect diverse therapeutic approaches and patient needs. Understanding these classifications is crucial for identifying areas of concentrated demand and emerging treatment paradigms. This detailed breakdown highlights the mechanisms of action and delivery methods shaping patient access and clinical outcomes.
Product Type:
The functional classification of immuno-oncology drugs reveals distinct mechanisms for engaging the immune system against cancer.
- Monoclonal Antibodies:These engineered proteins specifically bind to target antigens on cancer cells or immune cells, neutralizing inhibitory signals or activating immune responses. Their broad application across various cancer types underpins a significant portion of market volume.
- Checkpoint Inhibitors:A crucial subset of monoclonal antibodies, these therapies block immune checkpoints like PD-1/PD-L1 or CTLA-4, releasing the brakes on anti-tumor immune responses. Their efficacy in solid tumors drives substantial market growth and clinical adoption.
- Cytokines:These signaling proteins modulate immune cell activity, enhancing anti-tumor immunity through direct stimulation or regulation of immune cell proliferation.
- Oncolytic Virus Therapy:Genetically modified viruses selectively infect and replicate within cancer cells, causing cell lysis and stimulating anti-tumor immune responses.
Monoclonal Antibodies command the established base. The steepest expansion runs through Checkpoint Inhibitors.
Therapy Area:
The application spectrum of immuno-oncology drugs addresses a wide range of cancer types, from widespread solid tumors to specific hematological malignancies.
- Solid Tumors:This category encompasses cancers like melanoma, lung, and renal cell carcinoma, where immune checkpoint inhibitors have demonstrated significant clinical efficacy. Applications in solid tumors represent the largest and most established therapy area, driving volume.
- Hematological Malignancies:These blood cancers, including leukemia and lymphoma, are increasingly treated with advanced cell therapies like CAR-T. Clinical adoption is accelerating due to targeted efficacy against these specific cancer types.
- Cancer Immunotherapy:This broad category includes all treatments that stimulate or restore the immune system's ability to fight cancer.
- Neoantigen Targeting:Therapies in this area focus on patient-specific tumor neoantigens, offering a pathway toward individualized cancer treatment.
Demand for Solid Tumors remains foundational. Hematological Malignancies demonstrate rapid market penetration.
Delivery Mode:
Patient administration routes for immuno-oncology drugs vary based on drug characteristics and therapeutic requirements, impacting patient convenience and treatment settings.
- Intravenous:This mode involves direct injection into a vein, ensuring rapid and complete systemic bioavailability for complex biologics. Hospitals and specialized clinics are the primary settings for intravenous administration.
- Subcutaneous:Administered under the skin, this method offers increased patient convenience and potential for home administration, reducing healthcare burden. Its adoption is growing for certain monoclonal antibodies.
- Oral:Oral formulations provide significant convenience for patients, allowing self-administration outside of clinical settings for specific small molecule immunomodulators.
- Topical:Applied directly to the skin, topical delivery is primarily used for localized skin cancers or pre-cancerous lesions, minimizing systemic exposure.
Intravenous delivery represents the standard of care. Subcutaneous administration is gaining traction due to patient convenience.
End User:
The primary care delivery points and research hubs for immuno-oncology drugs span various healthcare and scientific institutions, each playing a distinct role in patient treatment and therapeutic advancement.
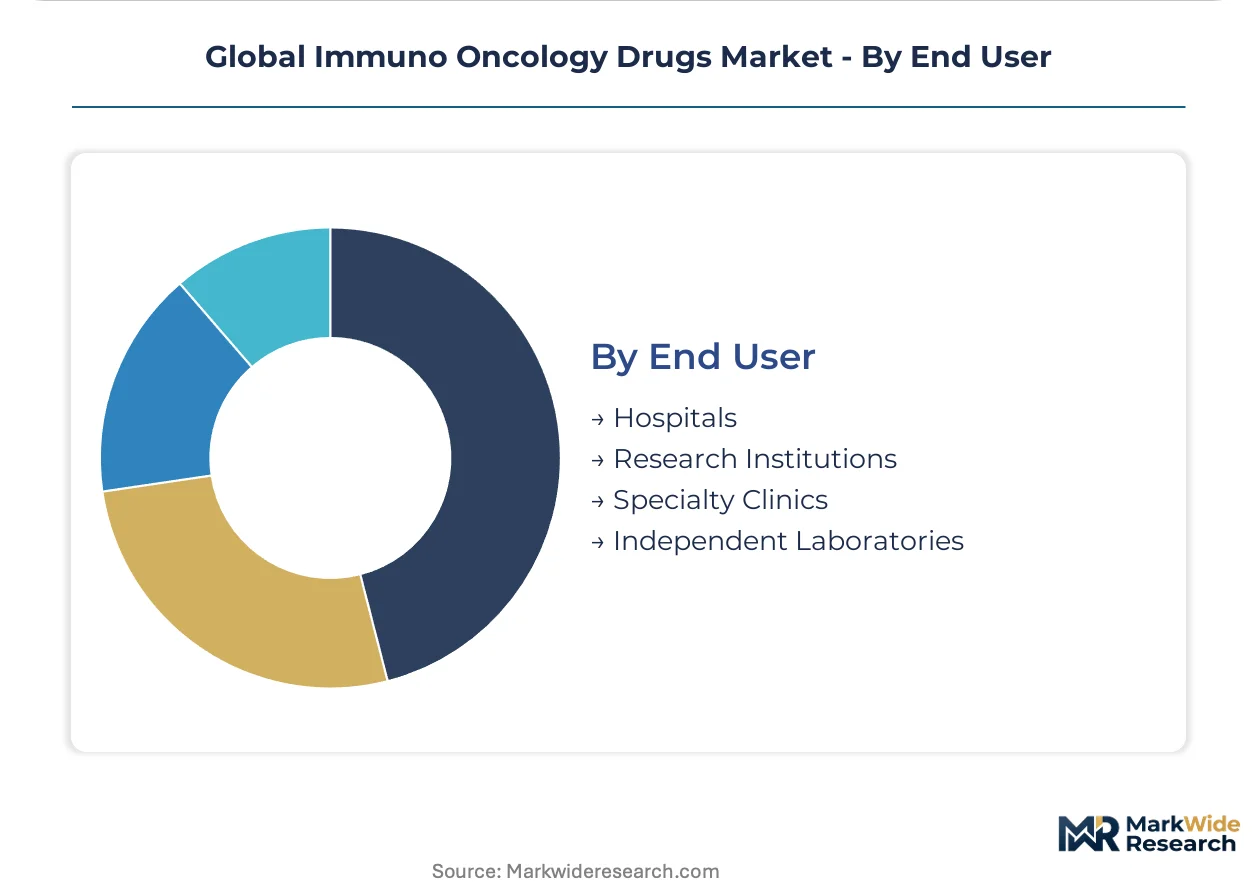
- Hospitals:These institutions serve as the main centers for cancer diagnosis, treatment, and long-term patient management, administering a vast majority of immuno-oncology therapies. Their comprehensive facilities support complex treatment regimens.
- Research Institutions:Academic and private research centers are pivotal in discovering novel targets, developing new drug candidates, and conducting clinical trials. They drive the innovation pipeline for future immuno-oncology treatments.
- Specialty Clinics:These outpatient facilities provide focused cancer care, often offering chemotherapy and immunotherapy services with specialized oncologists.
- Independent Laboratories:These laboratories perform diagnostic testing, including biomarker analysis, essential for patient selection and monitoring immuno-oncology drug response.
Hospitals drive the majority of drug utilization. Research Institutions are critical for advancing future therapies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global immuno-oncology drugs market exhibits a complex trade dynamic, with significant innovation hubs driving exports of novel therapies while patient-dense regions increasingly import these advanced treatments. Market expansion is closely tied to regulatory modernization and healthcare infrastructure development across diverse geographies.
United States
Demand for advanced immuno-oncology drugs stems from a large patient population and robust healthcare spending. The FDA's accelerated approval pathway facilitates rapid market entry for promising new therapies. Major biotech clusters in Boston and San Francisco drive research and development, fostering continuous innovation in cancer treatment.
China
Immuno-oncology drug adoption accelerates due to extensive patient needs and government support for domestic innovation. China's NMPA has streamlined drug approval processes, expanding patient access to novel treatments. Shanghai and Beijing host significant pharmaceutical research parks, attracting investment in oncology drug development.
Germany
A strong healthcare system and a focus on precision medicine underpin the demand for high-value immuno-oncology therapies. The European Medicines Agency (EMA) ensures rigorous safety and efficacy standards for market authorization. Pharmaceutical hubs like Munich and Frankfurt are centers for both drug manufacturing and clinical research.
Japan
An aging population and high prevalence of certain cancers contribute to sustained demand for effective immuno-oncology treatments. Japan's PMDA provides a clear regulatory framework for drug approvals, including expedited pathways for unmet medical needs. The Kansai region, particularly Osaka, is a key center for pharmaceutical R&D and manufacturing.
Brazil
Underpenetrated markets present significant growth avenues as healthcare access expands for advanced biologics. ANVISA, the national health surveillance agency, modernizes its regulatory frameworks for complex therapies. São Paulo serves as a major medical hub, driving both clinical trials and the distribution of specialized oncology drugs.
Global Immuno Oncology Drugs Market Key Industry Players
On the supply side, the industry is characterized by a concentrated core of large pharmaceutical companies, complemented by a vibrant ecosystem of specialized biotech firms. These established players leverage extensive R&D capabilities and global distribution networks. Strategic partnerships and targeted acquisitions dominate competitive moves, alongside continuous portfolio diversification into novel therapeutic modalities.
Among established pharmaceutical innovators, Bristol Myers Squibb Company exemplifies leadership in checkpoint inhibitors, drawing on extensive clinical data to secure market access. F. Hoffmann-La Roche Ltd. occupies a strategic position through its integrated companion diagnostics, linking drug efficacy to specific patient biomarkers. Merck & Co., Inc. anchors a significant portion of the market, particularly with its foundational immuno-oncology assets.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol Myers Squibb Company |
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca plc |
| Novartis AG |
| Pfizer Inc. |
| AbbVie Inc. |
| Amgen Inc. |
| GSK Plc. |
Cost & Logistics Intelligence
Limited manufacturing capacity for advanced cell therapies, particularly CAR-T, directly influences supplier behavior and pricing strategies. This undercapacity sustains premium pricing for complex biotherapeutics while driving investment in new production facilities globally.
Pricing Analysis
Healthcare system buyers, including national health services and private insurers, anchor value-based pricing models for immuno-oncology drugs. This pricing links payment to robust evidence of long-term efficacy and clinical outcomes, departing from traditional fee-for-service. Price differentiation stems from drug efficacy in specific patient populations, often identified by companion diagnostics, and the severity of the targeted cancer. Pricing pressure stems from extreme treatment costs and stringent payer reimbursement hurdles. Single-payer systems in Europe exhibit the highest price sensitivity, while private markets with robust healthcare spending show less.
Supply Chain Analysis
Stringent regulatory controls on biopharmaceutical manufacturing processes and specialized raw materials limit global supply flows for immuno-oncology drugs. Geographic supply concentration exists in the United States for advanced biologics production and in China for certain active pharmaceutical ingredients. The supply chain draws from highly specialized inputs, including viral vectors and patient-specific T-cells for CAR-T therapies. A structural risk involves cell therapy manufacturing scalability, which faces logistical and cost challenges. Distribution runs through a network of hospitals and specialized oncology clinics for patient administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immuno-oncology market is in an early-cycle expansion phase, driven by accelerating adoption of checkpoint inhibitors for solid tumors. This growth reflects expanding clinical indications and increasing patient access through regulatory reforms in key markets.
For Market Incumbents: Build a regulatory and clinical data moat around established checkpoint inhibitors by leveraging extensive real-world evidence. This defends against emerging biosimilar threats and new entrants with less robust data packages. Focus R&D investment into novel combination therapies and personalized neoantigen vaccines to overcome resistance mechanisms. Expand manufacturing capacity for advanced cell therapies in key regions to mitigate supply chain risks.
For New Entrants and Emerging Players: Latin American markets, particularly Brazil, represent a significant geographic underpenetration for advanced immuno-oncology biologics. Target niche indications within hematological malignancies or rare solid tumors with high unmet medical need to establish clinical proof-of-concept. A go-to-market angle involves partnering with local research institutions and leveraging regulatory modernization efforts by agencies like ANVISA for expedited approvals. Focus on therapies addressing patient-specific tumor neoantigens.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among companies with established checkpoint inhibitor franchises and a diversified pipeline of late-stage assets. Long-term viability over a 5-10 year window favors firms investing heavily in personalized medicine and cell therapy platforms. Identify acquisition targets specializing in advanced biomarker discovery or novel delivery platforms that can overcome resistance. The signal to watch is successful Phase 3 readouts for combination therapies targeting solid tumors.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for novel immunotherapies by demonstrating robust efficacy and safety data. |
| Regulatory Approval Pathway | Leverages expedited programs like the FDA's accelerated pathway to bring promising drugs to patients faster. |
| Manufacturing Scale-Up | Addresses complex logistical challenges for cell therapies, ensuring broader patient access and consistent supply. |
| Pipeline Diversification | Expands therapeutic offerings beyond established checkpoint inhibitors into new modalities and targets. |
| Licensing Agreement | Secures access to innovative technologies or specific patient biomarkers, enhancing competitive positioning. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform this analysis. Primary interviews included drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. This primary data was validated against extensive secondary sources, such as FDA filings, EMA submissions, ClinicalTrials.gov, and national formulary databases. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
The analytical framework was calibrated through a multi-stage process, integrating historical data with forward-looking projections across the analysis window. Segmentation dimensions modeled include product type, therapy area, delivery mode, end user, and regional regulatory cluster. Compound Annual Growth Rates (CAGRs) were derived by analyzing market drivers and restraints, alongside industry-specific inputs such as clinical trial success rates and payer reimbursement uptake. This comprehensive approach ensures robust forecast accuracy.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large pharmaceutical companies or disruptive biotech firms would shift outcomes. Forecasts reflect assumptions regarding regulatory reforms and clinical trial progression. Material shifts in major drug approvals or reimbursement policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
Hepatitis Therapeutics Market