
 Ceftriaxone Market | 2026-2036
Ceftriaxone Market Size, Share, and Industry Trends Forecast 2026-2036
Ceftriaxone Market Outlook
The divergence between premium lyophilized vials and commodity powder-for-solution formats is hardening as hospital formularies tighten procurement specifications. Pfizer Inc. leverages its sterile injectable infrastructure to command premium shelf space in regulated markets. Hikma Pharmaceuticals PLC anchors its position through vertical control over API sourcing and finished-dose production. Lupin Pharmaceuticals, Inc. competes aggressively on cost in emerging markets where national tenders dominate volume allocation.
Ceftriaxone is a third-generation cephalosporin antibiotic with a broad gram-negative spectrum, manufactured via 7-ACA nucleus acylation followed by sterile crystallization or lyophilization to achieve parenteral stability; its primary purpose is empiric treatment of severe bacterial infections and perioperative prophylaxis in inpatient settings. Injectable formulations lead value contribution due to hospital preference for IV/IM administration in critical care, while lyophilized products capture premium pricing through extended shelf stability and cold-chain flexibility. Surgery prophylaxis indication pools are deepening as preoperative antibiotic protocols expand across tertiary hospitals in Asia-Pacific and Latin America.
FDA sterility guidelines, EMA Good Manufacturing Practice annexes for cephalosporins, and India's CDSCO Schedule M requirements collectively elevate barrier costs for new entrants while accelerating consolidation among established manufacturers. WHO prequalification status increasingly determines eligibility for bulk procurement by global health funds and national essential medicine programs. Stakeholders must monitor evolving carbapenem-resistance patterns that could trigger formulary substitution away from extended-spectrum cephalosporins in high-burden infectious disease settings.
Market Dynamics
Antimicrobial stewardship mandates across India and China are forcing hospital formulary committees to consolidate injectable antibiotic procurement around pre-qualified sterile cephalosporin suppliers, compressing vendor lists while elevating batch-traceability requirements.
Growth Catalysts
- CDSCO Schedule M enforcement:India's tightened sterile manufacturing standards are disqualifying sub-scale API producers and redirecting hospital tenders toward integrated manufacturers with captive 7-ACA supply.
- Surgical volume expansion:Tertiary hospital construction across Maharashtra and Gujarat is deepening perioperative prophylaxis demand for lyophilized vial formats with extended cold-chain tolerance.
- WHO prequalification pathway:Global health fund eligibility rules are concentrating export demand on manufacturers with documented sterile process validation and API-to-finished-dose traceability.
Market Restraints
- 7-ACA feedstock concentration:Three chemical clusters in Shandong Province control over 60 percent of global cephalosporin nucleus supply, exposing finished-dose manufacturers to input volatility and quota restrictions.
- EMA Annex 1 sterile barrier costs:Updated good manufacturing practice requirements for isolator technology and continuous particulate monitoring are elevating capital intensity for lyophilization lines by an estimated 25-40 percent.
- Carbapenem displacement risk:Rising extended-spectrum beta-lactamase prevalence in Indian intensive care units is triggering protocol substitution toward meropenem and ertapenem for empiric sepsis coverage.
Strategic Opportunities
- Sub-Saharan tender eligibility:WHO prequalification status remains underpenetrated among Indian mid-tier injectable specialists, creating first-mover advantage for manufacturers completing sterile process validation documentation.
- Fixed-dose combination development:Ceftriaxone-sulbactam and ceftriaxone-tazobactam formulations are capturing formulary slots in Brazilian and Mexican public hospitals seeking spectrum extension without carbapenem escalation.
- Pre-filled syringe automation:Robotics-enabled aseptic filling lines are enabling point-of-care reconstitution convenience for emergency department and ambulance settings in Saudi Arabia and UAE Ministry of Health tenders.
Industry Challenges
- Sterile process engineering talent scarcity:Lyophilization cycle optimization and isolator qualification expertise concentrates among a limited pool of specialists trained at Pfizer's legacy Kalamazoo and Hikma's Portugal technical centers.
- FDA warning letter remediation timelines:Data integrity deficiencies in laboratory information management systems have extended approval cycles for Indian manufacturers by 18-24 months, freezing capacity expansion plans.
- API-finished dose synchronization:Mismatch between 7-ACA fermentation batch cycles and sterile filling line scheduling creates working capital compression and expiry risk for powder-for-solution formats with shorter shelf stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceftriaxone Market |
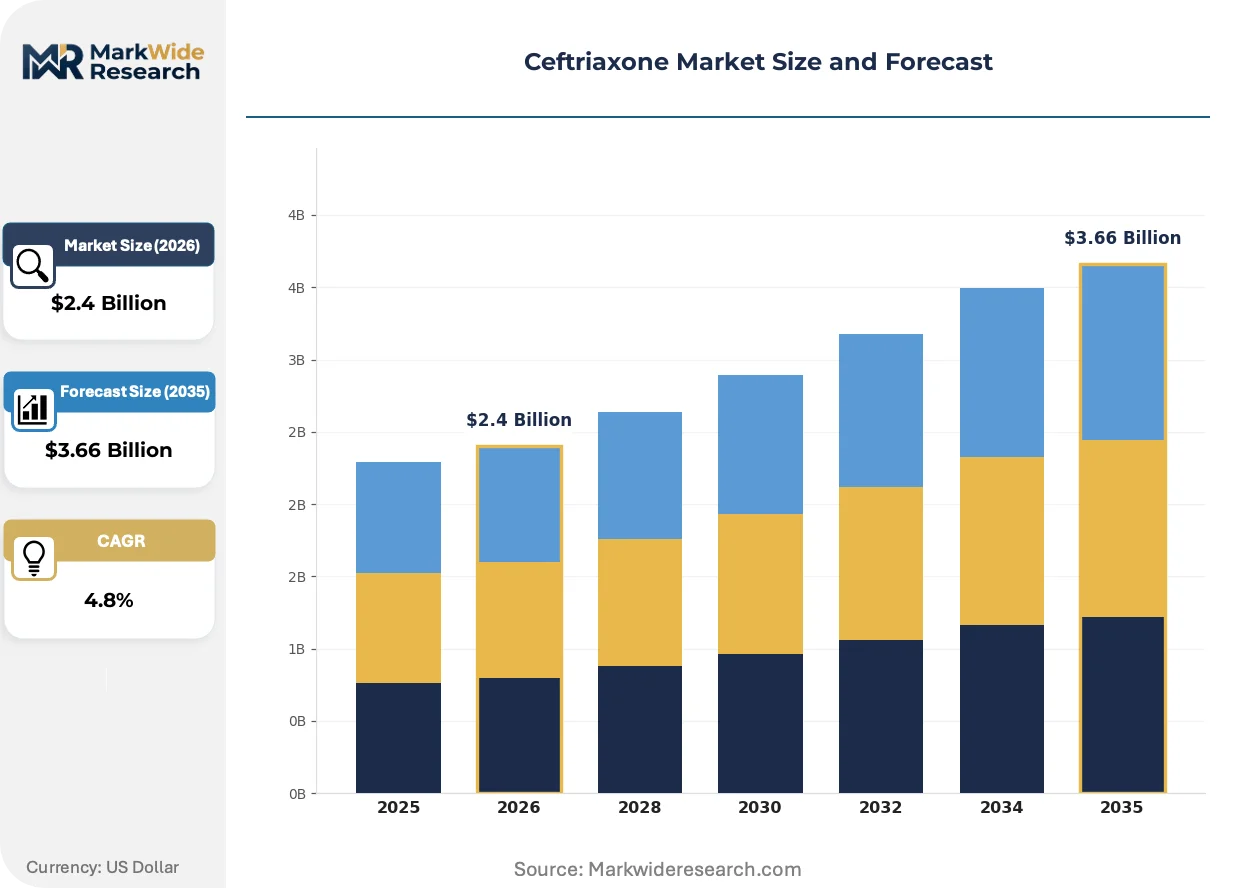
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Powder for Solution, Lyophilized Indication: Infections, Surgery Prophylaxis, Meningitis, Pneumonia End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Therapeutic Class: Beta-Lactams, Cephalosporins, Antibiotics, Others |
| Companies Covered | GlaxoSmithKline plc, Lupin Pharmaceuticals, Inc., Pfizer Inc., Hikma Pharmaceuticals PLC, Fresenius Kabi AG, F. Hoffmann-La Roche Ltd., Aurobindo Pharma Ltd., Teva Pharmaceutical Industries Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceftriaxone Market Strategic Shifts
Continuous manufacturing technologies and real-time release testing protocols are displacing traditional batch-based sterile processing, compressing inspection timelines while elevating sensor and analytics infrastructure requirements across cephalosporin injectable lines.
Single-use bioreactor and sterile connector technologies are expanding into cephalosporin API fermentation and downstream processing, reducing cross-contamination risk between beta-lactam and non-beta-lactam campaigns. European contract manufacturers including those serving Swissmedic-regulated markets are adopting these disposable systems to accelerate product changeover and reduce cleaning validation burden. The shift is compressing campaign turnaround times from weeks to days, enabling smaller-batch production economics for niche indications and pediatric dosing formats.
EMA's revised Annex 1 on sterile medicinal products, effective August 2023, mandates barrier isolation technology for all Grade A filling operations and continuous viable and non-viable particle monitoring. Manufacturers serving European hospital procurement are retrofitting legacy cleanrooms with restricted access barrier systems or constructing greenfield isolator-based lines, elevating compliance capital outlays while disqualifying facilities unable to fund upgrades. Indian exporters targeting EMA-regulated markets are consolidating production at Gujarat-based sites with pre-existing isolator infrastructure.
Hospital purchasing consortiums in São Paulo State and Mexico's IMSS system are consolidating antibiotic tenders under outcome-based compliance metrics linking supplier selection to surgical site infection rate performance. Traditional distributor networks with markup-based compensation are losing share to direct manufacturer-contracting models with transparent unit pricing and bundled technical support. Brazilian tertiary hospitals are piloting this procurement evolution through ANVISA's risk-based inspection framework, which rewards documented sterility assurance with reduced audit frequency.
Ceftriaxone Market Segmentation
Ceftriaxone procurement patterns diverge sharply across formulation technologies and care settings, with hospital formularies tightening specifications around sterile injectable stability and cold-chain tolerance. Segmentation reveals how antimicrobial stewardship programs are compressing vendor lists while elevating batch-traceability requirements for specific product formats.
Product Type:
Upgrade cycles from powder-for-solution to lyophilized formats are accelerating as tertiary hospitals in Maharashtra and Gujarat prioritize extended shelf stability for perioperative protocols.
- Injectable:Intravenous and intramuscular formulations dominate inpatient empiric therapy, with Maharashtra's tertiary hospitals consolidating procurement around pre-qualified sterile cephalosporin suppliers. CDSCO Schedule M enforcement is disqualifying sub-scale producers from hospital tender eligibility.
- Lyophilized:Freeze-dried vial formats command premium positioning through cold-chain flexibility and multi-year shelf stability. Demand concentrates in Saudi Arabia and UAE Ministry of Health tenders where point-of-care reconstitution convenience drives formulary preference.
- Powder for Solution:Commodity-grade presentations serve cost-sensitive national tenders in emerging markets where shorter stability windows align with rapid inventory turnover. Working capital compression from API-finished dose synchronization creates expiry risk.
- Oral:Limited bioavailability restricts this format to step-down therapy in outpatient settings, with minimal penetration in severe infection protocols.
Injectable formats sit at the top of the volume ranking, with lyophilized products climbing the fastest.
Indication:
Cost tier differentiation separates empiric sepsis coverage from scheduled surgical prophylaxis, with the latter commanding stricter sterility documentation and supplier qualification thresholds.
- Surgery Prophylaxis:Preoperative antibiotic protocols across tertiary hospitals in Asia-Pacific and Latin America are deepening demand pools. Brazilian ANVISA risk-based inspection frameworks reward documented sterility assurance with reduced audit frequency for compliant suppliers.
- Infections:Broad-spectrum empiric therapy for severe bacterial infections anchors volume in intensive care units, though rising extended-spectrum beta-lactamase prevalence in Indian ICUs is triggering protocol substitution toward carbapenems.
- Pneumonia:Community-acquired and hospital-acquired pneumonia indications compete against respiratory fluoroquinolones in outpatient settings, with injectable ceftriaxone reserved for inpatient escalation.
- Meningitis:CNS penetration requirements limit this segment to high-dose IV protocols in pediatric and adult neurology wards, with stringent batch-testing documentation for regulated markets.
Surgery prophylaxis captures the largest addressable patient volume, though infection indications face the steepest competitive pressure from alternative antibiotic classes.
End User:
Customer type determines packaging specifications, with hospital procurement demanding multi-dose vial formats and homecare settings requiring single-use prefilled systems.
- Hospitals:Tertiary and secondary inpatient facilities drive value concentration through IV/IM administration preference in critical care. India's antimicrobial stewardship mandates are forcing formulary committees to consolidate around integrated manufacturers with captive 7-ACA supply.
- Clinics:Ambulatory surgical centers and outpatient infusion facilities favor lyophilized formats with simplified reconstitution protocols for same-day discharge workflows.
- Long-term Care Facilities:Extended-duration therapy in skilled nursing settings requires stability-optimized presentations with reduced refrigeration dependency.
- Homecare:Subcutaneous and IM administration in residential settings is expanding in Saudi Arabia and UAE through Ministry of Health pilot programs for post-surgical antibiotic continuation.
Hospitals maintain dominant procurement volume, while homecare channels are gaining share fastest in Gulf Cooperation Council markets.
Therapeutic Class:
Margin structures within the beta-lactam supercategory favor third-generation cephalosporins with documented sterile process validation over older generic alternatives facing price compression.
- Cephalosporins:Third-generation spectrum positioning distinguishes ceftriaxone from first and second-generation alternatives, with EMA Annex 1 sterile barrier requirements elevating compliance costs for manufacturers serving European hospital procurement.
- Beta-Lactams:The broader class encompassing penicillins and cephalosporins faces cross-resistance surveillance protocols that inform formulary tier placement across Indian and Chinese hospital systems.
- Antibiotics:General anti-infective category competition includes macrolides, fluoroquinolones, and glycopeptides, with spectrum-specific guidelines determining empiric therapy hierarchies.
- Others:Adjunctive therapeutic categories including combination therapies with beta-lactamase inhibitors capture formulary slots in Brazilian and Mexican public hospitals seeking spectrum extension.
Cephalosporins anchor the revenue base within this segmentation, with beta-lactamase inhibitor combinations expanding most quickly in Latin American tender markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sterile process engineering talent concentrates in Pfizer's Kalamazoo complex and Hikma's Portugal technical centers, anchoring North American and European supply reliability. Indian API-to-finished-dose integration clusters in Maharashtra and Gujarat now capture expanding hospital tender volumes across emerging markets.
United States
Hospital procurement consolidation around antimicrobial stewardship programs drives demand for documented sterile process validation. FDA sterility guidelines and warning letter enforcement compress vendor lists toward established manufacturers with legacy injectable infrastructure. Pfizer's Kalamazoo facility anchors domestic lyophilized capacity serving tertiary hospital networks.
India
Tertiary hospital construction across Maharashtra and Gujarat deepens perioperative prophylaxis demand for cold-chain-tolerant formats. CDSCO Schedule M enforcement disqualifies sub-scale API producers and redirects tenders toward integrated manufacturers with captive 7-ACA supply. Mumbai and Ahmedabad pharmaceutical clusters dominate export supply through WHO prequalification pathways.
China
Three chemical clusters in Shandong Province control over sixty percent of global cephalosporin nucleus supply, exposing finished-dose manufacturers to input volatility. NMPA sterile manufacturing standards align with international GMP benchmarks, elevating compliance costs for domestic producers. Yangtze River Delta formulation facilities serve as contract manufacturing hubs for regulated market exporters.
Brazil
São Paulo State hospital purchasing consortiums consolidate antibiotic tenders under outcome-based compliance metrics linking supplier selection to surgical site infection performance. ANVISA's risk-based inspection framework rewards documented sterility assurance with reduced audit frequency. Public hospital formulary slots for ceftriaxone-sulbactam combinations expand spectrum extension without carbapenem escalation.
Germany
EMA Annex 1 sterile barrier requirements mandate isolator technology for all Grade A filling operations, elevating capital intensity for lyophilization lines. Fresenius Kabi's domestic manufacturing anchors European hospital procurement through documented API-to-finished-dose traceability. Bavaria-based contract manufacturers adopt single-use bioreactor technologies to accelerate product changeover and reduce cleaning validation burden.
Ceftriaxone Market Competitive Environment
Top-tier vendors anchor regulated market premium positioning, while mid-tier Indian specialists compete on cost in emerging market tenders. The vendor base stratifies across three tiers: multinational pharmaceutical corporations with legacy sterile injectable infrastructure, vertically integrated Indian manufacturers with captive API supply, and European contract manufacturers serving Swissmedic-regulated markets. Consolidation accelerates through M&A targeting sterile process validation capabilities and capacity expansion at Gujarat-based sites with pre-existing isolator infrastructure.
Within the multinational tier, Pfizer Inc. and Hikma Pharmaceuticals PLC exemplify divergent strategic archetypes—Pfizer leveraging legacy infrastructure for premium shelf space, Hikma anchoring position through upstream control over API sourcing. Lupin Pharmaceuticals, Inc. occupies a position among Indian cost-competitive specialists aggressively pursuing national tender volumes. These three entities collectively represent the competitive tension between premium regulated market positioning and emerging market volume capture.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Lupin Pharmaceuticals, Inc. |
| Pfizer Inc. |
| Hikma Pharmaceuticals PLC |
| Fresenius Kabi AG |
| F. Hoffmann-La Roche Ltd. |
| Aurobindo Pharma Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Lyophilized-premium versus powder-commodity bifurcation manifests in divergent margin structures and sourcing configurations across hospital procurement networks. EMA Annex 1 compliance costs for isolator technology anchor premium tier pricing in European tenders, while Indian national tenders absorb cost-optimized powder formats from Maharashtra-based integrated manufacturers.
Pricing Analysis
Bundled sterility assurance and technical documentation services command premium positioning in regulated markets, while unbundled commodity transactions dominate emerging market tenders. Price differentiation rests on WHO prequalification status and EMA sterile barrier certification, with CDSCO Schedule M enforcement compressing margins for non-compliant Indian suppliers. Pricing pressure stems from carbapenem substitution protocols in Indian ICUs, eroding empiric therapy volumes. Government hospital tenders exhibit highest price sensitivity; Saudi Ministry of Health procurement shows lowest sensitivity due to cold-chain reliability premiums.
Supply Chain Analysis
Direct-to-hospital channels handle tertiary institution demand in Maharashtra and Gujarat, while distributor networks serve secondary facilities across emerging markets. API concentration centers on Shandong Province chemical clusters, with finished-dose manufacturing anchoring in Indian pharmaceutical corridors and European contract facilities. Raw material dependencies include 7-ACA cephalosporin nucleus, acylation reagents, and sterile packaging components. Single-source vulnerability in Shandong's 7-ACA supply exposes manufacturers to quota restrictions and input volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceftriaxone functions as a regulatory compounder where EMA Annex 1 sterile barrier mandates and CDSCO Schedule M enforcement accelerate demand concentration toward validated manufacturers.
For Market Incumbents: Deepen isolator infrastructure investment at Gujarat-based production sites to defend EMA-regulated market access against emerging Indian competitors. Prioritize captive 7-ACA supply integration to buffer Shandong feedstock volatility. Reinforce WHO prequalification documentation to maintain eligibility for Sub-Saharan tender pools. For New Entrants and Emerging Players: Launch via WHO prequalification pathway targeting underpenetrated Sub-Saharan antibiotic tenders where sterile process validation documentation creates first-mover advantage. Focus initial penetration on ceftriaxone-sulbactam fixed-dose combinations in Brazilian public hospital procurement. Deploy direct manufacturer-contracting models to displace traditional distributor markups in São Paulo State purchasing consortiums. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA warning letter remediation timelines extend 18-24 months for data integrity deficiencies, freezing capacity expansion and creating distressed acquisition opportunities. Long-term viability favors vertically integrated manufacturers with documented API-to-finished-dose traceability. Target acquisition archetype: Indian mid-tier injectable specialists with pre-existing isolator infrastructure and incomplete sterile process validation documentation. Monitor carbapenem-resistance surveillance data from Indian ICUs as inflection indicator for cephalosporin substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Retrofit | EMA Annex 1 compliance secures European hospital procurement eligibility against non-upgraded competitors. |
| WHO Prequalification Completion | Global health fund eligibility unlocks Sub-Saharan tender volumes for validated sterile process manufacturers. |
| Fixed-Dose Combination Development | Ceftriaxone-sulbactam formulations capture Brazilian ANVISA formulary slots without carbapenem escalation. |
| Captive 7-ACA Integration | Backward integration into cephalosporin nucleus supply buffers Shandong quota volatility and input cost swings. |
| Pre-Filled Syringe Automation | Robotics-enabled aseptic filling addresses Saudi and UAE Ministry of Health point-of-care reconstitution requirements. |
Study Parameters
Coverage spans United States, India, China, Brazil, and Germany, with primary inputs from each market's hospital procurement and regulatory environments. The analysis combines interviews with formulary directors, sterile manufacturing engineers, regulatory affairs leads, and hospital procurement managers with secondary validation from FDA warning letters, EMA GMP inspection reports, CDSCO Schedule M filings, and WHO prequalification databases. Bottom-up demand modeling triangulates against top-down market sizing across the projection horizon.
Granularity-level framing applies country-specific regulatory cluster modeling alongside product format and indication segmentation. The analytical framework projects volume and value across lyophilized, powder-for-solution, and injectable presentations, with administration route and shelf stability specifications as cross-cutting dimensions. CAGRs derive from sterilization capacity expansion timelines, hospital construction pipelines, and antimicrobial stewardship policy implementation curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbapenem-resistance acceleration or 7-ACA supply disruption scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Psychedelic Drugs Market