
 Hemorrhoids Treatment Market | 2026-2036
Hemorrhoids Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hemorrhoids Treatment Market Outlook
Single-source API procurement for topical hemorrhoid formulations is shifting toward multi-source agreements as manufacturers seek supply resilience. Bayer AG leverages its established dermatology infrastructure to sustain brand loyalty in retail pharmacy channels. Abbott Laboratories competes through device-led portfolios that bridge pharmaceutical and interventional care. Church & Dwight Co., Inc. anchors its position in the consumer-accessible segment with broad retail distribution.
Hemorrhoids treatment encompasses pharmacological, mechanical, and surgical interventions targeting swollen vascular structures in the anal canal, with topical formulations typically combining vasoconstrictors, corticosteroids, or local anesthetics in standardized concentrations. The primary commercial purpose centers on symptom relief, procedural intervention, and recurrence prevention across outpatient and self-care settings. Topical creams and suppositories occupy the largest revenue pool due to repeat-purchase behavior and minimal prescription barriers. Minimally invasive treatment techniques represent the fastest-expanding category as rubber band ligation and sclerotherapy displace conventional surgery in ambulatory settings. Surgical instruments segment margins concentrate in specialized energy devices and disposable kits used in hospital outpatient departments.
The FDA regulates topical drug formulations and labeling claims for OTC hemorrhoid products under monograph standards, while the EPA oversees manufacturing facility environmental compliance affecting active ingredient production. HIPAA privacy frameworks shape how clinics and hospitals collect patient-reported outcome data used in post-procedural follow-up protocols. Stakeholders must monitor evolving reimbursement thresholds for office-based procedures versus surgical intervention as payers recalibrate site-of-service differentials.
Market Dynamics
FDA tightening of OTC topical drug labeling standards is forcing manufacturers to reformulate active ingredient concentrations and revalidate clinical claims, compressing product development timelines while elevating compliance costs across the consumer-accessible segment.
Growth Catalysts
- Site-of-service migration:Payer reimbursement differentials favoring ambulatory surgical centers over hospital outpatient departments are accelerating procedural volume shifts toward lower-acuity settings.
- REACH chemical safety protocols:European harmonization of excipient purity standards is streamlining cross-border formulation approvals and reducing regulatory fragmentation for topical manufacturers.
- Dual-source API contracting:Supply resilience mandates from procurement departments at major retail pharmacy chains are expanding qualified supplier pools beyond single-source dependencies.
Market Restraints
- Active ingredient concentration caps:FDA monograph revisions limiting phenylephrine and hydrocortisone percentages in OTC products are constraining formulation efficacy differentiation.
- Specialized energy device supply:German and Japanese precision electronics suppliers dominate radiofrequency and laser component manufacturing for interventional devices, creating geographic concentration risk.
- Generic topical substitution:Pharmacy benefit managers are auto-substituting branded creams and suppositories with therapeutically equivalent private-label alternatives, compressing brand premium capture.
Strategic Opportunities
- India outpatient clinic expansion:Tier-2 and Tier-3 city healthcare infrastructure investments under Ayushman Bharat are creating procedural capacity for rubber band ligation and sclerotherapy services.
- Digital therapeutics integration:Smartphone-based symptom tracking and telehealth consultation platforms are converging with traditional pharmaceutical distribution to capture pre-treatment patient journeys.
- Extended-release suppository formulations:Polymeric matrix technologies enabling 12-hour active ingredient release are opening premium positioning opportunities in the prescription channel.
Industry Challenges
- Clinical trial recruitment:Patient reluctance to participate in hemorrhoid-related studies due to stigma is elongating FDA 505(b)(2) pathway timelines for novel topical entities.
- Legacy EHR integration:Ambulatory surgical center adoption of procedure-specific outcome tracking modules requires custom API development with dominant hospital system electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemorrhoids Treatment Market |
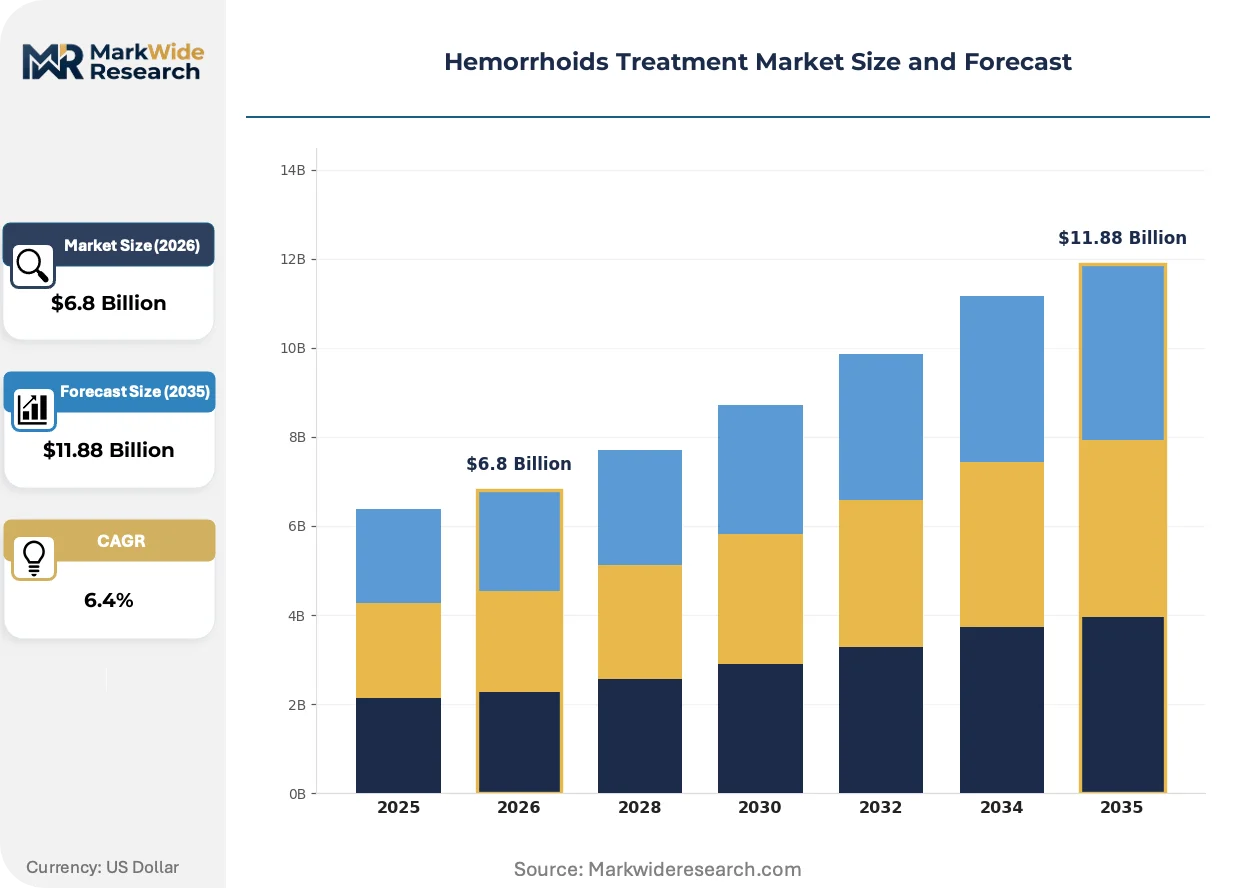
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Suppositories, Oral Medications, Surgical Instruments Application: In-office Procedures, Home Remedies, Surgical Treatment, Preventive Care End User: Clinics, Hospitals, Home Care, Pharmacies Treatment Technique: Minimally Invasive, Conventional Surgery, Laser Therapy, Cryotherapy |
| Companies Covered | Haleon Group of Companies, Bayer AG, Abbott Laboratories, Church & Dwight Co., Inc., Lupin, Cipla, Sanofi, Boston Scientific Corporation, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemorrhoids Treatment Market Strategic Shifts
Technological convergence between minimally invasive devices and pharmaceutical delivery systems is compressing the traditional boundary between self-care and procedural intervention, while regulatory pressure on formulation transparency accelerates ingredient sourcing disclosure.
Radiofrequency ablation platforms with disposable catheter kits are modularizing the treatment workflow for grade II-III internal hemorrhoids, enabling gastroenterology practices to convert examination rooms into procedure suites without capital-intensive surgical infrastructure. Ambulatory surgical centers in the United States and Germany are adopting these systems at replacement cycles of 18-24 months. This modularization is compressing equipment vendor margins while expanding addressable procedure volumes beyond traditional colorectal surgery referral networks.
REACH Annex XVII restrictions on boron compounds and specific corticosteroid esters are forcing European topical manufacturers to reformulate with alternative vasoconstrictor complexes and synthetic steroid analogs. The industrial consequence is a 12-18 month revalidation burden for existing product registrations. OTC suppository and cream categories face the most acute compliance pressure, with several mid-tier suppliers exiting the market rather than absorbing reformulation costs.
Direct-to-consumer subscription models for prescription-strength topical combinations are disrupting traditional retail pharmacy fulfillment, particularly among patients with recurrent symptomatic episodes. Telehealth platforms are capturing the initial consultation and prescription authorization, displacing primary care physician visits. This channel shift is most visible in the United States, where HIPAA-compliant digital health infrastructure enables seamless pharmacy benefit integration.
Hemorrhoids Treatment Market Segmentation
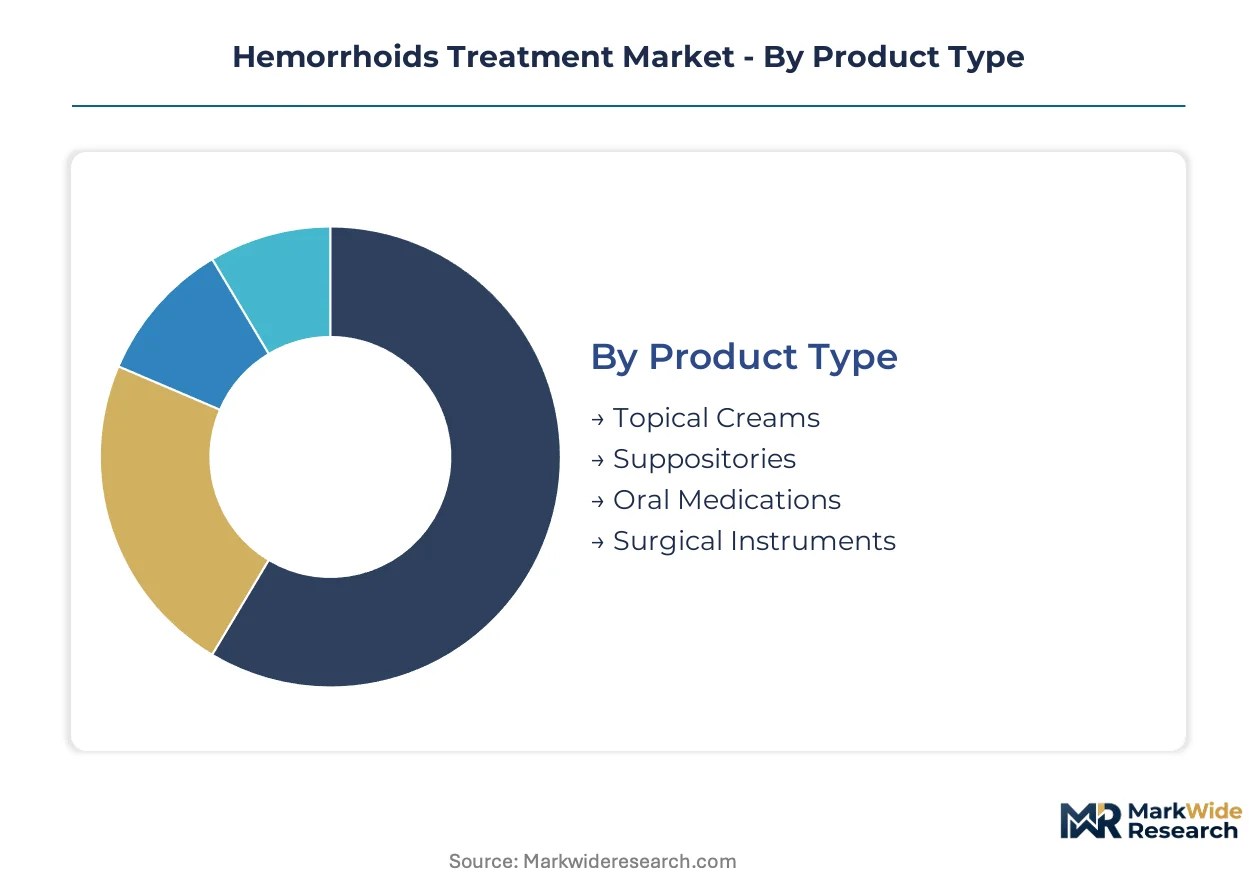
Product heterogeneity across the hemorrhoids treatment market creates distinct margin profiles and channel requirements. Manufacturers must align formulation investments with site-of-service evolution and patient self-care preferences.
Product Type:
Replacement cycles for topical delivery systems are compressing as FDA monograph revisions force reformulation investments.
- Topical Creams:Vasoconstrictor-corticosteroid-anesthetic combinations in standardized concentrations dominate retail pharmacy shelves. United States demand concentrates in multi-symptom formulations as pharmacy benefit managers auto-substitute private-label alternatives, compressing brand premium capture.
- Suppositories:Polymeric matrix technologies enable extended-release active ingredient delivery over 12-hour intervals. Prescription channel positioning is expanding as gastroenterology practices seek post-procedural adjunctive therapy with superior mucosal contact duration.
- Oral Medications:Venotonic agents and stool softeners address underlying pathophysiology rather than symptomatic relief.
- Surgical Instruments:Disposable kits and specialized energy devices command hospital outpatient department procurement budgets.
Volume placements concentrate in Topical Creams; the faster expansion belongs to Suppositories.
Application:
Cost tier differentiation separates acute intervention from maintenance regimens across reimbursement categories.
- In-office Procedures:Rubber band ligation and sclerotherapy performed in ambulatory settings displace surgical referrals. German and United States gastroenterology practices are converting examination rooms to procedure suites using modular radiofrequency platforms, expanding addressable volumes beyond traditional colorectal surgery networks.
- Home Remedies:OTC topical products and dietary fiber supplements constitute the lowest-acuity intervention tier. Retail pharmacy chain procurement departments are mandating dual-source API agreements to reduce single-supplier dependency risks.
- Surgical Treatment:Hemorrhoidectomy and stapled procedures remain reserved for grade IV or complicated presentations.
- Preventive Care:Lifestyle modification protocols and symptom monitoring applications target recurrence reduction.
Revenue concentration favors In-office Procedures; Home Remedies are climbing the fastest as telehealth platforms capture pre-treatment patient journeys.
End User:
Customer type determines regulatory exposure and outcome data collection obligations under HIPAA frameworks.
- Clinics:Independent gastroenterology and colorectal surgery practices drive procedural volume migration toward lower-acuity settings. Custom API development with dominant electronic health record platforms is required for procedure-specific outcome tracking module adoption.
- Hospitals:Outpatient departments retain complex case referrals while losing routine procedures to ambulatory competitors. Site-of-service reimbursement differentials are accelerating this volume shift.
- Home Care:Direct-to-consumer subscription models for prescription-strength topical combinations are disrupting traditional retail pharmacy fulfillment.
- Pharmacies:Community and retail chains remain the dominant distribution channel for OTC self-care products.
Procurement gravity centers on Clinics; Home Care is gaining share fastest through digital therapeutics integration.
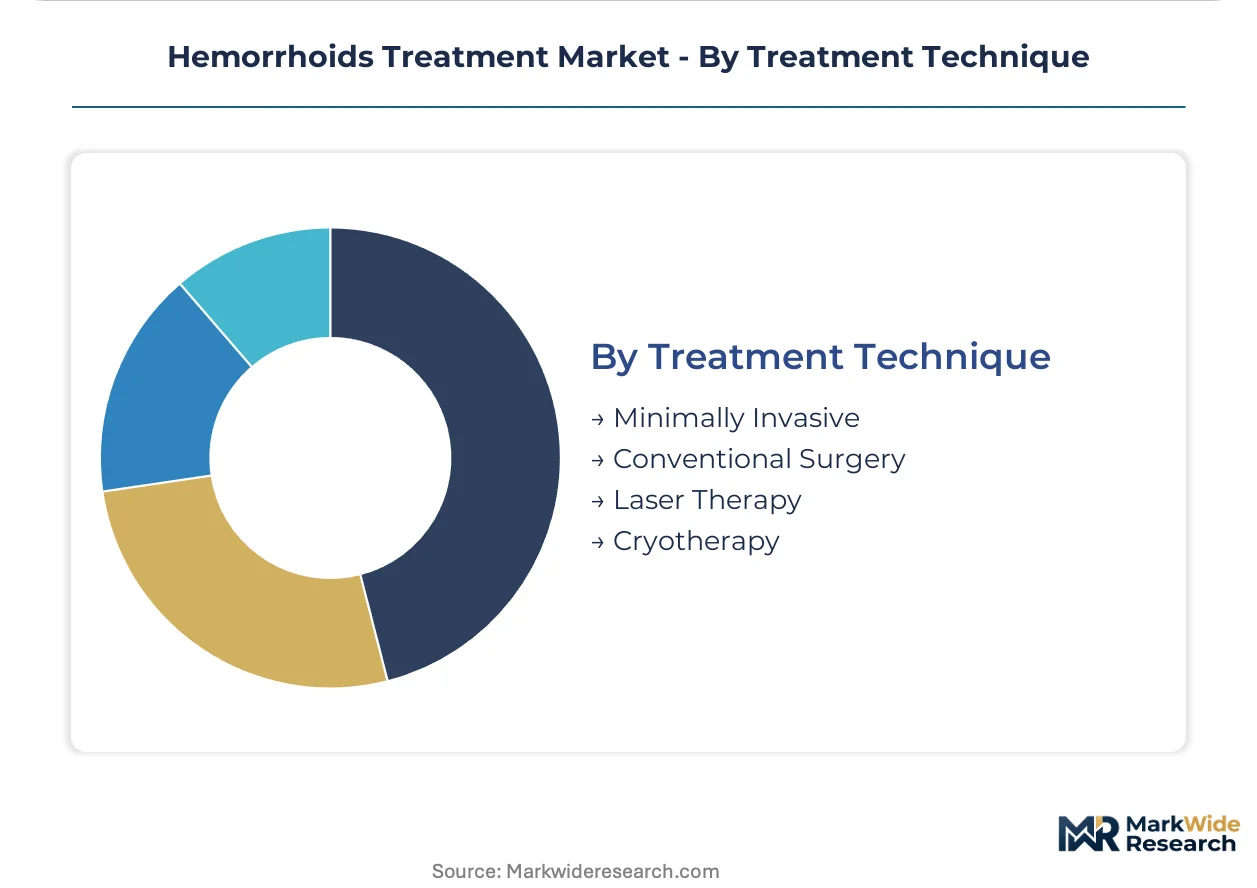
Treatment Technique:
Technology maturity separates established modalities from emerging platform investments.
- Minimally Invasive:Rubber band ligation, sclerotherapy, and radiofrequency ablation dominate grade II-III internal hemorrhoid management. India's Tier-2 and Tier-3 city infrastructure investments under Ayushman Bharat are creating procedural capacity expansion opportunities.
- Laser Therapy:Precision energy delivery systems command premium positioning in private-pay markets. German and Japanese precision electronics suppliers dominate component manufacturing, creating geographic concentration risk in the supply base.
- Conventional Surgery:Hemorrhoidectomy remains the reference standard for advanced or recurrent disease.
- Cryotherapy:Nitrous oxide-based tissue destruction offers alternative thermal ablation with distinct recovery profiles.
Procedure volumes concentrate in Minimally Invasive techniques; Laser Therapy shows the steepest expansion trajectory as disposable catheter kits modularize treatment workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient sourcing for topical vasoconstrictors concentrates in Gujarat and Zhejiang manufacturing clusters, with German precision electronics suppliers anchoring interventional device component production.
United States
Aging demographics and elevated obesity rates sustain higher treatment-seeking behavior across ambulatory surgical centers. FDA monograph revisions for OTC topical products are forcing reformulation investments and compressing product development timelines. Gastroenterology practices in Texas and Florida are converting examination rooms to procedure suites using modular radiofrequency platforms.
Germany
REACH Annex XVII restrictions on boron compounds and corticosteroid esters are forcing reformulation with alternative vasoconstrictor complexes. ECHA chemical safety protocols are streamlining cross-border formulation approvals for topical manufacturers. Precision electronics suppliers in Bavaria and Baden-Württemberg dominate radiofrequency and laser component manufacturing for interventional devices.
India
Tier-2 and Tier-3 city healthcare infrastructure investments under Ayushman Bharat are creating procedural capacity for rubber band ligation and sclerotherapy services. CDSCO regulates topical drug formulations while state pharmacy councils oversee retail distribution compliance. Manufacturing clusters in Maharashtra and Gujarat supply API feedstock for domestic and export markets.
Japan
PMDA oversight of medical devices maintains stringent approval pathways for interventional energy systems. METI industrial policy supports domestic production of precision surgical instruments. Tokyo and Osaka metropolitan areas concentrate specialized colorectal surgery capacity and device procurement decision-making.
China
NMPA regulatory harmonization with international standards is accelerating approval timelines for imported interventional devices. Domestic API production in Zhejiang and Jiangsu provinces reduces import dependency for topical formulation feedstock. Shanghai and Beijing hospital outpatient departments retain complex case referrals while routine procedures migrate to ambulatory competitors.
Hemorrhoids Treatment Market Competitive Environment
Global majors compete with regional champions across formulation technology and distribution reach, producing a tiered structure where multinational pharmaceutical conglomerates hold retail pharmacy shelf space while regional device specialists capture ambulatory procedure volumes. Three archetypes dominate: dermatology-focused consumer health divisions, diversified medical technology conglomerates with interventional portfolios, and API-to-formulation integrated Indian pharmaceutical houses. Consolidation pressure manifests through strategic partnerships between device manufacturers and telehealth platforms, plus geographic licensing agreements for extended-release formulation technologies.
Within the consumer-accessible tier, Church & Dwight Co., Inc. and Bayer AG exemplify retail pharmacy channel dominance through established dermatology infrastructure and broad distribution networks. Abbott Laboratories occupies a position bridging pharmaceutical and interventional care through device-led portfolios. Among Indian pharmaceutical houses, Lupin and Cipla represent API-to-formulation integration strategies targeting both domestic procedural growth and export market penetration.
| Leading Market Players |
|---|
| Haleon Group of Companies |
| Bayer AG |
| Abbott Laboratories |
| Church & Dwight Co., Inc. |
| Lupin |
| Cipla |
| Sanofi |
| Boston Scientific Corporation |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up gastroenterology practice networks in the United States and Germany are consolidating procurement decisions for radiofrequency ablation platforms, compressing vendor margins while extending payment terms that strain working capital across disposable kit manufacturers.
Pricing Analysis
After-sales service bundling separates premium device vendors from unbundled competitors in the interventional segment. Three-tier pricing structure across premium, standard, and economy levels prevails, with FDA 510(k) clearance tier and disposable catheter compatibility driving price differentiation. Pricing pressure stems from pharmacy benefit managers auto-substituting branded topical creams with private-label equivalents. Home care patients exhibit highest price sensitivity; hospital outpatient departments show lowest due to site-of-service reimbursement differentials.
Supply Chain Analysis
ISO 13485 certification and FDA establishment registration function as non-negotiable gating criteria for API suppliers serving topical formulation manufacturers. Active pharmaceutical ingredient production concentrates in India, China, and Germany; precision electronics for energy devices originate from Japan and Bavaria. Boron compound restrictions under REACH Annex XVII and hydrocortisone ester limitations are forcing reformulation cycles. Single-source vulnerability persists in specialized laser component supply. Distribution runs through retail pharmacy chains, ambulatory surgical center group purchasing organizations, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemorrhoids treatment market is executing a technology-transition phase as radiofrequency ablation platforms displace conventional surgical infrastructure in ambulatory settings.
For Market Incumbents: Acquire extended-release formulation technology portfolios to defend against generic topical substitution. Secure dual-source API agreements with Gujarat and Zhejiang manufacturing clusters to mitigate supply disruption risk from REACH chemical safety protocol revisions. Invest in HIPAA-compliant outcome tracking modules that integrate with dominant electronic health record platforms to lock in ambulatory surgical center loyalty. For New Entrants and Emerging Players: Smartphone-based symptom monitoring applications offer a technology-first wedge into the pre-treatment patient journey. Target Tier-2 and Tier-3 Indian cities where Ayushman Bharat infrastructure investments are creating procedural capacity without established competitor presence. Partner with telehealth platforms for prescription authorization and pharmacy benefit integration to bypass traditional primary care physician channel gatekeeping. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European topical manufacturers facing REACH reformulation cost burdens in Germany and France. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Monitor FDA monograph revision timelines for phenylephrine and hydrocortisone concentration caps as inflection indicators for OTC segment consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Polymeric matrix technologies enable 12-hour dosing intervals that command prescription channel premium positioning. |
| Ambulatory Procedure Suite Conversion | Modular radiofrequency platforms allow gastroenterology practices to capture hospital outpatient department volume migration. |
| Dual-Source API Contracting | Supply resilience mandates from major retail pharmacy chains are expanding qualified supplier pools beyond single-source dependencies. |
| Telehealth Platform Integration | Direct-to-consumer subscription models for prescription-strength combinations displace traditional retail pharmacy fulfillment. |
| REACH Compliance Reformulation | Alternative vasoconstrictor complexes and synthetic steroid analogs address boron compound and corticosteroid ester restrictions. |
Study Parameters
Independent corroboration across regulatory filings, procurement databases, and clinical outcome registries underwrites the qualitative findings in this study. Primary interviews with colorectal surgeons, gastroenterology practice administrators, ambulatory surgical center procurement directors, and pharmacy benefit managers were combined with secondary validation from FDA 510(k) clearances, EMA marketing authorization applications, CMS Medicare reimbursement schedules, and hospital group purchasing organization contract disclosures. Bottom-up procedure volume estimates and top-down pharmaceutical sales data were triangulated to anchor market sizing.
Comparable-period anchoring to historical procedural volume baselines and pharmaceutical shipment records established the forecast reference frame. The analytical framework segments by product type, application, end user, and treatment technique across the projection horizon, with CAGRs derived from trend extrapolation moderated by regulatory event probability weighting. Forecast inputs include site-of-service reimbursement differential trajectories, REACH chemical safety protocol amendment calendars, and ambulatory surgical center capital expenditure cycle timing.
Several conditions sit outside the modeled scope, including novel surgical robot introductions for colorectal procedures and biosimilar competition in venotonic oral medications. Forecasts reflect documented assumptions regarding payer behavior stability and API supply base geographic concentration. A model refresh is warranted upon material change in FDA monograph revision implementation timelines or Ayushman Bharat infrastructure deployment velocity in Indian Tier-2 cities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Otoplasty Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Microwave Ablation Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market