
 Belgium Data Center Construction Market | 2026-2036
Belgium Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Data Center Construction Market Insights
Hyperscale cloud buyers is collapsing the historical dominance of enterprise self-builds across Belgian data center procurement. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale projects in the Brussels periphery. DPR Construction, Inc. competes through design-build delivery models that compress commissioning timelines for colocation operators. Vertiv Group Corp. differentiates via thermal management specialization as rack densities climb past 50 kW in new facilities.
Data center construction encompasses the engineering, physical build-out, and systems integration of facilities housing compute, storage, and network infrastructure, requiring precision environmental controls, redundant power architectures, and tiered reliability certifications. Modular technology leads deployment velocity as prefabricated power and cooling modules slash on-site construction duration, while green technology represents the fastest-expanding margin pool driven by EU Green Deal compliance and carbon reporting mandates under CSRD. Traditional stick-built methods still occupy legacy enterprise retrofits where existing building envelopes constrain factory-built module insertion.
Belgium's federal and regional authorities enforce EU F-Gas Regulation limits on synthetic refrigerants, pushing operators toward liquid cooling and natural refrigerant architectures. CE marking and national electrical safety standards administered by the country's federal agency for nuclear control and regional environmental inspectors shape equipment market access and contractor qualification requirements. Stakeholders must monitor grid interconnection queue positions and renewable energy certificate sourcing strategies as electrification intensity outpaces transmission expansion in Flanders and Wallonia.
Market Dynamics
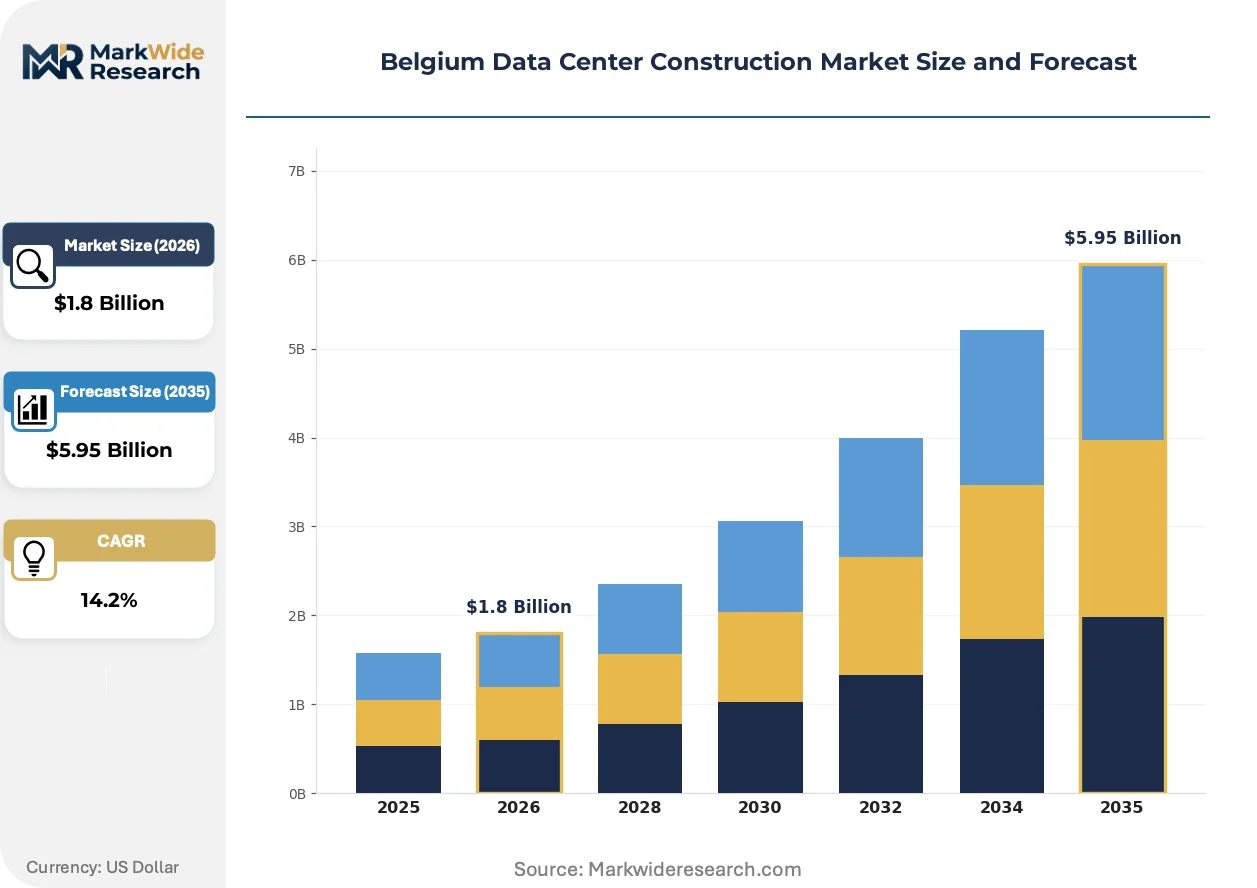
Hyperscale cloud providers are compressing traditional enterprise build cycles and forcing modular, liquid-cooled designs across Belgian data center construction as rack densities exceed 50 kW per cabinet.
Growth Catalysts
- EU Green Deal carbon neutrality mandates:Belgium's federal and regional authorities enforce strict renewable energy targets that accelerate liquid cooling adoption and solar-plus-storage integration in new facilities.
- Cloud service provider expansion:Hyperscale buyers are consolidating procurement volumes and demanding faster commissioning timelines that favor design-build delivery models.
- Brussels-Antwerp fiber density convergence:Grid access and dark fiber availability in these corridors attract concentrated data center clustering with superior interconnection economics.
Market Restraints
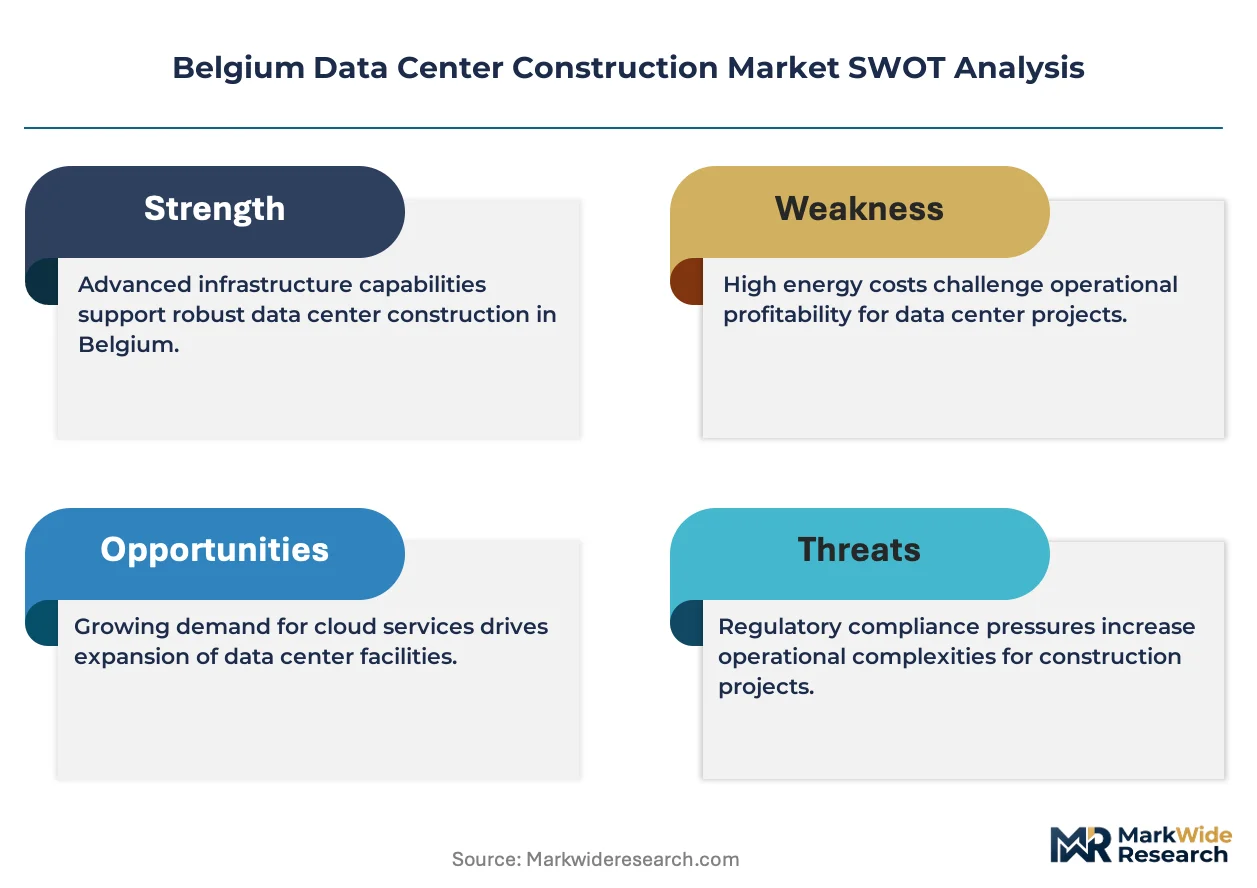
- Copper and electrical steel input volatility:Transformer and busbar material costs fluctuate with commodity markets, compressing contractor margins on fixed-price contracts.
- F-Gas Regulation synthetic refrigerant limits:The EU framework phases down hydrofluorocarbon availability, forcing expensive retrofits or alternative cooling architectures before end-of-life.
- Grid interconnection queue congestion:Electrification intensity in Flanders and Wallonia outpaces transmission expansion, delaying energization dates by 18-36 months.
Strategic Opportunities
- Wallonia brownfield industrial site repurposing:Decommissioned manufacturing facilities offer existing grid capacity and cooling water access for retrofit data center projects.
- CSRD carbon reporting compliance services:Mandatory sustainability disclosures create adjacent revenue streams for construction firms offering embodied carbon tracking and renewable energy certificate sourcing.
- Direct liquid cooling and immersion convergence:Hybrid thermal architectures combining cold plate and single-phase immersion enable 100+ kW rack densities for AI training workloads.
Industry Challenges
- Specialized mechanical and electrical craft shortages:Belgium's construction labor pool lacks sufficient technicians certified in precision cooling, medium-voltage switching, and fire suppression integration.
- Tier III and Tier IV certification timeline compression:Uptime Institute and TSI standards require extended commissioning periods that conflict with hyperscale speed-to-market demands.
- Legacy building envelope constraints:Existing structures in Brussels-Capital limit prefabricated module insertion, forcing costlier stick-built retrofits with inferior thermal performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Data Center Construction Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Maintenance, Commissioning Technology: Modular, Traditional, Hybrid, Green End User: Cloud Service Providers, Enterprises, Colocation Providers, Government Size: Small, Medium, Large, Hyper-scale |
| Companies Covered | AECOM, Atos, Schneider Electric SE, DPR Construction, Inc., Turner Construction, Fortis Construction Inc., Johnson Controls, Vertiv Group Corp., Digital Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Data Center Construction Market Trends and Innovations
Belgian data center construction is pivoting toward factory-built modularity, natural refrigerant architectures, and procurement models that transfer operational risk from end-users to specialized contractors.
Prefabricated power and cooling modules are decomposing traditional on-site construction sequences. Colocation operators in the Brussels periphery now specify skid-mounted UPS and chiller packages that cut mechanical installation from 16 weeks to 4 weeks. This compression is decomposing the competitive advantage of general contractors without modular fabrication partnerships.
The EU F-Gas Regulation is prohibiting high-global-warming-potential refrigerants in new data center cooling systems. Belgium's federal environmental inspectors enforce these limits through construction permitting, pushing operators toward ammonia, CO2, or propane architectures. Liquid cooling specialists capture margin expansion as synthetic refrigerant equipment becomes stranded asset risk.
Power purchase agreement structures are displacing traditional utility procurement for data center energy supply. Hyperscale tenants in Antwerp corridor facilities now require bundled renewable energy certificates with 10-15 year contract terms. This financing complexity favors construction firms with in-house energy advisory capabilities over pure EPC players.
Belgium Data Center Construction Market Segmentation
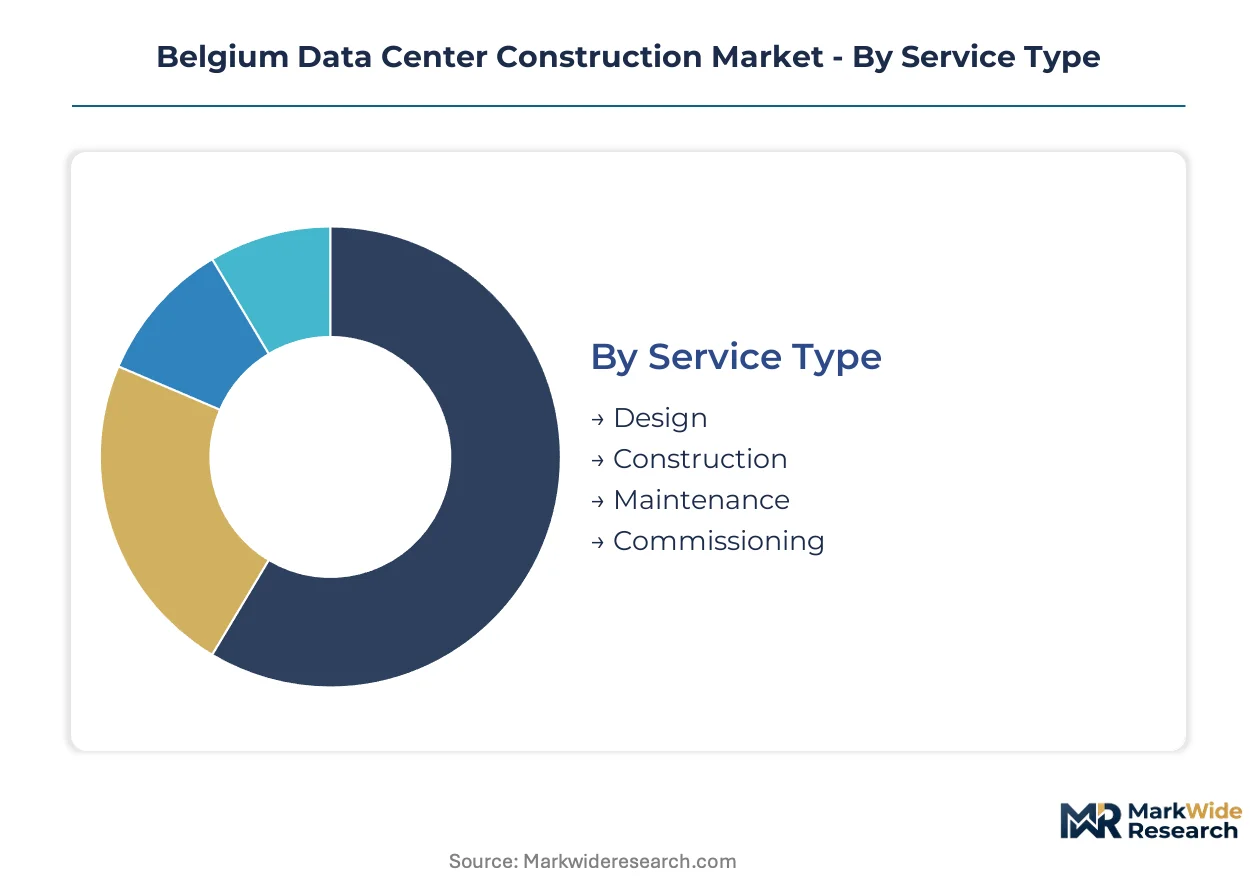
Belgian data center construction segments reflect divergent procurement patterns between hyperscale cloud buyers demanding compressed timelines and legacy enterprises favoring conventional delivery. Service type and technology splits capture the tension between modular velocity and stick-built customization across Brussels-Antwerp corridor projects.
Service Type:
Geographic concentration varies sharply: design and commissioning services cluster domestically around Brussels engineering hubs, while construction execution draws cross-border contractor labor from the Netherlands and France.
- Design:Architectural and MEP engineering services specify liquid cooling architectures and medium-voltage distribution for facilities exceeding 50 kW rack densities. Brussels-based engineering consultancies capture hyperscale cloud provider contracts requiring EU Green Deal compliance documentation.
- Construction:Physical build-out encompasses civil works, structural steel, and precision environmental system installation. Flemish contractors dominate concrete shell delivery while specialized mechanical-electrical trades concentrate in Antwerp and Ghent industrial zones.
- Maintenance:Post-commissioning facility operations and preventive servicing contracts. Regional service providers in Wallonia leverage proximity to decommissioned industrial sites repurposed for data center use.
- Commissioning:Integrated systems testing and Tier certification validation. Uptime Institute and TSI auditors require extended on-site presence that conflicts with hyperscale speed demands in Brussels periphery projects.
Construction holds the largest share; momentum sits with Commissioning as certification complexity escalates.
Technology:
Cost tier stratification separates premium factory-built solutions from economy stick-built approaches, with margin compression most severe in mid-market hybrid configurations.
- Modular:Prefabricated power and cooling modules manufactured off-site for rapid on-site assembly. Skid-mounted UPS and chiller packages cut mechanical installation duration from sixteen weeks to four weeks in Brussels colocation builds.
- Traditional:Conventional stick-built methods using on-site construction sequences and custom-fabricated components. Legacy enterprise retrofits in Brussels-Capital constrained by existing building envelopes retain this approach despite inferior thermal performance.
- Hybrid:Blended delivery combining factory-built critical infrastructure with conventional architectural elements. Mid-scale operators in Flanders adopt this compromise to balance speed requirements with customization needs.
- Green:Renewable-powered designs integrating solar-plus-storage, natural refrigerant cooling, and embodied carbon tracking. EU F-Gas Regulation enforcement through Belgium's federal environmental inspectors accelerates this segment's expansion.
Traditional technology retains volume leadership; Green configurations are climbing the fastest as CSRD mandates harden.
End User:
Customer type determines procurement model complexity, with hyperscale buyers consolidating volumes and demanding operational risk transfer that reshapes contractor margins.
- Cloud Service Providers:Hyperscale tenants requiring 10-15 year power purchase agreements with bundled renewable energy certificates. These buyers compress commissioning timelines and specify liquid-cooled designs for AI training workloads above 100 kW per rack.
- Enterprises:Corporate self-builds historically dominant but declining as procurement shifts toward colocation and cloud. Remaining enterprise projects concentrate in Brussels financial services and Antwerp port logistics sectors.
- Colocation Providers:Multi-tenant facility operators specifying design-build delivery to accelerate revenue-generating capacity. Brussels periphery and Antwerp corridor clustering reflects superior fiber density and grid interconnection economics.
- Government:Federal and regional public sector data centers subject to additional security and sovereignty requirements. Belgian federal agency for nuclear control administers electrical safety standards that extend procurement cycles.
Colocation Providers command the largest construction contract value; Cloud Service Providers show the steepest expansion trajectory.
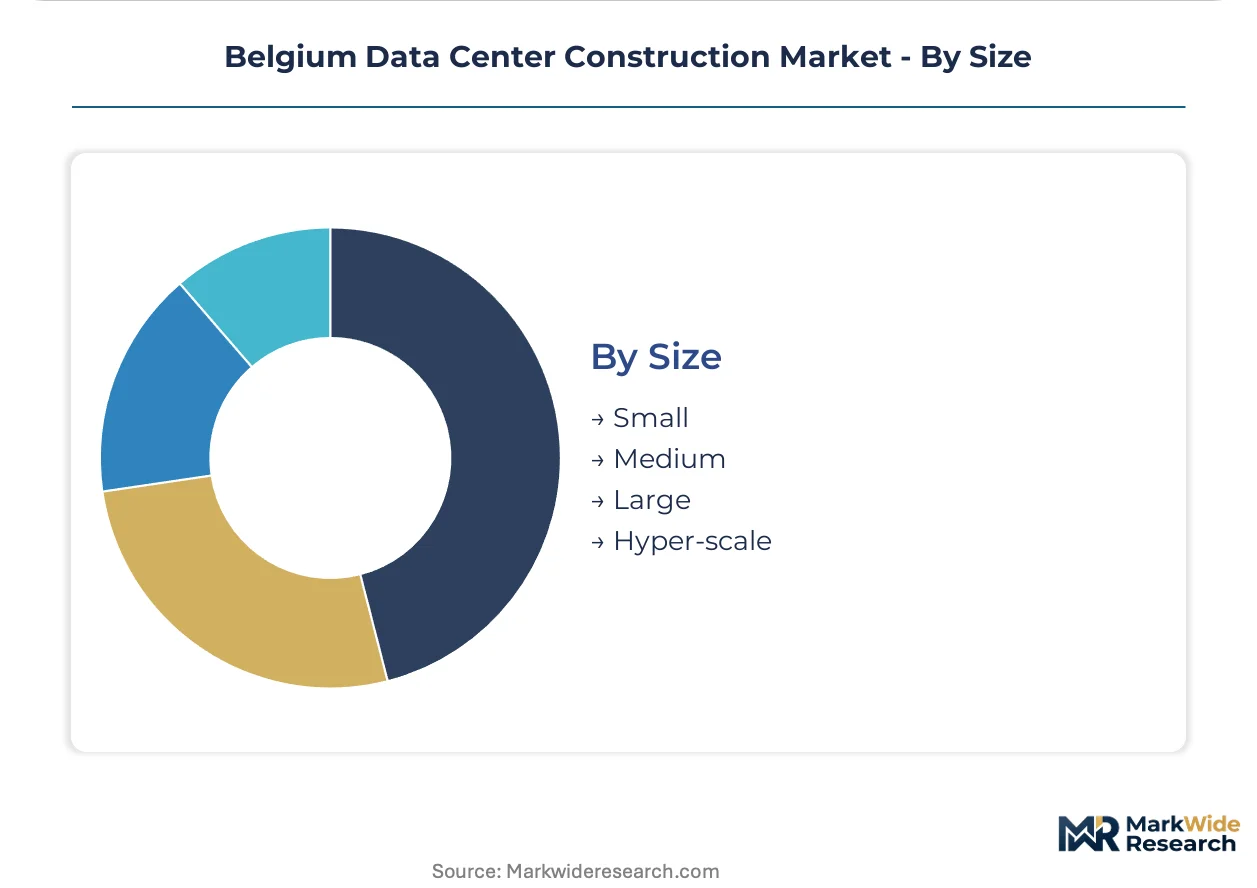
Size:
Volume concentration aligns with grid access availability, as electrification intensity outpaces transmission expansion in Flanders and Wallonia.
- Small:Facilities under 1 MW capacity serving edge computing and distributed enterprise workloads. Limited grid interconnection queue positions in congested Flanders regions constrain this segment's deployment velocity.
- Medium:1-10 MW facilities representing the traditional colocation sweet spot. Antwerp corridor brownfield industrial sites offer existing grid capacity attractive to this scale tier.
- Large:10-50 MW campuses requiring dedicated substations and cooling water access. Wallonia decommissioned manufacturing facilities provide suitable footprints with established utility infrastructure.
- Hyper-scale:Facilities exceeding 50 MW with phased multi-building expansion capability. Brussels-Antwerp fiber density convergence and superior interconnection economics concentrate this segment geographically.
Large facilities retain dominant share; Hyper-scale projects gain share fastest as cloud provider expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea-Baltic Corridor rail and fiber trunk lines position Belgium as a continental data exchange hub. Dense submarine cable landings at Zeebrugge and Ostend anchor transatlantic connectivity. Grid interconnection capacity in Flanders and Wallonia shapes where hyperscale facilities can energize.
Brussels-Capital Region
EU institutional presence drives sovereign cloud demand from diplomatic and regulatory bodies. The Brussels regional government enforces strict urban planning codes that constrain greenfield expansion. Colocation clusters concentrate in peripheral municipalities where fiber density meets available transmission capacity.
Flanders
Port of Antwerp logistics operators and chemical industry digitization fuel enterprise data center demand. Flemish environmental permitting through the Department of Environment and Spatial Development applies EU F-Gas Regulation limits on cooling system refrigerants. Waasland industrial zone brownfield sites attract retrofit projects with existing medium-voltage infrastructure.
Wallonia
Decommissioned steel and manufacturing facilities in Charleroi and Liège basins offer grid-ready footprints for large-scale campuses. Walloon regional investment incentives target data center job creation in economically restructuring territories. Sambre-Meuse valley cooling water access supports liquid-cooled designs for AI training workloads.
Netherlands
Amsterdam Metro fiber ring and AMS-IX exchange proximity creates cross-border cluster effects with Belgian facilities. Dutch Authority for Digital Infrastructure enforces sustainability criteria for data center permitting that Belgian operators reference for best practice. North Brabant logistics corridors extend Antwerp data center ecosystem into Dutch territory.
France
Northern France wind and nuclear generation capacity competes for hyperscale power purchase agreements with Belgian renewable sourcing. French CRE grid regulator interconnection timelines influence Belgian project scheduling decisions. Lille metropolitan area dark fiber networks interconnect with Belgian facilities for disaster recovery topology.
Belgium Data Center Construction Market Competitive Landscape
Listed infrastructure conglomerates compete with private construction specialists across design-build delivery capability and thermal engineering depth. Market structure shows moderate concentration with three to five integrated players anchoring large-scale hyperscale contracts while regional contractors capture mid-market retrofits. Strategic archetypes separate integrated power-cooling portfolio vendors, precision mechanical-electrical specialists, and design-build generalists. Dominant competitive moves include modular fabrication partnerships and in-house energy advisory capability development.
Within the integrated infrastructure tier, Schneider Electric SE and Vertiv Group Corp. represent archetypes combining power distribution with thermal management portfolios. DPR Construction, Inc. exemplifies the design-build specialist model compressing commissioning timelines for speed-sensitive colocation operators. These three anchors demonstrate how procurement consolidation by hyperscale cloud buyers rewards contractors with bundled capability across electrical, mechanical, and energy structuring disciplines.
| Leading Market Players |
|---|
| AECOM |
| Atos |
| Schneider Electric SE |
| DPR Construction, Inc. |
| Turner Construction |
| Fortis Construction Inc. |
| Johnson Controls |
| Vertiv Group Corp. |
| Digital Realty |
| Others |
Pricing and Supply Chain Analysis
CE marking and Belgium's federal electrical safety standards administered by the national agency for nuclear control simultaneously gate contractor qualification and stratify project pricing tiers. Contractors holding full certification command premium positioning on hyperscale cloud contracts where liquid cooling complexity demands proven compliance track records.
Pricing Analysis
Volume-discount tiering separates hyperscale cloud provider contracts from mid-market colocation and legacy enterprise retrofits. Pricing stratifies across premium, standard, and economy tiers based on certification grade and bundled energy advisory services. Cost compression in the economy tier intensifies as commodity copper and electrical steel volatility squeezes fixed-price contractor margins. Hyperscale buyers show lowest price sensitivity given their focus on speed-to-market and renewable energy certificate bundling.
Supply Chain Analysis
Rotterdam-Antwerp port congestion and Rhine river water level volatility create intermittent chokepoints for transformer and precision cooling equipment delivery. Manufacturing concentrates in Germany, the Netherlands, and China for switchgear, chillers, and skid-mounted power modules. The supply chain draws from copper mining in Chile, electrical steel production in South Korea, and semiconductor components from Taiwan. Single-source vulnerability runs through German medium-voltage switchgear specialists. Distribution runs through Antwerp logistics hubs and cross-border contractor networks from France and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium data center construction operates as a service-attach opportunity where commissioning and carbon compliance advisory layers expand faster than physical build-out margins. Post-commissioning facility operations and CSRD reporting services now capture recurring revenue streams exceeding initial construction yields.
For Market Incumbents: Fortify modular fabrication partnerships to compress mechanical installation timelines from sixteen weeks to four weeks. Deepen in-house energy advisory capabilities to capture power purchase agreement structuring margins. Defend against emerging design-build specialists by anchoring integrated power-cooling portfolios in Brussels periphery hyperscale projects.
For New Entrants and Emerging Players: Lead with Wallonia brownfield industrial site repurposing where decommissioned manufacturing facilities offer existing grid capacity and cooling water access. Target mid-scale colocation operators in Charleroi and Liège basins seeking retrofit speed advantages. Differentiate through CSRD carbon reporting compliance services as mandatory sustainability disclosures harden.
For Investors and Strategic Acquirers: EU F-Gas Regulation enforcement reshapes the acquisition landscape toward liquid cooling specialists with natural refrigerant expertise. Long-term viability centers on contractors capable of 100+ kW rack density architectures for AI training workloads. Target acquisition archetypes combine thermal engineering depth with design-build delivery capability. The signal to watch is grid interconnection queue position advancement in Flanders and Wallonia as electrification intensity outpaces transmission expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Partnership | Skid-mounted UPS and chiller packages cut mechanical installation duration by twelve weeks in Brussels colocation builds. |
| Liquid Cooling Capability Buildout | Ammonia and CO2 architectures capture margin expansion as synthetic refrigerant equipment becomes stranded asset risk under F-Gas Regulation. |
| Energy Advisory Service Launch | Bundled renewable energy certificate sourcing with 10-15 year power purchase agreements attracts hyperscale cloud provider contracts. |
| Wallonia Brownfield Site Acquisition | Decommissioned steel facilities in Charleroi offer grid-ready footprints with established medium-voltage infrastructure for large campuses. |
| CSRD Compliance Service Development | Embodied carbon tracking and sustainability disclosure documentation create adjacent revenue streams from mandatory reporting mandates. |
Research Methodology
Desk research of EPC contractor filings, EU regulatory databases, and transmission operator interconnection queue data preceded structured interviews with data center developers, MEP engineering directors, colocation procurement leads, and federal environmental inspectors. Secondary validation drew from Flanders Department of Environment permitting records, Walloon regional investment incentive disclosures, and hyperscaler capital expenditure announcements. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across the analysis window.
Variance decomposition across service type, technology tier, end user segment, and facility size dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate assumptions calibrated against grid interconnection capacity expansion and cloud provider footprint announcements. Forecast inputs incorporated F-Gas Regulation phase-down schedules, copper price futures curves, and renewable energy certificate market liquidity projections.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale cloud expansion and EU Green Deal compliance trajectory would require recalibration. Forecasts reflect assumptions around transmission infrastructure buildout pacing and liquid cooling technology cost curves. Practitioners should keep alternative scenarios live as grid interconnection queue congestion and commodity input volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market